

|
시장보고서
상품코드
2155234
염화마그네슘 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Magnesium Chloride - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
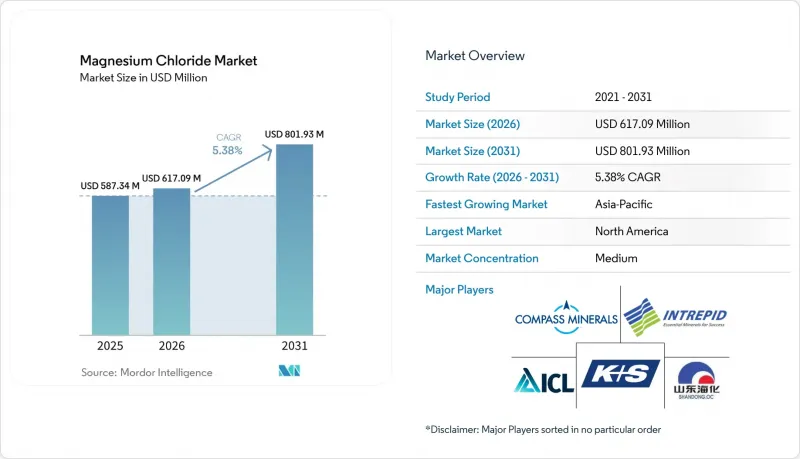
에 따르면 염화마그네슘 시장 규모는 2025년에 5억 8,734만 달러로 추계되고 있으며, 예측 기간(2026-2031년)에 CAGR 5.38%로 확대하며, 2026년 6억 1,709만 달러에서 2031년에는 8억 193만 달러에 달할 것으로 전망되고 있습니다.
세계 염화마그네슘 시장의 동향 및 인사이트
지자체 차원의 제설·방빙 자재 조달
지자체 조달 담당자들은 단일 겨울철의 일시적 구매에서 액체 및 고체 자재에 대한 다년 계약으로 전환하고 있으며, 이를 통해 생산자들은 여러 겨울철 주기에 걸친 수요를 보다 명확하게 파악할 수 있게 되었습니다. 2026년 시즌에는 아이다호주, 버몬트주, 와이오밍주, 인디애나주, 텍사스주에서 진행된 입찰에서 부식 방지제가 첨가된 액체 자재가 상당량 대상에 포함되었습니다. 에이다 카운티 도로 관리국은 단일 관할 구역에서 최대 60만 갤런을 조달하는 2027 회계연도(FY27) 계약을 발주했습니다. ICL 그룹은 2025 회계연도 특수 광물 판매 증가의 요인으로, 조기 강설과 도로 관리 기관의 시즌 전 비축에 이어 미국내 염화마그네슘 제설제 수요가 견고했던 점을 꼽고 있습니다. 각 기관에서는 적설이 발생하기 전에 눈이 포장 도로 표면에 달라붙는 것을 방지하기 위해 사전 처리를 점점 더 많이 활용하고 있습니다. 이러한 운영상의 변화로 인해 시장의 겨울철 수요 범위가 확대되고, 일시적인 구매에 대한 의존도가 낮아지고 있습니다.
건설 현장의 분진 억제 및 도로 안정화 분야의 성장
먼지 억제 및 도로 안정화는 겨울철 도로 유지 관리와는 다른 여름철 수요원을 염화마그네슘 시장에 제공하고 있습니다. 카운티 도로국, 광산 회사, 건설 현장 관리자가 주요 구매자입니다. 콜로라도주 메사 카운티는 2026년, 엔바이로텍 서비스(Envirotech Services)사에 64마일의 자갈길 시공을 통해 노면 재정비 빈도를 줄이고 도로의 수명을 연장하기 위한 목적으로 27만 5,000달러 규모의 계약을 체결했습니다. 2025년 아이오와주에서 실시된 도로 조사에 따르면 염화마그네슘을 함유한 흡습성 화학 안정제를 사용함으로써, 처리되지 않은 대조 구간에 비해 건설 및 유지 관리 비용이 19.1% 절감된 것으로 나타났습니다. 건조 지역 및 반건조 지역의 물 사용권 제한으로 인해 살수차 사용이 제한되고 있으며, 염화마그네슘 시장에서 흡습성 분진 억제제에 대한 수요가 증가하고 있습니다.
염화물의 유출, 토양내 축적 및 생태계 노출
처리된 도로 인근의 염화물 축적은 염화마그네슘 시장에서 환경적 우려 사항으로 보고되고 있으며, 미국 및 유럽의 규제 당국은 유출수 및 살포 방법에 더욱 주의를 기울이고 있습니다. 2025년 미국 지질조사국(USGS)이 뉴욕주 에섹스 카운티의 3개 고속도로 유역에 대해 실시한 조사에 따르면 고속도로에서 유출되는 물의 염화물 농도가 0.75-29,200mg/L 범위로 나타났습니다. 하류의 지표수 농도 중앙값은 상류 수준보다 10-45배 높았으며, 조지 호수의 농도는 1940년 이후 약 30배 상승하여 미국 환경보호청(EPA)이 정한 수생 생물에 대한 만성 영향 임계치인 230mg/L에 근접하고 있습니다. 인디애나주의 교통 조사에 따르면 염화물의 축적으로 인해 살포 시즌이 끝난 후에도 도로변 토양으로의 침투가 발생하거나 식물의 생존율이 저하될 가능성이 있는 것으로 밝혀졌습니다. 콜로라도 주립대학교는 민감한 침엽수에 대한 위험이 있으므로, 산림 지대를 지나는 도로나 가파른 경사면에서 염화마그네슘 사용을 자제할 것을 권고하고 있습니다. 보다 엄격한 지역별 규제가 마련된다면, 염화마그네슘 시장의 민감한 분야에서 조달량을 줄일 수 있을 가능성이 있습니다.
부문 분석
2025년 기준, 무수 염화마그네슘은 염화마그네슘 시장 점유율의 56.34%를 차지했으며, 2031년까지의 예측 연평균 성장률(CAGR)은 5.67%로 가장 높았습니다. 이러한 위상은 1차 마그네슘 전해 및 티타늄 스폰지 병생산에서 무수 염화마그네슘이 수행하는 역할에 기인합니다. 전해법에 의한 생산은 피존(Pigeon) 공법에 비해 보고된 온실가스 배출량이 적어, 배출량 보고 의무를 지는 제조업체들 사이에서 고순도 무수 원료에 대한 수요를 지원하고 있습니다. 2025년 조사에서는 비스코파이트(MgCl₂·6H₂O)를 무수 염화마그네슘으로 변환하기 위한 탈수 방법이 검토되었습니다. 공용매를 이용한 탈수나 반응성 건조를 통해 전해 성능을 저하시키는 가수분해 부산물을 줄일 수 있으므로, 염화마그네슘 시장에서 품질을 중시하는 가격 책정이 지원되고 있습니다.
6수화물 염화마그네슘, 즉 비스코파이트는 용액상 제품이 허용되는 식품, 의약품 및 분진 억제 용도로 사용되며, 시장 점유율 2위를 차지하고 있습니다. 액체 브라인은 세 번째 제품 유형으로, 동결 방지를 위한 전처리로서 즉시 사용 가능한 액체를 선호하는 지자체들의 도로 살포 프로그램에 사용되고 있습니다. 이러한 프로그램에서 염화마그네슘은 가격 및 운영 성능 면에서 염화칼슘 브라인과 경쟁하고 있습니다. 또한 비쇼파이트는 두부 응고에 사용되는 식품 등급 니가리의 원료이기도 하며, 식품 용도로 사용하기 전에 재결정화 및 인증이 필요합니다.
2025년에는 염화마그네슘 시장 중 플레이크형 제품이 44.82%를 차지했으며, 2031년까지 연평균 성장률(CAGR)이 5.95%로 가장 빠르게 성장하는 형태였습니다. 이 제품들은 겨울철 동결 방지 및 여름철 먼지 억제에 사용됩니다. 흡습성이 있는 표면 덕분에 수분을 신속하게 흡수할 수 있으며, 수동 살포기나 벌크 살포 트럭에 사용하기에 적합합니다. ICL 그룹의 데드씨 웍스(Dead Sea Works)는 고체 염화마그네슘의 연간 생산량이 137 kt라고 보고하고 있으며, 주요 고체 제품은 플레이크 형태입니다.
과립은 형태별 생산량에서 2위를 차지하며, 서방형 농업 용도나 용해 속도가 느려야 하는 도로 사전 처리 프로그램 등에서 사용됩니다. ‘기타’ 범주에는 펠릿, 분말, 그리고 의약품 제조 및 실험용 시약용 특수 형태가 포함되어 있으며, 특정 취급 요건이나 순도 요건이 요구되는 용도에 대응하고 있습니다. 제품 선택은 여전히 구매자의 사용 방법과 보관 요구 사항에 따라 결정됩니다.
지역별 분석
2025년, 북미는 전 세계 염화마그네슘 시장 점유율의 33.05%를 차지했습니다. 미국 및 캐나다의 연간 동계 유지 관리 프로그램이 이러한 위치를 지원하고 있으며, 많은 프로그램이 다년간의 포괄적 계약을 기반으로 운영되고 있습니다. 컴퍼스 미네랄스(Compass Minerals)는 2025 회계연도 ‘소금’ 부문 매출이 10억 2,250만 달러를 기록하여, 제설제 가격 및 판매량 개선을 배경으로 13% 증가했다고 보고했습니다. 건조한 서부 주들의 여름철 먼지 억제 계약은, 물 사용권 제한으로 인해 살수차를 이용한 살포가 현실적으로 어려운 경우, 추가적인 수요원이 되고 있습니다. 컴퍼스 미네랄스의 그레이트 솔트레이크 오그덴 시설 및 지역 판매 대리점은 염화마그네슘 시장에서 구매자에게 다양한 조달 옵션을 제공하고 있습니다.
아시아태평양은 2031년까지 5.78%라는 지역별 최고 연평균 성장률(CAGR)을 기록할 것으로 예측됩니다. 중국의 염호 및 염소-알칼리 일체형 생산 거점은 산동성, 칭하이성, 톈진에 집중되어 있으며, 이러한 거점들은 산업용 등급 소재에서 비용 면에서 우위를 점하고 있습니다. 인도는 건설 활동, 농업용 마그네슘 수요, 가공 식품에서의 식품 등급 사용으로 인해 신흥 소비 시장으로 부상하고 있습니다. 일본과 한국은 고사양 산업용 및 식품용 소재의 확고한 시장이며, 반도체 관련 화학 처리 및 전통 식품 생산 분야에서도 염화마그네슘이 사용되고 있습니다.
유럽에서는 제설제 혼합물, 칼륨·마그네슘계 비료, 산업용 등급 소재 분야에서 높은 제품 품질이 요구되고 있습니다. 독일, 영국, 프랑스, 이탈리아 및 북유럽 국가들이 이 지역의 주요 수요 거점으로 자리 잡고 있습니다. K+S사의 칼륨 및 마그네슘 사업은 산업용, 공업용, 의약품 용도를 위한 공급을 지원하고 있습니다. 남미는 비교적 소규모 시장이지만, 브라질과 아르헨티나에서는 분진 억제가 필요한 내륙 농업용 도로에 대한 투자가 진행되고 있습니다. 중동 및 아프리카 역시 여전히 소규모 시장입니다. ICL 데드씨웍스(ICL Dead Sea Works)는 52 km²에 달하는 사해 채굴권 지역에서 고품질의 고체 염화마그네슘을 공급하며, 전 세계 식품 및 의약품 업계의 구매자들에게 제품을 제공하고 있습니다. 전반적으로 염화마그네슘 시장의 지역별 수요는 기상 조건에 좌우되는 도로 이용, 산업용 규격, 그리고 건설 활동의 조합을 반영하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 폼별
- 등급별
- 용도별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Alkim Alkali Kimya A.S.
- Antera Agro Chem
- Celtic Chemicals
- Compass Minerals
- DEUSA International GmbH
- HuiTai Investment Co
- ICL
- Intrepid Potash
- K+S Aktiengesellschaft
- Nedmag B.V.
- NikoMag
- Shandong Haihua Group Co., Ltd.
- Shouguang Dingsheng Chemical Co., Ltd.
- Skyline Chemical Corporation
- Tianjin Changlu Haijing Group Co., Ltd.
- Weifang Yuze Chemical Co., Ltd
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the magnesium chloride market size was estimated at USD 587.34 million in 2025 and is estimated to grow from USD 617.09 million in 2026 to USD 801.93 million by 2031, at a CAGR of 5.38% during the forecast period (2026-2031).
Global Magnesium Chloride Market Trends and Insights
Municipal De-Icing and Anti-Icing Procurement
Municipal purchasers are moving beyond single-winter spot buying toward multi-year contracts for liquid and solid material, giving producers clearer demand visibility across several winter cycles. In the 2026 season, tenders in Idaho, Vermont, Wyoming, Indiana, and Texas covered substantial quantities of corrosion-inhibited liquid material. The Ada County Highway District issued a Fiscal Year 2027 (FY27) contract for up to 600,000 gallons from a single district. ICL Group linked its fiscal year 2025 specialty minerals sales growth to stronger U.S. magnesium chloride de-icing demand following early snowfall and pre-season stockpiling by road agencies. Agencies are increasingly using pre-treatment to prevent snow from bonding to pavement before accumulation occurs. This operational change broadens the market's winter demand profile and reduces dependence on reactive purchasing.
Growth in Construction Dust Control and Road Stabilization
Dust control and road stabilization provide the magnesium chloride market with a summer demand source distinct from winter road maintenance. County road departments, mining companies, and construction-site managers are key buyers. Mesa County, Colorado, awarded EnviroTech Services a USD 275,000 contract in 2026 for applications on 64 miles of gravel roads to reduce the frequency of regrading and extend road life. A 2025 Iowa road study found that water-absorbent chemical stabilizers, including magnesium chloride, reduced construction and maintenance costs by 19.1% against untreated control sections. Water-rights restrictions in arid and semi-arid areas limit the use of water trucks, supporting demand for hygroscopic suppressants in the magnesium chloride market.
Chloride Runoff, Soil Accumulation, and Ecosystem Exposure
Chloride accumulation near treated roads is a documented environmental concern for the magnesium chloride market, with regulators in the United States and Europe paying greater attention to runoff and application practices. A 2025 U.S. Geological Survey review of three highway watersheds in Essex County, New York, found highway runoff chloride concentrations ranging from 0.75 to 29,200 mg/L. Downstream median surface-water concentrations were 10-45 times higher than upstream levels, and Lake George concentrations had risen nearly 30-fold since 1940, approaching the U.S. Environmental Protection Agency chronic aquatic-life threshold of 230 mg/L. Indiana transportation research found that chloride accumulation can reduce infiltration into roadside soil and plant viability beyond the application season. Colorado State University advises against using magnesium chloride on roads through forested areas or on steep slopes due to risks to sensitive conifers. More prescriptive local limits could reduce procurement in sensitive areas of the magnesium chloride market.
Other drivers and restraints analyzed in the detailed report include:
- Magnesium Chloride Adoption in Low-Carbon Building Materials
- Expansion of Magnesium Metal and Chemical Derivative Production
- Corrosion of Vehicles, Bridges, and Reinforced Concrete
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Anhydrous magnesium chloride held 56.34% of the magnesium chloride market share in 2025 and had the highest forecast CAGR at 5.67% through 2031. Its position is based on its role in primary magnesium electrolysis and titanium sponge co-production. Electrolytic production has a lower reported greenhouse gas profile than the Pidgeon route, supporting demand for high-purity anhydrous feedstock among manufacturers subject to emissions reporting requirements. A 2025 review examined dehydration methods for converting bischofite (MgCl2*6H2O) into anhydrous magnesium chloride. Co-solvent dehydration and reactive drying can reduce hydrolysis byproducts that impair electrolysis performance, supporting quality-focused pricing in the magnesium chloride market.
Hexahydrate magnesium chloride, or bischofite, held the second-largest position, serving food, pharmaceutical, and dust-control applications where a solution-phase product is acceptable. Liquid brine was the third product type, used in municipal road-spraying programs where agencies favor ready-to-use liquids for anti-icing pre-treatment. In these programs, magnesium chloride competes with calcium chloride brine on price and operating performance. Bischofite is also the basis for food-grade nigari used in tofu coagulation, requiring recrystallization and certification before food use.
Flakes accounted for 44.82% of the magnesium chloride market in 2025 and were the fastest-growing form, with a 5.95% CAGR through 2031. They are used for winter de-icing and summer dust control. Their hygroscopic surface enables rapid moisture absorption, supporting use in manual broadcast equipment and bulk spreader trucks. ICL Group's Dead Sea Works reported an annual output of 137 kt of solid magnesium chloride, with flakes as its primary solid product.
Granules ranked second among forms and are used in controlled-release agricultural applications and road pre-treatment programs where a slower dissolution rate is required. The Others category includes pellets, powders, and specialized forms for pharmaceutical manufacturing and laboratory reagents, serving applications with specific handling and purity requirements. Selection remains tied to the purchaser's application method and storage needs.
Complete Report Scope:
- By Product Type
- Anhydrous Magnesium Chloride
- Hexahydrate Magnesium Chloride
- Liquid Magnesium Chloride Brine
- By Form
- Flakes
- Granules
- Others
- By Grade
- Industrial Grade
- Technical Grade
- Food Grade
- Others
- By Application
- Metallurgy
- Chemical Processing and Derivatives
- Building Materials
- Road Stabilization and De-Icing
- Food and Feed
- Pharmaceuticals
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America accounted for 33.05% of the global magnesium chloride market share in 2025. Annual winter maintenance programs in the United States and Canada support this position, with many programs operating through multi-year blanket contracts. Compass Minerals reported fiscal year 2025 Salt segment revenue of USD 1,022.5 million, up 13%, driven by improvements in deicing pricing and quantity. Summer dust-control contracts in arid western states provide an additional layer of demand, where water-rights restrictions can make water-truck applications less practical. Compass Minerals' Great Salt Lake Ogden facility and regional distributors provide buyers with multiple procurement options in the magnesium chloride market.
Asia-Pacific is forecast to record the fastest regional CAGR of 5.78% through 2031. China's salt lakes and integrated chlor-alkali production bases are concentrated in Shandong, Qinghai, and Tianjin, giving these bases cost advantages in industrial-grade materials. India is an emerging consumer market due to construction activity, demand for agricultural magnesium, and food-grade use in processed foods. Japan and South Korea are established markets for higher-specification technical and food-grade materials, and also use magnesium chloride in semiconductor-adjacent chemical processing and traditional food production.
Europe requires high product quality across deicing salt blends, potassium-magnesium fertilizers, and industrial-grade material. Germany, the United Kingdom, France, Italy, and the Nordic countries are the main regional demand centers. K+S's Potash and Magnesium activities support supply for technical, industrial, and pharmaceutical uses. South America represents a smaller opportunity, with Brazil and Argentina investing in interior agricultural roads that require dust control. The Middle East and Africa also remain smaller markets. ICL Dead Sea Works supplies premium solid magnesium chloride from its 52 km2 Dead Sea concession, serving food and pharmaceutical buyers across global destinations. Overall, geographic demand in the magnesium chloride market reflects a combination of weather-related road use, industrial specifications, and construction activity.
- Alkim Alkali Kimya A.S.
- Antera Agro Chem
- Celtic Chemicals
- Compass Minerals
- DEUSA International GmbH
- HuiTai Investment Co
- ICL
- Intrepid Potash
- K+S Aktiengesellschaft
- Nedmag B.V.
- NikoMag
- Shandong Haihua Group Co., Ltd.
- Shouguang Dingsheng Chemical Co., Ltd.
- Skyline Chemical Corporation
- Tianjin Changlu Haijing Group Co., Ltd.
- Weifang Yuze Chemical Co., Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Municipal De-Icing and Anti-Icing Procurement
- 4.2.2 Expansion of Magnesium Metal and Chemical Derivative Production
- 4.2.3 Growth in Construction Dust Control and Road Stabilization
- 4.2.4 Higher Demand for High-Purity and Traceable Grades
- 4.2.5 Brine-Based Production and Co-Product Valorization
- 4.2.6 Magnesium Chloride Adoption in Low-Carbon Building Materials
- 4.3 Market Restraints
- 4.3.1 Chloride Runoff, Soil Accumulation, and Ecosystem Exposure
- 4.3.2 Corrosion of Vehicles, Bridges, and Reinforced Concrete
- 4.3.3 Seasonal Demand Volatility and Municipal Inventory Risk
- 4.3.4 Brine-Source Concentration and Energy-Intensive Purification
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Anhydrous Magnesium Chloride
- 5.1.2 Hexahydrate Magnesium Chloride
- 5.1.3 Liquid Magnesium Chloride Brine
- 5.2 By Form
- 5.2.1 Flakes
- 5.2.2 Granules
- 5.2.3 Others
- 5.3 By Grade
- 5.3.1 Industrial Grade
- 5.3.2 Technical Grade
- 5.3.3 Food Grade
- 5.3.4 Others
- 5.4 By Application
- 5.4.1 Metallurgy
- 5.4.2 Chemical Processing and Derivatives
- 5.4.3 Building Materials
- 5.4.4 Road Stabilization and De-Icing
- 5.4.5 Food and Feed
- 5.4.6 Pharmaceuticals
- 5.4.7 Others
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 NORDIC Countries
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Alkim Alkali Kimya A.S.
- 6.4.2 Antera Agro Chem
- 6.4.3 Celtic Chemicals
- 6.4.4 Compass Minerals
- 6.4.5 DEUSA International GmbH
- 6.4.6 HuiTai Investment Co
- 6.4.7 ICL
- 6.4.8 Intrepid Potash
- 6.4.9 K+S Aktiengesellschaft
- 6.4.10 Nedmag B.V.
- 6.4.11 NikoMag
- 6.4.12 Shandong Haihua Group Co., Ltd.
- 6.4.13 Shouguang Dingsheng Chemical Co., Ltd.
- 6.4.14 Skyline Chemical Corporation
- 6.4.15 Tianjin Changlu Haijing Group Co., Ltd.
- 6.4.16 Weifang Yuze Chemical Co., Ltd
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


