

|
시장보고서
상품코드
2155313
방수 테이프 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Waterproof Tapes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
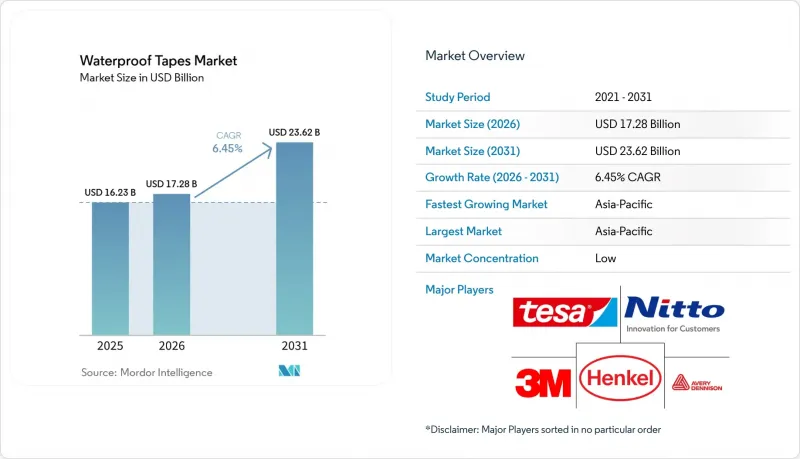
에 따르면 방수 테이프 시장 규모는 2025년에 162억 3,000만 달러로 평가되며, 2026년 172억 8,000만 달러에서 2031년까지 236억 2,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 6.45%에 달할 전망입니다.
전 세계 방수 테이프 시장의 동향 및 인사이트
건축물의 방수 공사 및 인프라 유지 관리 확대
인프라 갱신은 신축 공사만 있는 경우보다 방수 테이프 시장에 안정적인 수요원을 제공합니다. 노후화된 지붕, 외벽, 이음매의 보수에는 기존 구조물 주변에 시공할 수 있는 습기 관리 제품이 필요합니다. 미국에서는 노후화된 주택으로 인해 건축 외피 보수 공사가 반복적으로 발생하고 있으며, 이는 보수를 목적으로 하는 실링 시스템에 대한 수요를 지원하고 있습니다. 테이프 제품은 액상 대체재에 수반되는 경화 기간이 필요 없으며, 한 번의 시공으로 적용할 수 있습니다. 이 때문에 시공 속도가 공정 계획에 영향을 미치는 상업 프로젝트나 조립식 건축에서 유용합니다. 방수 테이프 시장은 시공업체가 준비 작업의 경감, 취급의 간편함, 복잡한 표면에서의 신뢰성 높은 성능을 중시하는 상황에서 혜택을 보고 있습니다. 이러한 상황은 보수 공사, 조립식 프로젝트, 접근이 제한된 현장이나 공기가 촉박한 현장에서 흔히 볼 수 있습니다. 또한 테이프를 사용하면 시공자가 습식 도포재의 경화를 기다리지 않고 다음 작업을 시작할 수 있으므로, 작업 순서를 간소화할 수도 있습니다.
전자제품 및 전기자동차 분야의 방습 요구 사항 증가
운송 수단의 전동화에 따라 테이프에 대한 요구 사항도 변화하고 있습니다. 배터리 모듈에는 절연성, 방습성 및 열 안정성이 동시에 요구되기 때문입니다. 기존 등급으로는 반복되는 열 사이클을 견디지 못하는 경우, 실리콘이나 고성능 아크릴 배합 테이프가 선호됩니다. 이러한 용도에서는 지속적인 작동 스트레스 하에서도 접착력을 유지할 수 있는 더 얇은 소재에 대한 수요가 높아지고 있습니다. 또한 제한된 공간에 정밀한 다이컷 부품이 필요한 디바이스 설계 역시 방수 테이프 시장의 확대에 기여하고 있습니다. 유럽의 스마트폰 수리 요건으로 인해 단말기를 개봉하고 재조립할 때 실링 수요가 증가할 가능성이 있습니다. 제조업체는 얇은 디자인과 습기, 열, 수리 후 반복적인 취급에 대한 내성 사이의 균형을 맞춰야 합니다. 이에 따라 더 복잡한 밀봉 기법으로 인한 무게나 공간 증가를 초래하지 않으면서 기기를 보호하는 데 고성능 테이프가 중요한 역할을 하고 있습니다.
원자재 가격 변동
방수 테이프 생산은 필름, 아크릴 모노머, 부틸 고무, 실리콘과 같은 원자재에 의존하고 있으나, 이러한 가격은 급격하게 변동할 가능성이 있습니다. 이러한 가격 변동 위험에 노출된 상황에서 공급 계약이나 사내 수지 생산 능력을 갖추지 못한 컨버터에게는 대응이 가장 어렵습니다. 원자재 가격의 빈번한 조정으로 인해 분기 내에 여러 차례 가격표 변경이 필요할 수 있으며, 이로 인해 고객은 프로젝트 예산 수립에 어려움을 겪을 수 있습니다. 대형 제조사는 장기 조달 계약이나 폭넓은 조달처를 확보함으로써 이러한 위험의 일부를 관리할 수 있습니다. 소규모 컨버터의 경우, 고객과의 계약 기간을 짧게 설정함으로써 비용 변동을 전가할 수밖에 없는 경우가 있습니다. 방수 테이프 시장은 특히 시장 경쟁으로 인해 제조사가 상승한 원자재 비용을 회수하는 능력이 제한될 때, 이러한 불균형한 비용 상황에 지속적으로 노출되어 있습니다. 그 결과 발생하는 압박은 제품 선정, 계약 조건 및 고객의 구매 시기에 영향을 미칠 가능성이 있습니다. 또한 제조업체 입장에서는 조달 체계를 개선하거나, 기술적 가치를 통해 보다 안정적인 가격 책정이 가능한 용도를 우선시하도록 유도하는 요인이 되기도 합니다.
부문 분석
실리콘은 2025년 방수 테이프 시장 점유율의 43.16%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 7.04%로 확대될 것으로 예측됩니다. 이러한 위상은 실리콘의 성능이 전자제품, 전기자동차 조립 및 피부에 접촉하는 의료 용도의 요구 사항과 부합함을 반영합니다. 이 소재는 -50°C에서 200°C에 이르는 온도 범위에서 기능을 유지할 수 있으며, 이는 배터리 케이스 및 전력 전자 장치에 있으며, 중요합니다. 또한 지속적인 열 사이클에 노출되는 용도에서 방습성과 유전 성능도 발휘합니다. 이러한 복합적인 요구 사항으로 인해 고부가가치 조립품에서 범용 제품의 적용이 제한되고 있습니다.
아크릴은 자외선에 대한 안정성을 갖추고 있으며, 수성 캐리어 시스템과의 호환성이 좋아 건축·건설, 포장 및 일반 산업 분야에서 계속해서 널리 사용되고 있습니다. 부틸 테이프는 불규칙하거나 습한 표면에서 상온 접착이 요구되는 지하 방수, 배관 접합부 실링, 지붕 관통부 등에서 여전히 중요한 역할을 하고 있습니다. 고무계 핫멜트 및 하이브리드 화학 물질을 포함한 기타 수지는 식품 접촉용 포장 및 고습도 환경의 산업 용도에 대응하고 있습니다. 수지 수요는 프리미엄 실리콘 및 첨단 아크릴 배합과 인프라 용도로 사용되는 비용 중심의 제품 사이에서 점차 양극화되고 있습니다. 이로 인해 초기 재료 비용보다 검증된 성능이 중시되는 방수 테이프 업계에서 실리콘은 여전히 중심적인 위치를 차지하고 있습니다. 이러한 용도의 구매자들은 대체재가 단열성, 밀봉성, 내구성 요건을 충족할 수 있다는 증거가 없는 한, 소재를 변경할 가능성이 낮습니다. 그 결과, 수지 선정은 완제품의 사용 조건 및 승인 요건과 밀접하게 연관되어 있습니다.
지역별 분석
아시아태평양은 2025년에 방수 테이프 시장 점유율의 36.57%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 7.68%로 확대될 전망입니다. 이 지역은 대규모 전자기기 제조 거점인 동시에 주요 건설 시장이기도 합니다. 중국은 전자기기 생산, 인프라 구축, 전기자동차 조립을 통해 지역내 수요를 지원하고 있습니다. 일본과 한국은 디스플레이, 자동차 및 첨단 기기 용도를 위한 정밀한 제품 형태에 중점을 두고 있습니다. 닛토덴코 주식회사는 44억 8,000만 대만 달러(약 1억 4,030만 달러)를 투자하여 2026년 7월 가오슝에 제조 및 연구 시설을 완공했습니다.
이 시설에서는 반도체 및 자동차 업계 고객을 대상으로 폴리염화비닐 테이프와 전자용 접착 테이프를 생산하고 있습니다. 인도, 동남아시아국가연합(ASEAN) 국가들, 그리고 한국은 의료, 인프라, 자동차 생산 각 분야에서 성장을 주도하고 있습니다. 이로 인해 범용 등급 및 중성능 등급 모두에 대한 폭넓은 수요가 지원되고 있습니다. 북미에서는 인프라 보수, 대규모 자동차 애프터마켓, 그리고 보수 제품의 광범위한 소매 유통이 호재로 작용하고 있습니다. 멕시코는 자동차 조립 및 제조에 대한 투자를 통해 산업 수요에 기여하고 있습니다. 캐나다에서는 추운 지역에서 시공 시에도 접착력을 유지하는 부틸계 및 첨단 아크릴계 제품이 독자적인 틈새 시장을 형성하고 있습니다. 북미 전역에서 성숙한 보수 유통망과 확립된 시공업체 관행이 유지보수 및 신축 공사에 사용되는 제품에 대한 지속적인 수요를 지원하고 있습니다.
유럽에서는 신축 및 대규모 개보수시 기밀성이 높고 습기 관리가 잘된 외벽을 권장하는 건축 규제의 영향을 받고 있습니다. 남미는 브라질과 아르헨티나가 주도하고 있으며, 주택, 인프라, 포장 분야가 수요를 지원하고 있습니다. 칠레에서는 신축 및 지진 피해를 입은 구조물의 복구 과정에서 유연한 방수 솔루션에 대한 수요가 있습니다. 중동 및 아프리카의 수요는 걸프협력회의(GCC) 회원국의 건설 공사와 남아프리카공화국의 산업용 유지보수에 의해 지원되고 있습니다. 사우디아라비아의 ‘비전 2030’에 기반한 인프라 정비 계획과 아랍에미리트(UAE)의 지속적인 상업용 부동산 개발은 건설 관련 수요의 주요 원천이 되고 있습니다. 이 지역의 비즈니스 기회는 프로젝트 진행 속도와 테이프 공급업체가 현지 성능 요건 및 유통 요건을 충족할 수 있는지 여부에 여전히 좌우됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 수지 유형별
- 기재 유형별
- 최종 용도 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- 3M
- Avery Dennison Corporation
- Henkel AG & Co. KGaA
- IPG
- LINTEC Corporation
- Lohmann
- Medline Industries, LP
- NICHIBAN Co., Ltd.
- Nitto Denko Corporation
- SEKISUI CHEMICAL CO., LTD.
- Shurtape Technologies, LLC
- Teraoka Seisakusho co.,Ltd.
- tesa SE
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the waterproof tapes market size was valued at USD 16.23 billion in 2025 and is estimated to grow from USD 17.28 billion in 2026 to reach USD 23.62 billion by 2031, at a CAGR of 6.45% during the forecast period (2026-2031).
Global Waterproof Tapes Market Trends and Insights
Expansion of Building Waterproofing and Infrastructure Maintenance
Infrastructure renewal gives the waterproof tapes market a steadier source of demand than new construction activity alone. Repairs to older roofs, facades, and joints require moisture-management products that can be fitted around existing structures. In the United States, older housing creates recurring work on building envelopes and supports demand for repair-oriented sealing systems. Tape products can be applied in a single pass, without the cure periods associated with liquid alternatives. This makes them useful in commercial projects and prefabricated construction, where installation speed affects scheduling. The waterproof tapes market benefits where contractors value reduced preparation, simpler handling, and dependable performance on complex surfaces. These conditions are common in repair work, prefabricated projects, and installations with limited access or narrow scheduling windows. Tape can also simplify sequencing because the installer does not need to wait for a wet-applied material to cure before the next task begins.
Rising Moisture-Protection Requirements in Electronics and Electric Vehicles
Transport electrification changes tape requirements because battery modules need insulation, moisture protection, and thermal stability at the same time. Silicone and high-performance acrylic formulations are favored where conventional grades cannot withstand repeated thermal cycling. These applications support demand for thinner materials that retain adhesion under sustained operating stress. The waterproof tapes market also gains from device designs that need precision die-cut parts for tight spaces. European repair requirements for smartphones can add sealing demand when devices are opened and reassembled. Manufacturers must balance thin construction with resistance to moisture, heat, and repeated handling after repair. This gives high-performance tapes a role in maintaining device protection without adding the weight or space associated with more complex sealing approaches.
Raw Material Price Volatility
Waterproof tape production depends on films, acrylic monomers, butyl rubber, and silicone inputs whose prices can change quickly. This exposure is most difficult for converters that do not have supply contracts or internal resin capacity. Frequent input adjustments can require several price-list changes within a quarter and make project budgeting harder for customers. Larger manufacturers can manage some of this risk through longer purchasing arrangements and broader sourcing options. Smaller converters may have to pass through cost movements using shorter customer contracts. The waterproof tapes market remains exposed to this uneven cost position, especially where price competition limits a producer's ability to recover higher input costs. The resulting pressure can affect product selection, contract terms, and the timing of customer purchases. It also encourages manufacturers to improve sourcing discipline and to prioritize applications where technical value supports more stable pricing.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Healthcare Wearables and Waterproof Medical Fixation
- Preference for Fast, Clean, Lightweight Sealing over Liquid Sealants
- Competition from Liquid Sealants, Membranes, and Mechanical Fasteners
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone held 43.16% of the waterproof tapes market share in 2025 and is projected to advance at a 7.04% CAGR through 2031. Its position reflects the alignment between silicone performance and requirements in electronics, electric vehicle assembly, and skin-contact medical uses. The material can maintain function across temperatures from -50 °C to 200 °C, which is important for battery enclosures and power electronics. It also supports moisture protection and dielectric performance in applications subject to sustained thermal cycling. These combined needs restrict the suitability of commodity products in high-value assemblies.
Acrylic remains widely used in building and construction, packaging, and general industrial applications because it provides ultraviolet stability and works with water-based carrier systems. Butyl tapes remain important for underground waterproofing, pipe-joint sealing, and roofing penetrations where irregular or wet surfaces require cold-applied adhesion. Other resins, including rubber-based hot-melt and hybrid chemistries, address food-contact packaging and high-humidity industrial conditions. Resin demand is gradually separating between premium silicone and advanced acrylic formulations, and value-focused products used in infrastructure applications. This keeps silicone central to the waterproof tapes industry, where validated performance matters more than initial material cost. Buyers in these uses are less likely to change materials without evidence that an alternative can maintain insulation, sealing, and durability requirements. As a result, resin selection is closely tied to the operating conditions and approval needs of the finished assembly.
Complete Report Scope:
- By Resin Type
- Silicone
- Acrylic
- Butyl
- Others
- By Substrate Type
- Plastic
- Metal
- Rubber
- Others
- By End-Use Industry
- Electrical and Electronics
- Automotive
- Building and Construction
- Healthcare
- Packaging
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 36.57% of the waterproof tapes market share in 2025 and is projected to advance at a 7.68% CAGR through 2031. The region is both a large electronics manufacturing center and a major construction market. China supports regional demand through electronics production, infrastructure work, and electric vehicle assembly. Japan and South Korea emphasize precision formats for display, automotive, and advanced device applications. Nitto Denko Corporation completed a Kaohsiung manufacturing and research facility in July 2026 after a TWD 4.48 billion (approximately USD 140.3 million) investment.
The facility produces polyvinyl chloride tapes and electronic adhesive tapes for semiconductor and automotive customers. India, the Association of Southeast Asian Nations countries, and South Korea add growth across healthcare, infrastructure, and automotive production. This supports broad demand for both commodity and mid-performance grades. North America benefits from infrastructure repair, a large automotive aftermarket, and broad retail distribution for repair products. Mexico contributes to industrial demand through automotive assembly and manufacturing investment. Canada provides a separate niche for butyl and advanced acrylic products that retain adhesion during cold-weather installation. Across North America, mature repair channels and established contractor practices support recurring demand for products used in maintenance as well as new construction.
Europe is influenced by building rules that favor airtight and moisture-managed envelopes in new construction and deep renovation. South America is led by Brazil and Argentina, where housing, infrastructure, and packaging support demand. Chile has a need for flexible waterproofing solutions in new construction and repairs to earthquake-affected structures. The Middle East and Africa demand is supported by construction in Gulf Cooperation Council countries and industrial maintenance in South Africa. Saudi Arabia's Vision 2030 infrastructure pipeline and continued commercial real estate development in the United Arab Emirates represent concentrated sources of construction-related demand. The regional opportunity remains tied to the pace of project execution and the ability of tape suppliers to meet local performance and distribution requirements.
- 3M
- Avery Dennison Corporation
- Henkel AG & Co. KGaA
- IPG
- LINTEC Corporation
- Lohmann
- Medline Industries, LP
- NICHIBAN Co., Ltd.
- Nitto Denko Corporation
- SEKISUI CHEMICAL CO., LTD.
- Shurtape Technologies, LLC
- Teraoka Seisakusho co.,Ltd.
- tesa SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Building Waterproofing and Infrastructure Maintenance
- 4.2.2 Rising Moisture-Protection Requirements in Electronics and Electric Vehicles
- 4.2.3 Growth of Healthcare Wearables and Waterproof Medical Fixation
- 4.2.4 Preference for Fast, Clean, Lightweight Sealing over Liquid Sealants
- 4.2.5 E-Commerce and Do-It-Yourself Repair Adoption
- 4.3 Market Restraints
- 4.3.1 Raw Material Price Volatility
- 4.3.2 Competition from Liquid Sealants, Membranes, and Mechanical Fasteners
- 4.3.3 Product Differentiation and Certification Complexity
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Silicone
- 5.1.2 Acrylic
- 5.1.3 Butyl
- 5.1.4 Others
- 5.2 By Substrate Type
- 5.2.1 Plastic
- 5.2.2 Metal
- 5.2.3 Rubber
- 5.2.4 Others
- 5.3 By End-Use Industry
- 5.3.1 Electrical and Electronics
- 5.3.2 Automotive
- 5.3.3 Building and Construction
- 5.3.4 Healthcare
- 5.3.5 Packaging
- 5.3.6 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Avery Dennison Corporation
- 6.4.3 Henkel AG & Co. KGaA
- 6.4.4 IPG
- 6.4.5 LINTEC Corporation
- 6.4.6 Lohmann
- 6.4.7 Medline Industries, LP
- 6.4.8 NICHIBAN Co., Ltd.
- 6.4.9 Nitto Denko Corporation
- 6.4.10 SEKISUI CHEMICAL CO., LTD.
- 6.4.11 Shurtape Technologies, LLC
- 6.4.12 Teraoka Seisakusho co.,Ltd.
- 6.4.13 tesa SE
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


