

|
시장보고서
상품코드
2155314
평강 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Flat Steel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
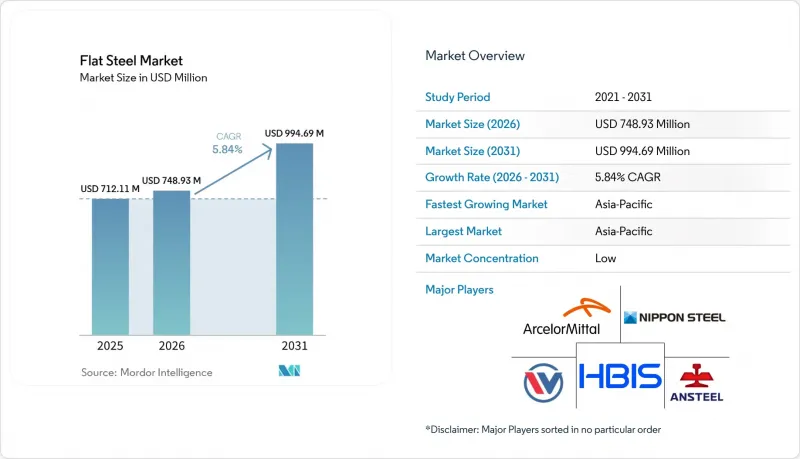
에 따르면 평강 시장 규모는 2025년에 7억 1,211만 달러로 추계되고 있으며, 예측 기간(2026-2031년)에 CAGR 5.84%로 확대하며, 2026년 7억 4,893만 달러에서 2031년에는 9억 9,469만 달러에 달할 것으로 전망되고 있습니다.
세계 평강 시장의 동향 및 인사이트
인프라 현대화 및 산업용 건설
정부 주도의 자본 지출은 건축 외장, 교량 데크, 창고 및 산업 시설에 사용되는 평판 강재 제품에 대한 확실한 수요 원천으로 자리 잡고 있습니다. 인도의 철강 수요는 국가 인프라 계획 및 자동차 생산에 힘입어 2025년에 증가했습니다. 미국은 공공 인프라 지출 및 조선 계획을 구조용 강판이 사용되는 분야에 집중하고 있습니다. 2026년 2월에 발표된 ‘미국 해양 행동 계획’은 이러한 수요에 대한 추가적인 원천이 되고 있습니다. 조립식 및 모듈식 건축에서는 현장 성형 부재보다 코팅 및 도장 처리된 강판이 더 자주 사용되므로 평강 시장에서 제품의 품질과 마감의 중요성이 점점 더 커지고 있습니다.
자동차 경량화 및 전기자동차 생산
전기자동차(EV) 플랫폼은 배터리 팩의 무게가 400-800킬로그램 증가함에 따라 평강에 대한 수요 패턴에 변화를 가져오고 있습니다. 자동차 제조사들은 차량 중량을 관리하고 배터리 시스템을 보호하기 위해 프레스 경화강, 냉간 압연 듀얼 페이즈강 및 초고장력강을 사용하고 있습니다. 초고장력강은 기존 강재에 비해 차량의 구조 중량을 15%에서 25%까지 줄일 수 있습니다. 이러한 강종은 충돌 안전 성능을 유지하면서 차체 구조 부품의 두께를 얇게 만들 수 있게 해줍니다. 그 결과, 제품 구성은 기존의 열간압연 코일에서 더 엄격한 인증 요건을 충족하는 특수 소재로 전환되고 있습니다. 이는 주요 자동차 생산 거점 인근에서 자동차용 등급의 제품을 안정적으로 공급할 수 있는 제조업체에게 유리하게 작용합니다.
세계적인 철강 생산 과잉과 수출 압력
전 세계 철강 과잉 생산 능력은 2025년에 6억 4,000만 톤에 달하고, 2028년까지 7억 4,500만 톤으로 증가할 것으로 예측됩니다. 중국은 2025년에 사상 최대인 1억 3,120만 톤의 철강을 수출했는데, 이는 부동산 시장의 침체로 인해 생산이 수출 시장으로 전환되었기 때문입니다. 이러한 변화는 열연 및 냉연 평판 제품을 판매하는 아세안, 남미, 유럽의 생산자들에게 특히 큰 영향을 미치고 있습니다. 2025년, 중국에서 동남아시아로 수출된 반제품 강재는 300% 증가했으며, 그 일부는 가공 후 재수출되었습니다. OECD 기록에 따르면 2025년에는 75건의 새로운 반덤핑 및 상계관세 조사가 실시되었습니다. 무역 조치로 인해 일부 수입이 제한될 가능성은 있지만, 근본적인 공급 과잉이나 이것이 가격에 미치는 영향을 해결하는 것은 아닙니다.
부문별 분석
2025년, 시트 및 스트립은 평강 시장에서 금액 기준 74.73%의 점유율을 차지했습니다. 이는 자동차 차체 패널, 가전제품 케이스, 건축 외장재, 태양광발전용 랙 프레임 등으로의 용도를 반영한 것입니다. 플레이트는 압력 용기, 조선, 중장비 프레임 등 보다 전문적인 용도로 사용됩니다. 시트 및 스트립의 최종 용도가 광범위하다는 점이 그 지배적인 지위를 설명해 줍니다. 범용 열간압연 코일은 이 제품군 중에서 생산량은 많지만 이익률은 낮은 부문입니다. 반면, 냉간 압연 및 코팅 제품은 표면 품질, 성형성, 내식성에 대한 요구 사항이 더 엄격하므로 부가가치가 높습니다.
시트 및 스트립 시장 규모는 2026-2031년에 연평균 성장률(CAGR) 6.34%로 확대될 것으로 예측됩니다. 이러한 성장은 지붕 자재, 태양전지판 기판, 전기자동차 구조 부품에 사용되는 아연·알루미늄·마그네슘 도금 제품에 의해 지원되고 있습니다. 일본 산업 규격의 제정으로 인해 국내 생산은 첨단 고강도 등급에 대한 자동차 OEM 제조사의 요구 사항과 더욱 밀접하게 부합하게 되었습니다. 각 공급업체는 범용 코일 시장의 경쟁 압력에 대응하기 위해 부가가치가 높은 표면 처리 및 고등급 제품으로의 전환을 추진하고 있습니다. 시트 및 스트립에 대한 의존도가 높기 때문에 코일 가격 변동은 계속해서 플랫 강재 시장 전체에 영향을 미치고 있습니다. 생산자들은 코팅 제품, 자동차용 등급 및 기타 차별화된 제품 카테고리에서 매출을 늘림으로써 이러한 영향을 완화할 수 있습니다.
지역별 분석
아시아태평양은 2025년에 평판강 시장 점유율의 44.39%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 6.27%로 성장할 것으로 전망됩니다. 중국에서는 부동산 시장의 침체가 지속됨에 따라 2025년 국내 평판강 소비량이 6.9% 감소했습니다. 인도의 철강 수요는 2025년에 9.8% 증가했습니다. 아세안(ASEAN)의 수요는 제조업 투자와 공공 인프라 사업에 힘입어 2025년에 4.3% 증가했습니다. 한국과 일본은 2025년에 합계 5.1%의 수요 감소를 기록했습니다.
북미는 평판강 시장에서 두 번째로 큰 규모를 자랑하는 지역입니다. 2025년 미국의 수요는 0.7% 증가했습니다. 이는 주택 건설의 부진을 산업 활동과 공공 인프라 지출이 상쇄했기 때문입니다. 캐나다에서는 2025년에 2.7%의 수요 증가가 나타난 반면, 멕시코에서는 4.6%의 감소를 기록했습니다. 2025년 6월에 50%로 인상된 제232조 관세로 인해 국내 생산자에 대한 수입 압력이 어느 정도 억제되었습니다. 또한 미국의 ‘해사 행동 계획’도 조선 분야의 강판 수요를 지원할 것으로 예상됩니다. 2025년 국내 평판강 출하량의 60%를 전기 아크로 제조사가 차지하고 있으며, 이 생산 경로에서 해당 지역은 확고한 입지를 구축하고 있습니다.
2025년 유럽의 평판강 수요는 1.2% 감소했으며, 프랑스는 12.6% 감소, 독일은 6.1% 감소했습니다. 유럽연합(EU)은 2026년 4월, 할당 초과분에 대한 철강 관세를 25%에서 50%로 인상하고, 평판강 수입 할당량을 EU 소비량의 15%로 제한했습니다. 남미의 수요는 2025년에 0.7% 증가했습니다. 중동의 수요는 2025년에 6.4% 증가했으며, 아프리카는 건설 및 에너지 인프라 투자에 힘입어 16.1% 증가했습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 생산 프로세스별
- 최종사용자 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 러시아
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Ansteel Group Corporation Limited
- ARCELORMITTAL
- BAOWU Metal
- Cleveland-Cliffs Inc.
- HBIS GROUP
- HYUNDAI Corporation
- JFE Steel Corporation
- JSW Steel Limited
- NIPPON STEEL CORPORATION
- Nucor Corporation
- Posco Group
- SHAGANG GROUP Inc.
- Shandong Jianlong Steel Co.
- Shougang Group Co., Ltd.
- Tata Steel Limited
- United States Steel Corporation
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the flat steel market size was estimated at USD 712.11 million in 2025 and is estimated to grow from USD 748.93 million in 2026 to USD 994.69 million by 2031, at a CAGR of 5.84% during the forecast period (2026-2031).
Global Flat Steel Market Trends and Insights
Infrastructure Renewal and Industrial Construction
Government-backed capital spending remains a reliable source of demand for flat steel products used in building envelopes, bridge decks, warehouses, and industrial facilities. India's steel demand grew in 2025, supported by the National Infrastructure Pipeline and automotive production. The United States is directing public infrastructure spending and shipbuilding plans toward applications that use structural plate. America's Maritime Action Plan, released in February 2026, provides an additional channel for this demand. Prefabricated and modular construction uses coated and pre-painted sheets more frequently than site-formed sections, increasing the importance of product quality and finishing within the flat steel market.
Automotive Lightweighting and Electric Vehicle Production
Electric vehicle platforms create a different demand pattern for flat steel because battery packs add 400 to 800 kilograms of weight. Automakers use press-hardened steel, cold-rolled dual-phase grades, and advanced high-strength steel to manage vehicle weight and protect battery systems. Advanced high-strength steel can reduce vehicle structural weight by 15% to 25% compared with conventional steel. These grades support crash performance while allowing thinner components in body structures. The product mix, therefore, shifts away from conventional hot-rolled coil and toward specialized materials with tighter certification requirements. This favors producers that can consistently supply automotive-grade products near major vehicle manufacturing centers.
Global Steel Overcapacity and Export Pressure
Global excess steelmaking capacity reached 640 million tons in 2025 and is projected to rise to 745 million tons by 2028. China exported a record 131.2 million tons of steel in 2025, as weaker real estate activity redirected output toward export markets. This shift particularly affects producers in ASEAN, South America, and Europe that sell hot-rolled and cold-rolled flat products. China's semi-finished steel exports to Southeast Asia increased by 300% in 2025, and some of the material was re-exported after processing. The OECD recorded 75 new antidumping and countervailing duty investigations in 2025. Trade actions may limit some imports, but they do not address the underlying surplus or its effect on prices.
Other drivers and restraints analyzed in the detailed report include:
- Renewable Energy and Grid Equipment Expansion
- Advanced High-Strength Steel Adoption
- Volatile Iron Ore, Coking Coal, and Scrap Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sheets and strips held 74.73% of the flat steel market share by value in 2025. This reflects their use in automotive body panels, appliance casings, building envelopes, and solar racking frames. Plates are used in more specialized applications, including pressure vessels, shipbuilding, and heavy machinery frames. The wider range of end uses for sheets and strips explains their dominant position. Commodity hot-rolled coil represents the larger-output, lower-margin segment within this product group. Cold-rolled and coated variants carry a higher value due to tighter requirements for surface quality, forming, and corrosion performance.
Sheets and strips are forecast to grow at a 6.34% CAGR from 2026 to 2031. This growth is supported by zinc-aluminum-magnesium-coated products used in roofing, solar substrates, and electric vehicle structures. Japan's industrial standards work has more closely aligned domestic production with automotive original equipment manufacturer requirements for advanced high-strength grades. Suppliers are responding to competitive pressure in commodity coil by expanding into value-added finishes and higher-grade products. The heavy reliance on sheets and strips means changes in coil prices continue to influence the broader flat steel market. Producers can reduce this exposure by growing sales in coatings, automotive grades, and other differentiated product categories.
Complete Report Scope:
- By Product Type
- Sheets and Strips
- Plates
- By Production Process
- Basic Oxygen Furnace
- Electric Arc Furnace
- Others
- By End-User Industry
- Building and Infrastructure
- Mechanical Equipment
- Automotive and Other Transport
- Renewable Energy and Power Equipment
- Other End-Use Sectors
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 44.39% of the flat steel market share in 2025 and is forecast to grow at a 6.27% CAGR through 2031. China's domestic flat steel consumption declined 6.9% in 2025 as its real estate downturn continued. India's steel demand grew 9.8% in 2025. ASEAN demand grew 4.3% in 2025, supported by manufacturing investment and public infrastructure programs. South Korea and Japan recorded a combined 5.1% decline in demand in 2025.
North America is the second-largest region in the flat steel market. United States demand grew 0.7% in 2025, with industrial activity and public infrastructure spending helping to offset weak residential construction. Canada recorded 2.7% demand growth in 2025, while Mexico recorded a 4.6% decline. Section 232 tariffs, increased to 50% in June 2025, limited some import pressure on domestic producers. America's Maritime Action Plan is also expected to support plate demand from shipbuilding. Electric arc furnace producers accounted for 60% of domestic flat steel shipments in 2025, positioning the region strongly in this production route.
Europe's flat steel demand declined 1.2% in 2025, with France down 12.6% and Germany down 6.1%. The European Union raised above-quota steel tariffs from 25% to 50% in April 2026 and capped flat steel import quotas at 15% of European Union consumption. South America's demand grew 0.7% in 2025. Middle East demand grew 6.4% in 2025, while Africa grew 16.1%, supported by construction and energy infrastructure investment.
- Ansteel Group Corporation Limited
- ARCELORMITTAL
- BAOWU Metal
- Cleveland-Cliffs Inc.
- HBIS GROUP
- HYUNDAI Corporation
- JFE Steel Corporation
- JSW Steel Limited
- NIPPON STEEL CORPORATION
- Nucor Corporation
- Posco Group
- SHAGANG GROUP Inc.
- Shandong Jianlong Steel Co.
- Shougang Group Co., Ltd.
- Tata Steel Limited
- United States Steel Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure Renewal and Industrial Construction
- 4.2.2 Automotive Lightweighting and Electric Vehicle Production
- 4.2.3 Renewable Energy and Grid Equipment Expansion
- 4.2.4 Growth of Coated and Corrosion-Resistant Flat Steel
- 4.2.5 Advanced High-Strength Steel Adoption
- 4.3 Market Restraints
- 4.3.1 Global Steel Overcapacity and Export Pressure
- 4.3.2 Volatile Iron Ore, Coking Coal and Scrap Costs
- 4.3.3 Carbon Compliance and Decarbonization Capital Requirements
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Sheets and Strips
- 5.1.2 Plates
- 5.2 By Production Process
- 5.2.1 Basic Oxygen Furnace
- 5.2.2 Electric Arc Furnace
- 5.2.3 Others
- 5.3 By End-User Industry
- 5.3.1 Building and Infrastructure
- 5.3.2 Mechanical Equipment
- 5.3.3 Automotive and Other Transport
- 5.3.4 Renewable Energy and Power Equipment
- 5.3.5 Other End-Use Sectors
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Ansteel Group Corporation Limited
- 6.4.2 ARCELORMITTAL
- 6.4.3 BAOWU Metal
- 6.4.4 Cleveland-Cliffs Inc.
- 6.4.5 HBIS GROUP
- 6.4.6 HYUNDAI Corporation
- 6.4.7 JFE Steel Corporation
- 6.4.8 JSW Steel Limited
- 6.4.9 NIPPON STEEL CORPORATION
- 6.4.10 Nucor Corporation
- 6.4.11 Posco Group
- 6.4.12 SHAGANG GROUP Inc.
- 6.4.13 Shandong Jianlong Steel Co.
- 6.4.14 Shougang Group Co., Ltd.
- 6.4.15 Tata Steel Limited
- 6.4.16 United States Steel Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


