

|
시장보고서
상품코드
2155671
유리섬유 바닥재 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Fiberglass Flooring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
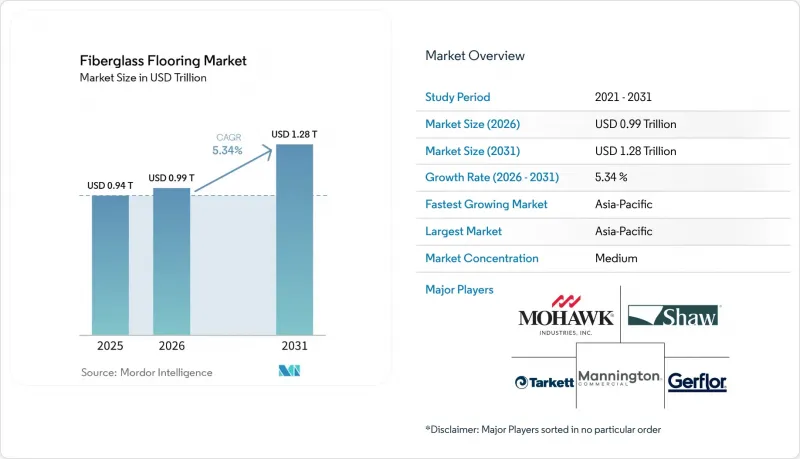
에 따르면 유리섬유 바닥재 시장 규모는 2025년에 9억 4,000만 달러, 2026년에 9억 9,000만 달러에 달하고, 2031년까지 12억 8,000만 달러에 달할 것으로 예측되며, 2026년부터 2031년까지 CAGR 5.34%로 성장할 것으로 전망됩니다.
세계 유리섬유 바닥재 시장의 동향 및 인사이트
방수성 및 치수 안정성이 뛰어난 바닥재에 대한 수요
유리섬유 바닥재 시장은 일반적인 온도 변동 조건에서도 안정성을 유지하는 바닥재에 대한 상업적 수요에 힘입어 성장하고 있습니다. 유리섬유 보강을 통해 뒤틀림, 가장자리 들뜸, 그리고 하층의 요철이 두드러지는 현상이 최소화되며, 이러한 현상들은 시설 운영 단계에서 조기 바닥재 교체를 초래할 수 있습니다. 의료, 외식, 교육 분야의 구매 담당자들은 상업 시설의 난방, 환기, 공조(HVAC) 환경에서도 치수 안정성이 보장된다는 보증을 점점 더 요구하고 있습니다. 디지털 인쇄 기술의 발전으로 인해 상업 시설 인테리어에서 탄성 바닥재와 세라믹 타일의 외관상 차이는 줄어들고 있습니다. 그 결과, 조달 결정에 있어 외관뿐만 아니라 치수 성능과 유지보수 요건이 점점 더 중요하게 여겨지고 있습니다. 인터페이스(Interface)사는 2026년 2월, 폴리염화비닐(PVC)을 포함하지 않는 탄성 바닥재 플랫폼 ‘Noravant’를 발표했으며, 이 제품의 수명은 최대 35년으로 알려져 있습니다. 이번 개발은 상업 시설에서 저휘발성 유기화합물(VOC)을 배출하며 치수 안정성이 뛰어난 탄성 바닥재에 대한 수요를 반영한 것입니다.
상업 시설의 리노베이션 및 공공 시설 건설의 확대
유리섬유 백킹 바닥재 시장은 가격에 민감한 조달 환경 속에서 초기 비용이라는 장벽에 직면해 있습니다. 유리섬유 백킹이 적용된 고급 비닐 타일(LVT) 및 비닐 시트 제품은 기존의 세라믹 타일이나 두께가 지정되지 않은 비닐에 비해 20-40% 정도 비쌀 수 있습니다. 아시아태평양, 중동 및 아프리카, 남미 등의 신흥 시장 구매자들은 수년에 걸친 유지 관리비 절감보다 연간 자본 예산을 우선시하는 경향이 있습니다. 이러한 동향으로 인해 선진국의 상업 프로젝트와 신흥 시장의 저비용 프로젝트 간에 뚜렷한 구매 패턴 차이가 나타나고 있습니다. 2020년부터 2022년까지 연기되었던 설비 투자가 재개됨에 따라 진행되는 개보수 계획이 유리섬유 바닥재 시장을 뒷받침하고 있습니다. 의료 시설, 공립 학교, 정부 시설에서는 누적된 바닥재 교체 수요에 대한 대응이 계속되고 있습니다. 인도의 경우 2025년 1월 산업생산지수가 5.0%의 성장률을 기록했는데, 이는 상업용 및 산업용 바닥재의 다운스트림 수요를 뒷받침하는 활발한 제조 활동을 보여줍니다.
유리섬유, PVC, 수지, 가소제의 원가 변동
유리섬유 바닥재 시장은 유리섬유, PVC 수지, 가소제 및 에너지 가격 변동의 영향을 지속적으로 받고 있습니다. PVC 수지는 유리섬유 뒷면 처리 비닐 바닥재의 총 투입 비용의 45-50%를 차지하고 있어, 석유화학제품 가격 변동이 완제품의 이익률에 직접적인 영향을 미치고 있습니다. 2025년, 유럽 제조업체들은 에너지 비용 상승, 수요 부진, 경쟁력 있는 수입품, 가동률 하락에 직면하여 지역 공급 상황에 영향을 미쳤습니다. 2025년 9월, 중국의 유리섬유 제조업체들은 관세 관련 압박에 대응하여 원사 가격을 5-10% 인상했습니다. 또한, 화학제품의 등록, 평가, 허가 및 제한에 관한 규정(REACH)으로 인해 유럽 제조업체들은 프탈레이트계 가소제를 사용하지 않는 제품으로 전환할 수밖에 없었지만, 그 비용은 기존의 대체품보다 15-30% 더 높습니다. 통합된 공급망과 장기 원자재 조달 계약은 현물 구매에 비해 투입 비용 변동으로 인한 위험을 완화할 수 있습니다.
부문별 분석
2025년에는 럭셔리 비닐 타일(LVT)이 매출의 46.32%를 차지했습니다. 이러한 위상은 의료 시설, 소매점, 기업 인테리어 등 폭넓은 분야에서 채택되고 있음을 반영하며, 치수 안정성, 풍부한 디자인 선택지, 유지 관리가 용이하다는 특징이 높은 부가가치를 뒷받침하고 있습니다. 비닐 복합 타일(VCT)은 2026년부터 2031년까지 연평균 성장률(CAGR) 6.07%로 성장할 것으로 예상되며, 이는 제품 유형 중 가장 높은 성장률입니다. VCT는 초기 자본 예산이 자재 선정의 결정 요인이 되는 공립학교, 관공서, 지방 자치 단체의 의료 시설 등에서 계속해서 사용되고 있습니다. 성장이 빠르다고 해서 고부가가치 프로젝트에서 LVT 사양으로의 전환 추세가 역전되는 것은 아닙니다. 오히려 이는 예산을 중시하는 기관에서 VCT가 차지하는 역할과, LVT가 구매 임계치를 넘어서는 신흥 시장에서의 채택 현황을 반영한 것입니다.
비닐 시트는 병원 복도, 공항 콩코스, 식품 가공 시설, 클린룸 등에서 이음매 없는 시공에 있어 여전히 중요한 역할을 하고 있습니다. 이러한 환경에서는 위생 및 안전상의 이유로 이음매 없는 표면이 요구되지만, 타일 형태로는 이를 완벽하게 재현할 수 없습니다. 다층 유리섬유 바닥재와 관련된 사용 후 문제를 해결하기 위한 소재 개발은 계속되고 있습니다. 2025년 특허 출원에는 PVC의 완전한 재활용이 가능하도록 설계된, 유리섬유 직물로 보강된 다층 PVC 피복재가 기재되어 있습니다. 2028년까지 재활용 가능한 유리섬유 뒷면 처리 비닐이 유럽의 공공 조달 시장에서 상용화된다면, 유리섬유 바닥재 시장은 입찰에서 우위를 점할 가능성이 있습니다. 이러한 진전은 특히 성능 사양 외에도 순환 경제에 관한 문서가 요구되는 경우, 유리섬유 바닥재 시장에서 특정 친환경 조달 결정을 제한하고 있다는 우려를 해소해 줄 것입니다. 경질 코어형 석재-플라스틱 복합재(SPC) 제품은 LVT 부문 내에서 일정한 대체 압력을 발생시키고 있지만, 두께가 두꺼워짐에 따라 기존 바닥의 리노베이션이 복잡해질 가능성이 있습니다. 이러한 제약으로 인해 상업 시설의 리모델링 프로젝트에서 유연한 유리 매트 백킹형 LVT의 역할은 여전히 유지되고 있습니다.
지역별 분석
아시아태평양은 2025년에 유리섬유 바닥재 시장의 44.83%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.19%로 성장할 것으로 전망됩니다. 상업 시설의 인테리어 공사 및 인프라 투자가 계속해서 바닥재 수요를 견인하고 있어, 중국은 여전히 이 지역에서 가장 큰 기여를 하는 국가로 남아 있습니다. 인도의 ‘프라단 만트리 아와스 요자나 어반 2.0’에는 2024-25 회계연도에 2.2 락 크롤(263억 달러)의 예산이 배정되어, 저렴한 주택, 학교, 지역 의료 시설의 건설 계획이 뒷받침되고 있습니다. 또한 인도에서는 2025년 1월 산업 생산이 5.0% 증가하여 상업용 및 산업용 바닥재 수요를 견인하고 있습니다. 일본에서는 실내 공기질 관련 규제가 인증된 저휘발성 바닥재에 대한 수요를 뒷받침하고 있으며, LX Hausys 및 NOX Corporation 등의 제조업체들이 국내 및 아세안(ASEAN) 지역의 상업 프로젝트에 제품을 공급하고 있습니다.
아시아태평양 이외에서는 북미와 유럽이 최대의 수익원이 되고 있으나, 그 수요를 견인하는 요인은 서로 다릅니다. 북미에서는 1990년대부터 2000년대 초반에 걸쳐 학교, 정부 청사, 지역 의료 센터에 시공된 비닐 복합 타일(VCT)의 교체 공사가 수요의 주요 원동력이 되고 있습니다. 교체 프로젝트에서는 유리섬유 백킹이 적용된 럭셔리 비닐 타일(LVT)의 사용이 증가하고 있으며, 이로 인해 기존 상업 시설 전반에 걸쳐 평균 판매 가격 상승이 뒷받침되고 있습니다. 유럽에서는 2025년에 건설 및 리모델링 수요의 성장세가 둔화되었습니다. 포르보 플로어링 시스템즈는 2025년에 7억 3,820만 스위스 프랑(8억 2,400만 달러)의 매출을 기록했습니다. 북유럽 국가 및 독일에서는 저배출이 입증된 바닥재와 환경 제품 선언(EPD)에 대한 수요가 지속적으로 나타나고 있는 반면, REACH 규정의 요건으로 인해 기존의 가소제 함유 제품에 대한 규정 준수 비용이 증가하고 있습니다.
남미, 중동 및 아프리카는 사양 기준을 충족하는 유리섬유 바닥재에 있어 여전히 도입 초기 단계에 있는 지역입니다. 남미의 상업용 건축 및 호텔·리조트 시설 리노베이션 시장에서는 브라질이 가장 큰 점유율을 차지하고 있지만, 아르헨티나에서는 경제 변동으로 인해 리모델링 속도가 둔화되고 있습니다. 그러나 아르헨티나의 소매점 및 의료 시설에서는 여전히 탄력성 있는 바닥재 사양이 채택되고 있습니다. 사우디아라비아의 ‘비전 2030’과 관련된 건설 프로그램은 호텔·관광, 의료, 공항 터미널의 인테리어 공사에 대한 수요를 뒷받침하고 있습니다. 남아프리카공화국도 호텔·관광 업계 및 민간 의료 시설의 리모델링 프로젝트를 통해 수요를 견인하고 있습니다. 이러한 지역에서는 수요 수준이 현지 신규 생산 시설에 대한 투자를 정당화하지 못할 가능성이 있으므로, 유리섬유 바닥재 시장은 유통 계약 확대를 통해 해당 지역에 대응할 수 있습니다. 이러한 접근 방식을 통해 기존 공급업체는 수요가 충분한 규모에 도달하기 전에 생산 거점을 확보하지 않고도, 기존 유통 채널을 통해 지역 프로젝트 수요에 대응할 수 있게 됩니다.
기타 이점:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 용도별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- AWI Licensing, LLC
- Beaulieu International Group
- Congoleum
- Forbo Flooring Systems
- Gerflor
- Interface, Inc.
- IVC Group
- Karndean Designflooring
- LG Hausys
- Lico AG
- Mannington Commercial
- Milliken
- MOHAWK INDUSTRIES, INC.
- Novalis
- NOX Corporation
- Shaw Industries Group, Inc.
- Tarkett
제7장 시장 기회와 향후 전망
KSM 26.10.30According to Mordor Intelligence, the fiberglass flooring market size is projected to be USD 0.94 billion in 2025, USD 0.99 billion in 2026, and reach USD 1.28 billion by 2031, growing at a CAGR of 5.34% from 2026 to 2031.
Global Fiberglass Flooring Market Trends and Insights
Demand for Waterproof and Dimensionally Stable Flooring
The fiberglass flooring market is driven by commercial demand for flooring that remains stable under normal temperature fluctuations. Fiberglass reinforcement minimizes curling, edge lift, and visible subfloor irregularities, which can lead to early replacement in occupied facilities. Healthcare, foodservice, and education buyers increasingly require warranties that ensure dimensional stability under commercial heating, ventilation, and air conditioning (HVAC) conditions. Advancements in digital printing have reduced visual differences between resilient flooring and ceramic tile in commercial interiors. Consequently, procurement decisions increasingly prioritize dimensional performance and maintenance requirements over appearance alone. Interface introduced its polyvinyl chloride (PVC)-free Noravant resilient platform in February 2026, with a stated service life of up to 35 years. This development reflects demand for low-volatile organic compound (VOC), dimensionally stable, resilient flooring in commercial settings.
Expansion of Commercial Renovation and Institutional Construction
The fiberglass flooring market faces a first-cost barrier in price-sensitive procurement environments. Fiberglass-backed luxury vinyl tile (LVT) and vinyl sheet products may carry a 20-40% premium over conventional ceramic tile and ungauged vinyl. Buyers in emerging Asia-Pacific, the Middle East, Africa, and South America may prioritize annual capital budgets over multiyear maintenance savings. This dynamic creates distinct purchasing patterns between developed commercial projects and lower-cost projects in emerging markets. Renovation programs that resumed following delayed capital expenditure between 2020 and 2022 support the fiberglass flooring market. Healthcare systems, public schools, and government facilities continue to address accumulated flooring replacement requirements. India recorded 5.0% growth in its Index of Industrial Production in January 2025, indicating manufacturing activity that supports downstream demand for commercial and industrial flooring.
Volatility in Glass Fiber, PVC, Resin, and Plasticizer Costs
The fiberglass flooring market remains exposed to fluctuations in the prices of glass fiber, PVC resin, plasticizers, and energy. PVC resin represents 45-50% of the total input cost for fiberglass-backed vinyl flooring, directly linking petrochemical price movements to finished-product margins. In 2025, European producers faced higher energy costs, lower demand, competitive imports, and limited operating rates, affecting regional supply conditions. In September 2025, Chinese glass fiber manufacturers increased direct yarn prices by 5-10% in response to tariff-related pressures. In addition, Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH) regulations prompted European producers to shift toward phthalate-free plasticizers, which cost 15-30% more than conventional alternatives. Integrated supply chains and long-term material procurement agreements can reduce exposure to input-cost fluctuations compared with spot purchasing.
Other drivers and restraints analyzed in the detailed report include:
- Low-Maintenance and Anti-Allergen Flooring Preference
- Growth of Fiberglass-Backed Luxury Vinyl Flooring
- Higher Initial Cost Compared with Conventional Vinyl and Ceramic Flooring
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Luxury vinyl tile (LVT) accounted for 46.32% of revenue in 2025. Its position reflects its use across healthcare, retail, and corporate interiors, where dimensional stability, design options, and lower maintenance requirements support a premium in value. Vinyl composite tile (VCT) is forecast to grow at a CAGR of 6.07% from 2026 to 2031, the fastest rate among product types. VCT remains used in public schools, government offices, and municipal healthcare facilities, where initial capital budgets drive material selection. Its faster growth does not reverse the shift toward LVT specifications in higher-value projects. Instead, it reflects VCT's role in budget-conscious institutions and its adoption in emerging markets where LVT exceeds purchasing thresholds.
Vinyl sheets remain relevant for seamless installations in hospital corridors, airport concourses, food-processing facilities, and clean rooms. These environments require joint-free surfaces for hygiene and safety reasons that tile formats cannot fully replicate. Material development continues to address end-of-life constraints associated with multilayer fiberglass flooring. A 2025 patent application described a multilayer PVC covering with woven fiberglass reinforcement designed to enable full recyclability of PVC. The fiberglass flooring market could gain a tender advantage if recyclable fiberglass-backed vinyl becomes commercially available in European public procurement before 2028. This development would address a concern that limits certain environmental procurement decisions in the fiberglass flooring market, particularly where circularity documentation is required alongside performance specifications. Rigid-core stone-plastic composite (SPC) products create some substitution pressure within the LVT category, but their added thickness can complicate renovations on existing floors. This limitation preserves a role for flexible glass-mat-backed LVT in commercial retrofit projects.
Complete Report Scope:
- By Product Type
- Luxury Vinyl Tiles
- Vinyl Composite Tiles
- Vinyl Sheets
- By Application
- Residential
- Commercial
- Industrial
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 44.83% of the fiberglass flooring market in 2025 and is projected to grow at a CAGR of 6.19% through 2031. China remains the region's largest contributor, as commercial fit-out activity and infrastructure investment continue to support flooring specifications. India's Pradhan Mantri Awas Yojana Urban 2.0 received an allocation of INR 2.2 lakh crore (USD 26.3 billion) for 2024-25, supporting a pipeline of affordable housing, schools, and community healthcare facilities. India also recorded 5.0% growth in industrial production in January 2025, supporting demand for commercial and industrial flooring. Japan's indoor air quality requirements support demand for certified low-emission flooring, while manufacturers such as LX Hausys and NOX Corporation supply domestic and ASEAN commercial projects.
North America and Europe represent the largest revenue-generating regions outside Asia-Pacific, although their demand drivers differ. In North America, demand is primarily driven by the replacement of Vinyl Composition Tile (VCT) installed in schools, government buildings, and community health centers during the 1990s and early 2000s. Replacement projects increasingly use fiberglass-backed Luxury Vinyl Tile (LVT), supporting higher average selling prices across the installed commercial base. Europe experienced slower construction and renovation demand in 2025. Forbo Flooring Systems generated CHF 738.2 million (USD 824 million) in sales in 2025. Nordic countries and Germany continue to demonstrate demand for documented low-emission flooring and Environmental Product Declarations, while REACH requirements increase compliance costs for conventional plasticizer formulations.
South America, the Middle East, and Africa remain early-stage regions for specification-grade fiberglass flooring. Brazil accounts for the largest share of South American commercial construction and hospitality renovations, while economic volatility in Argentina slows the pace of upgrades. However, retail and healthcare facilities in Argentina continue to use resilient flooring specifications. Saudi Arabia's Vision 2030-related construction programs support demand for hospitality, healthcare, and airport terminal fit-outs. South Africa also contributes demand through hospitality and private healthcare renovation projects. The fiberglass flooring market can serve these regions through expanded distribution agreements, as demand levels may not justify investments in new local manufacturing facilities. This approach enables established suppliers to meet regional project demand through existing channels without committing to a manufacturing footprint before demand reaches sufficient scale.
- AWI Licensing, LLC
- Beaulieu International Group
- Congoleum
- Forbo Flooring Systems
- Gerflor
- Interface, Inc.
- IVC Group
- Karndean Designflooring
- LG Hausys
- Lico AG
- Mannington Commercial
- Milliken
- MOHAWK INDUSTRIES, INC.
- Novalis
- NOX Corporation
- Shaw Industries Group, Inc.
- Tarkett
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for Waterproof and Dimensionally Stable Flooring
- 4.2.2 Expansion of Commercial Renovation and Institutional Construction
- 4.2.3 Low-Maintenance and Anti-Allergen Flooring Preference
- 4.2.4 Growth of Fiberglass-Backed Luxury Vinyl Flooring
- 4.2.5 Retrofitting of Healthcare, Hospitality, and Retail Facilities
- 4.3 Market Restraints
- 4.3.1 Volatility in Glass Fiber, PVC, Resin, and Plasticizer Costs
- 4.3.2 Higher Initial Cost Compared With Conventional Vinyl and Ceramic Flooring
- 4.3.3 Limited End-of-Life Recycling Infrastructure for Multilayer Flooring
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Luxury Vinyl Tiles
- 5.1.2 Vinyl Composite Tiles
- 5.1.3 Vinyl Sheets
- 5.2 By Application
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Industrial
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 AWI Licensing, LLC
- 6.4.2 Beaulieu International Group
- 6.4.3 Congoleum
- 6.4.4 Forbo Flooring Systems
- 6.4.5 Gerflor
- 6.4.6 Interface, Inc.
- 6.4.7 IVC Group
- 6.4.8 Karndean Designflooring
- 6.4.9 LG Hausys
- 6.4.10 Lico AG
- 6.4.11 Mannington Commercial
- 6.4.12 Milliken
- 6.4.13 MOHAWK INDUSTRIES, INC.
- 6.4.14 Novalis
- 6.4.15 NOX Corporation
- 6.4.16 Shaw Industries Group, Inc.
- 6.4.17 Tarkett
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


