

|
시장보고서
상품코드
2156939
전기 절연 테이프 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Electrical Insulation Tape - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
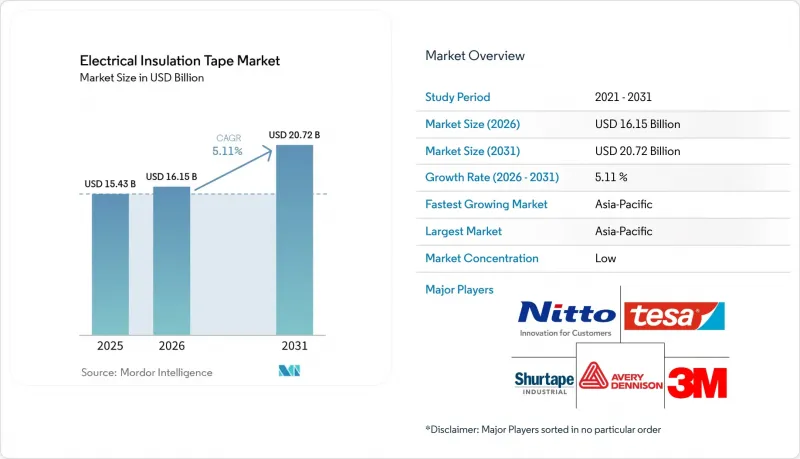
에 따르면 전기 절연 테이프 시장 규모는 2025년에 154억 3,000만 달러로 평가되어 예측 기간(2026-2031년)에 CAGR 5.11%로 확대하며, 2026년 161억 5,000만 달러에서 2031년에는 207억 2,000만 달러에 달할 것으로 추정되고 있습니다.
전 세계 전기 절연 테이프 시장의 동향 및 인사이트
전력망 현대화 및 재생에너지 인프라 확대
전력망 구축은 전기 절연 테이프 시장에 지속적인 수요원을 제공하고 있습니다. 이는 업그레이드, 수리, 송전망 확장 및 재생 가능 에너지 연결시 절연이 필요하기 때문입니다. 운전상의 부하와 환경적 스트레스에 노출되는 케이블, 접합부, 종단부, 패널 및 장비 주변에는 다양한 등급의 테이프가 사용되고 있습니다. 전 세계 전력망에 대한 투자액은 2020년 3,000억 달러에서 2025년에는 4,800억 달러로 증가했습니다. 국제에너지기구(IEA)는 2030년까지의 전력 수요를 충족시키기 위해서는 연간 송전망 투자액을 4,000억 달러라는 기준치에서 50% 증가시켜야 한다고 밝혔습니다. 미국 에너지부는 2026년 3월, 도체 교체 및 송전망 업그레이드에 19억 달러를 지원하기로 결정했습니다. 한편, 아메리칸 일렉트릭 파워(American Electric Power)사의 2026-2030년의 계획에 따르면 780억 달러 규모의 자본 계획 중 330억 달러가 송전망에 배정되어 있습니다. 송전망 건설 및 재생 가능 에너지 통합에는 많은 배전 프로젝트보다 더 엄격한 요건을 충족하는 테이프 시스템이 필요하며, 이로 인해 더 우수한 절연성, 난연성 및 기계적 특성을 갖춘 등급에 대한 수요가 지원되고 있습니다. 또한 공공 사업 프로젝트에서는 초기 설치 자재와 유지보수 자재가 모두 필요하므로 시장 기회가 확대되고 있습니다.
차량의 전기화와 고전압 하네스의 확대
차량의 전기화로 인해 차량 1대당 절연 테이프 사용량이 증가하고 있으며, 전기 절연 테이프 시장의 공급업체가 직면한 요구 사항도 변화하고 있습니다. 배터리 팩, 고전압 케이블 배선, 와이어 하네스 및 전자제어 시스템은 각각 신뢰성 높은 전기적 절연과 물리적 보호가 필요합니다. 배터리식 전기자동차에는 180-250미터의 절연 테이프가 사용되지만, 기존의 내연기관 차량에서는 80-120미터에 그칩니다. 새로운 800V 플랫폼에서는 많은 400V 시스템보다 더 높은 절연 내력과 열 안정성이 요구됩니다. 배터리식 전기자동차의 고전압 배선 길이는 1-2km로 추정되지만, 내연기관 차량에서는 200-300m입니다. 국제표준화기구(ISO) 19642 및 LV 215 규격은 신에너지 차량에 인증된 와이어 하네스 소재의 필요성을 강조하고 있습니다. 이러한 규격은 OEM의 승인 요건을 충족하고 차량의 수명 주기 전반에 걸쳐 성능을 유지할 수 있는 제품을 권장하고 있습니다.
PVC, 고무, 폴리에스터 필름 및 접착제의 원자재 가격 변동
수지, 고무, 필름, 접착제의 비용은 테이프의 이익률에 직접적인 영향을 미치므로, 원자재 비용의 변동은 전기 절연 테이프 시장에 여전히 시급한 우려 사항으로 남아 있습니다. 자동차, 공공사업, 전자, 건설 각 업계의 구매자들은 가격의 신속한 조정이 제한되는 상황에서 사업을 운영하고 있을 가능성이 있습니다. 2026년 6월, 미국의 PVC 수지 가격은 1미터톤당 644달러에 달한 반면, 아시아의 에틸렌계 PVC 가격은 2026년 초 2개월 동안 1미터톤당 최대 300달러의 변동을 보였습니다. 신에츠 화학공업은 2026년 5월, 염소-알칼리 생산 능력 부족과 해상 운임 급등을 이유로 PVC 수지의 공장 출하 가격을 1kg당 30엔 이상 인상한다고 발표했습니다. 공급 제한이 포함된 계약을 체결한 하류 제조업체는 고정 가격의 OEM 계약 하에서는 투입 비용 상승분을 완전히 전가하지 못할 가능성이 있습니다. 대규모 일체형 생산 제조업체는 헤지 거래를 하거나, 여러 공급처로부터 조달하거나, 재고를 많이 보유하는 것이 가능하며, 이를 통해 가격 변동이 심한 시기에 비용 면에서의 우위를 더욱 확대할 수 있습니다.
부문 분석
2025년, PVC 테이프는 전기 절연 테이프 시장 점유율의 60.45%를 차지했습니다. 이는 주택용 배선, 저전압 산업 작업, 현장 수리, 건물 유지보수, 그리고 구하기 쉽고 비용 대비 효율이 높은 테이프 제품에 의존하는 일상적인 전기 작업에서 PVC 테이프가 확고한 입지를 구축하고 있음을 반영합니다. UL 510 또는 CSA-C22.2 요건을 충족하는 난연성 PVC 테이프가 지정되는 상황에서는 여전히 비용 대비 성능의 균형이 중요하게 여겨지고 있습니다. 또한 PVC는 특히 많은 시장의 건축용 전선 용도에서 수년 동안 판매 대리점을 통해 안정적으로 공급되어 온 이점도 있습니다. 이러한 높은 시장 점유율은 다른 소재의 개발이 뒤처졌기 때문이 아니라, 확립된 유통망과 익숙한 사양에 기인합니다. 건설 활동과 정기적인 송전망 유지보수는 계속해서 이 부문의 기초적인 수요를 지원하고 있습니다. 구매자들이 더 높은 내열 성능과 낮은 할로겐 함유량의 제품을 요구하는 가운데, PVC 공급업체는 배합 변경 요건에 대응해야 합니다. PVC 전기 절연 테이프 시장의 규모는 광범위한 교체 수요와 대규모 도입 실적을 바탕으로 하고 있으며, 고객이 까다로운 용도를 위해 보다 전문적인 소재를 채택하게 되더라도 여전히 중요한 부문으로 남아 있습니다. PVC 수지가 주요 원료이기 때문에 이 부문은 계속해서 원자재 비용의 영향을 받기 쉬운 상황에 놓여 있습니다.
고무 테이프 시장은 2031년까지 연평균 성장률(CAGR) 5.75%로 성장할 것으로 예상되며, 이는 완전 전기 절연 테이프 시장의 성장률을 상회하는 수치입니다. 이는 자가융합성 소재가 요철이 있는 표면, 케이블 접합부 및 가혹한 조건 하의 종단부를 확실하게 덮어야 하는 고전압 용도에 대응하기 때문입니다. 자가 융합형 고무 제품은 15kV를 초과하는 케이블의 접속부 및 종단부에서 기포가 없는 절연층을 형성할 수 있으며, 표준 PVC 테이프로는 효과적으로 대처할 수 없는 조건을 충족시킵니다. 송전망 사업자들은 1차 절연과 기계적 보호를 결합한 테이프 시스템의 채택을 점점 더 지정하고 있으며, 이것이 고무 테이프의 보급을 지원하고 있습니다. UL 510 및 국제전기기술위원회(IEC) 60454-3-1의 요구 사항은 고전압 송전 및 배전 작업에서의 사용을 더욱 촉진하고 있습니다. 폴리에스테르 테이프는 모터 권선, 변압기 절연, PCB 마스킹에 사용되며, 치수 안정성과 내화학성으로 인해 프리미엄 위치를 확립하고 있습니다. 유리섬유, 폴리이미드, 특수 라미네이트 등을 포함하는 ‘기타’ 범주의 제품은 테이프가 인증된 공정 재료로 사용되는 항공우주 및 반도체 용도에 공급되고 있습니다. 3M은 UL 510A, UL 840 및 IEC 60112 인증을 받은 폴리에스테르 및 유리섬유 테이프 제품 라인에 투자해 왔습니다. 이러한 제품 간의 차이로 인해 더 높은 사양 요건을 충족하는 소재로 가치가 이동하고 있습니다.
지역별 분석
아시아태평양은 2025년 전기 절연 테이프 시장 점유율의 57.84%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 5.83%로 확대될 것으로 예측됩니다. 전자제품 생산, 가전제품 제조, 자동차 공급망, 송전망 건설 및 전기 제품 유통이 맞물려 이러한 성장을 지원하고 있습니다. 이 지역에는 전자기기 조립, 자동차용 와이어 하네스 생산, 가전제품 제조가 집중되어 있으며, 지역내 수요와 짧은 공급망을 지탱하고 있습니다. 중국은 전자기기 제조 거점과 송전망 투자 프로그램을 통해 이 지역의 생산과 소비를 주도하고 있습니다. 인도의 전기 절연 테이프 수요는 인프라 개발, 스마트 시티 구상, 국내 전기자동차(EV) 생산, 그리고 인도 표준국(BIS)의 인증 요건 강화에 힘입어 지원되고 있습니다. 주택·도시개발부에 따르면 8,067건의 스마트 시티 프로젝트 중 94%가 2025년 6월까지 완료되었다고 합니다. 일본과 한국은 자동차 및 전자기기 공급망을 통해 더 높은 사양의 제품에 대한 수요를 끌어올리고 있습니다.
북미의 전기 절연 테이프 시장 수요는 송전망 노후화, 데이터센터의 전력 수요, 그리고 전기자동차(EV) 인프라에 대한 투자에 의해 견인되고 있으며, 송전 프로젝트, 배전망 업그레이드, 자동차 생산, 그리고 규제 대상 전기 공사가 해당 지역의 용도 구성을 형성하고 있습니다. 캘리포니아 독립계통운영기구(CAISO)는 2026년 5월, 38개 프로젝트에 총 67억 달러를 투자하는 2025-2026년까지의 송전 계획을 승인했습니다. 퍼스트 에너지(First Energy)가 진행하는 9억 5,000만 달러 규모의 오하이오주-펜실베이니아주 간 송전망 개보수 사업과 아메리칸 일렉트릭 파워(American Electric Power)의 자본 계획도 송전 프로젝트 파이프라인에 포함되었습니다. 멕시코는 북미 자동차 공급망 및 전기자동차용 와이어 하네스 생산에서 담당하는 역할을 통해 수요를 지원하고 있습니다. 미국 및 캐나다의 규제 환경은 기존 공급업체에 유리하게 작용하고 있습니다. 이는 프로젝트에서 언더라이터스 래버러토리즈(UL) 인증 제품이나 해당 캐나다 표준 협회(CSA) 규격 준수가 요구되는 경우가 많기 때문입니다. 또한 인건비 급등으로 인해 특정 고신뢰성 용도를 위한 사전 절연 커넥터에 대한 관심도 높아지고 있습니다. 이러한 요인들로 인해 인증 제품에 대한 수요가 발생하는 한편, 표준 테이프 형식에 대한 대체 압력이 강해지고 있습니다.
유럽에서는 자동차의 전기화와 재생 가능 에너지의 통합이 진행되고 있으며, 전기 절연 테이프 시장에서 독특한 수요 동향이 나타나고 있습니다. 규정 준수 요건과 산업 공급망이 송전 설비, 차량 시스템, 전자 기기 및 건축 관련 전기 용도에 선정되는 재료를 결정짓고 있습니다. 유럽연합 집행위원회의 ‘그리드 액션 플랜(Grid Action Plan)’은 유럽 주요 국가들의 송전망 업그레이드를 위한 인허가 및 자금 조달을 지원하고 있습니다. REACH 및 IEC 60454-3-1 요건에 따라 대체품이 이용 가능한 경우 할로겐 함유 PVC에서 다른 소재로의 전환이 촉진되고 있습니다. 남미, 중동 및 아프리카는 광범위한 사양 업그레이드보다 송전망 확장 및 도시화가 더 중요시되는 수요 형성의 초기 단계에 있는 지역입니다. 브라질이 남미의 활동을 주도하는 한편, 사우디아라비아와 남아프리카공화국은 인프라 및 에너지 공급 능력 개발을 통해 프로젝트 주도형 수요를 창출하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 최종사용자 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- 3M
- ACHEM
- Advance Tapes International.
- Avery Dennison Corporation
- Coroplast Fritz Muller GmbH & Co. KG
- Denka Company Limited
- HellermannTyton
- IPG
- Nitto Denko Corporation
- Pidilite Industries Ltd.
- Saint-Gobain
- Scapa
- Shurtape Technologies, LLC
- Teraoka Seisakusho co.,Ltd.
- tesa SE
제7장 시장 기회와 향후 전망
KSA 26.10.29According to Mordor Intelligence, the electrical insulation tape market size was valued at USD 15.43 billion in 2025 and is estimated to grow from USD 16.15 billion in 2026 to USD 20.72 billion by 2031, at a CAGR of 5.11% during the forecast period (2026-2031).
Global Electrical Insulation Tape Market Trends and Insights
Expansion of Power-Grid Modernization and Renewable-Energy Infrastructure
Power grid work provides a durable source of demand for the electrical insulation tape market, as insulation is required during upgrades, repairs, transmission expansion, and renewable energy connections. Different tape grades are used around cables, splices, terminations, panels, and equipment that are exposed to operating and environmental stresses. Global grid spending rose from USD 300 billion in 2020 to USD 480 billion in 2025. The International Energy Agency stated that annual grid investment needs to increase 50% from the USD 400 billion baseline to meet electricity demand through 2030. The US Department of Energy committed USD 1.9 billion in March 2026 for reconductoring and transmission upgrades, while American Electric Power's 2026 to 2030 plan allocated USD 33 billion to transmission within its USD 78 billion capital plan. Transmission construction and renewable integration require more demanding tape systems than many distribution projects, supporting demand for grades with stronger dielectric, flame-retardant, and mechanical properties. Utility projects also require both initial installation materials and maintenance supplies, broadening the market opportunity.
Electrification of Vehicles and Growth of High-Voltage Harnesses
Vehicle electrification is increasing tape use per vehicle and changing the requirements faced by suppliers in the electrical insulation tape market. Battery packs, high-voltage cable runs, wire harnesses, and electronic control systems each require reliable electrical separation and physical protection. A battery-electric vehicle uses 180 to 250 meters of insulating tape, compared with 80 to 120 meters in a conventional internal-combustion vehicle. New 800V platforms require greater dielectric strength and thermal stability than many 400V systems. High-voltage cabling in a battery-electric vehicle is estimated at 1 to 2 km, compared with 200 to 300 m in an internal-combustion vehicle. International Organization for Standardization (ISO) 19642 and LV 215 frameworks reinforce the need for qualified wiring-harness materials in new-energy vehicles. These specifications favor products that meet OEM approval requirements and sustain performance across the vehicle life cycle.
Volatility in PVC, Rubber, Polyester Film, and Adhesive Inputs
Input cost movements remain an immediate concern for the electrical insulation tape market, as resin, rubber, film, and adhesive costs directly affect tape margins. Buyers in automotive, utilities, electronics, and construction may operate under conditions that limit rapid price adjustments. PVC resin prices in the United States reached USD 644 per metric ton in June 2026, while ethylene-based PVC prices in Asia moved by as much as USD 300 per metric ton over a two-month period earlier in 2026. Shin-Etsu Chemical announced an ex-factory price increase for PVC resin of more than JPY 30 per kg in May 2026, citing tighter chlor-alkali capacity and higher maritime freight rates. Downstream manufacturers with limited-supply contracts may not be able to fully pass through higher input costs under fixed-price OEM agreements. Larger integrated suppliers can hedge, source from multiple suppliers, and hold more inventory, which can widen their cost advantage during periods of price volatility.
Other drivers and restraints analyzed in the detailed report include:
- Rising Complexity of Electronics and Connected Devices
- Demand for Certified Flame-Retardant and High-Temperature Tapes
- Substitution by Heat-Shrink Tubing, Connectors, and Molded Insulation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PVC tapes accounted for 60.45% of the electrical insulation tape market share in 2025, reflecting their established position in residential wiring, low-voltage industrial work, field repair, building maintenance, and everyday electrical tasks that rely on accessible, cost-effective tape products. Their cost-performance balance remains relevant where flame-retardant PVC tape meeting UL 510 or CSA-C22.2 requirements is specified. PVC also benefits from long-standing availability from distributors, particularly in building wire applications across many markets. Its large share reflects established distribution and familiar specifications rather than an absence of development in other materials. Construction activity and routine grid maintenance continue to support the segment's underlying demand. PVC suppliers must respond to reformulation requirements as buyers seek products with higher temperature performance and lower halogen content. The electrical insulation tape market size for PVC is supported by widespread replacement demand and a broad installed base, making it an important segment even as customers adopt more specialized materials for demanding applications. The segment remains exposed to raw material costs, as PVC resin is a major input.
Rubber tapes are forecast to grow at a 5.75% CAGR through 2031, outpacing the overall electrical insulation tape market growth rate, as self-amalgamating materials address high-voltage applications requiring reliable coverage of uneven surfaces, cable joints, and demanding terminations. Self-amalgamating rubber products can form void-free insulation at cable splices and terminations above 15 kV, addressing conditions that standard PVC tapes cannot effectively address. Grid operators increasingly specify tape systems that combine primary insulation and mechanical protection, which supports rubber tape adoption. UL 510 and International Electrotechnical Commission (IEC) 60454-3-1 requirements further support use in high-voltage transmission and distribution work. Polyester tape is used for motor winding, transformer insulation, and PCB masking, where its dimensional stability and chemical resistance support a premium position. Products in the other category, including glass cloth, polyimide, and specialty laminates, serve aerospace and semiconductor applications where tape is a certified process material. 3M has invested in polyester and glass-cloth tape lines with recognition under UL 510A, UL 840, and IEC 60112. These product differences shift value toward materials that meet higher specification requirements.
Complete Report Scope:
- By Product Type
- PVC Tapes
- Rubber Tapes
- Polyester Tapes
- Other Product Types
- By End-User Industry
- Electrical and Electronics
- Automotive
- Aerospace
- Construction
- Telecommunications
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 57.84% of the electrical insulation tape market share in 2025 and is projected to expand at a 5.83% CAGR through 2031. The combined scale of electronics production, appliance manufacturing, automotive supply chains, grid construction, and electrical-product distribution supports this growth. Electronics assembly, automotive wire-harness production, and appliance manufacturing are concentrated in the region, supporting localized demand and short supply chains. China leads the region in production and consumption due to its electronics manufacturing base and grid investment program. India's demand for electrical insulation tape is supported by infrastructure development, Smart Cities initiatives, domestic electric vehicle (EV) production, and tighter Bureau of Indian Standards (BIS) certification requirements. The Ministry of Housing and Urban Affairs stated that 94% of 8,067 Smart Cities projects had been completed by June 2025. Japan and South Korea add demand for higher-specification products through automotive and electronics supply chains.
North American demand in the electrical insulation tape market is driven by an aging grid, data-center electricity demand, and EV infrastructure investment, with transmission projects, power-distribution upgrades, automotive production, and regulated electrical work shaping the region's application mix. The California Independent System Operator (CAISO) approved a 2025 to 2026 transmission plan covering USD 6.7 billion across 38 projects in May 2026. FirstEnergy's USD 950 million Ohio-Pennsylvania upgrade and American Electric Power's capital plan add to the transmission project pipeline. Mexico supports demand through its role in North American automotive supply chains and EV wire-harness production. The regulatory environment in the United States and Canada favors established suppliers, as projects often require Underwriters Laboratories (UL)-listed products and applicable Canadian Standards Association (CSA) compliance. High labor costs also increase interest in pre-insulated connectors for selected high-reliability applications. These factors create demand for certified products while increasing substitution pressure on standard tape formats.
Europe combines automotive electrification with renewable-energy integration, creating a distinct demand profile for the electrical insulation tape market. Compliance requirements and industrial supply chains shape the materials selected for transmission equipment, vehicle systems, electronics, and building-related electrical applications. The European Commission's Grid Action Plan supports permitting and financing for transmission upgrades across major European countries. REACH and IEC 60454-3-1 requirements are encouraging reformulation away from halogen-containing PVC where alternatives are available. South America, the Middle East, and Africa are earlier-stage demand regions where grid expansion and urbanization are more important than broad specification upgrades. Brazil anchors South American activity, while Saudi Arabia and South Africa contribute project-led demand through infrastructure and energy-capacity development.
- 3M
- ACHEM
- Advance Tapes International.
- Avery Dennison Corporation
- Coroplast Fritz Muller GmbH & Co. KG
- Denka Company Limited
- HellermannTyton
- IPG
- Nitto Denko Corporation
- Pidilite Industries Ltd.
- Saint-Gobain
- Scapa
- Shurtape Technologies, LLC
- Teraoka Seisakusho co.,Ltd.
- tesa SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Power-Grid Modernization and Renewable-Energy Infrastructure
- 4.2.2 Electrification of Vehicles and Growth of High-Voltage Harnesses
- 4.2.3 Rising Complexity of Electronics and Connected Devices
- 4.2.4 Demand for Certified Flame-Retardant and High-Temperature Tapes
- 4.2.5 Qualification of Tape Performance Through Electrochemical-Migration Testing
- 4.3 Market Restraints
- 4.3.1 Volatility in PVC, Rubber, Polyester Film and Adhesive Inputs
- 4.3.2 Substitution by Heat-Shrink Tubing, Connectors and Molded Insulation
- 4.3.3 Failure Risk from Incorrect Installation, Surface Contamination and Incompatible Adhesives
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size And Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 PVC Tapes
- 5.1.2 Rubber Tapes
- 5.1.3 Polyester Tapes
- 5.1.4 Other Product Types
- 5.2 By End-User Industry
- 5.2.1 Electrical and Electronics
- 5.2.2 Automotive
- 5.2.3 Aerospace
- 5.2.4 Construction
- 5.2.5 Telecommunications
- 5.2.6 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 ACHEM
- 6.4.3 Advance Tapes International.
- 6.4.4 Avery Dennison Corporation
- 6.4.5 Coroplast Fritz Muller GmbH & Co. KG
- 6.4.6 Denka Company Limited
- 6.4.7 HellermannTyton
- 6.4.8 IPG
- 6.4.9 Nitto Denko Corporation
- 6.4.10 Pidilite Industries Ltd.
- 6.4.11 Saint-Gobain
- 6.4.12 Scapa
- 6.4.13 Shurtape Technologies, LLC
- 6.4.14 Teraoka Seisakusho co.,Ltd.
- 6.4.15 tesa SE
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


