

|
시장보고서
상품코드
2157120
미국의 금속 성형 장비 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Metal Forming Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
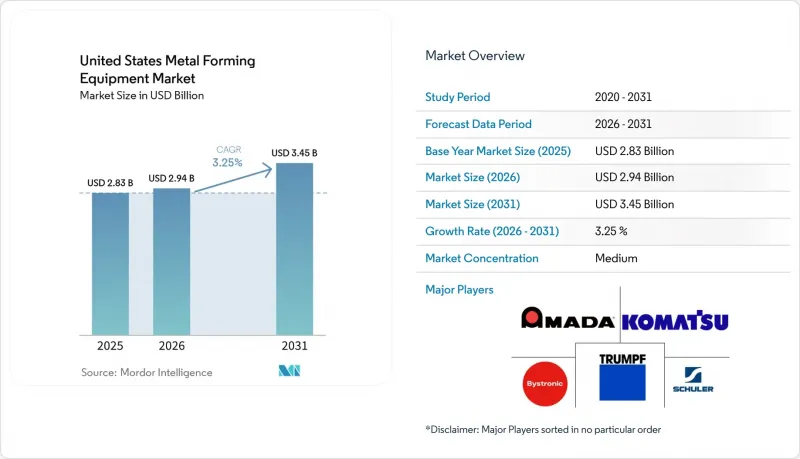
에 따르면 미국의 금속 성형 장비 시장 규모는 2025년에 28억 3,000만 달러, 2026년에 29억 4,000만 달러에 달하며, 2031년까지 34억 5,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 3.25%로 성장할 것으로 전망되고 있습니다.
미국 금속 성형 장비 시장의 동향 및 분석
리쇼어링과 연방 정부의 제조업 투자
‘Build America, Buy America(미국에서 건설, 미국 제품 구매)’ 규정에 따라 연방 정부의 지원을 받는 인프라 프로젝트에 사용되는 모든 철강 제조 공정은 미국 내에서 이루어져야 하며, 연방 정부 자금을 통한 건설 수요는 인증을 받은 국내 제조 시설과 연계되어 있습니다. 이 요건은 규정을 준수하는 부품을 제조하는 가공업체가 사용하는 프레스기, 롤 포머, 굽힘 가공기 및 관련 시스템의 구매를 촉진하고 있습니다. ‘리쇼어링 구상’ 보고서에 따르면 2025년 금속 가공품의 리쇼어링은 19% 증가하여 더 많은 생산 활동이 미국의 제조 거점으로 돌아오고 있는 것으로 나타났습니다. 또한 관세를 이유로 한 리쇼어링 근거가 전년 대비 12배 증가한 것으로 기록되어, 입지 결정에 있으며, 무역 정세가 차지하는 비중이 커지고 있음을 보여줍니다. 이러한 상황은 생산 거점의 단기적인 변경이 아닌, 프레스 라인, 단조 프레스, 롤 성형 시스템에 대한 지속적인 투자를 촉진하고 있습니다. 140개 프로젝트에 걸쳐 6,300억 달러를 초과한다고 발표된 반도체 투자는 시설 건물, 데이터센터, 변전소에서 사용되는 구조용 강재 및 알루미늄의 가공 수요를 증가시키고 있습니다.
전기자동차(EV), 배터리 및 경량 부품 제조
전기자동차(EV)에는 배터리 통합, 구조적 지지, 그리고 관련 파워트레인의 변경을 위해 전용으로 설계된 프레스 성형 부품이 필요하며, 공급업체가 성형해야 하는 금속 부품의 범위가 확대되고 있습니다. 알루미늄으로 제작된 배터리 하우징으로 인해 생산 및 품질 요건을 충족하면서 경량 판재를 가공할 수 있는 설비에 대한 수요가 높아지고 있습니다. 노벨리스(Novelis)는 알루미늄 솔루션을 통해 동등한 강철 솔루션에 비해 배터리 하우징의 질량을 최대 50%까지 줄일 수 있다고 밝혔으며, 이로 인해 재료의 무게가 설비 선정에 있으며, 핵심적인 역할을 하게 되었습니다. 이러한 요건으로 인해 적절한 제어 시스템, 금형, 성형 능력을 갖춘 알루미늄용 서보 프레스, 하이드로포밍 장비 및 CNC 프레스 브레이크가 유리해집니다. 배터리 부품에 대한 국내 조달 요건으로 인해 이 업무의 더 큰 비중이 해외 조달이 아닌 미국내 공장으로 전환되고 있습니다. 또한 알루미늄 파생 제품에 대한 관세도 성형 알루미늄 부품 및 관련 구성품 시스템의 현지 조달에 있으며, 비용 면에서의 이점을 더욱 강화하고 있습니다.
높은 설비 투자 비용과 자금 조달의 어려움
새로운 성형 설비에는 막대한 자본이 필요합니다. 특히 자금 조달 신청을 지원하거나 예측 가능한 설비 가동률을 확보하기 위한 OEM(주문자 상표 제조업체)과의 장기 공급 계약을 맺지 않은 소규모 가공업체의 경우, 그 부담이 더욱 큽니다. 2026년에 나타날 발주 수량 감소와 발주 금액 증가라는 대조적인 추세는 자동화 수준과 첨단 제어 기능이 신규 설비 구입 비용을 어떻게 끌어올리는지를 보여줍니다. 중소기업청(SBA)의 504 프로그램은 프로그램 요건을 충족하는 설비 투자를 포함하여 적격 중소기업에 고정자산 대출을 제공하고 있습니다. 이 승인 절차는 납기 기한이 촉박한 계약 수주와 연계된 구매를 지연시킬 가능성이 있으며, 새로운 생산 기회에 신속하게 대응하려는 가공업체에게는 실무상 과제가 됩니다. 2023-2025년에 걸친 금리 상승기에는 설비 교체 결정이 지연되어, 미국의 금속 성형 설비 시장이 자금 조달 환경의 영향을 받기 쉬운 것으로 드러났습니다. 세무상 즉시 비용 계상을 통해 취득 비용을 경감하는 것은 가능하지만, 대규모 프레스 라인에 대한 투자의 경우 이러한 조치가 최대 효과를 발휘하는 범위를 초과할 가능성이 있습니다.
부문별 분석
2025년 현재, 프레스 기계는 미국 금속 성형 장비 시장 규모의 44%를 차지하고 있으며, 이는 대량 생산되는 자동차용 프레스 가공, 산업용 부품 제조 및 일반 금속 제품 제조 공정에서 사용되는 기계식 및 유압식 시스템에 의해 지원되고 있습니다. 서보 프레스는 가장 빠르게 성장하는 하위 부문으로, 2026-2031년까지 연평균 성장률(CAGR) 5.3%를 기록할 것으로 예상됩니다. 이는 프로그래밍 가능한 슬라이드 동작이 전기자동차 부품, 항공우주 부품 및 정밀 의료 성형 용도를 지원하고 있기 때문입니다. 2026년에 실시된 25,000 kN 대형 서보 프레스에 대한 연구에 따르면 동적 매개변수의 보정을 통해 피크 토크 오차가 72.7% 감소한 것으로 나타났습니다. 동 조사에서는 유효 모터 토크의 예측 오차도 7.6%에서 1.4%로 감소한 것으로 나타났으며, 이는 정밀도와 재현성이 요구되는 상황에서 서보 기술의 채택을 지원하는 결과입니다. 유압 프레스는 긴 스트로크 길이에 걸쳐 제어된 힘이 필요한 심압 성형, 고무 패드 성형, 하이드로포밍 분야에서 여전히 중요한 역할을 수행하고 있습니다.
기계식 프레스는 높은 생산 속도가 경제성의 핵심으로 남아 있으므로 범용 프레스 가공 분야에서 여전히 중요한 역할을 수행하고 있습니다. 프레스 브레이크와 굽힘 가공기는 두 번째로 큰 설비 범주이지만, 구매자들이 에너지 소비와 수명 주기 비용을 고려함에 따라 전동식 및 서보식 기종에 대한 관심이 높아지고 있습니다. 롤 성형 장비는 건설 및 인프라 공사에 활용되는 한편, 단조 장비는 특수 부품이 필요한 항공우주 및 방위 분야 용도를 지원하고 있습니다. 하이드로포밍 장비 및 압출 프레스는 자동차 구조 부품, 항공우주용 덕트, 알루미늄 배터리 케이스 프레임 등에서 요구되는 정밀한 사양을 충족시키고 있습니다. 슐러(Schuler Inc.)와 파인툴(Feintool)은 2026년 1월, 차세대 HFA 파인 블랭킹 프레스를 출시했습니다. 이 프레스는 서보 제어식 유압 펌프 구동 장치, 더 높은 스트로크 속도, 그리고 두 자릿수의 에너지 효율 향상을 실현했습니다.
2025년 기준, 스탬핑 및 펀칭은 미국 금속 성형 설비 시장 규모의 32.5%를 차지하고 있으며, 이는 자동차 차체 패널, 전기 기기 하우징, 가전 부품, 산업용 하드웨어 등 폭넓은 분야에서 활용되고 있음을 반영합니다. 순차 금형 및 트랜스퍼 프레스 라인은 재현성이 높은 부품을 대량으로 생산할 수 있으므로 이러한 용도에 적합합니다. 하이드로포밍은 가장 빠르게 성장하는 공정 분야로, 2026-2031년까지 연평균 성장률(CAGR) 4.9%로 확대될 것으로 예측됩니다. 전기자동차 플랫폼이나 항공우주용 덕트 시스템에는 기존의 금형 프레스로는 일관되게 제공할 수 없는 이음매 없는 관형 또는 판 성형 형상이 요구됩니다. 프레스 브레이크 및 롤 벤딩을 포함한 굽힘 가공도 해군 함정 및 우주 발사 구조물용 대형 프레스 기계에 대한 항공우주·방위 분야의 투자 혜택을 받고 있습니다.
신시내티 인코퍼레이티드(Cincinnati Incorporated)는 2026년 5월, 로켓 개발 프로그램을 위해 대형 프레스 브레이크를 납품했으며, 이는 대형 구조 부품의 정밀 가공에 대한 수요가 높음을 보여줍니다. 딥 드로잉 가공은 드로잉 깊이, 두께, 표면 마감이 중요한 가전 제품, 의료기기, 항공우주용 연료 시스템 분야에서 여전히 중요한 역할을 하고 있습니다. 단조 분야에서는 항공우주 및 미사일 프로그램에 사용되는 고신뢰성 티타늄 및 니켈 초합금 부품의 국방 조달로 인한 혜택을 받고 있습니다. 압연 및 롤 성형 공정에서는 고속도로, 교량, 건설 프로젝트를 위한 구조용 강재 및 알루미늄 형재가 공급되고 있습니다. 전자기 성형, 고무 패드 성형, 증분 시트 성형과 같은 기타 공정은 소량 생산되는 복잡한 항공우주 및 방위용 프로토타입에 활용되고 있는 반면, 디지털 트윈 시스템은 핫 스탬핑 인증에서 그 중요성이 커지고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- 지정학적 이벤트가 시장에 미치는 영향의 평가
제5장 시장 규모와 성장 예측
- 기기 유형별
- 성형 프로세스별
- 성형 재료별
- 최종 용도 산업별
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- TRUMPF Inc.
- AMADA AMERICA, INC.
- Bystronic Inc.
- Komatsu America Industries LLC
- Schuler Inc.
- Cincinnati Incorporated
- Prima Power North America Inc.
- Salvagnini America, Inc.
- LVD Company NV
- MC Machinery Systems, Inc.
- Mazak Optonics Corporation
- Mitsubishi Electric Automation, Inc.
- Beckwood Press Company
- Greenerd Press & Machine Company, Inc.
- AIDA Engineering, Ltd.
- Fagor Arrasate S. Coop.
- Wilson Tool International
- Piranha Fabrication Equipment
- Accurpress
- Ermak USA, Inc.
- Haco-Atlantic, Inc.
- Pacific Press Technologies
- Wysong and Miles Company
제7장 시장 기회와 향후 전망
KSA 26.10.30According to Mordor Intelligence, the United States metal forming equipment market size is projected to be USD 2.83 billion in 2025, USD 2.94 billion in 2026, and reach USD 3.45 billion by 2031, growing at a CAGR of 3.25% from 2026 to 2031.
United States Metal Forming Equipment Market Trends and Insights
Reshoring and Federal Manufacturing Investment
Build America, Buy America provisions require every iron and steel manufacturing process used for federally assisted infrastructure projects to occur within the United States, tying federally funded construction demand to qualified domestic fabrication facilities. This requirement supports purchases of presses, roll formers, bending machines, and related systems used by fabricators making compliant components. The Reshoring Initiative reported that fabricated metals reshoring grew 19% in 2025, indicating that more production activity was returning to United States manufacturing locations. It also recorded a 12-fold year-over-year rise in tariff-driven reshoring rationales, showing the growing role of trade conditions in location decisions. These conditions favor committed spending on stamping lines, forging presses, and roll-forming systems instead of short-term changes in where production is performed. Announced semiconductor investments exceeding USD 630 billion across 140 projects add fabrication work for structural steel and aluminum used in facility buildings, data centers, and power substations.
EV, Battery, and Lightweight-Component Manufacturing
Electric vehicles require purpose-designed stamped components for battery integration, structural support, and related powertrain changes, increasing the range of metal parts that suppliers must form. Aluminum battery enclosures increase demand for equipment that can process lightweight sheet materials while meeting production and quality requirements. Novelis states that aluminum solutions can reduce battery enclosure mass by up to 50% compared with equivalent steel solutions, which gives material weight a central role in equipment selection. This requirement favors aluminum-capable servo presses, hydroforming equipment, and CNC press brakes with suitable controls, tooling, and forming capability. Domestic-content requirements for battery components direct a greater share of this work toward United States plants rather than offshore supply arrangements. Tariffs on aluminum derivatives also reinforce the cost case for local sourcing of formed aluminum parts and related component systems.
High Capital Cost and Financing Sensitivity
New forming equipment requires substantial capital, particularly for smaller fabricators that lack long-term original equipment manufacturer supply agreements to support financing applications or secure predictable equipment use. The contrast between lower unit orders and higher order value in 2026 shows how automation content and advanced controls can raise the cost of a new equipment purchase. The Small Business Administration 504 program offers fixed-asset financing for eligible small businesses, including equipment investments that meet program requirements. Its approval process can slow purchases tied to time-sensitive contract awards, creating a practical challenge for fabricators seeking to respond quickly to new production opportunities. The 2023-2025 period of elevated interest rates delayed equipment replacement decisions and showed that the United States metal forming equipment market is sensitive to financing conditions. Tax expensing can ease acquisition costs, but larger press-line investments can exceed the range where those provisions provide the strongest support.
Other drivers and restraints analyzed in the detailed report include:
- Industry 4.0 Automation and Labor-Productivity Imperatives
- Aerospace, Defense, and Shipbuilding Capacity Expansion
- Skilled Technician and Controls-Engineer Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Press machines held 44% of the United States metal forming equipment market size in 2025, supported by mechanical and hydraulic systems used in high-volume automotive stamping, industrial component fabrication, and general metal-products operations. Servo presses are the fastest-growing subsegment, with a projected 5.3% CAGR from 2026 to 2031, because programmable slide motion supports electric vehicle components, aerospace parts, and precision medical forming applications. A 2026 study of a 25,000 kN heavy-duty servo press found that dynamics parameter calibration reduced peak torque error by 72.7%. The same study reduced effective motor torque prediction error from 7.6% to 1.4%, which supports the use of servo technology where precision and repeatable operation are required. Hydraulic presses remain important for deep drawing, rubber-pad forming, and hydroforming, where controlled force is needed over long stroke lengths.
Mechanical presses retain a role in commodity stamping because high production speed remains central to their economics. Press brakes and bending machines are the second-largest equipment category, while electric and servo variants gain interest as purchasers consider energy use and lifetime operating costs. Roll-forming equipment serves construction and infrastructure work, whereas forging equipment supports aerospace and defense applications requiring specialized parts. Hydroforming equipment and extrusion presses address adjacent precision requirements for automotive structures, aerospace ducts, and aluminum battery enclosure frames. Schuler Inc. and Feintool launched a new HFA fineblanking press generation during January 2026, with servo-controlled hydraulic pump drives, higher stroke rates, and double-digit energy-efficiency gains.
Stamping and punching held 32.5% of the United States metal forming equipment market size in 2025, reflecting their broad use across automotive body panels, electrical enclosures, appliance components, and industrial hardware. Progressive-die and transfer-press lines suit these applications because they can produce repeatable parts at high volumes. Hydroforming is the fastest-growing process segment, forecast to expand at a 4.9% CAGR from 2026 to 2031. Electric vehicle platforms and aerospace duct systems require seamless tubular or sheet-formed shapes that conventional die stamping cannot consistently provide. Bending, including press-brake and roll-bending work, also benefits from aerospace and defense investment in high-tonnage systems for naval vessels and space-launch structures.
Cincinnati Incorporated delivered large press brakes to rocket programs during May 2026, illustrating demand for precision fabrication of large structural components. Deep drawing remains important for consumer appliances, medical devices, and aerospace fuel systems, where draw depth, wall thickness, and surface finish matter. Forging benefits from the defense procurement of high-integrity titanium and nickel-superalloy parts used in aerospace and missile programs. Rolling and roll-forming processes provide structural steel and aluminum profiles for highway, bridge, and construction projects. Other processes, including electromagnetic forming, rubber-pad forming, and incremental sheet forming, have uses in low-volume, complex aerospace and defense prototypes, while digital-twin systems are becoming relevant in hot-stamping qualification.
Complete Report Scope:
- By Equipment Type
- Press Machines
- Mechanical Presses
- Hydraulic Presses
- Servo Presses
- Other General-Purpose Presses
- Press Brakes and Bending Machines
- Hydraulic Press Brakes
- Servo / Electric Press Brakes
- Mechanical Press Brakes
- Other Bending Machines
- Forging Equipment
- Forging Presses
- Forging Hammers
- Upsetting and Heading Machines
- Other Forging Equipment
- Roll Forming and Plate/Profile Rolling Equipment
- Roll Forming Machines
- Plate Rolling Machines
- Section and Profile Rolling Machines
- Other Secondary Rolling/Forming Equipment
- Wire, Tube and Profile Forming Equipment
- Wire and Bar Drawing/Forming Equipment
- Tube Forming and Bending Equipment
- Profile Forming Equipment
- Extrusion Presses
- Hydroforming Equipment
- Other Metal Forming Equipment
- Press Machines
- By Forming Process
- Stamping and Punching
- Deep Drawing
- Bending
- Forging
- Rolling and Roll Forming
- Extrusion
- Hydroforming
- Other Forming Processes
- By Material Formed
- Carbon and Low-Alloy Steel
- Stainless Steel
- Aluminum and Aluminum Alloys
- Copper and Copper Alloys
- Titanium, Nickel and Other Non-Ferrous Metals
- Other Materials
- By End-Use Industry
- Automotive and Transportation
- Aerospace and Defense
- Industrial Machinery and Capital Equipment
- Metal Products and Fabrication
- Electrical and Electronics
- Construction and Infrastructure
- Energy and Power
- Consumer Appliances and Durable Goods
- Medical and Precision Manufacturing
- Other End-Use Industries
List of Companies Covered in this Report:
- TRUMPF Inc.
- AMADA AMERICA, INC.
- Bystronic Inc.
- Komatsu America Industries LLC
- Schuler Inc.
- Cincinnati Incorporated
- Prima Power North America Inc.
- Salvagnini America, Inc.
- LVD Company NV
- MC Machinery Systems, Inc.
- Mazak Optonics Corporation
- Mitsubishi Electric Automation, Inc.
- Beckwood Press Company
- Greenerd Press & Machine Company, Inc.
- AIDA Engineering, Ltd.
- Fagor Arrasate S. Coop.
- Wilson Tool International
- Piranha Fabrication Equipment
- Accurpress
- Ermak USA, Inc.
- Haco-Atlantic, Inc.
- Pacific Press Technologies
- Wysong and Miles Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Reshoring and Federal Manufacturing Investment
- 4.2.2 EV, Battery and Lightweight-Component Manufacturing
- 4.2.3 Industry 4.0 Automation and Labor-Productivity Imperatives
- 4.2.4 Aerospace, Defense and Shipbuilding Capacity Expansion
- 4.2.5 Distributed Production Requiring Fast-Changeover Forming Cells
- 4.2.6 Digital Serviceability of Legacy Presses and Controls
- 4.3 Market Restraints
- 4.3.1 High Capital Cost and Financing Sensitivity
- 4.3.2 Skilled Technician and Controls-Engineer Shortages
- 4.3.3 Tariff Exposure and Imported Component Volatility
- 4.3.4 Integration Risk Across Mixed-Vintage Factory Systems
- 4.4 Value / Supply-Chain Analysis
- 4.4.1 Steel, Aluminum and Specialty-Alloy Inputs
- 4.4.2 Dies, Tooling, Controls, Servo Drives and Sensors
- 4.4.3 Machine Builders, Integrators, Distributors and Service Providers
- 4.4.4 Fabricators, Tier Suppliers and Large OEM Buyers
- 4.4.5 Aftermarket Parts, Retrofits, Training and Remote Diagnostics
- 4.5 Regulatory Landscape
- 4.5.1 Occupational Safety and Machine Guarding Requirements
- 4.5.2 Energy Efficiency, Emissions and Environmental Compliance
- 4.5.3 Buy America, Federal Procurement and Domestic-Content Rules
- 4.5.4 Trade Remedies, Tariffs and Customs Classification
- 4.6 Technological Outlook
- 4.6.1 Servo-Electric and Hybrid Press Architectures
- 4.6.2 Fiber Laser, CNC and Multi-Axis Forming Integration
- 4.6.3 Robotics, Vision Inspection and In-Die Sensing
- 4.6.4 Digital Twins, Predictive Maintenance and Remote Monitoring
- 4.6.5 Energy Monitoring and Regenerative Drives
- 4.7 Impact Assessment of Geopolitical Events on the Market
5 Market Size & Growth Forecasts
- 5.1 By Equipment Type
- 5.1.1 Press Machines
- 5.1.1.1 Mechanical Presses
- 5.1.1.2 Hydraulic Presses
- 5.1.1.3 Servo Presses
- 5.1.1.4 Other General-Purpose Presses
- 5.1.2 Press Brakes and Bending Machines
- 5.1.2.1 Hydraulic Press Brakes
- 5.1.2.2 Servo / Electric Press Brakes
- 5.1.2.3 Mechanical Press Brakes
- 5.1.2.4 Other Bending Machines
- 5.1.3 Forging Equipment
- 5.1.3.1 Forging Presses
- 5.1.3.2 Forging Hammers
- 5.1.3.3 Upsetting and Heading Machines
- 5.1.3.4 Other Forging Equipment
- 5.1.4 Roll Forming and Plate/Profile Rolling Equipment
- 5.1.4.1 Roll Forming Machines
- 5.1.4.2 Plate Rolling Machines
- 5.1.4.3 Section and Profile Rolling Machines
- 5.1.4.4 Other Secondary Rolling/Forming Equipment
- 5.1.5 Wire, Tube and Profile Forming Equipment
- 5.1.5.1 Wire and Bar Drawing/Forming Equipment
- 5.1.5.2 Tube Forming and Bending Equipment
- 5.1.5.3 Profile Forming Equipment
- 5.1.6 Extrusion Presses
- 5.1.7 Hydroforming Equipment
- 5.1.8 Other Metal Forming Equipment
- 5.1.1 Press Machines
- 5.2 By Forming Process
- 5.2.1 Stamping and Punching
- 5.2.2 Deep Drawing
- 5.2.3 Bending
- 5.2.4 Forging
- 5.2.5 Rolling and Roll Forming
- 5.2.6 Extrusion
- 5.2.7 Hydroforming
- 5.2.8 Other Forming Processes
- 5.3 By Material Formed
- 5.3.1 Carbon and Low-Alloy Steel
- 5.3.2 Stainless Steel
- 5.3.3 Aluminum and Aluminum Alloys
- 5.3.4 Copper and Copper Alloys
- 5.3.5 Titanium, Nickel and Other Non-Ferrous Metals
- 5.3.6 Other Materials
- 5.4 By End-Use Industry
- 5.4.1 Automotive and Transportation
- 5.4.2 Aerospace and Defense
- 5.4.3 Industrial Machinery and Capital Equipment
- 5.4.4 Metal Products and Fabrication
- 5.4.5 Electrical and Electronics
- 5.4.6 Construction and Infrastructure
- 5.4.7 Energy and Power
- 5.4.8 Consumer Appliances and Durable Goods
- 5.4.9 Medical and Precision Manufacturing
- 5.4.10 Other End-Use Industries
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 TRUMPF Inc.
- 6.4.2 AMADA AMERICA, INC.
- 6.4.3 Bystronic Inc.
- 6.4.4 Komatsu America Industries LLC
- 6.4.5 Schuler Inc.
- 6.4.6 Cincinnati Incorporated
- 6.4.7 Prima Power North America Inc.
- 6.4.8 Salvagnini America, Inc.
- 6.4.9 LVD Company NV
- 6.4.10 MC Machinery Systems, Inc.
- 6.4.11 Mazak Optonics Corporation
- 6.4.12 Mitsubishi Electric Automation, Inc.
- 6.4.13 Beckwood Press Company
- 6.4.14 Greenerd Press & Machine Company, Inc.
- 6.4.15 AIDA Engineering, Ltd.
- 6.4.16 Fagor Arrasate S. Coop.
- 6.4.17 Wilson Tool International
- 6.4.18 Piranha Fabrication Equipment
- 6.4.19 Accurpress
- 6.4.20 Ermak USA, Inc.
- 6.4.21 Haco-Atlantic, Inc.
- 6.4.22 Pacific Press Technologies
- 6.4.23 Wysong and Miles Company
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Retrofit-First Automation for Small and Mid-Sized Fabricators
- 7.1.2 Domestic Service and Spare-Parts Localization
- 7.1.3 Low-Energy Forming for Electrified Production Lines
- 7.1.4 Flexible Cells for High-Mix, Low-Volume Production
- 7.1.5 Cybersecure Connectivity for Legacy Equipment


