

|
시장보고서
상품코드
2106278
차세대 약물 복합체 시장(제2판) : 약물 복합체 유형, 표적 리간드, 페이로드, 투여 경로, 치료법, 치료 영역, 지역별 동향 및 판매 예측(-2035년)Next Generation Drug Conjugates Market (2nd Edition) by Type of Drug Conjugate, Targeting Ligand, Payload, Route of Administration, Type of Therapy, Therapeutic Area, Geographical Regions, and Sales Forecast - Trends and Forecast, Till 2035 |
||||||

차세대 약물 복합체 시장 : 개요
Roots Analysis 조사에 의하면, 세계의 차세대 약물 복합체 시장 규모는 올해 번 112억 달러에서 2035년에는 262억 달러로 확대되어 2035년까지 예측 기간중은 CAGR 9.9%로 성장한다고 추정되고 있습니다.
차세대 약물 복합체 시장 : 성장 및 동향
차세대 약물 복합체(XDC)는 다양한 유효 성분, 링커 기술, 표적화 메커니즘을 활용하여 표적 외 독성을 최소화하면서 병변 조직으로의 치료제 정밀 전달을 가능하게 합니다. 첨단 화학 공학 기술, 혁신적인 설계 기법, 고특이성 표적화 모달리티의 도입을 통해 치료 계수 및 유효성이 대폭 향상되어, 더욱 정교한 부위 특이적 치료 옵션의 개발이 가능해졌습니다.
차세대 약물 복합체 시장은 올리고뉴클레오티드, 펩타이드, 저분자 화합물 등의 페이로드 기술의 지속적인 진보에 더해, 분자 안정성을 높이고 약물의 제어 방출을 가능하게 하는 링커 설계 및 접합 플랫폼의 혁신을 배경으로 급속히 확대되고 있습니다. 한편, 이러한 기술 발전에도 불구하고 페이로드와 표적 간의 적합성, 제조의 확장성, 물리화학적 복잡성과 관련된 과제는 여전히 남아 있어, 보다 광범위한 도입 및 상용화의 장벽이 되고 있습니다.
종양, 희귀질환, 면역 매개 질환에서의 XDC 적용 확대에 더해, 정밀의료 및 다각적 치료 접근법에 대한 투자 증가가 맞물리면서 시장의 성장세는 지속될 것으로 예측됩니다. 그 결과, 차세대 약물 복합체는 차세대 약물 복합체는 접합체 치료제 시장 전체에서도 특히 유망하고 혁신성이 높은 분야로 주목받고 있습니다.
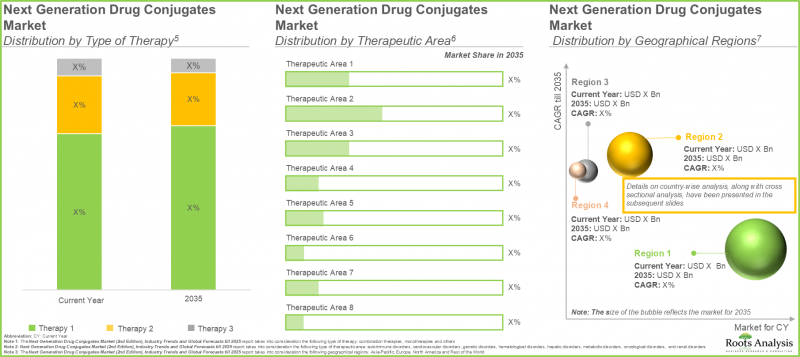
차세대 약물 복합체 시장의 세분화
시장 규모 및 기회 분석은 다음 매개변수를 기준으로 분류됩니다.
약물 복합체 유형별
- 리간드 매개형 RNAi 복합체
- 리간드 결합 안티센스 의약품
- 펩타이드·방사성 핵종 복합체
- 저분자 약물 복합체
- 바이러스 유사 약물 복합체
- 방사성 약물 복합체
표적 리간드별
- 아미노당
- 펩타이드
- 지질
- 바이러스 유사 입자
- 기타
페이로드별
- siRNA
- 방사성 핵종
- 안티센스 올리고뉴클레오티드
- 약물
- 기타
투여 경로별
- 피하
- 정맥 내
- 맥락막 상강 투여
- 기타
치료 유형별
- 단일 요법
- 병용 요법
- 기타
치료 분야별
- 유전성 질환
- 종양성 질환
- 대사성 질환
- 심혈관 질환
- 자가면역 질환
- 혈액 질환
- 신장 질환
- 간 질환
지역별
- 북미
- 미국
- 캐나다
- 유럽
- 독일
- 스페인
- 프랑스
- 영국
- 이탈리아
- 기타 유럽
- 아시아태평양
- 중국
- 일본
- 호주
- 기타 아시아태평양
- 세계 기타 지역
- 브라질
- 아르헨티나
- 사우디아라비아
차세대 의약품 접합체 시장 : 주요 부문 분석
리간드 매개형 RNAi 복합체가 암 치료제 개발을 주도
리간드 매개형 RNAi 복합체는 현재 약 55%의 점유율을 차지하며 시장을 선도하고 있습니다. 이러한 우위는 효능 향상과 안전성 프로파일 개선을 실현하는 치료법에 대한 수요가 증가하고 있기 때문입니다.
바이러스 유사 약물 복합체의 높은 성장 가능성
바이러스 유사 약물 복합체는 예측 기간 동안 비교적 높은 연평균 성장률(CAGR)로 성장할 것으로 예상되어, 큰 성장 잠재력을 가지고 있습니다. 이러한 성장은 천연 바이러스의 세포 침투 경로를 모방함으로써 치료용 페이로드를 세포 내부로 고효율로 전달할 수 있기 때문입니다.
피하 투여가 시장 확대를 주도
시장 예측에 따르면, 피하 투여는 현재 투여 경로별 시장 매출의 60% 이상을 차지하고 있습니다. 이러한 우위는 투여의 용이성, 환자 순응도 향상, 병원 시술에 대한 의존도 감소, 암 환자 수 증가, 암 정밀의료의 발전, 연구개발 투자 확대 등에 의해 뒷받침되고 있습니다.
단일 요법이 계속해서 주류를 이룰 전망
시장 분석에 따르면, 현재 차세대 약물 복합체의 약 95%가 단일 요법으로 처방되고 있으며, 이러한 추세는 앞으로도 지속될 것으로 예측됩니다. 그 주된 이유로는 투여 요법이 간편하다는 점, 독성을 저감할 수 있다는 점, 장기적인 질환 관리 및 맞춤형 치료에 적합하다는 점이 꼽힙니다. 이러한 경향을 뒷받침하는 최근 승인된 의약품으로는 GIVLAARI®(기보실란), OXLUMO®(루마실란), Leqvio®(인크리실란), AMVUTTRA®(부트리실란), PLUVICTO®(루테튬-177 비피보티드 테트라세탄), Illuccix®(Ga-68 PSMA-11) 등이 있습니다.
북미가 시장 동향을 주도
북미는 2035년까지 차세대 약물 복합체 시장의 55% 이상을 차지하며, 최대 지역 시장이 될 것으로 예측됩니다. 이러한 우위는 산학 협력의 강점, 복잡한 약물 복합체를 제조하는 첨단 기술력, 견고한 지적 재산권 제도에 의해 뒷받침되고 있습니다. 이 지역에서 승인된 주요 XDC로는 GIVLAARI(R), DAWNZERA(TM), TRYNGOLZA(R), WAINZUA, Lutathera 등이 있으며, 이들 제품은 2025년에 약 8억 달러의 순매출을 기록했습니다.
유럽의 강력한 성장 전망
유럽의 차세대 약물 복합체 시장은 예측 기간 동안 약 14%의 연평균 성장률(CAGR)로 성장할 것으로 전망됩니다. 이러한 성장은 Novartis, Novo Nordisk, AstraZeneca, Bayer 등 주요 바이오의약품 기업들이 해당 지역에 진출해 지속적으로 혁신과 개발을 강화하고 있는 데 힘입은 것입니다.
본 보고서는 전 세계 차세대 약물 복합체 시장을 조사했으며, 시장 개요, 배경, 시장 영향요인 분석, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 현황, 주요 기업 프로파일 등을 정리했습니다.
목차
제1장 배경
제2장 조사 방법
제3장 시장 역학
제4장 거시경제 지표
제5장 주요 요약
제6장 서론
제7장 시장 구도
제8장 기업 개요
제9장 임상시험 분석
제10장 제휴와 협력 관계
제11장 학술 연구 보조금 분석
제12장 논문 분석
제13장 약제 실패 분석
제14장 성공 프로토콜 분석
제15장 세계의 차세대 약물 복합체 시장
제16장 차세대 약물 복합체 시장 : 약물 복합체 유형별
제17장 차세대 약물 복합체 시장 : 표적 리간드별
제18장 차세대 약물 복합체 시장 : 페이로드별
제19장 차세대 약물 복합체 시장 : 투여 경로별
제20장 차세대 약물 복합체 시장 : 치료 유형별
제21장 차세대 약물 복합체 시장 : 치료 영역별
제22장 차세대 약물 복합체 시장 : 지역별
제23장 시장 기회 분석 : 북미
제24장 시장 기회 분석 : 유럽
제25장 시장 기회 분석 : 아시아태평양
제26장 시장 기회 분석 : 기타 지역
제27장 차세대 약물 복합체 시장 : 판매 예측
제28장 결론
제29장 주요 인사이트
제30장 부록 1 : 표 형식 데이터
제31장 부록 2 : 기업 및 조직 리스트
LSH 26.08.19NEXT GENERATION DRUG CONJUGATES MARKET: OVERVIEW
As per Roots Analysis, the global next generation drug conjugates market is estimated to grow from USD 11.2 billion in the current year to USD 26.2 billion by 2035, at a CAGR of 9.9% during the forecast period, till 2035.
NEXT GENERATION DRUG CONJUGATES MARKET: GROWTH AND TRENDS
Next generation drug conjugates (XDCs) leverage diverse payloads, linker technologies, and targeting mechanisms to facilitate the precise delivery of therapeutic agents to diseased tissues while minimizing off-target toxicity. The incorporation of advanced chemical engineering techniques, innovative design approaches, and highly specific targeting modalities has significantly improved their therapeutic index and efficacy, enabling the development of more sophisticated, site-directed treatment options.
The next generation drug conjugates landscape is witnessing rapid expansion, supported by continuous advancements in payload technologies, including oligonucleotides, peptides, and small molecules, as well as innovations in linker design and conjugation platforms that enhance molecular stability and enable controlled drug release. However, despite these technological developments, challenges related to payload-target compatibility, manufacturing scalability, and physicochemical complexity continue to pose barriers to broader adoption and commercialization.
Growing application of XDCs across oncology, rare diseases, and immune-mediated disorders, coupled with increasing investments in precision medicine and multimodal therapeutic approaches, is expected to sustain market momentum. As a result, next generation drug conjugates are emerging as a highly promising and transformative segment within the broader conjugate therapeutics industry.
Growth Drivers: Strategic Enablers of Market Expansion
The next generation drug conjugates (XDCs) field is undergoing rapid evolution, driven by continuous advancements in targeting precision, payload innovation, and hybrid therapeutic design. Improvements in linker stability, payload potency, and targeted delivery technologies are enhancing the therapeutic index of XDCs, enabling more effective eradication of diseased cells while reducing off-target toxicity. At the same time, increasing interest in RNA-based therapeutics is accelerating innovation in oligonucleotide payloads, with developers focusing on improving molecular stability, intracellular delivery, and controlled-release capabilities to unlock new opportunities in precision gene regulation. Building on these advances, the emergence of hybrid XDCs that integrate multiple payload modalities, including small molecules, peptides, and oligonucleotides, is expanding the therapeutic potential of conjugate platforms. These next generation constructs can simultaneously address multiple disease pathways through dual- or multi-mechanism approaches, positioning XDCs as a transformative therapeutic class capable of overcoming the limitations of conventional monotherapies and addressing increasingly complex disease indications.
Market Challenges: Critical Barriers Impeding Progress
The next generation drug conjugates (XDCs) market continues to face several development and commercialization challenges despite ongoing technological advancements. A key obstacle is achieving optimal compatibility between payloads, linkers, and targeting moieties, as variations in biological targets and intracellular delivery pathways can impact therapeutic efficacy and safety. In addition, the increasing structural complexity of XDCs, particularly those incorporating novel payloads such as oligonucleotides, peptides, and multi-functional constructs, creates significant manufacturing and scalability challenges related to process consistency, quality control, and cost efficiency. Furthermore, the physicochemical complexity of these therapeutics can affect stability, formulation, and pharmacokinetic performance, while evolving regulatory requirements for emerging conjugate modalities often necessitate extensive characterization and validation efforts. Collectively, these factors can prolong development timelines, increase commercialization costs, and present barriers to the broader adoption of next generation drug conjugates.
NEXT GENERATION DRUG CONJUGATES MARKET: KEY INSIGHTS
The report delves into the current state of the next generation drug conjugates market and identifies potential growth opportunities within the industry. Some key findings from the report include:
1. More than 320 XDCs (~270 unique therapies) are currently approved / being investigated across various stages of development for various indications; of these, close to 60% are under different phases of clinical trials.
2. Most (40%) of the XDC therapy programs are classified as ligand-drug conjugates; of these, over 95% function through sequence-specific target binding, ensuring covalent stability and exclusive payload delivery to target cells.
3 Most of the trials (~30%) were registered in H2 2025; notably, more than 70% of the registered trials are currently recruiting potential candidates for investigating next generation drug conjugates for various indications.
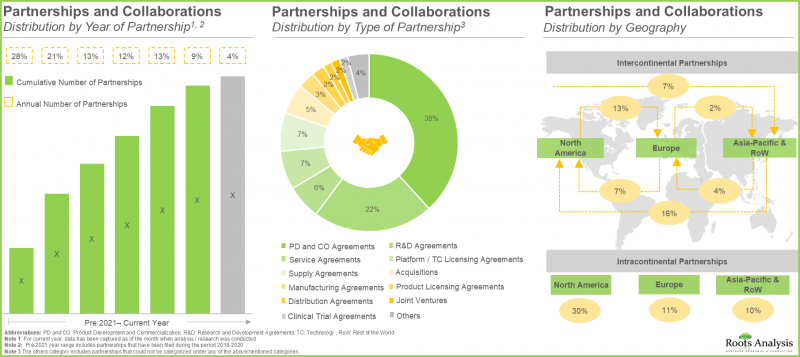
4. The growing interest in this industry is evident from the rise in partnership activity; in fact, the maximum number of collaborations related to next generation drug conjugates were inked in 2021 and 2024.
5. Close to 70% of the grants related to next generation drug conjugates were allocated for non-small business innovative research / small business technology transfer research.
6. The rising number of scientific articles being published in next generation drug conjugates market is indicative of the substantial efforts being undertaken by various stakeholders active in this domain.
7. 60% of the next generation drug conjugates were discontinued in Phase II of clinical trials; further, more than 45% of the conjugates that have been discontinued till date were ligand mediated RNAi conjugates.
8. The next generation drug conjugates market is likely to grow at an annualized rate (CAGR) of 9.9%, till 2035; notably, the ligand-mediated RNAi conjugates is anticipated to capture the majority share in the market by 2035.
9. Currently, majority of the market share is captured by the genetic disorders sub-segment; a substantial market share is expected to be captured by North America, by 2035.
Next Generation Drug Conjugates Market Segments
The market sizing and opportunity analysis has been segmented across the following parameters:
By Type of Drug Conjugate
- Ligand Mediated RNAi Conjugates
- Ligand Conjugated Antisense Medicines
- Peptide-Radionuclide Conjugates
- Small Molecule Drug Conjugates
- Virus-like Drug Conjugates
- Radioconjugates
By Type of Targeting Ligand
- Amino Sugars
- Peptides
- Lipids
- Virus-like Particles
- Others
By Type of Payload
- siRNAs
- Radionuclides
- Antisense Oligonucleotides
- Drugs
- Others
By Route of Administration
- Subcutaneous
- Intravenous
- Suprachoroidal
- Others
By Type of Therapy
- Monotherapies
- Combination Therapies
- Others
By Therapeutic Area
- Genetic Disorders
- Oncological Disorders
- Metabolic Disorders
- Cardiovascular Disorders
- Autoimmune Disorders
- Hematological Disorders
- Renal Disorders
- Hepatic Disorders
By Geographical Regions
- North America
- US
- Canada
- Europe
- Germany
- Spain
- France
- UK
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- Australia
- Rest of Asia-Pacific
- Rest of the World
- Brazil
- Argentina
- Saudi Arabia
NEXT GENERATION DRUG CONJUGATES MARKET: KEY SEGMENT INSIGHTS
Ligand-Mediated RNAi Conjugates Driving Cancer Therapy Development
According to the next generation drug conjugates market forecast, ligand-mediated RNAi conjugates currently dominate the market with approximately 55% share, driven by increasing demand for therapies with enhanced efficacy and improved safety profiles.
Growth Potential of Virus-Like Drug Conjugates
Virus-like drug conjugates are projected to expand at a higher CAGR, indicating significant growth potential over the forecast period. This growth is attributed to their ability to mimic natural viral entry pathways, enabling highly efficient intracellular delivery of therapeutic payloads.
Subcutaneous Administration Driving Market Expansion
Based on market forecasts, subcutaneous administration accounts for more than 60% of current revenues across routes of administration. This dominance is supported by ease of administration, improved patient adherence, reduced reliance on hospital-based procedures, rising cancer prevalence, advancements in oncology precision medicine, and increasing R&D investments in the field.
Next Generation Drug Conjugate Monotherapies to Remain Dominant
According to market analysis, approximately 95% of next generation drug conjugates are currently prescribed as monotherapy, a trend expected to persist in the foreseeable future. This is primarily due to simplified dosing regimens, reduced toxicity, and suitability for long-term disease management and personalized treatment approaches. Recent approvals supporting this trend include GIVLAARI(R) (givosiran), OXLUMO(R) (lumasiran), Leqvio(R) (inclisiran), AMVUTTRA(R) (vutrisiran), PLUVICTO(R) (lutetium Lu 177 vipivotide tetraxetan), and Illuccix(R) (Ga-68 PSMA-11).
North America Dominating the Market Landscape
North America is expected to lead the next generation drug conjugates market, accounting for over 55% share by 2035. This dominance is driven by strong academia-industry collaborations, advanced manufacturing capabilities for complex conjugates, and a robust intellectual property framework. Notable approved XDCs in the region include GIVLAARI(R), DAWNZERA(TM), TRYNGOLZA(R), WAINZUA, and Lutathera, which generated approximately USD 0.8 billion in net sales in 2025.
Strong Growth Outlook for Europe
The European next generation drug conjugates market is projected to grow at a CAGR of approximately 14% over the forecast period. This growth is supported by the presence of leading biopharmaceutical companies such as Novartis, Novo Nordisk, AstraZeneca, and Bayer, which continue to strengthen innovation and development within the region.
Example Players in Next Generation Drug Conjugates Market
- Alnylam Pharmaceuticals
- Arrowhead Pharmaceuticals
- Geron
- Ionis Pharmaceuticals
- Novartis
- Novo Nordisk
- Stemline Therapeutics
- Telix Pharmaceuticals
Next Generation Drug Conjugates Market Experts
The opinions and insights presented in this study were influenced by discussions conducted with multiple stakeholders. The research report features detailed transcripts of the following third-party discussions:
- Doctor of Medicine, Large Organization, Canada, North America
- Doctor of Medicine, PhD, Large Organization, Spain, Europe
- Vice President of Biologics Engineering and Tumor-Targeted Delivery, Large Organization, Europe
- Surgical Oncologist, Cancer Research Organization, Denver, North America
- Doctor of Medicine, Cancer Research Organization, US, North America
- Chief Executive Officer, Large Organization, UK, Europe
NEXT GENERATION DRUG CONJUGATES MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: The report features an in-depth analysis of the next generation drug conjugates market, focusing on key market segments, including [A] type of drug conjugate, [B] type of targeting ligand, [C] type of payload, [D] route of administration, [E] type of therapy, [F] therapeutic area, [G] geographical regions, and [H] sales forecast.
- Market Landscape: A detailed assessment of the overall next generation drug conjugates drugs landscape, featuring information on several relevant parameters, such as [A] stage of development, [B] type of conjugate, [C] mechanism of action, [D] type of therapy, [E] route of administration, [F] target indication, [G] therapeutic area, [H] target patient population [I] year of establishment, [J] company size, [K] location of headquarters, and [L] most active players.
- Company Profiles: In-depth profiles of key drug developers in the next generation drug conjugate market, focusing on [A] company overview, [B] financial information, [C] drug portfolio, [D] recent developments and [E] an informed future outlook.
- Clinical Trial Analysis: An analysis of completed and ongoing clinical trials related to next generation drug conjugates, based on several relevant parameters, such as [A] trial registration year, [B] enrolled patient population, [C] trial phase, [D] trial status, [E] type of sponsor / collaborator, [F] patient gender, [G] study design (type of trial masking, type of intervention model, trial purpose and design allocation), [H] leading industry and non-industry players (based on number of clinical trials) and [I] geography.
- Partnerships and Collaborations: An analysis of partnerships and collaborations signed in the next generation drug conjugates market, based on several relevant parameters, such as [A] year of partnership, [B] type of partnership, [C] therapeutic area, [D] most active players, and [E] regional analysis.
- Academic Grants Analysis: A comprehensive academic grants analysis, based on several parameters, such as [A] year of grant award, [B] amount awarded, [C] funding institute center, [D] support period, [E] type of grant application, [F] purpose of grant and [G] most popular recipient organizations.
- Publication Analysis: An insightful publication analysis, based on several parameters, such as [A] year of publication, [B] type of publication, [C] most active publishers, and [D] most popular journals.
- Drug Failure Analysis: An insightful drug failure analysis, based on several parameters, such as [A] trial phase, [B] trial status, [C] reason for drug discontinuation, [D] study start year, [E] year of discontinuation, [F] type of molecule, and [G] route of administration.
- Success Protocol Analysis: An insightful analysis of recently approved next generation drug conjugates, based on several relevant parameters, such as [A] dosing frequency, [B] drug exclusivity, [C] safety and efficacy, [D] geographical reach, [E] intra-class competition, [F] line of treatment, [G] prevalence, [H] price, [I] type of therapy, and [J] existing competition among developers.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which are the leading companies in the next generation drugs market?
- Which region dominates the next generation drugs market?
- What are the key trends observed in the next generation drugs market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by next generation drug developers?
- What is the current and future market size?
- What is the CAGR of this market?
- How is the current and future market opportunity likely to be distributed across key market segments?
REASONS TO BUY THIS REPORT
- The report provides a comprehensive market analysis, offering detailed revenue projections of the overall market and its specific sub-segments. This information is valuable to both established market leaders and emerging entrants.
- The report offers stakeholders a comprehensive overview of the market, including key drivers, barriers, opportunities, and challenges. This information empowers stakeholders to stay abreast of market trends and make data-driven decisions to capitalize on growth prospects.
- The report can aid businesses in identifying future opportunities in any sector. It also helps in understanding if those opportunities are worth pursuing.
- The report helps in identifying customer demand by understanding the needs, preferences, and behavior of the target audience in order to tailor products or services effectively.
- The report equips new entrants with requisite information regarding a particular market to help them build successful business strategies.
- The report allows for more effective communication with the audience and in building strong business relations.
ADDITIONAL BENEFITS
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. BACKGROUND
- 1.1. Context
- 1.2. Project Objectives
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations on the Industry
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
- 5.1. Executive Summary: Market Landscape
- 5.2. Executive Summary: Market Trends
- 5.3. Executive Summary: Market Forecast and Opportunity Analysis
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. Overview of Next Generation Drug Conjugates
- 6.3. Key Historical Events
- 6.4. Structure of Next Generation Drug Conjugates
- 6.5. Biochemical Interaction and Mechanism of Action
- 6.6. Key Target Indications
- 6.7. Advantages of Next Generation Drug Conjugates
- 6.8. Challenges Associated with Next Generation Drug Conjugates
- 6.9. Future Perspective
7. MARKET LANDSCAPE
- 7.1. Methodology and Key Parameters
- 7.2. Next Generation Drug Conjugates: List of Therapy Programs
- 7.2.1. Analysis by Stage of Development
- 7.2.2. Analysis by Type of Conjugate
- 7.2.3. Analysis by Mechanism of Action
- 7.2.4. Analysis by Type of Therapy
- 7.2.5. Analysis by Route of Administration
- 7.2.6. Analysis by Target Indication
- 7.2.7. Analysis by Therapeutic Area
- 7.2.8. Analysis by Target Patient Population
- 7.3. Next Generation Drug Conjugates Therapy Programs: Developer Landscape
- 7.3.1. Analysis by Year of Establishment
- 7.3.2. Analysis by Company Size
- 7.3.3. Analysis by Location of Headquarters
- 7.3.4. Most Active Players: Analysis by Number of Next Generation Drug Conjugates
8. COMPANY PROFILES
- 8.1. Alnylam Pharmaceuticals
- 8.1.1. Company Overview
- 8.1.2. Management Team
- 8.1.3. Drug Portfolio
- 8.1.4. Key Initiatives
- 8.2. Arrowhead Pharmaceuticals
- 8.3. Geron
- 8.4. Ionis Pharmaceuticals
- 8.5. Novartis
- 8.6. Novo Nordisk
- 8.7. Stemline Therapeutics
- 8.8. Telix Pharmaceuticals
9. CLINICAL TRIAL ANALYSIS
- 9.1. Methodology and Key Parameters
- 9.2. Next Generation Drug Conjugates: Clinical Trial Analysis
- 9.2.1. Analysis by Trial Registration Year
- 9.2.2. Analysis by Trial Status
- 9.2.3. Analysis by Trial Registration Year and Trial Status
- 9.2.4. Analysis of Patient Enrolled by Trial Registration Year
- 9.2.5. Analysis by Trial Phase
- 9.2.6. Analysis of Patient Enrolled by Trial Phase
- 9.2.7. Analysis by Type of Sponsor / Collaborator
- 9.2.8. Analysis by Study Design
- 9.2.9. Analysis by Target Patient Population
- 9.2.10. Most Active Industry Players: Analysis by Number of Clinical Trials
- 9.2.11. Most Active Non-Industry Players: Analysis by Number of Clinical Trials
- 9.2.12. Geographical Distribution: Analysis by Number of Trials and Patients Enrolled
- 9.2.13. Analysis by Trial Status and Geography
- 9.2.14. Analysis of Patients Enrolled by Trial Status and Geography
10. PARTNERSHIPS AND COLLABORATIONS
- 10.1. Methodology and Key Parameters
- 10.2. Partnership Models
- 10.3. Next Generation Drug Conjugates: Partnerships and Collaborations
- 10.3.1. Analysis by Year of Partnership
- 10.3.2. Analysis by Type of Partnership
- 10.3.3. Analysis by Year and Type of Partnership
- 10.3.4. Analysis by Therapeutic Area
- 10.3.5. Most Active Players: Analysis by Number of Partnerships
- 10.3.6. Analysis by Local and International Agreements
- 10.3.7. Analysis by Intercontinental and Intracontinental Agreements
11. ACADEMIC GRANTS ANALYSIS
- 11.1. Methodology and Key Parameters
- 11.2. Next Generation Drug Conjugates: Academic Grants Analysis
- 11.2.1. Analysis by Year of Grant Award
- 11.2.2. Analysis by Amount Awarded
- 11.2.3. Analysis by Funding Institute Center
- 11.2.4. Analysis by Support Period
- 11.2.5. Analysis by Funding Institute Center and Support Period
- 11.2.6. Analysis by Type of Grant Application
- 11.2.7. Analysis by Purpose of Grant
- 11.2.8. Analysis by Activity Code
- 11.2.9. Analysis by Study Section
- 11.2.10. Popular NIH Departments: Analysis by Number of Grants
- 11.2.11. Analysis by Type of Recipient Organization
- 11.2.11.1. Most Popular Recipient Organizations: Analysis by Number of Grants
- 11.2.11.2. Most Popular Recipient Organizations: Analysis by Amount Awarded
- 11.2.12. Prominent Program Officers: Analysis by Number of Grants
- 11.2.13. Analysis by Location of Recipient Organizations in the US
12. PUBLICATION ANALYSIS
- 12.1. Methodology and Key Parameters
- 12.2. Next Generation Drug Conjugates: Publication Analysis
- 12.2.1. Analysis by Year of Publication
- 12.2.2. Analysis by Type of Publication
- 12.2.3. Analysis by Year and Type of Publication
- 12.2.4. Most Active Publishers: Analysis by Number of Publications
- 12.2.5. Most Popular Journals: Analysis by Number of Publications
- 12.2.6. Most Popular Journals: Analysis by Impact Factor
13. DRUG FAILURE ANALYSIS
- 13.1. Methodology and Key Parameters
- 13.2. Next Generation Drug Conjugates: Drug Failure Analysis
- 13.2.1. Analysis by Trial Phase
- 13.2.2. Analysis by Trial Status
- 13.2.3. Analysis by Reason for Drug Discontinuation
- 13.2.4. Analysis by Study Start Year and Year of Discontinuation
- 13.2.5. Analysis by Target Indication
- 13.2.6. Analysis by Type of Conjugate
- 13.2.7. Analysis by Type of Sponsor / Collaborator
14. SUCCESS PROTOCOL ANALYSIS
- 14.1. Methodology and Key Parameters
- 14.2. Scoring Criteria
- 14.3. Success Protocol Analysis
- 14.4. Harvey Ball Analysis: Assessment of Approved Next Generation Drug Conjugates across Key Parameters
15. GLOBAL NEXT GENERATION DRUG CONJUGATES MARKET
- 15.1. Chapter Overview
- 15.2. Key Assumptions and Methodology
- 15.3. Next Generation Drug Conjugates Market, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 15.3.1. Scenario Analysis
- 15.3.1.1. Conservative Scenario
- 15.3.1.2. Optimistic Scenario
- 15.3.1. Scenario Analysis
- 15.4. Key Market Segmentations
16. NEXT GENERATION DRUG CONJUGATES MARKET, BY TYPE OF CONJUGATE
- 16.1. Next Generation Drug Conjugates Market: Distribution by Type of Conjugate
- 16.1.1. Next Generation Drug Conjugates Market for Ligand Mediated RNAi Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 16.1.2. Next Generation Drug Conjugates Market for Ligand Conjugated Antisense Medicines, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 16.1.3. Next Generation Drug Conjugates Market for Peptide-Radionuclide Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 16.1.4. Next Generation Drug Conjugates Market for Small Molecule Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 16.1.5. Next Generation Drug Conjugates Market for Virus-like Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 16.1.6. Next Generation Drug Conjugates Market for Radioconjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
17. NEXT GENERATION DRUG CONJUGATES MARKET, BY TYPE OF TARGETING LIGAND
- 17.1. Next Generation Drug Conjugates Market: Distribution by Type of Targeting Ligand
- 17.1.1. Next Generation Drug Conjugates Market for Amino Sugars, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 17.1.2. Next Generation Drug Conjugates Market for Peptides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 17.1.3. Next Generation Drug Conjugates Market for Lipids, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 17.1.4. Next Generation Drug Conjugates Market for Virus-like Particles, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 17.1.5. Next Generation Drug Conjugates Market for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
18. NEXT GENERATION DRUG CONJUGATES MARKET, BY TYPE OF PAYLOAD
- 18.1. Next Generation Drug Conjugates Market: Distribution by Type of Payload
- 18.1.1. Next Generation Drug Conjugates Market for siRNAs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 18.1.2. Next Generation Drug Conjugates Market for Radionuclides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 18.1.3. Next Generation Drug Conjugates Market for Antisense Oligonucleotides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 18.1.4. Next Generation Drug Conjugates Market for Drugs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 18.1.5. Next Generation Drug Conjugates Market for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
19. NEXT GENERATION DRUG CONJUGATES MARKET, BY ROUTE OF ADMINISTRATION
- 19.1. Next Generation Drug Conjugates Market: Distribution by Route of Administration
- 19.1.1. Next Generation Drug Conjugates Market for Subcutaneous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 19.1.2. Next Generation Drug Conjugates Market for Intravenous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 19.1.3. Next Generation Drug Conjugates Market for Suprachoroidal, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 19.1.4. Next Generation Drug Conjugates Market for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
20. NEXT GENERATION DRUG CONJUGATES MARKET, BY TYPE OF THERAPY
- 20.1. Next Generation Drug Conjugates Market: Distribution by Type of Therapy
- 20.1.1. Next Generation Drug Conjugates Market for Monotherapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 20.1.2. Next Generation Drug Conjugates Market for Combination Therapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 20.1.3. Next Generation Drug Conjugates Market for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
21. NEXT GENERATION DRUG CONJUGATES MARKET, BY THERAPEUTIC AREA
- 21.1. Next Generation Drug Conjugates Market: Distribution by Therapeutic Area
- 21.1.1. Next Generation Drug Conjugates Market for Genetic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 21.1.2. Next Generation Drug Conjugates Market for Oncological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 21.1.3. Next Generation Drug Conjugates Market for Metabolic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 21.1.4. Next Generation Drug Conjugates Market for Cardiovascular Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 21.1.5. Next Generation Drug Conjugates Market for Autoimmune Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 21.1.6. Next Generation Drug Conjugates Market for Hematological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 21.1.7. Next Generation Drug Conjugates Market for Renal Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 21.1.8. Next Generation Drug Conjugates Market for Hepatic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
22. NEXT GENERATION DRUG CONJUGATES MARKET, BY GEOGRAPHICAL REGIONS
- 22.1. Next Generation Drug Conjugates Market: Distribution by Geographical Regions
- 22.1.1. Next Generation Drug Conjugates Market in North America, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.1.1.1. Next Generation Drug Conjugates Market in the US, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.1.1.2. Next Generation Drug Conjugates Market in Canada, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.1.1. Next Generation Drug Conjugates Market in North America, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.2. Next Generation Drug Conjugates Market in Europe, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.2.1. Next Generation Drug Conjugates Market in Germany, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.2.2. Next Generation Drug Conjugates Market in Spain, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.2.3. Next Generation Drug Conjugates Market in France, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.2.4. Next Generation Drug Conjugates Market in the UK, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.2.5. Next Generation Drug Conjugates Market in Italy, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.2.6. Next Generation Drug Conjugates Market in Rest of Europe, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.3. Next Generation Drug Conjugates Market in Asia-Pacific, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.3.1. Next Generation Drug Conjugates Market in China, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.3.2. Next Generation Drug Conjugates Market in Japan, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.3.3. Next Generation Drug Conjugates Market in Australia, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.3.4. Next Generation Drug Conjugates Market in Rest of Asia-Pacific, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.4. Next Generation Drug Conjugates Market in Rest of the World, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.4.1. Next Generation Drug Conjugates Market in Brazil, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.4.2. Next Generation Drug Conjugates Market in Argentina, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 22.4.3. Next Generation Drug Conjugates Market in Saudi Arabia, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
23. MARKET OPPORTUNITY ANALYSIS: NORTH AMERICA
- 23.1 Next Generation Drug Conjugates Market in North America: Distribution by Type of Conjugate
- 23.1.1. Next Generation Drug Conjugates Market in North America for Ligand Mediated RNAi Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.1.2. Next Generation Drug Conjugates Market in North America for Ligand Conjugated Antisense Medicines, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.1.3. Next Generation Drug Conjugates Market in North America for Peptide-Radionuclide Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.1.4. Next Generation Drug Conjugates Market in North America for Small Molecule Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.1.5. Next Generation Drug Conjugates Market in North America for Virus-like Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.1.6. Next Generation Drug Conjugates Market in North America for Radioconjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.2. Next Generation Drug Conjugates Market in North America: Distribution by Type of Targeting Ligand
- 23.2.1. Next Generation Drug Conjugates Market in North America for Amino Sugars, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.2.2. Next Generation Drug Conjugates Market in North America for Peptides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.2.3. Next Generation Drug Conjugates Market in North America for Lipids, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.2.4. Next Generation Drug Conjugates Market in North America for Virus-like Particles, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.2.5. Next Generation Drug Conjugates Market in North America for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.3. Next Generation Drug Conjugates Market in North America: Distribution by Type of Payload
- 23.3.1. Next Generation Drug Conjugates Market in North America for siRNAs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.3.2. Next Generation Drug Conjugates Market in North America for Radionuclides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.3.3. Next Generation Drug Conjugates Market in North America for Antisense Oligonucleotides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.3.4. Next Generation Drug Conjugates Market in North America for Drugs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.3.5. Next Generation Drug Conjugates Market in North America for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.4. Next Generation Drug Conjugates Market in North America: Distribution by Route of Administration
- 23.4.1. Next Generation Drug Conjugates Market in North America for Subcutaneous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.4.2. Next Generation Drug Conjugates Market in North America for Intravenous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.4.3. Next Generation Drug Conjugates Market in North America for Suprachoroidal, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.4.4. Next Generation Drug Conjugates Market in North America for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.5. Next Generation Drug Conjugates Market in North America: Distribution by Type of Therapy
- 23.5.1. Next Generation Drug Conjugates Market in North America for Monotherapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.5.2. Next Generation Drug Conjugates Market in North America for Combination Therapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.5.3. Next Generation Drug Conjugates Market in North America for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6. Next Generation Drug Conjugates Market in North America: Distribution by Therapeutic Area
- 23.6.1. Next Generation Drug Conjugates Market in North America for Genetic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6.2. Next Generation Drug Conjugates Market in North America for Oncological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6.3. Next Generation Drug Conjugates Market in North America for Metabolic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6.4. Next Generation Drug Conjugates Market in North America for Cardiovascular Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6.5. Next Generation Drug Conjugates Market in North America for Autoimmune Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6.6. Next Generation Drug Conjugates Market in North America for Hematological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6.7. Next Generation Drug Conjugates Market in North America for Renal Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 23.6.8. Next Generation Drug Conjugates Market in North America for Hepatic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
24. MARKET OPPORTUNITY ANALYSIS: EUROPE
- 24.1 Next Generation Drug Conjugates Market in Europe: Distribution by Type of Conjugate
- 24.1.1 Next Generation Drug Conjugates Market in Europe for Ligand Mediated RNAi Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.1.2. Next Generation Drug Conjugates Market in Europe for Ligand Conjugated Antisense Medicines, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.1.3. Next Generation Drug Conjugates Market in Europe for Peptide-Radionuclide Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.1.4. Next Generation Drug Conjugates Market in Europe for Small Molecule Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.1.5. Next Generation Drug Conjugates Market in Europe for Virus-like Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.1.6. Next Generation Drug Conjugates Market in Europe for Radioconjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.2. Next Generation Drug Conjugates Market in Europe: Distribution by Type of Targeting Ligand
- 24.2.1. Next Generation Drug Conjugates Market in Europe for Amino Sugars, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.2.2. Next Generation Drug Conjugates Market in Europe for Peptides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.2.3. Next Generation Drug Conjugates Market in Europe for Lipids, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.2.4. Next Generation Drug Conjugates Market in Europe for Virus-like Particles, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.2.5. Next Generation Drug Conjugates Market in Europe for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.3. Next Generation Drug Conjugates Market in Europe: Distribution by Type of Payload
- 24.3.1. Next Generation Drug Conjugates Market in Europe for siRNAs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.3.2. Next Generation Drug Conjugates Market in Europe for Radionuclides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.3.3. Next Generation Drug Conjugates Market in Europe for Antisense Oligonucleotides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.3.4. Next Generation Drug Conjugates Market in Europe for Drugs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.3.5. Next Generation Drug Conjugates Market in Europe for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.4. Next Generation Drug Conjugates Market in Europe: Distribution by Route of Administration
- 24.4.1. Next Generation Drug Conjugates Market in Europe for Subcutaneous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.4.2. Next Generation Drug Conjugates Market in Europe for Intravenous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.4.3. Next Generation Drug Conjugates Market in Europe for Suprachoroidal, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.4.4. Next Generation Drug Conjugates Market in Europe for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.5. Next Generation Drug Conjugates Market in Europe: Distribution by Type of Therapy
- 24.5.1. Next Generation Drug Conjugates Market in Europe for Monotherapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.5.2. Next Generation Drug Conjugates Market in Europe for Combination Therapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.5.3. Next Generation Drug Conjugates Market in Europe for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6. Next Generation Drug Conjugates Market in Europe: Distribution by Therapeutic Area
- 24.6.1. Next Generation Drug Conjugates Market in Europe for Genetic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6.2. Next Generation Drug Conjugates Market in Europe for Oncological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6.3. Next Generation Drug Conjugates Market in Europe for Metabolic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6.4. Next Generation Drug Conjugates Market in Europe for Cardiovascular Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6.5. Next Generation Drug Conjugates Market in Europe for Autoimmune Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6.6. Next Generation Drug Conjugates Market in Europe for Hematological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6.7. Next Generation Drug Conjugates Market in Europe for Renal Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 24.6.8. Next Generation Drug Conjugates Market in Europe for Hepatic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
25. MARKET OPPORTUNITY ANALYSIS: ASIA-PACIFIC
- 25.1 Next Generation Drug Conjugates Market in Asia-Pacific: Distribution by Type of Conjugate
- 25.1.1. Next Generation Drug Conjugates Market in Asia-Pacific for Ligand Mediated RNAi Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.1.2. Next Generation Drug Conjugates Market in Asia-Pacific for Ligand Conjugated Antisense Medicines, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.1.3. Next Generation Drug Conjugates Market in Asia-Pacific for Peptide-Radionuclide Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.1.4. Next Generation Drug Conjugates Market in Asia-Pacific for Small Molecule Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.1.5. Next Generation Drug Conjugates Market in Asia-Pacific for Virus-like Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.1.6. Next Generation Drug Conjugates Market in Asia-Pacific for Radioconjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.2. Next Generation Drug Conjugates Market in Asia-Pacific: Distribution by Type of Targeting Ligand
- 25.2.1. Next Generation Drug Conjugates Market in Asia-Pacific for Amino Sugars, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.2.2. Next Generation Drug Conjugates Market in Asia-Pacific for Peptides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.2.3. Next Generation Drug Conjugates Market in Asia-Pacific for Lipids, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.2.4. Next Generation Drug Conjugates Market in Asia-Pacific for Virus-like Particles, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.2.5. Next Generation Drug Conjugates Market in Asia-Pacific for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.3. Next Generation Drug Conjugates Market in Asia-Pacific: Distribution by Type of Payload
- 25.3.1. Next Generation Drug Conjugates Market in Asia-Pacific for siRNAs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.3.2. Next Generation Drug Conjugates Market in Asia-Pacific for Radionuclides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.3.3. Next Generation Drug Conjugates Market in Asia-Pacific for Antisense Oligonucleotides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.3.4. Next Generation Drug Conjugates Market in Asia-Pacific for Drugs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.3.5. Next Generation Drug Conjugates Market in Asia-Pacific for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.4. Next Generation Drug Conjugates Market in Asia-Pacific: Distribution by Route of Administration
- 25.4.1. Next Generation Drug Conjugates Market in Asia-Pacific for Subcutaneous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.4.2. Next Generation Drug Conjugates Market in Asia-Pacific for Intravenous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.4.3. Next Generation Drug Conjugates Market in Asia-Pacific for Suprachoroidal, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.4.4. Next Generation Drug Conjugates Market in Asia-Pacific for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.5. Next Generation Drug Conjugates Market in Asia-Pacific: Distribution by Type of Therapy
- 25.5.1. Next Generation Drug Conjugates Market in Asia-Pacific for Monotherapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.5.2. Next Generation Drug Conjugates Market in Asia-Pacific for Combination Therapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.5.3. Next Generation Drug Conjugates Market in Asia-Pacific for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6. Next Generation Drug Conjugates Market in Asia-Pacific: Distribution by Therapeutic Area
- 25.6.1. Next Generation Drug Conjugates Market in Asia-Pacific for Genetic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6.2. Next Generation Drug Conjugates Market in Asia-Pacific for Oncological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6.3. Next Generation Drug Conjugates Market in Asia-Pacific for Metabolic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6.4. Next Generation Drug Conjugates Market in Asia-Pacific for Cardiovascular Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6.5. Next Generation Drug Conjugates Market in Asia-Pacific for Autoimmune Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6.6. Next Generation Drug Conjugates Market in Asia-Pacific for Hematological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6.7. Next Generation Drug Conjugates Market in Asia-Pacific for Renal Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 25.6.8. Next Generation Drug Conjugates Market in Asia-Pacific for Hepatic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
26. MARKET OPPORTUNITY ANALYSIS: REST OF THE WORLD
- 26.1 Next Generation Drug Conjugates Market in Rest of the World: Distribution by Type of Conjugate
- 26.1.1. Next Generation Drug Conjugates Market in Rest of the World for Ligand Mediated RNAi Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.1.2. Next Generation Drug Conjugates Market in Rest of the World for Ligand Conjugated Antisense Medicines, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.1.3. Next Generation Drug Conjugates Market in Rest of the World for Peptide-Radionuclide Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.1.4. Next Generation Drug Conjugates Market in Rest of the World for Small Molecule Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.1.5. Next Generation Drug Conjugates Market in Rest of the World for Virus-like Drug Conjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.1.6. Next Generation Drug Conjugates Market in Rest of the World for Radioconjugates, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.2. Next Generation Drug Conjugates Market in Rest of the World: Distribution by Type of Targeting Ligand
- 26.2.1. Next Generation Drug Conjugates Market in Rest of the World for Amino Sugars, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.2.2. Next Generation Drug Conjugates Market in Rest of the World for Peptides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.2.3. Next Generation Drug Conjugates Market in Rest of the World for Lipids, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.2.4. Next Generation Drug Conjugates Market in Rest of the World for Virus-like Particles, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.2.5. Next Generation Drug Conjugates Market in Rest of the World for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.3. Next Generation Drug Conjugates Market in Rest of the World: Distribution by Type of Payload
- 26.3.1. Next Generation Drug Conjugates Market in Rest of the World for siRNAs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.3.2. Next Generation Drug Conjugates Market in Rest of the World for Radionuclides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.3.3. Next Generation Drug Conjugates Market in Rest of the World for Antisense Oligonucleotides, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.3.4. Next Generation Drug Conjugates Market in Rest of the World for Drugs, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.3.5. Next Generation Drug Conjugates Market in Rest of the World for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.4. Next Generation Drug Conjugates Market in Rest of the World: Distribution by Route of Administration
- 26.4.1. Next Generation Drug Conjugates Market in Rest of the World for Subcutaneous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.4.2. Next Generation Drug Conjugates Market in Rest of the World for Intravenous, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.4.3. Next Generation Drug Conjugates Market in Rest of the World for Suprachoroidal, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.4.4. Next Generation Drug Conjugates Market in Rest of the World for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.5. Next Generation Drug Conjugates Market in Rest of the World: Distribution by Type of Therapy
- 26.5.1. Next Generation Drug Conjugates Market in Rest of the World for Monotherapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.5.2. Next Generation Drug Conjugates Market in Rest of the World for Combination Therapies, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.5.3. Next Generation Drug Conjugates Market in Rest of the World for Others, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6. Next Generation Drug Conjugates Market in Rest of the World: Distribution by Therapeutic Area
- 26.6.1. Next Generation Drug Conjugates Market in Rest of the World for Genetic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6.2. Next Generation Drug Conjugates Market in Rest of the World for Oncological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6.3. Next Generation Drug Conjugates Market in Rest of the World for Metabolic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6.4. Next Generation Drug Conjugates Market in Rest of the World for Cardiovascular Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6.5. Next Generation Drug Conjugates Market in Rest of the World for Autoimmune Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6.6. Next Generation Drug Conjugates Market in Rest of the World for Hematological Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6.7. Next Generation Drug Conjugates Market in Rest of the World for Renal Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- 26.6.8. Next Generation Drug Conjugates Market in Rest of the World for Hepatic Disorders, Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
27. NEXT GENERATION DRUG CONJUGATES MARKET: SALES FORECAST
- 27.1. AMVUTTRA(R) / Vutrisiran / ALN-TTRSC04 / ALN-TTRSC02: Sales Forecast (USD Million)
- 27.2. AAA617 / PLUVICTO: Sales Forecast (USD Million)
- 27.3. Leqvio(R) / inclisiran: Sales Forecast (USD Million)
- 27.4. ARO-APOC3 / Plozasiran / REDEMPLO: Sales Forecast (USD Million)
- 27.5. Imetelstat: Sales Forecast (USD Million)
- 27.6. Qfitlia(TM) / Fitusiran: Sales Forecast (USD Million)
- 27.7. TRYNGOLZA(R) / olezarsen: Sales Forecast (USD Million)
- 27.8. WAINZUA / Eplontersen: Sales Forecast (USD Million)
- 27.9. Illuccix(R) (68Ga-PSMA-11): Sales Forecast (USD Million)
- 27.10. AAA601 / Lutathera(R): Sales Forecast (USD Million)
- 27.11. Gozellix(R): Sales Forecast (USD Million)
- 27.12. DAWNZERA(TM) / donidalorsen: Sales Forecast (USD Million)
- 27.13. OXLUMO(R) / lumasiran: Sales Forecast (USD Million)
- 27.14. GIVLAARI(R) / givosiran: Sales Forecast (USD Million)
- 27.15. LNTH-2501 / EVG-001: Sales Forecast (USD Million)
- 27.16. Pelacarsen: Sales Forecast (USD Million)
- 27.17. Cemdisiran: Sales Forecast (USD Million)
- 27.18. SAR-bis PSMA: Sales Forecast (USD Million)
- 27.19. RYZ-101: Sales Forecast (USD Million)
- 27.20. ARO-ANG3 / Zodasiran: Sales Forecast (USD Million)
- 27.21. Bel-sar / AU-011: Sales Forecast (USD Million)
- 27.22. RBD7022 / QLC7401: Sales Forecast (USD Million)


