|
시장보고서
상품코드
2109168
훈련기 시장 기회, 성장 촉진요인, 업계 동향 분석 및 예측(2026-2035년)Trainer Aircraft Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 훈련기 시장은 2025년에 43억 달러 규모로 평가되었고, CAGR 6.8%로 성장하여 84억 달러에 이를 것으로 추정되고 있습니다.
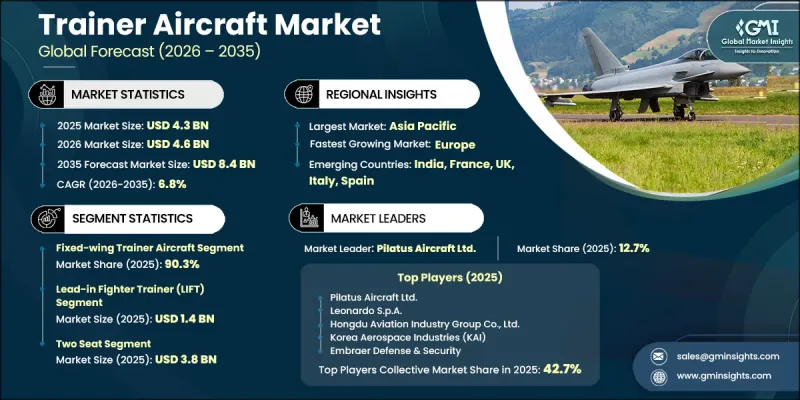
훈련기 업계 전체의 성장은 전 세계적인 자격을 갖춘 조종사 부족의 심화, 국방 분야의 현대화 노력 확대, 국내 훈련기 조달 확대, 그리고 조종사 훈련 프로그램에 첨단 디지털 기술과 시뮬레이션을 활용한 학습 도입이 진행되고 있는 점 등이 원동력이 되고 있습니다. 또한, 조종사 훈련 인프라 강화 및 항공 아카데미 확충을 목적으로 한 민관 투자가 시장 성장에 유리한 환경을 조성하고 있습니다. 더욱이 군사 및 민간 항공 양 분야에서 고도의 기술을 갖춘 항공 인력에 대한 수요가 높아짐에 따라, 각국 정부와 항공 기관은 최신 항공기 플랫폼을 통해 훈련 역량 강화를 도모하고 있습니다. 항공전자 장비, 디지털 비행 시스템, 시뮬레이션 기술의 지속적인 발전으로 훈련 효율이 향상될 뿐만 아니라, 운영 비용 절감과 조종사의 즉시 투입 능력 확보가 촉진되고 있습니다. 전 세계적으로 항공 활동이 지속적으로 확대되는 가운데, 차세대 훈련 솔루션에 대한 투자가 가속화될 것으로 예상되며, 이에 따라 첨단 훈련기의 장기적인 수요가 강화되어 전 세계 훈련기 시장 전체의 지속적인 성장을 뒷받침할 것으로 전망됩니다.
| 시장 범위 | |
|---|---|
| 시작 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 시작 금액 | 43억 달러 |
| 예측 금액 | 84억 달러 |
| CAGR | 6.8% |
세계 훈련기 산업은 군용 및 민간 항공 분야의 비행 훈련 역량 향상을 도모하는 동시에, 조종사 부족 문제에 대응해야 할 필요성이 높아짐에 따라 계속해서 혜택을 받고 있습니다. 항공 당국은 미래의 인력 수요에 대비하기 위해 비행 훈련 인프라 확충을 지원하고, 인증 훈련 기관의 수를 늘리고 있습니다. 동시에, 국방 현대화 프로그램을 통해 첨단 훈련기에 대한 추가적인 수요가 발생하고 있습니다. 이는 군 조직이 점점 더 고도화되는 항공기로의 전환을 지원할 수 있는 최신 조종사 훈련 플랫폼을 요구하고 있기 때문입니다. 이러한 동향으로 인해 작전 준비 태세를 향상시키고, 조종사의 기술을 높이며, 진화하는 항공 요건에 대응할 수 있는 기술적으로 선진적인 훈련 시스템에 대한 수요가 강해지고 있습니다.
2025년에는 고정익 훈련기 부문이 시장 점유율의 90.3%를 차지했습니다. 이러한 주도적 지위는 군 조직과 민간 비행 훈련 기관 모두에 서비스를 제공하는 기초, 중급 및 상급 조종사 훈련 프로그램에서의 광범위한 도입에 의해 뒷받침되고 있습니다. 낮은 운영 비용, 연장된 항속 시간, 첨단 디지털 항공 전자 장비, 그리고 통합된 시뮬레이션 기능 덕분에 고정익 훈련기는 전 세계의 대규모 조종사 훈련 및 항공기 함대 현대화 이니셔티브에서 계속해서 최적의 선택지로 자리 잡고 있습니다.
리드인 파이터 트레이너(LIFT) 부문은 2025년에 14억 달러에 달했습니다. 이 부문 수요는 고도로 정교한 훈련 환경을 통해 조종사들이 첨단 전투기 탑승에 대비할 수 있도록 준비시키는 중요한 역할에 힘입어 견인되고 있습니다. 최신 LIFT 플랫폼에는 첨단 항공전자 장비, 플라이-바이-와이어 기술, 통합 전술 시뮬레이션 및 임무 시스템이 통합되어 있어, 기초 비행 교육에서 실전 전투 준비 태세로 효율적으로 전환할 수 있게 해줍니다. 군사 현대화 노력의 확대와 조종사 양성 프로그램에 대한 지속적인 투자로 인해, 예측 기간 동안 리드-인 전투기 훈련기에 대한 견조한 수요가 유지될 것으로 예측됩니다.
2025년, 북미 훈련기 시장은 22.4%의 점유율을 차지했습니다. 지역적 성장은 진행 중인 방위 장비 현대화 이니셔티브, 차세대 조종사 훈련 프로그램에 대한 투자 확대, 그리고 최신 훈련 기술을 탑재한 첨단 훈련기의 조달 증가에 힘입고 있습니다. 업계의 강력한 역량, 디지털 훈련 환경에 대한 지속적인 투자, 시뮬레이션 기반 교육의 확대 활용은 조종사 양성을 강화하는 동시에 지역 전체의 장기적인 항공 전력 구축을 뒷받침하고 있습니다. 이러한 요인들은 세계 훈련기 산업에서 북미의 위상을 계속해서 공고히 하고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법과 범위
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 규모 및 예측 : 항공기 유형별(2022-2035년)
제6장 시장 규모 및 예측 : 트레이닝 단계별(2022-2035년)
제7장 시장 규모 및 예측 : 좌석 구성별(2022-2035년)
제8장 시장 규모 및 예측 : 최종 사용자별(2022-2035년)
제9장 시장 규모 및 예측 : 지역별(2022-2035년)
제10장 기업 개요
KTH 26.08.20The Global Trainer Aircraft Market was valued at USD 4.3 billion in 2025 and is estimated to grow at a CAGR of 6.8% to reach USD 8.4 billion by 2035.
Growth across the trainer aircraft industry is driven by the increasing global shortage of qualified pilots, rising defense modernization initiatives, expanding domestic procurement of trainer aircraft, and the growing integration of advanced digital technologies and simulation-based learning into pilot training programs. Public and private investments aimed at strengthening pilot training infrastructure and expanding aviation academies are also creating favorable conditions for market growth. In addition, increasing demand for highly skilled flight personnel across both military and commercial aviation sectors is encouraging governments and aviation organizations to enhance training capabilities through modern aircraft platforms. Continuous advancements in avionics, digital flight systems, and simulation technologies are improving training efficiency while reducing operational costs and enhancing pilot readiness. As aviation activity continues to expand worldwide, investments in next-generation training solutions are expected to accelerate, reinforcing long-term demand for advanced trainer aircraft and supporting sustained growth across the global trainer aircraft market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $4.3 Billion |
| Forecast Value | $8.4 Billion |
| CAGR | 6.8% |
The global trainer aircraft industry continues to benefit from the growing need to address pilot shortages while improving flight training capacity for military and civil aviation. Aviation authorities are supporting the expansion of flight training infrastructure and increasing the number of approved training organizations to prepare for future workforce requirements. At the same time, defense modernization programs are creating additional opportunities for advanced trainer aircraft as military organizations seek modern pilot training platforms capable of supporting the transition to increasingly sophisticated aircraft. These developments are strengthening demand for technologically advanced training systems that improve operational readiness, enhance pilot proficiency, and support evolving aviation requirements.
The fixed-wing trainer aircraft segment accounted for 90.3% share in 2025. Its leadership is supported by widespread deployment across basic, intermediate, and advanced pilot training programs serving both military organizations and commercial flight training institutions. Lower operating costs, extended operational endurance, advanced digital avionics, and integrated simulation capabilities continue to make fixed-wing trainer aircraft the preferred choice for large-scale pilot training and fleet modernization initiatives around the world.
The lead-in fighter trainer (LIFT) segment reached USD 1.4 billion in 2025. Demand for this segment is being driven by its critical role in preparing pilots for advanced combat aircraft through highly sophisticated training environments. Modern LIFT platforms incorporate advanced avionics, fly-by-wire technology, integrated tactical simulation, and mission systems that enable efficient progression from foundational flight instruction to operational combat readiness. Increasing military modernization efforts and continued investment in pilot development programs are expected to sustain strong demand for lead-in fighter trainer aircraft throughout the forecast period.
North America Trainer Aircraft Market accounted for a 22.4% share in 2025. Regional growth is being supported by ongoing defense recapitalization initiatives, rising investment in next-generation pilot training programs, and increasing procurement of advanced trainer aircraft equipped with modern training technologies. Strong industry capabilities, continued investment in digital training environments, and expanding use of simulation-based instruction are enhancing pilot preparation while supporting long-term aviation readiness across the region. These factors continue to reinforce North America's position within the global trainer aircraft industry.
Leading companies operating in the global trainer aircraft market include Aero Vodochody Aerospace, BAE Systems plc, Cirrus Aircraft, Diamond Aircraft Industries, Embraer Defense & Security, Evektor-Aerotechnik a.s., Grob Aircraft SE, Hongdu Aviation Industry Group Co., Ltd., Korea Aerospace Industries (KAI), Leonardo S.p.A., Pakistan Aeronautical Complex (PAC), Pilatus Aircraft Ltd., Piper Aircraft Inc., Tecnam S.r.l., Textron Aviation (Cessna brand), Textron Aviation Defense (Textron Inc.), The Boeing Company, Turkish Aerospace Industries (TAI), and Vulcanair S.p.A. Companies operating in the trainer aircraft industry are strengthening their market position through continuous investment in advanced aircraft technologies, digital training capabilities, and product innovation. Manufacturers are focusing on integrating next-generation avionics, simulation systems, and mission training technologies to improve pilot training effectiveness while reducing operational costs. Strategic partnerships with defense organizations, aviation academies, and government agencies are enabling companies to expand market reach and secure long-term procurement opportunities. Businesses are also investing in research and development, manufacturing modernization, and after-sales support services to enhance product reliability and customer satisfaction.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Aircraft type trends
- 2.2.2 Training stage trends
- 2.2.3 Seat configuration trends
- 2.2.4 End-user trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising global pilot shortage and expansion of flight training capacity
- 3.2.1.2 Increasing defense modernization and military pilot training programs
- 3.2.1.3 Growing procurement of indigenous trainer aircraft under national aerospace initiatives
- 3.2.1.4 Integration of advanced simulation, digital avionics, and Live-Virtual-Constructive (LVC) training
- 3.2.1.5 Expansion of public-private flight training partnerships and next-generation pilot academies
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High acquisition and lifecycle costs of advanced trainer aircraft
- 3.2.2.2 Lengthy certification, procurement, and defense acquisition cycles
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of AI-enabled simulation and Live-Virtual-Constructive (LVC) pilot training
- 3.2.3.2 Growing demand for trainer aircraft across emerging aviation markets
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Aircraft Type, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Fixed-wing trainer aircraft
- 5.3 Rotary-wing trainer aircraft
Chapter 6 Market Estimates and Forecast, By Training Stage, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Primary trainer
- 6.3 Basic trainer
- 6.4 Intermediate/advanced trainer
- 6.5 Lead-in fighter trainer (LIFT)
Chapter 7 Market Estimates and Forecast, By Seat Configuration, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Single seat
- 7.3 Two seat
- 7.4 Multi-crew (3 or More Seats)
Chapter 8 Market Estimates and Forecast, By End-User, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Military & Defense
- 8.3 Civil flight training organizations
- 8.4 Government civil aviation agencies
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Pilatus Aircraft Ltd.
- 10.1.2 Leonardo S.p.A.
- 10.1.3 Hongdu Aviation Industry Group Co., Ltd.
- 10.1.4 Korea Aerospace Industries (KAI)
- 10.1.5 Embraer Defense & Security
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 The Boeing Company
- 10.2.1.2 BAE Systems plc
- 10.2.1.3 Cirrus Aircraft
- 10.2.1.4 Piper Aircraft Inc.
- 10.2.1.5 Textron Aviation (Cessna brand)
- 10.2.2 Asia Pacific
- 10.2.2.1 Pakistan Aeronautical Complex (PAC)
- 10.2.3 Europe
- 10.2.3.1 Aero Vodochody Aerospace
- 10.2.3.2 Diamond Aircraft Industries
- 10.2.3.3 Evektor-Aerotechnik a.s.
- 10.2.3.4 Tecnam S.r.l.
- 10.2.3.5 Turkish Aerospace Industries (TAI)
- 10.2.3.6 Vulcanair S.p.A.
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 Grob Aircraft SE
- 10.3.2 Textron Aviation Defense (Textron Inc.)