

|
시장보고서
상품코드
2109266
터널 자동화 시장 : 시장 비즈니스 기회, 성장요인, 업계 동향 분석 및 예측(2026-2035년)Tunnel Automation Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 터널 자동화 시장은 2025년에 51억 달러 규모로 평가되었고, CAGR 8.2%로 성장할 전망이며, 2035년까지 112억 달러에 이를 것으로 추정되고 있습니다.

주요 경제권에서 각국 정부가 지하 교통 인프라에 대한 막대한 투자를 지속하고 있어, 터널 자동화 업계는 성장세를 보이고 있습니다. 신규 터널 건설에 대한 지출 증가와 기존 인프라의 현대화가 맞물리면서, 장기적으로 첨단 자동화 기술에 대한 지속적인 수요가 창출되고 있습니다. 노후화된 터널 네트워크에서는 진화하는 운영 및 안전 요건을 준수하기 위해 전기, 통신, 감시, 제어 시스템의 종합적인 업그레이드가 필요하며, 이는 시장 성장을 더욱 가속화하고 있습니다. 또한, 인프라 규제의 강화와 운영 효율성에 대한 기대감 고조로 인해 터널 운영 사업자들은 신뢰성과 시스템 성능을 향상시키는 첨단 자동화 솔루션 도입을 촉진하고 있습니다. 디지털 기술과 지능형 감시 시스템의 지속적인 발전은 예방 정비 및 자산 관리 개선을 지원할 뿐만 아니라, 보다 효율적인 터널 운영을 가능하게 하고 있습니다. 또한, 첨단 센싱 기술 및 통합형 자동화 플랫폼의 도입 확대는 인프라의 회복력을 강화하고 운영 전반의 안전성을 향상시키고 있습니다. 이러한 요인과 장기적인 인프라 투자가 맞물려, 예측 기간 동안 전 세계 터널 자동화 시장이 꾸준히 확대될 것으로 전망됩니다.
| 시장 범위 | |
|---|---|
| 개시 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 개시 연도 시장 규모 | 51억 달러 |
| 예측액 | 112억 달러 |
| CAGR | 8.2% |
규제 준수는 터널 자동화 시장 전체의 구매 결정을 좌우하는 데 있어 계속해서 중요한 역할을 하고 있습니다. 정교하고 내구성이 뛰어나며 비용 효율적인 센싱 기술이 점점 더 널리 이용 가능해짐에 따라, 인프라 운영 사업자는 설치 비용을 절감하면서도 보다 종합적인 모니터링 시스템을 도입할 수 있게 되었습니다. 지능형 모니터링 장비의 지속적인 개선을 통해 운영 상황의 가시성이 향상되고, 사고의 조기 감지가 촉진되며, 터널 전반의 안전성이 향상되고 있습니다. 또한, 커넥티드 자동화 기술의 보급으로 인해 보다 효율적인 인프라 관리와 시스템 성능 최적화가 가능해졌습니다.
하드웨어 부문은 2025년에 55%의 점유율을 차지한 것으로 평가되었으며, 2026-2035년 연평균 성장률(CAGR) 6.7%로 성장할 것으로 전망됩니다. 하드웨어는 여전히 터널 자동화 시스템의 핵심 구성 요소로서, 센싱, 제어, 통신, 전력 관리 및 생명 안전 기능에 필요한 필수 인프라를 제공합니다. 이 부문에는 감시, 자동화, 배전, 조명, 비상 대응, 통신 및 운영 제어를 지원하도록 설계된 장비가 포함되어 있으며, 현대 터널 인프라에 없어서는 안 될 존재가 되었습니다.
고속도로 및 일반 도로 터널 부문은 2025년에 42.7%의 점유율을 차지했으며, 터널 자동화 산업에서 가장 큰 용도 분야로 자리매김하고 있습니다. 광범위한 교통 터널 인프라는 교통 관리, 환기, 조명, 감시, 비상 통신, 전력 관리 및 중앙 집중식 운영 제어를 개선하는 통합형 자동화 솔루션에 대한 수요를 지속적으로 견인하고 있습니다. 교통 인프라 현대화를 위한 투자 증가로 인해 이 부문 전체 수요는 더욱 강화될 것으로 예측됩니다.
중국 터널 자동화 시장은 57%의 점유율을 차지했으며, 2025년에는 13억 달러 시장 규모를 기록했습니다. 중국은 교통, 유틸리티, 철도, 지하철, 지하 인프라 개발에 대한 지속적인 투자에 힘입어 여전히 최대의 지역 시장이자 세계에서 가장 빠르게 성장하는 시장 중 하나입니다. 터널 네트워크의 지속적인 확장과 급속한 도시 인프라 개발로 인해, 운영 효율성, 안전성, 감시, 통신 및 통합 인프라 관리를 향상시키는 첨단 자동화 기술에 대한 수요는 계속해서 증가하고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 추산 및 예측 : 제공별(2022-2035년)
제6장 시장 추산 및 예측 : 컴포넌트별(2022-2035년)
제7장 시장 추산 및 예측 : 터널별(2022-2035년)
제8장 시장 추산 및 예측 : 자동화 레벨별(2022-2035년)
제9장 시장 추산 및 예측 : 용도별(2022-2035년)
제10장 시장 추산 및 예측 : 지역별(2022-2035년)
제11장 기업 개요
AJY 26.08.18The Global Tunnel Automation Market was valued at USD 5.1 billion in 2025 and is estimated to grow at a CAGR of 8.2% to reach USD 11.2 billion by 2035.
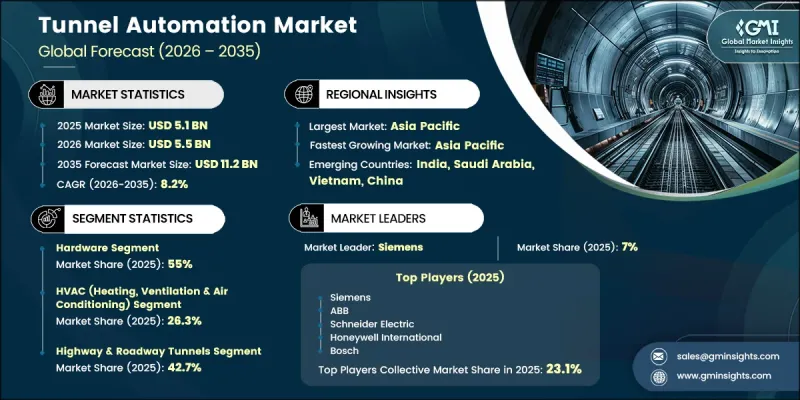
The tunnel automation industry is experiencing momentum as governments continue investing heavily in underground transportation infrastructure across major economies. Increasing expenditure on new tunnel construction, combined with the modernization of existing infrastructure, is creating sustained demand for advanced automation technologies over the long term. Aging tunnel networks require comprehensive upgrades to electrical, communication, monitoring, and control systems to comply with evolving operational and safety requirements, further accelerating market growth. In addition, stricter infrastructure regulations and higher expectations for operational efficiency are encouraging tunnel operators to adopt advanced automation solutions that improve reliability and system performance. Continuous advancements in digital technologies and intelligent monitoring systems are enabling more efficient tunnel operations while supporting preventive maintenance and improved asset management. The growing deployment of advanced sensing technologies and integrated automation platforms is also strengthening infrastructure resilience and enhancing overall operational safety. These factors, together with long-term infrastructure investments, are expected to support consistent expansion of the global tunnel automation market throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.1 Billion |
| Forecast Value | $11.2 Billion |
| CAGR | 8.2% |
Regulatory compliance continues to play a significant role in shaping purchasing decisions across the tunnel automation market. The increasing availability of advanced, durable, and cost-effective sensing technologies is allowing infrastructure operators to deploy more comprehensive monitoring systems while reducing installation costs. Continuous improvements in intelligent monitoring equipment are enhancing operational visibility, supporting faster incident detection, and improving overall tunnel safety. The widespread adoption of connected automation technologies is also enabling more efficient infrastructure management and optimized system performance.
The hardware segment accounted for a 55% share in 2025 and is expected to grow at a CAGR of 6.7% from 2026 to 2035. Hardware remains the core component of tunnel automation systems, providing the essential infrastructure required for sensing, control, communication, power management, and life-safety functions. This segment includes equipment designed to support monitoring, automation, electrical distribution, lighting, emergency response, communication, and operational control, making it fundamental to modern tunnel infrastructure.
The highway and roadway tunnels segment held a 42.7% share in 2025, making it the largest application segment within the tunnel automation industry. Extensive transportation tunnel infrastructure continues to drive demand for integrated automation solutions that improve traffic management, ventilation, lighting, surveillance, emergency communications, power management, and centralized operational control. Increasing investments in transportation infrastructure modernization are expected to further strengthen demand across this segment.
China Tunnel Automation Market accounted for a 57% share, generating USD 1.3 billion in 2025. The country remains the largest regional market and one of the fastest-growing markets globally, supported by continuous investments in transportation, utility, railway, metro, and underground infrastructure development. Ongoing expansion of tunnel networks and rapid urban infrastructure development continue to increase demand for advanced automation technologies that enhance operational efficiency, safety, monitoring, communications, and integrated infrastructure management.
Major companies operating in the global tunnel automation market include Siemens, ABB, Schneider Electric, Honeywell International, Bosch, Kapsch TrafficCom, Indra Sistemas, Eaton Corporation, Rockwell Automation, and FlaktGroup. Companies operating in the tunnel automation market are strengthening their competitive position through continuous investments in digital technologies, automation platforms, and intelligent infrastructure solutions. Manufacturers are expanding their product portfolios by developing advanced monitoring, communication, and control systems that improve operational efficiency and infrastructure safety. Many companies are increasing research and development investments to enhance system integration, real-time data analytics, and predictive maintenance capabilities. Strategic partnerships with infrastructure developers, transportation authorities, and engineering firms are also helping businesses expand their project pipelines and regional presence. In addition, companies are focusing on software integration, energy-efficient technologies, lifecycle service offerings, and customized automation solutions to address evolving customer requirements.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Offering
- 2.2.3 Component
- 2.2.4 Tunnel
- 2.2.5 Automation Level
- 2.2.6 Application
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Surge in Global Tunnel Infrastructure Investment
- 3.2.1.2 Stringent Government Safety Mandates Driving System Integration Across Tunnel Types
- 3.2.1.3 Rising Adoption of IoT, SCADA, & Edge Computing in Tunnel Operations
- 3.2.1.4 Energy Efficiency Imperatives & Sustainability Targets Among Tunnel Operators
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Upfront Capital Expenditure for Full Automation System Deployment
- 3.2.2.2 Complex Integration Challenges with Aging & Legacy Tunnel Infrastructure
- 3.2.3 Market opportunities
- 3.2.3.1 Untapped Automation Potential in Utility, Water & Mining Tunnel Segments
- 3.2.3.2 AI-Powered Predictive Maintenance as a Value-Added Services Growth Lever
- 3.2.3.3 Retrofitting Demand from Decades-Old European & North American Tunnel Networks
- 3.2.3.4 Public-Private Partnership Models Unlocking Capital for Emerging Market Tunnels
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by primary research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 U.S. National Tunnel Inspection Standards
- 3.6.1.2 NFPA 502 Standard for Road Tunnels, Bridges, and Other Limited Access Highways
- 3.6.1.3 NIST SP 800-82 Rev. 3 Guide to Operational Technology Security
- 3.6.1.4 Canada International Bridges and Tunnels Act
- 3.6.1.5 Canada Railway Safety Act and Passenger Rail Security Regulations
- 3.6.2 Europe
- 3.6.2.1 Directive 2004/54/EC on Minimum Safety Requirements for Tunnels in the Trans-European Road Network
- 3.6.2.2 Safety in Railway Tunnels Technical Specification for Interoperability
- 3.6.2.3 EU Intelligent Transport Systems Directive
- 3.6.2.4 Network and Information Security Directive 2
- 3.6.2.5 EU Cyber Resilience Act
- 3.6.3 Asia Pacific
- 3.6.3.1 China JTG D70/2-2014 Highway Tunnel Design Standard
- 3.6.3.2 China Highway Tunnel Maintenance Standards
- 3.6.3.3 Japan Road Structure Ordinance Tunnel Requirements
- 3.6.3.4 Japan Technical Regulatory Standards on Railways
- 3.6.3.5 Singapore Code of Practice for Fire Precautions in Road Tunnels
- 3.6.3.6 Singapore Code of Practice for Fire Precautions in Rapid Transit Systems
- 3.6.3.7 India Metro Railways General Rules and Underground Metro Safety Requirements
- 3.6.4 Latin America
- 3.6.4.1 Brazil ABNT NBR 15661 Fire Protection in Road and Urban Tunnels
- 3.6.4.2 Brazil ABNT NBR 5181 Tunnel Lighting
- 3.6.4.3 Mexico Manual for the Design and Construction of Road Tunnels
- 3.6.4.4 Mexico Intelligent Road Tunnel and Control Centre Standards
- 3.6.4.5 Chile Ministry of Public Works Road Tunnel Safety and Concession Requirements
- 3.6.5 Middle East & Africa
- 3.6.5.1 UAE Fire and Life Safety Code of Practice
- 3.6.5.2 UAE Information Assurance Regulation
- 3.6.5.3 Saudi Operational Technology Cybersecurity Controls
- 3.6.5.4 Saudi Critical Systems Cybersecurity Controls
- 3.6.5.5 South Africa Mine Health and Safety Act and Regulations
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by primary research)
- 3.9.1 Patent Filing Trends by Technology Area (HVAC Automation, Fire Detection, Signalization)
- 3.9.2 Leading Patent Holders & Innovation Concentration
- 3.10 Cost breakdown analysis
- 3.11 Impact of AI and Generative AI on the Market
- 3.11.1 AI Driven Disruption of Existing Business Models
- 3.11.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.11.3 Risks Limitations and Regulatory Considerations
- 3.12 Capacity & Production Landscape (Driven by Primary Research)
- 3.12.1 Installed Production Capacity by Region & Key Manufacturer
- 3.12.2 Capacity Utilization Rates & Expansion Pipelines Among Leading Suppliers
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.13.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Offering, 2022 - 2035 (USD Bn)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 Sensors & Detectors
- 5.2.2 Actuators & Controllers
- 5.2.3 Control Panels & HMI Units
- 5.2.4 Cameras & Imaging Devices
- 5.3 Software
- 5.3.1 SCADA & Tunnel Management Platforms
- 5.3.2 AI-Based Analytics & Decision Support Software
- 5.3.3 Cybersecurity & OT Security Software
- 5.3.4 Asset Management & Maintenance Software
- 5.4 Services
- 5.4.1 Professional Services
- 5.4.2 Managed Services
Chapter 6 Market Estimates & Forecast, By Component, 2022 - 2035 (USD Bn)
- 6.1 Key trends
- 6.2 HVAC (Heating, Ventilation & Air Conditioning)
- 6.3 Lighting & Power Supply
- 6.4 Signalization
- 6.5 Fire Detection & Suppression
- 6.6 Surveillance & Monitoring
- 6.7 Communication Systems
- 6.8 Others
Chapter 7 Market Estimates & Forecast, By Tunnel, 2022 - 2035 (USD Bn)
- 7.1 Key trends
- 7.2 Railway Tunnels
- 7.3 Highway & Roadway Tunnels
- 7.4 Utility & Water Tunnels
- 7.5 Mining Tunnels
Chapter 8 Market Estimates & Forecast, By Automation Level, 2022 - 2035 (USD Bn)
- 8.1 Key trends
- 8.2 Semi-Automated
- 8.3 Fully-Automated
Chapter 9 Market Estimates & Forecast, By Application, 2022 - 2035 (USD Bn)
- 9.1 Key trends
- 9.2 Traffic Management
- 9.3 Safety & Security & Monitoring
- 9.4 Ventilation & Environmental Control
- 9.5 Communication & Operations Management
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 (USD Bn)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Russia
- 10.3.7 Norway
- 10.3.8 Netherlands
- 10.3.9 Sweden
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.4.6 Singapore
- 10.4.7 Thailand
- 10.4.8 Indonesia
- 10.4.9 Vietnam
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
- 10.6.4 Turkey
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.1.1 Siemens AG
- 11.1.2 ABB Ltd.
- 11.1.3 Schneider Electric SE
- 11.1.4 Honeywell International Inc.
- 11.1.5 Bosch Security Systems
- 11.1.6 Johnson Controls International plc
- 11.1.7 Eaton Corporation plc
- 11.1.8 Rockwell Automation Inc.
- 11.1.9 FlaktGroup
- 11.1.10 Systemair AB
- 11.1.11 SICK AG
- 11.1.12 Phoenix Contact GmbH & Co. KG
- 11.1.13 Egis Group
- 11.1.14 Parsons Corporation
- 11.1.15 Indra Sistemas S.A.
- 11.2 Regional Players
- 11.2.1 China Railway Signal & Communication Corporation
- 11.2.2 CASCO Signal Ltd.
- 11.2.3 Kapsch TrafficCom AG
- 11.2.4 SWARCO AG
- 11.2.5 Q-Free ASA


