

|
시장보고서
상품코드
2109292
산업용 집진기 시장 : 시장 기회, 성장요인, 업계 동향 분석 및 예측(2026-2035년)Industrial Dust Collector Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 산업용 집진기 시장은 2025년에 47억 달러 규모로 평가되었고, CAGR 5.1%로 성장할 전망이며, 2035년까지 78억 달러에 이를 것으로 예측됩니다.
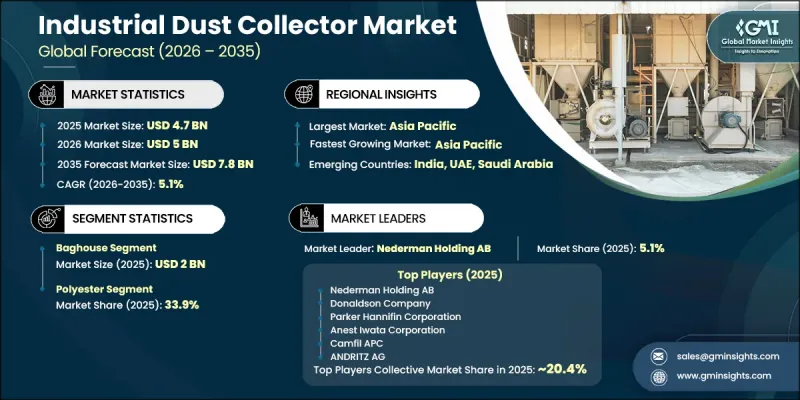
더 깨끗한 생산 환경과 작업장 안전성 향상에 대한 수요가 증가함에 따라, 다양한 산업 분야에서 산업용 집진 시스템 도입이 가속화되고 있습니다. 각 조직은 환경 규제 준수는 물론, 공기질 개선, 근로자 보호, 설비 마모 감소, 그리고 전반적인 업무 효율 향상을 도모하기 위해 첨단 분진 관리 기술에 대한 투자를 점점 더 늘리고 있습니다. 제조 시설의 현대화가 진행됨에 따라 기업들은 노후화된 여과 시스템을 더 높은 신뢰성, 간소화된 유지보수, 그리고 성능 향상을 실현하는 첨단 집진 설비로 교체하고 있습니다. 자동화 및 스마트 제조 기술의 도입 확대는 집진 시스템의 지속적인 모니터링, 실시간 성능 분석, 예측 유지보수를 가능하게 함으로써 시장 성장을 더욱 가속화하고 있습니다. 이러한 지능형 기능은 예기치 못한 가동 중지 시간을 최소화하면서 생산 효율 향상에 기여합니다. 지속 가능한 산업 운영, 설비 보호 및 장기적인 비용 최적화에 대한 중요성이 커짐에 따라, 첨단 집진 솔루션에 대한 수요는 계속해서 증가하고 있으며, 이는 예측 기간 동안 전 세계 산업용 집진기 시장의 꾸준한 성장을 뒷받침하고 있습니다.
| 시장 범위 | |
|---|---|
| 개시 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 초기 시장 규모 | 47억 달러 |
| 예측액 | 78억 달러 |
| CAGR | 5.1% |
백하우스 부문은 2025년에 20억 달러의 매출을 기록했습니다. 이 부문은 대량의 집진 요구 사항을 효율적으로 충족시키면서 신뢰성 높은 장기 여과 성능을 발휘할 수 있어 계속해서 지배적인 위치를 유지하고 있습니다. 내구성, 운영 효율성 및 지속적인 산업 운영에 대한 적응성 덕분에 수많은 가공 산업 분야에서 널리 채택되고 있습니다.
폴리에스터 부문은 2025년에 33.9%의 점유율을 기록하며, 필터 매체 유형 중 가장 큰 점유율을 차지했습니다. 폴리에스터 필터 매체는 비용 효율성, 범용성, 그리고 확립된 세계 공급망 덕분에 계속해서 널리 채택되고 있습니다. 광범위한 산업용 가동 조건에 대한 적합성과 방대한 도입 실적이 교체용 필터 미디어 및 신규 설비 도입 모두에 대한 견고한 수요를 지속적으로 뒷받침하고 있습니다.
미국 산업용 집진기 시장은 86.8%의 점유율을 차지하며, 2025년에는 17억 달러 규모 시장을 기록했습니다. 미국의 선도적 지위는 대규모 산업 생산 기반, 선진적인 생산 인프라, 그리고 산업용 대기질을 규제하는 엄격한 환경 기준에 의해 뒷받침되고 있습니다. 시설 현대화, 배기가스 제어 기술, 그리고 고성능 공기 여과 시스템에 대한 지속적인 투자가 여러 산업 분야에서 산업용 집진 장비에 대한 수요를 더욱 촉진하고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 추산 및 예측 : 컬렉터 유형별(2022-2035년)
제6장 시장 추산 및 예측 : 필터 세정 방법별(2022-2035년)
제7장 시장 추산 및 예측 : 필터 매체별(2022-2035년)
제8장 시장 추산 및 예측 : 모빌리티별(2022-2035년)
제9장 시장 추산 및 예측 : 최종 용도별(2022-2035년)
제10장 시장 추산 및 예측 : 유통 채널별(2022-2035년)
제11장 시장 추산 및 예측 : 지역별(2022-2035년)
제12장 기업 개요
AJY 26.08.18The Global Industrial Dust Collector Market was valued at USD 4.7 billion in 2025 and is estimated to grow at a CAGR of 5.1% to reach USD 7.8 billion by 2035.
Rising demand for cleaner production environments and improved workplace safety is driving the adoption of industrial dust collection systems across a wide range of industries. Organizations are increasingly investing in advanced dust management technologies not only to comply with environmental regulations but also to improve air quality, protect workers, reduce equipment wear, and enhance overall operational efficiency. As manufacturing facilities continue to modernize, companies are replacing aging filtration systems with advanced dust collection equipment that delivers higher reliability, simplified maintenance, and improved performance. The growing implementation of automation and smart manufacturing technologies is further accelerating market growth by enabling continuous monitoring, real-time performance analysis, and predictive maintenance of dust collection systems. These intelligent capabilities help minimize unexpected downtime while improving production efficiency. Increasing emphasis on sustainable industrial operations, equipment protection, and long-term cost optimization continues to strengthen demand for advanced dust collection solutions, supporting steady expansion of the global industrial dust collector market throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $4.7 Billion |
| Forecast Value | $7.8 Billion |
| CAGR | 5.1% |
The baghouse segment generated USD 2 billion in 2025. The segment continues to maintain its dominant position because of its ability to efficiently handle high-volume dust collection requirements while delivering reliable long-term filtration performance. Its durability, operational efficiency, and suitability for continuous industrial operations continue to support widespread adoption across numerous processing industries.
The polyester segment accounted for a 33.9% share in 2025, representing the largest share among filter media types. Polyester filter media remains widely adopted because of its cost-effectiveness, versatility, and well-established global supply chain. Its compatibility with a broad range of industrial operating conditions and extensive installed base continues to support strong demand for both replacement filter media and new equipment installations.
United States Industrial Dust Collector Market held an 86.8% share, generating USD 1.7 billion in 2025. The country's leadership is supported by its large industrial manufacturing base, advanced production infrastructure, and stringent environmental standards governing industrial air quality. Continuous investments in facility modernization, emissions control technologies, and high-performance air filtration systems continue to reinforce demand for industrial dust collection equipment across multiple industrial sectors.
Key players operating in the global industrial dust collector market include Donaldson Company, Inc., Parker Hannifin Corporation, Camfil Group, Nederman Holding AB, CECO Environmental Corp., AAF International (Daikin Group), ANDRITZ AG, Thermax Limited, KC Cottrell Co., Ltd., Intensiv-Filter Himenviro, Babcock & Wilcox Enterprises, Inc., Qlar Group, Zhejiang Feida Environmental Science & Technology Co., Ltd., Scheuch GmbH, Imperial Systems, Inc., RoboVent, Ducon Technologies Inc., Airflow Systems, Inc., Baghouse America, Inc., Teldust A/S, and Sly, Inc. Companies operating in the industrial dust collector market are strengthening their market position by investing in advanced filtration technologies, intelligent monitoring systems, and energy-efficient dust collection equipment. Manufacturers are expanding research and development activities to improve filtration performance, reduce maintenance requirements, and enhance automation capabilities through connected monitoring and predictive maintenance features. Strategic partnerships with industrial equipment manufacturers, engineering firms, and distribution networks are helping companies expand their customer base and strengthen regional market presence. Businesses are also increasing manufacturing capacity, enhancing aftermarket service offerings, and developing customized solutions for diverse industrial applications.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry snapshot
- 2.2 Business trends
- 2.3 Collector type trends
- 2.4 Filter cleaning method trends
- 2.5 Filter media trends
- 2.6 Mobility trends
- 2.7 End-use trends
- 2.8 Distribution channel trends
- 2.9 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem and value chain analysis
- 3.1.1 Raw material & component suppliers
- 3.1.2 Manufacturers & OEMs
- 3.1.3 Distributors & system integrators
- 3.1.4 End-user industries
- 3.1.5 Aftermarket & MRO service providers
- 3.1.6 Profit margin analysis by value chain node
- 3.1.7 Disruptions & future outlook
- 3.2 Industry impact forces
- 3.2.1 Market Driver
- 3.2.2 Market challenges/pitfalls
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Industry ecosystem analysis
- 3.5 Regulatory framework
- 3.5.1 U.S. regulations (OSHA PEL, NESHAP, EPA Clean Air Act)
- 3.5.2 EU directives (IED, ATEX, CE marking requirements)
- 3.5.3 Asia Pacific regulations (China GB standards, India CPCB norms)
- 3.5.4 Emerging market regulatory trends
- 3.6 Pricing analysis (driven by primary research)
- 3.6.1 Historical price trend analysis (2022–2024) (driven by primary research)
- 3.6.2 Pricing strategy by player type (premium / value / cost-plus) (driven by primary research)
- 3.7 Technology and innovation landscape
- 3.7.1 IoT-enabled & smart dust collection systems
- 3.7.2 Nanofiber & advanced filter media technologies
- 3.7.3 Energy-efficient motor & drive systems
- 3.7.4 Modular & scalable system architecture
- 3.8 Porter’s Analysis
- 3.9 PESTEL Analysis
- 3.10 Trade data analysis (driven by primary research)
- 3.10.1 Import/export volume & value trends (HS code 8421)
- 3.10.2 Key trade corridors & tariff impact
- 3.11 Impact of AI and generative AI on the market
- 3.11.1 AI-driven disruption of existing business models (predictive maintenance, remote diagnostics)
- 3.11.2 GenAI use cases & adoption roadmap by segment (filter life prediction, efficiency optimization)
- 3.11.3 Risks, limitations & regulatory considerations of AI integration
- 3.12 Capacity & production landscape (driven by primary research)
- 3.12.1 Installed manufacturing capacity by region & key producer (driven by primary research)
- 3.12.2 Capacity utilization rates & expansion pipelines (driven by primary research)
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 APAC
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Collector Type, 2022 – 2035 ($ Billion) (Thousand Units)
- 5.1 Key trends
- 5.2 Baghouse dust collectors
- 5.2.1 Woven filter baghouse
- 5.2.2 Non-woven filter baghouse
- 5.3 Cartridge dust collectors
- 5.3.1 Standard cartridge
- 5.3.2 High-efficiency cartridge (HEPA-grade)
- 5.4 Cyclone & inertial separators
- 5.4.1 Single-cyclone
- 5.4.2 Multi-cyclone
- 5.4.3 Gravity/baffle inertial separators
- 5.5 Electrostatic precipitators (ESP)
- 5.5.1 Dry ESP
- 5.5.2 Wet ESP
- 5.6 Wet scrubbers
- 5.6.1 Venturi scrubbers
- 5.6.2 Packed bed scrubbers
- 5.7 Others (modular/centralized systems)
Chapter 6 Market Estimates and Forecast, By Filter Cleaning Method, 2022 – 2035 ($ Billion) (Thousand Units)
- 6.1 Key trends
- 6.2 Pulse-jet cleaning
- 6.3 Reverse air cleaning
- 6.4 Shaker/vibration cleaning
- 6.5 Sonic/acoustic cleaning
Chapter 7 Market Estimates and Forecast, By Filter Media, 2022 – 2035 ($ Billion) (Thousand Units)
- 7.1 Key trends
- 7.2 Polyester
- 7.2.1 Standard polyester (woven & felt)
- 7.2.2 Anti-static polyester
- 7.3 Polypropylene
- 7.3.1 Standard polypropylene
- 7.3.2 Chemical-resistant polypropylene
- 7.4 Fiberglass
- 7.4.1 Standard fiberglass
- 7.4.2 High-temperature fiberglass
- 7.5 PTFE / ePTFE membrane laminate
- 7.6 Aramid & high-temperature specialty media (P84, PPS, Nomex)
- 7.7 Nanofiber composite media (PAN/PP-based sub-micron fiber coatings)
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Mobility, 2022 – 2035 ($ Billion) (Thousand Units)
- 8.1 Key trends
- 8.2 Fixed/stationary
- 8.3 Centralized fixed systems
- 8.4 Modular fixed systems
- 8.5 Portable/mobile
- 8.6 Single-unit portable collectors
- 8.7 Integrated portable workstations
Chapter 9 Market Estimates and Forecast, By End Use, 2022 – 2035 ($ Billion) (Thousand Units)
- 9.1 Key trends
- 9.2 Electronics & semiconductor manufacturing
- 9.3 Metalworking & metal fabrication
- 9.4 Pharmaceuticals
- 9.5 Food & beverage processing
- 9.6 Cement & construction materials
- 9.7 Power generation
- 9.8 Chemical processing
- 9.9 Mining & mineral processing
- 9.10 Woodworking & furniture
- 9.11 Textiles
- 9.12 Automotive & EV battery manufacturing
- 9.13 Others
Chapter 10 Market Estimates and Forecast, By Distribution Channel, 2022 – 2035 ($ Billion) (Thousand Units)
- 10.1 Key trends
- 10.2 Direct sales
- 10.3 Indirect sales
Chapter 11 Market Estimates and Forecast, By Region, 2022 – 2035 ($ Billion) (Thousand Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 US
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 Germany
- 11.3.2 UK
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 India
- 11.4.3 Japan
- 11.4.4 Australia
- 11.4.5 South Korea
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.6 Middle East and Africa
- 11.6.1 South Africa
- 11.6.2 Saudi Arabia
- 11.6.3 UAE
Chapter 12 Company Profiles
- 12.1 Top Global Players
- 12.1.1 Donaldson Company, Inc.
- 12.1.2 Parker Hannifin Corporation
- 12.1.3 Camfil Group
- 12.1.4 Nederman Holding AB
- 12.1.5 CECO Environmental Corp.
- 12.1.6 AAF International (Daikin Group)
- 12.1.7 ANDRITZ AG
- 12.2 Regional Players
- 12.2.1 Thermax Limited
- 12.2.2 KC Cottrell Co., Ltd.
- 12.2.3 Intensiv-Filter Himenviro
- 12.2.4 Babcock & Wilcox Enterprises, Inc.
- 12.2.5 Qlar Group
- 12.2.6 Zhejiang Feida Environmental Science & Technology Co., Ltd.
- 12.2.7 Scheuch GmbH
- 12.3 Niche & Specialist Players
- 12.3.1 Imperial Systems, Inc.
- 12.3.2 RoboVent
- 12.3.3 Ducon Technologies Inc.
- 12.3.4 Airflow Systems, Inc.
- 12.3.5 Baghouse America, Inc.
- 12.3.6 Teldust A/S
- 12.3.7 Sly, Inc.


