|
시장보고서
상품코드
2120870
농업용 미생물 시장 예측(-2031년) : 기능(토양 개량 및 작물 보호), 작물 유형(곡물, 지방 종자 및 두류, 과일 및 채소), 유형(세균, 진균, 바이러스, 원생동물), 용도, 지역별Agricultural Microbials Market by Function (Soil Amendment and Crop Protection), Crop Type (Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables), Type (Bacteria, Fungi, Virus, Protozoa), Application, and Region - Global Forecast To 2031 |
||||||

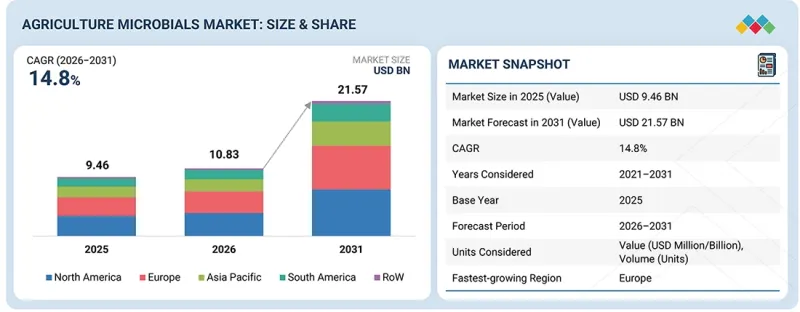
농업용 미생물 시장 규모는 2026년에 108억 3,000만 달러로 추계되며, 2031년에는 215억 7,000만 달러에 달하며, CAGR은 14.8%를 기록할 것으로 예측됩니다.
AI 도입으로 제품 개발, 정밀 시비, 의사결정 프로세스가 강화되면서 농업용 미생물 시장에 혁신이 일어나고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러)·톤 |
| 부문 | 유형, 기능, 형태, 작물 유형, 용도, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 남미, 기타 지역 |
AI 기반 툴와 기계학습 알고리즘은 토양 건강 상태, 기후 패턴, 작물 생육 상황과 같은 방대한 데이터세트를 분석하여 특정 환경에 적합한 최적의 미생물 제제를 파악하는 데 활용되고 있습니다. 이러한 기술은 미생물 제제의 정밀한 시용을 가능하게 하고, 낭비를 줄여 효율을 극대화함으로써 정밀농업도 지원하고 있습니다.
농업용 미생물 시장의 기회와 변화: 농업이 석유 화학을 기반으로 한 기존 생산 시스템에서 지속가능한 생물학적·재생형 농업 시스템으로 전환됨에 따라 농업용 미생물은 전 세계의 생물 유래 작물 자재 기업, 미생물 기술 기업, 생명공학 기업, 정밀농업 제공업체에 큰 성장 기회를 제공하고 있습니다. 농가가 합성 비료와 농약을 대체할 더 효과적인 바이오 기반 대안을 점점 더 요구함에 따라 미생물 관련 기업은 작물의 영양분 이용 효율을 높이고,생물적·비생물적 스트레스 요인에 대한 작물 및 토양의 내성을 높이고, 디지털 정밀농업 툴 및 기술과 통합하는 혁신적인 솔루션을 개발할 여지가 큽니다.
AI를 활용한 미생물 발굴 및 정밀농업: AI 및 기계학습 기술은 미생물 균주의 신속한 탐색, 제제 개발의 최적화, 정밀 시비 능력 향상을 촉진함으로써 농업용 미생물 시장의 활용 방식을 크게 변화시키고 있습니다. 예를 들어 이러한 시스템은 방대한 게놈 데이터, 토양 데이터, 기상 데이터, 작물 생산 데이터를 통합하여 기존 균주와 비교했을 때 더 높은 영양분 용해 능력, 뿌리권 정착 능력, 병해 억제 능력, 스트레스 내성을 보이는 균주를 선별합니다.
첨단 제형 기술: 새롭게 등장한 첨단 제형 기술은 미생물의 생존율과 보존 기간 향상, 포장에서의 안정성 향상, 시용의 용이성을 실현함으로써 농업용 미생물 제품의 시장 수용을 더욱 지원하고 있습니다. 마이크로캡슐화, 액상 제형, 운반체 기반 제형·시스템, 동결건조 기술, 서방형 전달 플랫폼 등의 새로운 혁신을 통해 저장 중 및 밭에서 시용시 유익한 미생물의 저온, 건조, 자외선, 건조에 대한 안정성이 향상됨과 동시에 다양한 기후 조건 하에서의 생존율도 높아지고 있습니다.
"작물 유형별로는 과일·채소 부문이 가장 큰 시장 점유율을 차지하고 있습니다."
이는 고품질이면서 잔류 농약이 적은 농산물에 대한 수요가 확대되고, 지속가능한 농업 방식에 대한 필요성이 높아지고 있기 때문입니다. 바이오 농약, 바이오 살균제, 바이오비료 등의 미생물 솔루션은 합성 화학 물질에 대한 의존을 최소화하면서, 이러한 작물을 해충, 질병, 토양 전염성 병원체로부터 보호하기 위해 점점 더 널리 활용되고 있습니다. 또한 유기농 식품 및 건강 지향 식품에 대한 소비자의 선호도 증가와 잔류 농약에 대한 엄격한 규제도 과일·채소 분야에서 미생물 제품의 채택을 더욱 촉진하고 있습니다. 이러한 작물은 화학 물질 잔류에 매우 민감하므로 친환경 대체제에 대한 수요는 앞으로도 계속 확대될 것으로 예상되며, 농업용 미생물 시장에서 이 부문의 중요성이 더욱 높아질 것으로 전망됩니다.
"예측 기간 중, 용도별로는 종자 처리 부문이 가장 높은 성장률을 보일 것으로 예측됩니다."
종자 처리 부문은 토양 전염병, 해충, 환경 스트레스로부터 종자를 보호하기 위한 효과적이고 지속가능한 솔루션에 대한 수요 증가에 힘입어 가장 높은 성장률을 보일 것으로 예상됩니다. 바이오 살균제 및 바이오 자극제를 포함한 미생물을 이용한 종자 처리는 종자의 발아율 향상, 뿌리 발달 촉진, 생육 초기 활력 증진에 큰 이점을 제공합니다. 농가가 화학 약품 기반의 종자 처리 대신 환경 친화적인 대안을 모색함에 따라 미생물 기반 솔루션은 환경에 미치는 영향을 최소화하면서 더 건강한 작물과 높은 수확량을 지원하는 이상적인 선택지가 될 것입니다.
"아시아태평양이 큰 점유율을 차지할 것으로 예상됩니다."
아시아태평양은 확대되는 농업 부문과 지속가능한 농업 실천에 대한 수요 증가를 배경으로 큰 점유율을 차지할 것으로 예상됩니다. 중국, 인도, 일본 등의 국가에서는 토양 황폐화, 해충의 내성화, 화학 농약 대체를 위한 친환경 대안의 필요성 등의 과제를 해결하기 위해 미생물 솔루션이 도입되고 있습니다. 유기농에 대한 관심 증가, 지속가능한 농업을 위한 정부의 지원, 식품 안전 및 환경 문제에 대한 소비자의 인식 제고가 해당 지역의 시장 확대를 더욱 지원하고 있습니다. 대규모 농업 기반과 농업 혁신에 대한 투자 확대를 배경으로, 아시아태평양은 중요한 역할을 수행할 준비가 되어 있습니다.
이 보고서에서는 전 세계 농업용 미생물 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 각종 요인 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 구상
제8장 고객 상황과 구매 행동
제9장 농업용 미생물 시장 : 기능별
제10장 농업용 미생물 시장 : 유형별
제11장 농업용 미생물 시장 : 용도별
제12장 농업용 미생물 시장 : 제제별
제13장 농업용 미생물 시장 : 작물 유형별
제14장 농업용 미생물 시장 : 지역별
제15장 경쟁 구도
제16장 기업 개요
제17장 조사 방법
제18장 인접 시장 및 관련 시장
제19장 부록
KSA 26.09.07The agricultural microbials market was estimated at USD 10.83 billion in 2026 and is projected to reach USD 21.57 billion by 2031, registering a CAGR of 14.8%. The adoption of artificial intelligence (AI) is transforming the agricultural microbials market by enhancing product development, precision application, and decision-making processes.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD) and Volume (KT) |
| Segments | By Type, Function, Formulation, Crop Type, Application, and Region |
| Regions covered | North America, Europe, Asia Pacific, South America, and RoW |
AI-driven tools and machine learning algorithms are being utilized to analyze vast datasets, such as soil health, climate patterns, and crop conditions, to identify optimal microbial formulations tailored to specific environments. These technologies also support precision agriculture by enabling the targeted application of microbial solutions, reducing waste and maximizing efficiency.

Opportunities and disruption in the agricultural microbials market: Agricultural microbials provide lucrative growth opportunities for biological crop input companies, microbial technology firms, biotech companies, and precision agriculture providers worldwide as agriculture transitions from petrochemical, conventional production systems to sustainable biological, regenerative farm systems. As farmers demand ever more effective bio-based alternatives to synthetic fertilizers and pesticides, there exists a large scope for microbial companies to develop innovative solutions that improve crop nutrient use efficiency, enhance crop and soil resilience to biotic and abiotic stressors, while integrating with digital precision farming tools and techniques.
AI-driven microbial discovery and precision agriculture: Artificial Intelligence and Machine Learning technologies are revolutionizing the agricultural applications of the microbial market by promoting quicker discovery of microbial strains, optimizing formulation development, and improving precision placement capabilities. These systems, for instance, synthesize a myriad of genomic, soil, weather, and crop production data to select strains that demonstrate more efficient mobilization of nutrients, root colonization, disease suppression, and stress tolerance relative to existing stocks.
Advanced formulation technologies: Emerging advanced formulation technologies are further boosting market acceptance of agricultural microbial products by providing improved microbial viability and shelf life, improved field stability, and ease of application. New innovations, including microencapsulation, liquid formulations, carrier-based formulations and systems, freeze-drying technologies, controlled release delivery platforms are improving the cold, dry, UV, and desiccation stability of beneficial microbes during storage and field application while offering better survival under different climatic conditions.
"The fruits & vegetables segment holds the highest market share in the crop type segment of the agricultural microbials market."
Fruits and vegetables hold the largest market share in the crop type segment of the agricultural microbials market, driven by the growing demand for high-quality, residue-free produce and the need for sustainable farming practices. Microbial solutions, such as biopesticides, biofungicides, and biofertilizers, are increasingly used to protect these crops from pests, diseases, and soil-borne pathogens while minimizing the reliance on synthetic chemicals. The rising consumer preference for organic and healthy food options, coupled with stringent regulations on pesticide residues, has further propelled the adoption of microbial products in the fruits and vegetables sector. As these crops are highly sensitive to chemical residues, the demand for eco-friendly alternatives is expected to continue growing, reinforcing the prominence of this segment in the agricultural microbials market.
"The seed treatment segment is projected to grow at the highest rate in the application segment during the forecast period."
The seed treatment application segment is expected to grow at the highest rate in the agricultural microbials market, driven by the increasing demand for effective and sustainable solutions to protect seeds from soil-borne diseases, pests, and environmental stress. Microbial seed treatments, including biofungicides and biostimulants, offer significant advantages in enhancing seed germination, improving root development, and boosting early plant vigor. As farmers seek eco-friendly alternatives to chemical-based seed treatments, microbial solutions provide an ideal option, supporting healthier crops and higher yields while minimizing environmental impact.
"Asia Pacific is expected to hold a significant share in the agricultural microbials market."
Asia Pacific is expected to hold a significant market share in the agricultural microbials market, driven by the region's rapidly expanding agricultural sector and increasing demand for sustainable farming practices. Countries like China, India, and Japan are adopting microbial solutions to address challenges such as soil degradation, pest resistance, and the need for environmentally friendly alternatives to chemical pesticides. The growing emphasis on organic farming, government support for sustainable agriculture, and rising consumer awareness of food safety and environmental issues further contribute to the market's expansion in the region. With a large agricultural base and increasing investment in agricultural innovation, Asia Pacific is poised to play a key role in the growth of the global agricultural microbials market.
In-depth interviews have been conducted with chief executive officers (CEOs), Directors, and other executives from various key organizations operating in the agricultural microbials market:
- By Company Type: Tier 1 - 25%, Tier 2 - 45%, and Tier 3 - 30%
- By Designation: Directors - 20%, Managers - 50%, Executives - 30%
- By Region: North America - 25%, Europe - 30%, Asia Pacific - 20%, South America - 15%, and Rest of the World - 10%
Prominent companies in the market include BASF SE (Germany), Bayer AG (Germany), Syngenta Group (Switzerland), UPL (India), Corteva (US), FMC Corporation (US), Nufarm (Australia), Sumitomo Chemical Co., Ltd. (Japan), BIONEMA (US), Koppert (Netherlands), Certis USA L.L.C. (US), Bioceres Crop Solutions (Argentina), Novonesis Group (Denmark), BioFirst Group (Belgium), and Lallemand Inc (Canada).
Other players include IPL Biologicals (India), Rovensa Next (Spain), Vestaron Corporation (US), AgriLife (India), Aphea.Bio (Belgium), Andermatt Group AG (Switzerland), Genica (Brazil), SEIPASA, S.A. (Spain), BioConsortia (US), and Nordic Microbes A/SV (Denmark).
Research coverage
This research report categorizes the agricultural microbials market by type (fungi, bacteria, protozoa, and virus), function (soil amendment, crop protection), application (foliar spray, seed treatment, soil treatment), formulation (liquid, dry), crop type (cereals & grains, fruits & vegetables, oilseeds & pulses) and region (North America, Europe, Asia Pacific, South America, and Rest of the World). The scope of the report covers detailed information regarding the major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the agricultural microbials market. A detailed analysis of the key industry players has been done to provide insights into their business overview, services, key strategies, contracts, partnerships, agreements, new service launches, mergers and acquisitions, and recent developments associated with the agricultural microbials market. Competitive analysis of upcoming startups in the agricultural microbials market ecosystem is covered in this report. Furthermore, industry-specific trends such as technology analysis, ecosystem and market mapping, patent, regulatory landscape, among others, are also covered in the study.
Reasons to buy this report
The report will help the market leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the overall agricultural microbials and the subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
1. In-depth Segmentation across Type, Crop Type, Form, Source and Mode of Application: The study examines key drivers (rising adoption of sustainable farming practices, growing concerns over soil degradation and excessive use of synthetic fertilizers and pesticides, government support for biological crop inputs and sustainable agriculture, increasing focus on improving crop productivity, soil health, and nutrient use efficiency), restraints (low farmer awareness and limited technical knowledge in developing markets, limited shelf life and stringent storage requirements of microbial products, variable field performance under different soil and climatic conditions), opportunities (expansion of organic and regenerative agriculture, strong growth potential in emerging agricultural economies, advancements in microbial strain discovery, fermentation, and formulation technologies), and challenges (product contamination and maintaining quality consistency, complex and time consuming regulatory approval processes, competition from low cost synthetic fertilizers and pesticides).
2. Region-specific Insights with Focus on Emerging Markets: The report provides detailed country- and region-level analysis, highlighting growth opportunities across Asia Pacific, North America, Europe, Latin America, and the Middle East & Africa. It evaluates regional demand patterns, irrigation penetration, regulatory policies related to nutrient management, and investment trends in precision agriculture, offering strategic guidance for expansion and localization initiatives.
3. Competitive Intelligence and Innovation Landscape: Leading market participants include Novonesis, UPL Limited, Syngenta AG, T. Stanes & Company, Lallemand Inc., Rizobacter Argentina S.A., Gujarat State Fertilizers and Chemicals Ltd (GSFC), Madras Fertilizers Limited, IPL Biologicals, Koppert Biological Systems, Corteva Agriscience, Kan Biosys, Mapleton Agri Biotech Pvt Ltd, Seipasa S.A., and AgriLife.
4. Demand Forecasts Backed by Data-driven Methodologies: Market sizing and growth projections through 2031 are developed using a combination of top-down and bottom-up approaches, validated by industry experts, trade associations, and official government data. These insights provide reliable guidance for investment planning and market opportunity assessment in the global sector.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.1.1 MARKET DEFINITION
- 1.2 MARKET SCOPE
- 1.2.1 MARKET SEGMENTATION
- 1.2.2 INCLUSIONS AND EXCLUSIONS
- 1.3 YEARS CONSIDERED
- 1.4 UNIT CONSIDERED
- 1.4.1 CURRENCY/VALUE UNIT
- 1.4.2 VOLUME CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN AGRICULTURAL MICROBIALS MARKET
- 2.4 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN AGRICULTURAL MICROBIALS MARKET
- 3.2 AGRICULTURAL MICROBIALS MARKET, BY CROP TYPE AND REGION
- 3.3 AGRICULTURAL MICROBIALS MARKET, BY FUNCTION
- 3.4 AGRICULTURAL MICROBIALS MARKET, BY TYPE
- 3.5 AGRICULTURAL MICROBIALS MARKET, BY APPLICATION
- 3.6 AGRICULTURAL MICROBIALS MARKET, BY FORMULATION
- 3.7 AGRICULTURAL MICROBIALS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising pest proliferation due to climate change
- 4.2.1.2 Lower development cost of microbials compared to chemical pesticides
- 4.2.1.3 Target specificity of microbial crop protectants
- 4.2.1.4 Global expansion of organic farmlands
- 4.2.2 RESTRAINTS
- 4.2.2.1 Shorter shelf life and complex storage requirements of microbial products
- 4.2.2.2 Environmental and technological limitations of agricultural microbial products
- 4.2.2.3 Low farmer awareness of biofertilizers and high labor costs
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Shift toward regenerative agriculture and sustainable farming practices
- 4.2.3.2 Government initiatives to address environmental impact of chemical pesticides
- 4.2.4 CHALLENGES
- 4.2.4.1 Unorganized market and easy availability of low-cost chemical fertilizers
- 4.2.4.2 Regulatory barriers
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN AGRICULTURAL MICROBIALS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INCREASE IN PRODUCTION OF HORTICULTURAL CROPS
- 5.2.2 GROWTH IN ORGANIC AGRICULTURAL PRACTICES
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 RAW MATERIAL SUPPLIERS
- 5.3.2 MICROBIAL PRODUCT MANUFACTURERS & FORMULATORS
- 5.3.3 SYSTEM INTEGRATORS & TECHNOLOGY/SOFTWARE PROVIDERS
- 5.3.4 DISTRIBUTION & AGRICULTURAL SERVICE NETWORK
- 5.3.5 AFTER-SALES & TECHNICAL SUPPORT
- 5.3.6 END USERS / FARMERS & COMMERCIAL GROWERS
- 5.4 ECOSYSTEM ANALYSIS
- 5.4.1 DEMAND SIDE
- 5.4.2 SUPPLY SIDE
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF KEY PLAYERS, BY FUNCTION
- 5.5.2 AVERAGE SELLING PRICE TREND, BY REGION
- 5.5.3 AVERAGE SELLING PRICE TREND, BY FUNCTION
- 5.6 TRADE ANALYSIS
- 5.6.1 EXPORT SCENARIO OF HS CODE 3808
- 5.6.2 IMPORT SCENARIO OF HS CODE 3808
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 BAYER: AI AND SYNTHETIC BIOLOGY ACCELERATING MICROBIAL DISCOVERY
- 5.10.2 CORTEVA: COMPUTATIONAL NATURE-DERIVED DISCOVERY FOR BIOLOGICAL CROP PROTECTION
- 5.10.3 SYNGENTA: AI-DRIVEN DEVELOPMENT OF NEXT-GENERATION BIOSTIMULANTS
- 5.11 IMPACT OF 2025 US TARIFF - AGRICULTURAL MICROBIALS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 Canada
- 5.11.4.2 Mexico
- 5.11.4.3 China
- 5.11.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 AI-DRIVEN MICROBIAL STRAIN DISCOVERY & OPTIMIZATION
- 6.1.2 SYNTHETIC BIOLOGY & MICROBIAL ENGINEERING
- 6.1.3 MICROBIOME SEQUENCING & PRECISION MICROBIOME ENGINEERING
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 PRECISION AGRICULTURE & IOT-BASED SOIL MONITORING
- 6.2.2 PRECISION APPLICATION & SMART SPRAYING TECHNOLOGIES
- 6.2.3 DIGITAL FARM MANAGEMENT & DECISION-SUPPORT PLATFORMS
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 RNA-BASED CROP PROTECTION TECHNOLOGIES
- 6.3.2 BIOLOGICALS-BASED BIOSTIMULANTS & PLANT BIOSTIMULANT TECHNOLOGIES
- 6.3.3 CONTROLLED-RELEASE & ENCAPSULATION TECHNOLOGIES
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 6.5 PATENT ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AI-POWERED MICROBIAL STRAIN DISCOVERY
- 6.6.2 ADVANCED MICROBIAL CONSORTIA
- 6.6.3 PRECISION MICROBIOME-BASED APPLICATION
- 6.6.4 SMART FORMULATION & CONTROLLED MICROBIAL DELIVERY
- 6.6.5 FULLY INTEGRATED DIGITAL MICROBIAL FARMING
- 6.7 IMPACT OF GENERATIVE AI ON AGRICULTURAL MICROBIALS MARKET
- 6.7.1 INTRODUCTION
- 6.7.2 USE OF GENERATIVE AI ON AGRICULTURAL MICROBIALS MARKET
- 6.7.3 TOP USE CASES AND MARKET POTENTIAL
- 6.7.4 BEST PRACTICES IN AGRICULTURAL MICROBIALS INDUSTRY
- 6.7.5 CASE STUDIES OF AI IMPLEMENTATION IN AGRICULTURAL MICROBIALS MARKET
- 6.7.6 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.7 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN AGRICULTURAL MICROBIALS MARKET
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIER AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USER/END-USE INDUSTRIES
- 8.4.1 COMMERCIAL FARMING
- 8.4.2 LARGE AGRIBUSINESSES
- 8.4.3 PLANTATION AGRICULTURE
- 8.4.4 HORTICULTURE & GREENHOUSE FARMING
- 8.4.5 ORGANIC FARMING
- 8.4.6 SEED TREATMENT INDUSTRY
- 8.5 MARKET PROFITABILITY
9 AGRICULTURAL MICROBIALS MARKET, BY FUNCTION
- 9.1 INTRODUCTION
- 9.2 SOIL AMENDMENTS
- 9.2.1 BIOFERTILIZERS
- 9.2.1.1 Biofertilizers improve nutrient use efficiency, strengthens root development
- 9.2.1.2 Nitrogen-fixing biofertilizers
- 9.2.1.2.1 Rhizobium
- 9.2.1.2.2 Azotobacter
- 9.2.1.2.3 Azospirillum
- 9.2.1.2.4 Other nitrogen-fixing biofertilizers
- 9.2.1.3 Phosphate solubilizing & mobilizing biofertilizers
- 9.2.1.3.1 Bacillus subtilis
- 9.2.1.3.2 Pseudomonas
- 9.2.1.3.3 Other phosphate solubilizing & mobilizing biofertilizers
- 9.2.1.4 Potassium solubilizing & mobilizing biofertilizers
- 9.2.1.4.1 Bacillus mucilaginosus
- 9.2.1.4.2 Other potassium solubilizing & mobilizing biofertilizers
- 9.2.1.5 Other biofertilizers
- 9.2.2 BIOSTIMULANTS
- 9.2.2.1 Biostimulants increase nutrient availability through biological nitrogen fixation or nutrient solubilization, microbial
- 9.2.1 BIOFERTILIZERS
- 9.3 CROP PROTECTION
- 9.3.1 BIOINSECTICIDES
- 9.3.1.1 Utilizing naturally occurring microorganisms to control insect pests
- 9.3.1.2 Bacillus thuringiensis
- 9.3.1.3 Beauveria bassiana
- 9.3.1.4 Metarhizium anisopliae
- 9.3.1.5 Verticillium lecanii
- 9.3.1.6 Baculovirus
- 9.3.1.7 Other bioinsecticides
- 9.3.2 BIOFUNGICIDES
- 9.3.2.1 Well-suited for organic farming methods but expanding to encompass conventional row-crop operations
- 9.3.2.2 Trichoderma
- 9.3.2.3 Bacillus
- 9.3.2.4 Pseudomonas
- 9.3.2.5 Streptomyces
- 9.3.2.6 Other biofungicides
- 9.3.3 BIONEMATICIDES
- 9.3.3.1 Microbials leading to the development and adoption of Bionematicides
- 9.3.3.2 Paecilomyces lilacinus
- 9.3.3.3 Bacillus firmus
- 9.3.3.4 Other bionematicides
- 9.3.4 BIOHERBICIDES
- 9.3.4.1 Bioherbicides is effective for managing herbicide-resistant plant populations
- 9.3.4.2 Colletotrichum SPP.
- 9.3.4.3 Xanthomonas campestris
- 9.3.4.4 Other bioherbicides
- 9.3.5 OTHER CROP PROTECTION FUNCTIONS
- 9.3.1 BIOINSECTICIDES
10 AGRICULTURAL MICROBIALS MARKET, BY TYPE
- 10.1 INTRODUCTION
- 10.2 BACTERIA
- 10.2.1 ENHANCING CROP PRODUCTIVITY AND SOIL HEALTH
- 10.3 FUNGI
- 10.3.1 AIDING NUTRIENT UPTAKE AND IMPROVING STRESS TOLERANCE
- 10.4 VIRUS
- 10.4.1 SERVING AS HIGHLY SELECTIVE BIOLOGICAL CONTROL AGENT FOR INSECT PESTS
- 10.5 PROTOZOA
- 10.5.1 MAINTAINING HEALTHY SOIL ECOSYSTEMS AND SUPPORTING SUSTAINABLE CROP PRODUCTION
11 AGRICULTURAL MICROBIALS MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 FOLIAR SPRAY
- 11.2.1 BROADENING BIOLOGICAL PEST AND DISEASE CONTROL THROUGH ADVANCED FOLIAR FORMULATION
- 11.3 SOIL TREATMENT
- 11.3.1 EXTENDING IN-FURROW AND GRANULAR MICROBIAL DELIVERY TO STRENGTHEN ROOT-ZONE PERFORMANCE
- 11.4 SEED TREATMENT
- 11.4.1 SCALING PRECISION MICROBIAL SEED COATINGS FOR EARLY-SEASON CROP PROTECTION AND VIGOR
- 11.5 OTHER APPLICATIONS
12 AGRICULTURAL MICROBIALS MARKET, BY FORMULATION
- 12.1 INTRODUCTION
- 12.2 LIQUID
- 12.2.1 ADVANCING CARRIER AND STABILIZATION TECHNOLOGY TO EXTEND LIQUID MICROBIAL FIELD PERFORMANCE
- 12.2.2 EMULSIFIABLE CONCENTRATES
- 12.2.3 SUSPENSION CONCENTRATES
- 12.2.4 SOLUBLE LIQUID CONCENTRATES
- 12.3 DRY
- 12.3.1 SCALING AMBIENT-STABLE POWDER AND GRANULE TECHNOLOGY FOR GLOBAL MARKET ACCESS
- 12.3.2 WETTABLE POWDERS
- 12.3.3 WATER-DISPERSIBLE GRANULES
- 12.3.4 DRY GRANULES
13 AGRICULTURAL MICROBIALS MARKET, BY CROP TYPE
- 13.1 INTRODUCTION
- 13.2 CEREALS & GRAINS
- 13.2.1 EXTENSIVE CULTIVATION AREA, HIGH FERTILIZER DEPENDENCY, AND GROWING EMPHASIS ON SUSTAINABLE YIELD IMPROVEMENT
- 13.2.2 CORN
- 13.2.3 WHEAT
- 13.2.4 RICE
- 13.2.5 OTHER CEREALS & GRAINS
- 13.3 OILSEEDS & PULSES
- 13.3.1 HIGH NUTRITIONAL VALUE, EXPANDING ROLE IN SUSTAINABLE CROP ROTATIONS, AND NATURAL COMPATIBILITY WITH BIOLOGICAL NITROGEN FIXATION
- 13.3.2 SOYBEAN
- 13.3.3 SUNFLOWER
- 13.3.4 OTHER OILSEEDS & PULSES
- 13.4 FRUIT & VEGETABLES
- 13.4.1 HIGH ECONOMIC VALUE, STRINGENT QUALITY STANDARDS, AND INTENSIVE CROP MANAGEMENT REQUIREMENTS
- 13.4.2 ROOT & TUBER VEGETABLES
- 13.4.3 LEAFY VEGETABLES
- 13.4.4 POME FRUITS
- 13.4.5 BERRIES
- 13.4.6 CITRUS FRUITS
- 13.4.7 OTHER FRUITS & VEGETABLES
- 13.5 OTHER CROP TYPES
14 AGRICULTURAL MICROBIALS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Government policies and initiatives to fuel market expansion
- 14.2.2 CANADA
- 14.2.2.1 Focus on innovation, policy support, and research investment to drive market
- 14.2.3 MEXICO
- 14.2.3.1 Growing emphasis on sustainable agricultural practices to fuel market growth
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 SPAIN
- 14.3.1.1 Collaborative innovations to drive demand for agricultural microbials
- 14.3.2 FRANCE
- 14.3.2.1 Increasing shift toward sustainable farming practices to drive market
- 14.3.3 GERMANY
- 14.3.3.1 Support for ban on chemical insecticides to drive market
- 14.3.4 ITALY
- 14.3.4.1 Significant use of microbials in horticulture and development of organic farming practices to support market growth
- 14.3.5 UK
- 14.3.5.1 Gradual focus of farmers on adopting organic practices to drive market
- 14.3.6 REST OF EUROPE
- 14.3.1 SPAIN
- 14.4 ASIA PACIFIC
- 14.4.1 CHINA
- 14.4.1.1 Focus on raising sustainable farming practices to support market growth
- 14.4.2 INDIA
- 14.4.2.1 Increasing awareness of sustainable farming practices and government initiatives to drive market
- 14.4.3 JAPAN
- 14.4.3.1 Rising food security and quality concerns to drive demand for microbials in crop cultivation
- 14.4.4 AUSTRALIA
- 14.4.4.1 Vast organic farmland to drive demand for agricultural microbial products
- 14.4.5 REST OF ASIA PACIFIC
- 14.4.1 CHINA
- 14.5 SOUTH AMERICA
- 14.5.1 ARGENTINA
- 14.5.1.1 Organic and sustainable farming initiatives to drive market
- 14.5.2 BRAZIL
- 14.5.2.1 Success of Bt biopesticides to propel agricultural microbial use
- 14.5.3 REST OF SOUTH AMERICA
- 14.5.1 ARGENTINA
- 14.6 REST OF THE WORLD
- 14.6.1 AFRICA
- 14.6.1.1 Collaborations between international organizations and biopesticide stakeholders to drive market
- 14.6.2 MIDDLE EAST
- 14.6.2.1 High demand for domestically produced organic foods to boost market
- 14.6.1 AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 15.3 REVENUE ANALYSIS
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2023
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.5.5.1 Company footprint
- 15.5.5.2 Regional footprint
- 15.5.5.3 Type footprint
- 15.5.5.4 Function footprint
- 15.5.5.5 Formulation footprint
- 15.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2023
- 15.6.1 PROGRESSIVE COMPANIES
- 15.6.2 RESPONSIVE COMPANIES
- 15.6.3 DYNAMIC COMPANIES
- 15.6.4 STARTING BLOCKS
- 15.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.6.5.1 Detailed list of key startups/SMEs
- 15.6.5.2 Competitive benchmarking of key startups/SMEs
- 15.7 COMPANY VALUATION AND FINANCIAL METRICS
- 15.8 BRAND/PRODUCT/SERVICE ANALYSIS
- 15.9 COMPETITIVE SCENARIO AND TRENDS
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 BASF SE
- 16.1.1.1 Business overview
- 16.1.1.2 Products offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product Launches
- 16.1.1.3.2 Expansions
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key Strengths
- 16.1.1.4.2 Strategic Choices
- 16.1.1.4.3 Weaknesses and Competitive Threats
- 16.1.2 BAYER AG
- 16.1.2.1 Business overview
- 16.1.2.2 Products offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Deals
- 16.1.2.3.2 Expansions
- 16.1.2.4 MnM view
- 16.1.2.4.1 Key Strengths
- 16.1.2.4.2 Strategic Choices
- 16.1.2.4.3 Weaknesses and Competitive Threats
- 16.1.3 SYNGENTA GROUP
- 16.1.3.1 Business overview
- 16.1.3.2 Products offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Product Launches
- 16.1.3.3.2 Deals
- 16.1.3.3.3 Expansions
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key Strengths
- 16.1.3.4.2 Strategic Choices
- 16.1.3.4.3 Weaknesses and Competitive Threats
- 16.1.4 CORTEVA INC.
- 16.1.4.1 Business overview
- 16.1.4.2 Products offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Product Launches
- 16.1.4.3.2 Deals
- 16.1.4.4 MnM view
- 16.1.4.4.1 Key strengths
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses and competitive threats
- 16.1.5 FMC CORPORATION
- 16.1.5.1 Business overview
- 16.1.5.2 Products offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Product launches
- 16.1.5.3.2 Deals
- 16.1.5.3.3 Expansions
- 16.1.5.3.4 Other developments
- 16.1.5.4 MnM view
- 16.1.5.4.1 Key strengths
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses and competitive threats
- 16.1.6 UPL
- 16.1.6.1 Business overview
- 16.1.6.2 Products offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Product launches
- 16.1.6.3.2 Deals
- 16.1.6.4 MnM view
- 16.1.7 SUMITOMO CHEMICAL CO., LTD.
- 16.1.7.1 Business overview
- 16.1.7.2 Products offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.7.3.2 Expansions
- 16.1.7.4 MnM view
- 16.1.8 NUFARM
- 16.1.8.1 Business overview
- 16.1.8.2 Products offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.8.4 MnM view
- 16.1.9 NOVONESIS
- 16.1.9.1 Business overview
- 16.1.9.2 Products offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Product launches
- 16.1.9.3.2 Deals
- 16.1.9.4 MnM view
- 16.1.10 BIOCERES CROP SOLUTIONS
- 16.1.10.1 Business overview
- 16.1.10.2 Products offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Product launches
- 16.1.10.3.2 Deals
- 16.1.10.4 MnM view
- 16.1.11 KOPPERT
- 16.1.11.1 Business overview
- 16.1.11.2 Products offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Deals
- 16.1.11.3.2 Expansions
- 16.1.11.4 MnM view
- 16.1.12 CERTIS USA L.L.C.
- 16.1.12.1 Business overview
- 16.1.12.2 Products offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Product launches
- 16.1.12.3.2 Deals
- 16.1.12.4 MnM view
- 16.1.13 IPL BIOLOGICALS
- 16.1.13.1 Business overview
- 16.1.13.2 Products offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 Product launches
- 16.1.13.3.2 Deals
- 16.1.13.3.3 Expansions
- 16.1.13.3.4 Other developments
- 16.1.13.4 MnM view
- 16.1.13.4.1 Right to Win
- 16.1.14 BIOFIRST GROUP
- 16.1.14.1 Business overview
- 16.1.14.2 Products offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Deals
- 16.1.14.4 MnM view
- 16.1.15 LALLEMAND INC
- 16.1.15.1 Business overview
- 16.1.15.2 Products offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Product launches
- 16.1.15.4 MnM view
- 16.1.1 BASF SE
- 16.2 OTHER PLAYERS (SMES/STARTUPS)
- 16.2.1 BIONEMA
- 16.2.1.1 Business overview
- 16.2.1.2 Products offered
- 16.2.1.3 Recent developments
- 16.2.1.3.1 Product launches
- 16.2.1.4 MnM view
- 16.2.2 GUJARAT STATE FERTILIZERS & CHEMICALS (GSFC)
- 16.2.2.1 Business overview
- 16.2.2.2 Products offered
- 16.2.2.3 MnM view
- 16.2.2.3.1 Right to Win
- 16.2.3 ROVENSA NEXT
- 16.2.3.1 Business overview
- 16.2.3.2 Products offered
- 16.2.3.3 Recent developments
- 16.2.3.3.1 Product launches
- 16.2.3.3.2 Expansions
- 16.2.3.4 MnM view
- 16.2.3.4.1 Right to Win
- 16.2.4 AGRILIFE
- 16.2.4.1 Business overview
- 16.2.4.2 Products offered
- 16.2.4.3 MnM view
- 16.2.4.3.1 Right to Win
- 16.2.5 ANDERMATT GROUP AG
- 16.2.6 APHEA.BIO
- 16.2.7 GENICA
- 16.2.8 NORDIC MICROBES A/S
- 16.2.9 GOWAN COMPANY
- 16.2.10 BIOCONSORTIA
- 16.2.1 BIONEMA
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 List of major secondary sources
- 17.1.1.2 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.2.3 Breakdown of primaries
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 BOTTOM-UP APPROACH
- 17.2.2 TOP-DOWN APPROACH
- 17.2.2.1 Approach to estimate market size using top-down analysis
- 17.3 DATA TRIANGULATION
- 17.4 RESEARCH ASSUMPTIONS
- 17.5 RESEARCH LIMITATIONS AND RISK ASSESSMENT
18 ADJACENT AND RELATED MARKETS
- 18.1 INTRODUCTION
- 18.2 LIMITATIONS
- 18.3 BIOPESTICIDES MARKET
- 18.3.1 MARKET DEFINITION
- 18.3.2 MARKET OVERVIEW
- 18.4 AGRICULTURAL BIOLOGICALS MARKET
- 18.4.1 MARKET DEFINITION
- 18.4.2 MARKET OVERVIEW
- 18.5 PLANT GROWTH REGULATORS MARKET
- 18.5.1 MARKET DEFINITION
- 18.5.2 MARKET OVERVIEW
19 APPENDIX
- 19.1 DISCUSSION GUIDE
- 19.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.3 CUSTOMIZATION OPTIONS
- 19.4 RELATED REPORTS
- 19.5 AUTHOR DETAILS