|
시장보고서
상품코드
2126324
종자 코팅 시장 예측(-2031년) : 첨가제 유형별, 코팅 유형별, 작물 유형별, 형태별, 가공 유형별, 지역별Seed Coating Market by Additive Type (Polymers, Colorants, Binders, Minerals/Pumice, Active Ingredients), Crop Type, Process (Film Coating, Pelleting, Encrusting), Coating Type (Bio-based, Synthetic), Form, and Region - Global Forecast To 2031 |
||||||

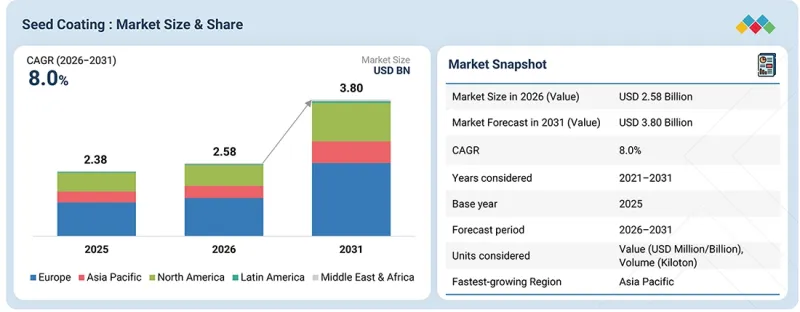
종자 코팅 시장 규모는 2026년에 25억 8,000만 달러로 추계되고 있으며, 2031년까지 CAGR 8.0%로 38억 달러에 달할 것으로 예측됩니다.
종자 코팅 시장은 발아율을 높이고, 생육 초기 해충으로부터 작물을 보호하며, 작물의 균일성을 향상시키는 고품질 종자에 대한 수요 증가에 힘입어 성장하고 있습니다. 지속가능한 농업 방식의 부상, 생물 유래 자재의 활용 확대, 그리고 정밀농업의 보급이 이 시장의 채택을 더욱 촉진하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(달러) 및 수량(1,000톤) |
| 부문 | 첨가제 유형별, 코팅 유형별, 작물 유형별, 형태별, 가공 유형별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 남미 및 기타 지역 |
또한 정부의 지원 정책과 제한된 경작지에서 작물 수확량 향상에 대한 수요가 시장 성장을 지속적으로 지원하고 있습니다. 폴리머계 및 바이오 기반 제제와 같은 코팅 기술의 발전도 종자의 성능과 취급 편의성 개선으로 이어지고 있습니다. 미량영양소, 농약, 미생물 제제를 코팅에 접목할 수 있다는 점은 농가에게 추가적인 부가가치를 제공합니다. 또한 종자 처리의 장기적인 이점에 대한 농가의 인식이 높아지고 있으며, 그 보급이 가속화되고 있습니다.
"종자 코팅 시장의 형태별 부문에서 액체 부문이 가장 큰 시장 점유율을 차지하고 있습니다."
종자 코팅 시장의 형태별 부문에서 액체 형태가 가장 큰 점유율을 차지하고 있습니다. 이는 주로 뛰어난 도포 효율, 균일한 피복성, 그리고 다양한 종자 유형에 대한 적응성 덕분입니다. 액체 코팅을 통해 비료, 미량영양소, 살균제, 살충제, 생물 제제 등의 유효 성분을 종자 표면에 직접적이고 정확하게 도포할 수 있으며, 일관된 성능과 발아율 향상을 보장합니다. 이 형태는 자동 처리 장비를 사용하여 쉽게 도포할 수 있으므로 대규모 농업 경영에 적합하며, 상업 농업에서 매우 선호됩니다. 또한 액체 종자 코팅은 건조 제제에 비해 밀착성이 높고 분진 비산이 적어 종자 취급, 안전성 및 환경 규제 준수가 향상됩니다.
"종자 코팅 시장의 공정 부문에서 엔크러스트(피막 형성) 부문이 가장 큰 시장 점유율을 차지하고 있습니다."
엔크러스트 처리 부문은 종자의 크기, 형태, 균일성 및 취급 특성을 개선할 수 있으므로 종자 코팅 시장에서 가장 높은 성장률을 보일 것으로 예상됩니다. 엔크러스트 처리에서는 종자의 본래 형태를 유지한 채 코팅재나 유효 성분을 도포할 수 있으므로, 정밀 파종이나 기계화된 파종에 적합합니다. 채소, 곡물 및 특수 종자에 대한 채택이 증가하고 있는 점도 이 부문의 성장을 더욱 지원하고 있습니다.
유럽은 세계 종자 코팅 시장에서 현저한 성장률을 보일 것으로 전망됩니다.
유럽에서는 지속가능한 농업에 대한 강력한 초점과 친환경 자재 사용을 촉진하는 엄격한 규제 체계를 배경으로, 종자 코팅 시장이 현저한 성장률을 보일 것으로 예상됩니다. EU 규제에 힘입어 생물학적 종자 처리 및 미세 플라스틱이 포함되지 않은 코팅의 채택이 확대되면서, 첨단 종자 코팅 기술에 대한 혁신과 투자가 촉진되고 있습니다. 또한 프랑스, 독일, 네덜란드와 같은 주요 농업 경제권이 존재하는 데다, 작물 수확량 증대 및 자원 효율 개선 측면에서 코팅 종자가 가져다주는 이점에 대한 농가의 인식 제고도 해당 지역 전체의 시장 꾸준한 성장에 기여하고 있습니다.
이 시장의 주요 기업으로는 BASF SE(독일), Syensqo(벨기에), Clariant(스위스), Croda International plc(영국), Sensient Technologies Corporation(미국), Germains Seed Technology(영국),Milliken(미국), Covestro AG(독일), BrettYoung(캐나다), Chromatech Incorporated(미국), Centor Group(네덜란드), Michelman, Inc.(미국), Precision Labs(미국), CR Minerals, LLC(미국), Universal Coating Systems(미국) 등이 있습니다.
그 밖의 주요 기업으로는 Acadian Plant Health(캐나다), Smith Seed Services(미국), Little's Agrivet(인도), AlfaGen Seeds Company Pty Ltd.(호주), Agathos BV(네덜란드),SP Colour & Chemicals(인도), Organic Dyes & Pigments LLC(미국), BIOWEG(독일), Southern Enterprises(인도), SEEDPOLY Biocoatings Private Limited(인도) 및 CISTRONICS TECHNOVATIONS PVT LTD.(인도) 등이 있습니다.
조사 범위:
본 조사 보고서에서는 종자 코팅 시장을 첨가제 유형(폴리머, 착색제, 광물/경석, 결합제, 유효 성분, 기타 첨가제), 가공 유형별(필름 코팅, 펠릿화, 피복),작물 유형별(곡물, 과일·채소, 지방종자·두류, 꽃·관상용 식물, 기타 작물), 코팅 유형별(합성계 및 바이오 기반), 형태별(액체 및 건조), 지역별(북미, 유럽, 아시아태평양, 남미, 기타 지역)로 분류하고 있습니다. 이 보고서의 조사 범위에는 종자 코팅 시장의 성장에 영향을 미치는 주요 요인(촉진요인, 제약 요인, 과제 및 기회 등)에 대한 상세한 정보가 포함되어 있습니다. 주요 업계 참여 기업에 대한 상세한 분석을 통해 사업 개요, 서비스, 주요 전략, 계약, 파트너십, 합의 사항, 신규 서비스 출시, 합병 및 인수, 그리고 종자 코팅 시장과 관련된 최근 동향에 대한 인사이트를 제공합니다. 이 보고서에서는 종자 코팅 시장 생태계에서 두각을 보이고 있는 스타트업 기업의 경쟁 분석도 다루고 있습니다. 또한 기술 분석, 생태계 및 시장 매핑, 특허 및 규제 현황 등 업계 특유의 동향에 대해서도 본 조사에서 포괄적으로 다루고 있습니다.
이 보고서를 구매해야 하는 이유:
이 보고서는 이 시장의 시장 선도 기업 및 신규 진입 기업에게 종자 코팅 시장 전체 및 각 하위 부문의 매출에 대한 가장 정확한 추정치를 제공합니다. 이 보고서는 이해관계자가 경쟁 구도를 이해하고, 비즈니스 위치를 최적화하며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻는 데 도움이 됩니다. 또한 이해관계자가 시장 동향을 파악할 수 있도록 지원하며, 주요 시장 촉진요인, 제약, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 종자 코팅 시장의 성장에 영향을 미치는 주요 촉진요인(기술 혁신), 제약 요인(엄격한 규제 환경), 기회(작물별로 맞춤화된 코팅), 그리고 과제(높은 연구개발비 및 배합 개발 비용)에 대한 분석
- 신제품 출시/혁신: 종자 코팅 시장의 연구개발 활동 및 신제품 출시에 대한 상세 인사이트
- 시장 동향: 수익성이 높은 시장에 대한 포괄적인 정보 - 이 보고서는 다양한 지역의 종자 코팅 시장을 분석합니다.
- 시장 다각화: 종자 코팅 시장의 새로운 서비스, 미개발 지역, 최근 동향 및 투자에 대한 포괄적인 정보.
- 경쟁 평가: BASF SE(독일), Syensqo(벨기에), Clariant(스위스), Croda International plc(영국),Sensient Technologies Corporation(미국), Germains Seed Technology(영국)를 비롯한 종자 코팅 시장의 주요 기업 및 기타 기업의 시장 점유율, 성장 전략, 제품 라인업, 브랜드/제품 비교, 제품 전개 현황에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 구상
제8장 고객 상황과 구매 행동
제9장 종자 코팅 시장(첨가제 유형별)
제10장 종자 코팅 시장(코팅 유형별)
제11장 종자 코팅 시장(작물 유형별)
제12장 종자 코팅 시장(형태별)
제13장 종자 코팅 시장(가공 유형별)
제14장 종자 코팅 시장(지역별)
제15장 경쟁 구도
제16장 기업 개요
제17장 조사 방법
제18장 인접 시장 및 관련 시장
제19장 부록
KSA 26.09.11The seed coating market is estimated at USD 2.58 billion in 2026 and is projected to reach USD 3.80 billion by 2031, at a CAGR of 8.0%. The seed coating market is driven by the growing demand for high-quality seeds that enhance germination, protect against early-stage pests, and improve crop uniformity. The rise of sustainable farming practices, increased use of biological inputs, and the expansion of precision agriculture are further fueling adoption.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD) and Volume (KT) |
| Segments | Additive type, Process, Coating Type, Form, Crop Type, and Region |
| Regions covered | North America, Europe, Asia Pacific, South America, and RoW |
Additionally, supportive government policies and the need for higher crop yields in limited arable land continue to boost market growth. Advancements in coating technologies, such as polymer-based and bio-based formulations, have also improved seed performance and handling. The ability to integrate micronutrients, pesticides, and microbial inoculants into coatings adds further value for farmers. Moreover, the growing awareness among farmers about the long-term benefits of seed treatments is accelerating adoption.
"The liquid segment holds the highest market share in the form segment of the seed coating market."
Liquid form holds the largest share in the form segment of the seed coating market, primarily due to its superior application efficiency, uniform coverage, and adaptability across various seed types. Liquid coatings allow precise delivery of active ingredients such as fertilizers, micronutrients, fungicides, insecticides, and biologicals directly onto the seed surface, ensuring consistent performance and improved germination. This form is highly favored in commercial agriculture because it can be easily applied using automated treatment equipment, making it suitable for large-scale operations. Moreover, liquid seed coatings enable better adhesion and reduced dust-off compared to dry formulations, which enhances seed handling, safety, and environmental compliance.
"The encrusting segment holds the highest market share in the process segment of the seed coating market."
The encrusting segment is expected to register the highest growth in the seed coating market, driven by its ability to improve seed size, shape, uniformity, and handling characteristics. Encrusting enables the application of coating materials and active ingredients while maintaining the seed's original shape, making it suitable for precision planting and mechanized sowing. Its increasing adoption in vegetable, cereal, and specialty seed applications is further supporting segment growth.
Europe to grow at a significant rate in the global seed coating market.
Europe is expected to grow at a significant rate in the seed coating market, driven by the region's strong focus on sustainable agriculture and strict regulatory frameworks promoting the use of environmentally friendly inputs. The increasing adoption of biological seed treatments and microplastic-free coatings, supported by EU regulations, is encouraging innovation and investment in advanced seed coating technologies. Additionally, the presence of major agricultural economies such as France, Germany, and the Netherlands, along with rising awareness among farmers about the benefits of coated seeds in improving crop performance and resource efficiency, is contributing to the market's steady growth across the region.
In-depth interviews have been conducted with chief executive officers (CEOs), Directors, and other executives from various key organizations operating in the seed coating market:
- By Company Type: Tier 1 - 25%, Tier 2 - 45%, and Tier 3 - 30%
- By Designation: Directors - 20%, Managers - 50%, Executives - 30%
- By Region: North America - 25%, Europe - 30%, Asia Pacific - 20%, South America - 15%, and Rest of the World - 10%
Prominent companies in the market include BASF SE (Germany), Syensqo (Belgium), Clariant (Switzerland), Croda International plc (UK), Sensient Technologies Corporation (US), Germains Seed Technology (UK), Milliken (US), Covestro AG (Germany), BrettYoung (Canada), Chromatech Incorporated (US), Centor Group (Netherlands), Michelman, Inc. (US), Precision Labs (US), CR Minerals, LLC (US), and Universal Coating Systems (US).
Other players include Acadian Plant Health (Canada), Smith Seed Services (US), Little's Agrivet (India), AlfaGen Seeds Company Pty Ltd. (Australia), Agathos BV (Netherlands), SP Colour & Chemicals (India), Organic Dyes & Pigments LLC (US), BIOWEG (Germany), Southern Enterprises (India), SEEDPOLY Biocoatings Private Limited (India), and CISTRONICS TECHNOVATIONS PVT LTD. (India).
Research Coverage:
This research report categorizes the seed coating market by additive type (polymer, colorants, minerals/pumice, binders, active ingredients, and other additives), process (film coating, pelleting, and encrusting), crop type (cereals & grains, fruits & vegetables, oilseeds & pulses, flowers & ornamentals, and other crop types), coating type (synthetic and bio-based), form (Liquid & dry), and region (North America, Europe, Asia Pacific, South America, and Rest of the World). The scope of the report covers detailed information regarding the major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the seed coating market. A detailed analysis of the key industry players has been done to provide insights into their business overview, services, key strategies, contracts, partnerships, agreements, new service launches, mergers and acquisitions, and recent developments associated with the seed coating market. Competitive analysis of upcoming startups in the seed coating market ecosystem is covered in this report. Furthermore, industry-specific trends such as technology analysis, ecosystem and market mapping, and patent and regulatory landscape, among others, are also covered in the study.
Reasons to buy this report:
The report will help the market leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the overall seed coating and the subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of key drivers (technological innovations in seed coating), restraints (stringent regulatory environment), opportunities (customized crop-specific coatings), and challenges (high R&D and formulation costs) influencing the growth of the seed coating market
- New product launch/Innovation: Detailed insights on research & development activities and new product launches in the seed coating market
- Market Development: Comprehensive information about lucrative markets - the report analyzes the seed coating market across varied regions
- Market Diversification: Exhaustive information about new services, untapped geographies, recent developments, and investments in the seed coating market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, brand/product comparison, and product footprints of leading players such as BASF SE (Germany), Syensqo (Belgium), Clariant (Switzerland), Croda International plc (UK), Sensient Technologies Corporation (US), Germains Seed Technology (UK), and other players in the seed coating market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.1.1 MARKET DEFINITION
- 1.2 MARKET SCOPE
- 1.2.1 MARKET SEGMENTATION
- 1.2.2 INCLUSIONS AND EXCLUSIONS
- 1.3 YEARS CONSIDERED
- 1.4 UNIT CONSIDERED
- 1.4.1 CURRENCY/VALUE UNIT
- 1.4.2 VOLUME CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN SEED COATING MARKET
- 3.2 SEED COATING MARKET, BY PROCESS TYPE AND COUNTRY
- 3.3 SEED COATING MARKET, BY FORM
- 3.4 SEED COATING MARKET, BY ADDITIVE TYPE
- 3.5 SEED COATING MARKET, BY COATING TYPE
- 3.6 SEED COATING MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Advancements in seed coating technologies
- 4.2.1.2 Reduced environmental impact
- 4.2.1.3 Growing adoption of precision agriculture
- 4.2.2 RESTRAINTS
- 4.2.2.1 Lack of harmonized international regulations
- 4.2.2.2 Limited shelf life
- 4.2.2.3 Fluctuating raw material costs and compatibility issues with active ingredients
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Development of bio-based seed coating products
- 4.2.3.2 Use of microbial inoculants in seed coating
- 4.2.3.3 Integration of biostimulants and micronutrients into seed coatings
- 4.2.4 CHALLENGES
- 4.2.4.1 Challenges in applying microbes to seed coatings
- 4.2.4.2 Lengthy duration of development of seed coating formulations
- 4.2.4.3 Maintaining uniform coating quality and seed germination performance
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN SEED COATING MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 GROWTH IN MAJOR COMMERCIAL SEED PRODUCTION
- 5.2.2 RISE IN MARKET DEMAND FOR HIGH-VALUE CROPS
- 5.2.3 GROWTH IN ORGANIC AGRICULTURE PRACTICES
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 RAW MATERIAL & SEED COATING INPUT SUPPLIERS
- 5.3.2 SEED COATING R&D & FORMULATION DEVELOPERS
- 5.3.3 SEED COATING MANUFACTURERS & FORMULATORS
- 5.3.4 DISTRIBUTION & SERVICE NETWORK
- 5.3.5 END USERS
- 5.3.6 AFTER-SALES & TECHNICAL SERVICES
- 5.4 ECOSYSTEM ANALYSIS
- 5.4.1 DEMAND SIDE
- 5.4.2 SUPPLY SIDE
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY CROP TYP
- 5.5.2 AVERAGE SELLING PRICE TREND, BY REGION
- 5.5.3 AVERAGE SELLING PRICE TREND, BY CROP TYPE
- 5.6 TRADE ANALYSIS
- 5.6.1 EXPORT SCENARIO OF HS CODE 1209
- 5.6.2 IMPORT SCENARIO OF HS CODE 1209
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 INCOTEC: ADVANCING MICROPLASTIC-FREE SEED COATINGS TO MEET SUSTAINABILITY AND REGULATORY REQUIREMENTS
- 5.10.2 BAYER: ADOPTING UPCYCLED POTATO STARCH TO DEVELOP SUSTAINABLE AND LOW-DUST SEED COATINGS
- 5.10.3 BASF: EXPANDING MICROPLASTIC-FREE COATING SOLUTIONS TO SUPPORT SUSTAINABLE CORN SEED TREATMENT
- 5.11 IMPACT OF 2026 US TARIFF - SEED COATING MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 India
- 5.11.4.2 China
- 5.11.4.3 European Union
- 5.11.4.4 Japan & South Korea
- 5.11.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 BIOPOLYMER-BASED AND MICROPLASTIC-FREE SEED COATINGS
- 6.1.2 SMART MULTILAYER AND CONTROLLED-RELEASE SEED COATINGS
- 6.1.3 NANO-ENABLED SEED COATINGS AND NANO-DELIVERY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 BIOLOGICAL SEED TREATMENT AND MICROBIAL ENCAPSULATION
- 6.2.2 ADVANCED SEED PRIMING AND PRECISION HYDRATION
- 6.2.3 PRECISION SEED TREATMENT EQUIPMENT AND AUTOMATED COATING
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 AI, COMPUTER VISION, AND DIGITAL SEED QUALITY INSPECTION
- 6.3.2 SEED GENETICS, BIOLOGICAL BREEDING, AND TRAIT-ENABLED SEED TREATMENT
- 6.3.3 PRECISION AGRICULTURE, IOT, AND DIGITAL TRACEABILITY
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID-TERM (2028-2031) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG-TERM (2032-2036+) | MASS COMMERCIALIZATION & DISRUPTION
- 6.5 PATENT ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AI-POWERED SEED COATING OPTIMIZATION
- 6.6.2 MULTI-FUNCTIONAL SEED COATING COMBINATIONS
- 6.6.3 PRECISION SEED COATING APPLICATION
- 6.6.4 SMART FORMULATION & CONTROLLED RELEASE
- 6.6.5 FULLY INTEGRATED DIGITAL SEED MANAGEMENT
- 6.7 IMPACT OF GENERATIVE AI ON SEED COATING MARKET
- 6.7.1 INTRODUCTION
- 6.7.2 USE OF GENERATIVE AI ON SEED COATING MARKET
- 6.7.3 TOP USE CASES AND MARKET POTENTIAL
- 6.7.4 BEST PRACTICES IN SEED COATING INDUSTRY
- 6.7.5 CASE STUDIES OF AI IMPLEMENTATION IN SEED COATING MARKET
- 6.7.6 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.7 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN SEED COATING MARKET
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USER/END-USE INDUSTRIES
- 8.4.1 COMMERCIAL FARMING
- 8.4.2 SEED COMPANIES & SEED PRODUCERS
- 8.4.3 CONTRACT SEED-TREATMENT PROVIDERS
- 8.4.4 VEGETABLE & HORTICULTURAL GROWERS
- 8.4.5 ORGANIC & SUSTAINABLE FARMING
- 8.4.6 PRECISION AGRICULTURE & TECHNOLOGY-ENABLED FARMS
- 8.4.7 SEED TREATMENT EQUIPMENT MANUFACTURERS
- 8.5 MARKET PROFITABILITY
9 SEED COATING MARKET, BY ADDITIVE TYPE
- 9.1 INTRODUCTION
- 9.2 POLYMERS
- 9.2.1 INNOVATIONS IN POLYMER TECHNOLOGIES AND MICROPLASTIC-FREE SOLUTIONS
- 9.2.2 POLYMER GELS
- 9.2.3 SUPERABSORBENT POLYMER GELS
- 9.3 COLORANTS
- 9.3.1 DRIVING COMPLIANCE AND DIFFERENTIATION WITH SEED COATING COLORANTS
- 9.4 BINDERS
- 9.4.1 ENHANCING SEED COATING PERFORMANCE WITH ADVANCED BINDER TECHNOLOGIES
- 9.5 MINERALS/PUMICE
- 9.5.1 PUMICE PROMOTES BETTER SEED GERMINATION AND HANDLING
- 9.6 ACTIVE INGREDIENTS
- 9.6.1 ENHANCED CROP PERFORMANCE WITH ACTIVE INGREDIENT-ENHANCED SEED COATINGS
- 9.6.2 PROTECTANTS
- 9.6.3 PHYTOACTIVE PROMOTERS
- 9.6.4 OTHER ACTIVE INGREDIENTS
- 9.7 OTHER ADDITIVES
10 SEED COATING MARKET, BY COATING TYPE
- 10.1 INTRODUCTION
- 10.2 SYNTHETIC COATING
- 10.2.1 SYNTHETIC COATING DOMINATES SEED COATING MARKET
- 10.3 BIO-BASED COATING
- 10.3.1 CHANGING REGULATORY FRAMEWORKS WILL BOOST DEMAND FOR BIO-BASED SEED COATING
11 SEED COATING MARKET, BY CROP TYPE
- 11.1 INTRODUCTION
- 11.2 CEREALS & GRAINS
- 11.2.1 SEED COATING SOLUTIONS TO ENHANCE CEREAL AND GRAIN PRODUCTION
- 11.2.2 CORN
- 11.2.3 WHEAT
- 11.2.4 RICE
- 11.2.5 SORGHUM
- 11.2.6 BARLEY
- 11.3 VEGETABLES
- 11.3.1 PELLETING HELPS IN INCREASING PRODUCTIVITY OF VEGETABLE SEED
- 11.3.2 SOLANACEOUS
- 11.3.3 CUCURBITS
- 11.3.4 BRASSICAS
- 11.3.5 LEAFY VEGETABLES
- 11.3.6 ROOT, BULB & TUBER VEGETABLES
- 11.3.7 OTHER VEGETABLES
- 11.4 FLOWERS & ORNAMENTALS
- 11.4.1 SEED COATING PROMOTES UNIFORM SEEDLING GROWTH
- 11.5 OILSEEDS & PULSES
- 11.5.1 SEED COATING INCREASES SURVIVAL OF BENEFICIAL BACTERIA IN OILSEEDS & PULSES
- 11.5.2 SOYBEAN
- 11.5.3 CANOLA
- 11.5.4 COTTON
- 11.5.5 SUNFLOWER
- 11.5.6 OTHER OILSEED & PULSES
- 11.6 OTHER CROP TYPES
12 SEED COATING MARKET, BY FORM
- 12.1 INTRODUCTION
- 12.2 LIQUID
- 12.2.1 LIQUID FORM PROVIDES UNIFORM COVERAGE, PROMOTES SEED HANDLING, AND ENHANCES SOWABILITY
- 12.3 POWDER
- 12.3.1 POWDER SEED COATINGS HELP IN ADDING WEIGHT TO LIGHT SEEDS
13 SEED COATING MARKET, BY PROCESS TYPE
- 13.1 INTRODUCTION
- 13.2 FILM COATING
- 13.2.1 INNOVATIONS IN SUSTAINABLE FILM COATING SOLUTIONS
- 13.3 PELLETING
- 13.3.1 PELLETING ENABLES PRECISE APPLICATION OF PLANT PROTECTION PRODUCTS
- 13.4 ENCRUSTING
- 13.4.1 ENCRUSTING ENHANCES ACCURACY AND EFFICIENCY OF MECHANICAL SOWING
14 SEED COATING MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Advancements in seed coating technologies to drive market
- 14.2.2 CANADA
- 14.2.2.1 Government support to drive market
- 14.2.3 MEXICO
- 14.2.3.1 Expansion of production of crops will boost demand for seed coating in Mexico
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 FRANCE
- 14.3.1.1 Country's sustainable agriculture targets to increase use of seed coating
- 14.3.2 GERMANY
- 14.3.2.1 Regulatory standards and innovation to drive seed coating market growth in Germany
- 14.3.3 UK
- 14.3.3.1 Improving crop production efficiency will boost demand
- 14.3.4 ITALY
- 14.3.4.1 Country's leadership in seed production will drive market
- 14.3.5 SPAIN
- 14.3.5.1 Climate variations will drive demand for seed coating
- 14.3.6 REST OF EUROPE
- 14.3.1 FRANCE
- 14.4 ASIA PACIFIC
- 14.4.1 CHINA
- 14.4.1.1 Growing seed treatment area in China to drive market growth
- 14.4.2 JAPAN
- 14.4.2.1 Country's export goals will drive market
- 14.4.3 INDIA
- 14.4.3.1 Government initiatives and technological advancement to drive market
- 14.4.4 AUSTRALIA & NEW ZEALAND
- 14.4.4.1 Growing emphasis on sustainable agriculture and improvement of seed performance to drive market
- 14.4.5 REST OF ASIA PACIFIC
- 14.4.1 CHINA
- 14.5 SOUTH AMERICA
- 14.5.1 BRAZIL
- 14.5.1.1 Expanding agricultural output and expansion by key players in Brazil to drive market
- 14.5.2 ARGENTINA
- 14.5.2.1 Partnership between companies to drive market demand
- 14.5.3 REST OF SOUTH AMERICA
- 14.5.1 BRAZIL
- 14.6 REST OF THE WORLD (ROW)
- 14.6.1 AFRICA
- 14.6.1.1 Expansion of Certified Seed Adoption to Drive Seed Coating Demand
- 14.6.2 MIDDLE EAST
- 14.6.2.1 Water Scarcity and Climate Stress to Drive Adoption of Advanced Seed Coatings
- 14.6.1 AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 15.3 ANNUAL REVENUE ANALYSIS
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.4.1 BASF SE
- 15.4.2 CRODA INTERNATIONAL PLC
- 15.4.3 CLARIANT
- 15.4.4 SYENSQO
- 15.4.5 SENSIENT TECHNOLOGIES CORPORATION
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.5.5.1 Company footprint
- 15.5.5.2 Region footprint
- 15.5.5.3 Additive type footprint
- 15.5.5.4 Process type footprint
- 15.5.5.5 Form footprint
- 15.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.6.1 PROGRESSIVE COMPANIES
- 15.6.2 RESPONSIVE COMPANIES
- 15.6.3 DYNAMIC COMPANIES
- 15.6.4 STARTING BLOCKS
- 15.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.6.5.1 Detailed list of key startups/SMEs
- 15.6.5.2 Competitive benchmarking of key startups/SMEs
- 15.7 COMPANY VALUATION AND FINANCIAL METRICS
- 15.8 BRAND/PRODUCT/SERVICE ANALYSIS
- 15.9 COMPETITIVE SCENARIO AND TRENDS
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 BASF SE
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Solutions/Services offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches
- 16.1.1.3.2 Deals
- 16.1.1.3.3 Expansions
- 16.1.1.4 MnM view
- 16.1.1.4.1 Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses and competitive threats
- 16.1.2 SYENSQO
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Solutions/Services offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Deals
- 16.1.2.4 MnM view
- 16.1.2.4.1 Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses and competitive threats
- 16.1.3 CLARIANT
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Solutions/Services offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Deals
- 16.1.3.4 MnM view
- 16.1.3.4.1 Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses and competitive threats
- 16.1.4 CRODA INTERNATIONAL PLC
- 16.1.4.1 Business overview
- 16.1.4.2 Products/Solutions/Services offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Product launches
- 16.1.4.3.2 Deals
- 16.1.4.4 MnM view
- 16.1.4.4.1 Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses and competitive threats
- 16.1.5 SENSIENT TECHNOLOGIES CORPORATION
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Solutions/Services offered
- 16.1.5.2.1 Deals
- 16.1.5.3 MnM view
- 16.1.5.3.1 Right to win
- 16.1.5.3.2 Strategic choices
- 16.1.5.3.3 Weaknesses and competitive threats
- 16.1.6 COVESTRO AG
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Solutions/Services offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Deals
- 16.1.6.4 MnM view
- 16.1.7 GERMAINS SEED TECHNOLOGY
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Solutions/Services offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.7.4 MnM view
- 16.1.8 MILLIKEN
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Solutions/Services offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Product launches
- 16.1.8.4 MnM view
- 16.1.9 BRETTYOUNG
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Solutions/Services offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Expansions
- 16.1.9.4 MnM view
- 16.1.10 CHROMATECH INCORPORATED
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Solutions/Services offered
- 16.1.10.3 MnM view
- 16.1.11 CENTOR GROUP
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Solutions/Services offered
- 16.1.11.3 MnM view
- 16.1.12 MICHELMAN, INC.
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Solutions/Services offered
- 16.1.12.3 MnM view
- 16.1.13 PRECISION LABS
- 16.1.13.1 Business overview
- 16.1.13.2 Products/Solutions/Services offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 Deals
- 16.1.13.4 MnM view
- 16.1.14 CR MINERALS COMPANY, LLC
- 16.1.14.1 Business overview
- 16.1.14.2 Products/Solutions/Services offered
- 16.1.14.3 MnM view
- 16.1.15 UNIVERSAL COATING SYSTEMS, LLC
- 16.1.15.1 Business overview
- 16.1.15.2 Products/Solutions/Services offered
- 16.1.15.3 MnM view
- 16.1.1 BASF SE
- 16.2 OTHER PLAYERS (SMES/STARTUPS)
- 16.2.1 SMITH SEED SERVICES
- 16.2.1.1 Business overview
- 16.2.1.2 Products/Solutions/Services offered
- 16.2.2 LITTLE'S AGRIVET
- 16.2.2.1 Business overview
- 16.2.3 ALFAGEN SEEDS COMPANY PTY LTD.
- 16.2.3.1 Business overview
- 16.2.3.2 Products/Solutions/Services offered
- 16.2.4 AGATHOS BV
- 16.2.4.1 Business overview
- 16.2.4.2 Product/Solutions/Services offered
- 16.2.5 SP COLOUR & CHEMICALS
- 16.2.5.1 Business overview
- 16.2.5.2 Products/Solutions/Services offered
- 16.2.6 ORGANIC DYES AND PIGMENTS LLC
- 16.2.7 BIOWEG
- 16.2.8 SOUTHERN ENTERPRISES
- 16.2.9 SEEDPOLY BIOCOATINGS PRIVATE LIMITED
- 16.2.10 CISTRONICS TECHNOVATIONS PVT LTD.
- 16.2.1 SMITH SEED SERVICES
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 List of major secondary sources
- 17.1.1.2 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.2.3 Breakdown of primaries
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 BOTTOM-UP APPROACH
- 17.2.2 TOP-DOWN APPROACH
- 17.2.2.1 Approach to estimate market size using top-down analysis
- 17.3 DATA TRIANGULATION
- 17.4 RESEARCH ASSUMPTIONS
- 17.5 RESEARCH LIMITATIONS AND RISK ASSESSMENT
18 ADJACENT AND RELATED MARKETS
- 18.1 INTRODUCTION
- 18.2 LIMITATIONS
- 18.3 SEED MARKET
- 18.3.1 MARKET DEFINITION
- 18.3.2 MARKET OVERVIEW
- 18.4 SEED TREATMENT MARKET
- 18.4.1 MARKET DEFINITION
- 18.4.2 MARKET OVERVIEW
19 APPENDIX
- 19.1 DISCUSSION GUIDE
- 19.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.3 CUSTOMIZATION OPTIONS
- 19.4 RELATED REPORTS
- 19.5 AUTHOR DETAILS