|
시장보고서
상품코드
2126789
콘크리트용 고성능 감수제 시장 예측(-2031년) : 제품 형태, 제품 유형, 용도, 지역별Concrete Superplasticizers Market by Product Form, Product Type, Application, and Region - Global Forecast to 2031 |
||||||

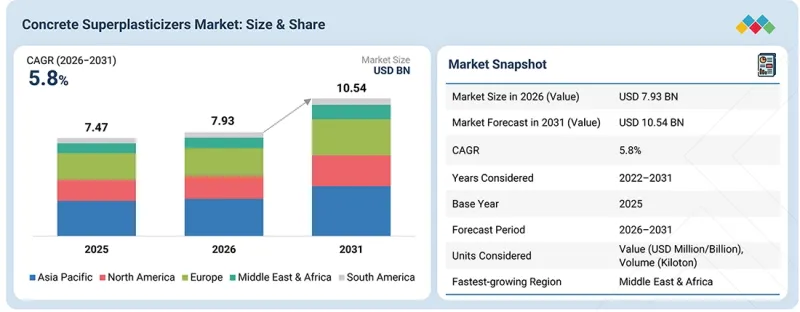
세계의 콘크리트용 고성능 감수제 시장 규모는 2026년 79억 3,000만 달러에서 2031년에는 105억 4,000만 달러로 성장하며, 예측 기간 중 CAGR 5.8%를 기록할 것으로 전망되고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러) , 킬로톤 |
| 부문 | 제품 형태, 제품 유형, 용도, 지역 |
| 대상 지역 | 아시아태평양, 북미, 유럽, 중동 및 아프리카, 남미 |
콘크리트용 고성능 감수제 시장은 인프라 투자 확대, 급속한 도시화, 레디믹스 콘크리트, 프리캐스트 콘크리트, 자가충진 콘크리트, 고강도 콘크리트, 고성능 콘크리트의 채택 증가에 힘입어 급속한 성장을 달성하고 있습니다. 특히 PCE(폴리카복실산 에테르) 계열 고성능 감수제의 사용을 통해 물-시멘트 비율을 낮게 유지하면서 시공성, 내구성, 강도, 펌프 송출성 향상을 추구하는 수요가 시장 성장을 지원하고 있습니다. 또한 고성능 감수제를 통해 콘크리트 성능을 높이고, 보조 시멘트계 재료(SCM)의 사용을 가능하게 함으로써 시멘트 사용량 및 매립 탄소 감축을 추구하는 움직임도 시장 성장 요인으로 작용하고 있습니다. 한편, 제조사들은 특히 석유화학계 원자재의 가격 변동에 직면해 있으며, 이는 이익률과 제품 가격에 압박 요인으로 작용하고 있습니다. 또한 시멘트의 유형나 보충 시멘트계 재료의 품질도 혼화제와의 궁합이나 콘크리트 성능에 영향을 미칠 가능성이 있으며, 배합의 복잡성을 더하고 있습니다. 또한 엄격한 건설 요건, 지역별 기술 규제의 차이, 기후 차이, 용도별 특화된 배합 설계의 필요성으로 인해 지속적인 연구개발, 현장 시험, 기술 지원이 요구되어 제조사의 비용 증가로 이어지고 있습니다.
"제품 유형별로는 예측 기간 중 폴리카복실산 유도체 부문이 가장 큰 시장 점유율을 차지할 것으로 예상됩니다."
폴리카복실산 유도체는 기존 화학계 고성능 감수제와 비교하여 우수한 특성을 갖추고 있으며, 최대 제품 유형 부문이 될 것으로 추정됩니다. 그 분자 구조 덕분에 입체 장애를 통해 시멘트 입자를 분산시킬 수 있으며, 콘크리트의 유동성을 저해하지 않으면서 낮은 수시멘트비를 실현할 수 있습니다. 폴리카복실산염은 슬럼프 유지성, 초기 강도, 자가충진 콘크리트, 장거리 운송 등 특정 특성에 맞춰 설계할 수 있습니다. 또한 보조 시멘트제와의 궁합이 좋아 폴리카복실산염의 채택이 증가하고 있습니다. 또한 각 제조사는 표준 콘크리트, 고강도 콘크리트, 유동성 콘크리트, 프리캐스트 콘크리트 등 다양한 시장에 어필하기 위해 새로운 PCE 등급을 지속적으로 개발하고 있습니다.
용도별로는 예측 기간 중 레디믹스 콘크리트 분야가 가장 큰 시장 점유율을 차지할 것으로 전망됩니다.
레디믹스 콘크리트는 제조 및 운송 공정에서 시공성, 응결 시간, 수분량, 품질은 물론 최종 제품의 함수 상태를 안정적으로 관리할 수 있으므로 가장 큰 시장 점유율을 차지하고 있습니다. 고성능 감수제, 특히 폴리카복실산 에테르(PCE) 계열 제품을 사용함으로써 레디믹스 콘크리트 제조업체는 강도와 내구성을 유지하면서 유동성을 향상시킬 수 있습니다. 레디믹스 콘크리트는 건설 현장과 떨어진 곳에서 제조되는 경우가 있으며, 배합부터 시공까지 걸리는 시간이 길어질 가능성이 있으므로 이는 특히 중요하며, 그로 인해 슬럼프 유지 시간을 연장할 수 있는 혼화제에 대한 수요가 높아지고 있습니다. PCE는 운송 중이거나 철근 주위에 콘크리트를 펌프로 주입해야 하는 경우에도 시공성을 유지할 수 있습니다. 또한 레디믹스 콘크리트 제조업체는 인프라, 주택, 상업, 산업 분야의 건설 공사와 관련된 프로젝트에 많이 참여하고 있으며, 안정적인 품질의 콘크리트를 대량으로 공급할 수 있습니다. 레디믹스 콘크리트용으로 특별히 설계된 PCE 등급이 등장함에 따라 레디믹스트 부문은 업계에서 매우 견고한 입지를 구축하고 있습니다.
"아시아태평양은 예측 기간 중 가장 큰 시장 점유율을 차지할 것으로 예상됩니다."
아시아태평양은 매우 활발한 건설 활동, 광범위한 인프라 개발, 급속한 도시화, 레디믹스 콘크리트 생산 확대가 맞물려 최대 지역 시장이 되었습니다. 중국과 인도는 주요 수요 거점이며, 교통, 주택, 산업 시설, 도시 인프라, 에너지 프로젝트에 대한 대규모 투자가 이를 지원하고 있습니다. 중국만 해도 2025년에는 고속철도가 2,862km, 신규 또는 개보수된 고속도로가 8,699km 연장될 예정이며, 이는 콘크리트를 대량으로 소비하는 인프라 활동의 규모를 보여줍니다. 인도에서도 강력한 인프라 개발이 진행되고 있을 뿐만 아니라, 인도네시아나 베트남과 같은 동남아시아 국가들에서도 도시 인프라와 교통 인프라가 확충되고 있습니다. 이 지역의 거대한 인구 규모, 도시 지역의 주택 수요 증가, 레디믹스 콘크리트, 프리캐스트 콘크리트, 고강도 콘크리트, 자가충진 콘크리트의 채택 확대에 따라 고성능 혼화제에 대한 수요는 더욱 높아지고 있습니다. 또한 국내외 주요 혼합제 제조사의 존재와 확대되는 현지 생산 능력이 공급의 안정성을 높여, 아시아태평양의 주도적 지위를 지원하고 있습니다.
이 보고서에서는 전 세계 콘크리트용 고성능 감수제 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 각종 요인 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 구상
제8장 고객 상황과 구매 행동
제9장 콘크리트용 고성능 감수제 시장 : 제품 형태별
제10장 콘크리트용 고성능 감수제 시장 : 제품 유형별
제11장 콘크리트용 고성능 감수제 시장 : 용도별
제12장 콘크리트용 고성능 감수제 시장 : 지역별
제13장 경쟁 구도
제14장 기업 개요
제15장 조사 방법
제16장 부록
KSAThe global concrete superplasticizers market is projected to grow from USD 7.93 billion in 2026 to USD 10.54 billion by 2031, registering a CAGR of 5.8% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion), Volume (Kiloton) |
| Segments | Product Form, Product Type, Application, and Region |
| Regions covered | Asia Pacific, North America, Europe, Middle East & Africa, and South America |
The concrete superplasticizers market is witnessing an upsurge due to rising investment in infrastructure, rapid urbanization, and increased adoption of ready-mixed, precast, self-compacting, high-strength, and high-performance concrete. Demand is fueled by the need for enhanced workability, durability, strength, and pumpability while maintaining a lower water-cement ratio, especially through the use of PCE-based (Polycarboxylate ether) superplasticizers. Another driver is the desire to reduce cement use and embodied carbon, as effective superplasticizers can boost performance and enable the use of supplementary cementitious materials. Nonetheless, producers face fluctuations in raw material prices, especially for petrochemical-based materials, which pressure margins and product pricing. Different cement types and the quality of supplementary cementitious materials may also influence admixture compatibility and concrete performance, adding to formulation complexity. Furthermore, strict construction requirements, regional variations in technical regulations, climatic differences, and the need for specific formulations necessitate ongoing research, field testing, and support, increasing costs for producers.

"By product type, the polycarboxylate derivatives segment is anticipated to account for the largest market share during the forecast period."
Polycarboxylate derivatives are estimated to be the largest product-type segment in the concrete superplasticizers market because of their superior properties over traditional chemistries. Their molecular structures allow them to disperse cement particles through steric hindrance, enabling users to achieve a low water-to-cement ratio without compromising concrete flowability. Polycarboxylates can be engineered for particular properties such as slump retention, early strength, self-compacting concrete, and long-distance transportation. Because they are compatible with supplementary cementing agents, the adoption of polycarboxylates is increasing. In addition, manufacturers continue to develop new PCE grades to appeal to different markets, including standard, high-strength, flowable, and precast concrete.
By application, the ready-mix concrete segment is anticipated to account for the largest market share during the forecast period.
Ready-mix concrete holds the largest application segment market share because its manufacturing and delivery provide a reliable way to control workability, setting time, water content, and quality, as well as the final product's humidity. Superplasticizers, particularly polycarboxylate ether (PCE) types, allow ready-mix concrete producers to improve flowability while maintaining strength and durability. This is especially important because ready-mix concrete may be produced far from the construction site, and the time gap between mix preparation and application can be long, increasing demand for admixtures that extend slump retention. PCEs can maintain workability during transportation and when concrete needs to be pumped around reinforcement. Moreover, ready-mix concrete producers are often engaged in projects involving construction works in infrastructure, residential, commercial, and industrial areas, which can provide a huge amount of concrete with stable quality. With the arrival of specially designed PCE grades for ready-mix concrete production, the ready-mix sector becomes very strong in the industry.
"Asia Pacific is anticipated to account for the largest market share during the forecast period.
Asia Pacific is the largest regional market for concrete superplasticizers because it combines exceptionally high construction activity, extensive infrastructure development, rapid urbanization, and expanding ready-mix concrete production. China and India are the primary demand centers, supported by large-scale investments in transportation, housing, industrial facilities, urban infrastructure, and energy projects. China alone added 2,862 km of high-speed railway and 8,699 km of new or rebuilt highways in 2025, demonstrating the scale of concrete-intensive infrastructure activity. India is also witnessing strong infrastructure development, while Southeast Asian economies such as Indonesia and Vietnam are expanding urban and transportation infrastructure. The region's large population, increasing urban housing requirements, and growing adoption of ready-mix, precast, high-strength, and self-compacting concrete further increase demand for high-performance admixtures. Additionally, major domestic and international admixture manufacturers and expanding local production capacity strengthen supply availability and support Asia Pacific's leading position.
In-depth interviews were conducted with chief executive officers (CEOs), marketing directors, other innovation and technology directors, and executives from various key organizations operating in the concrete superplasticizers market, and information was gathered from secondary research to determine and verify the market size of several segments.
- By Company Type: Tier 1 - 50%, Tier 2 - 30%, and Tier 3 - 20%
- By Designation: Managers - 15%, Directors - 20%, and Others - 65%
- By Region: North America - 35%, Europe - 30%, Asia Pacific - 25%, Middle East & Africa - 5%, and South America- 5%
The concrete superplasticizers market comprises major companies, such as Sika AG (Switzerland), Compagnie de Saint-Gobain S.A. (France), Kao Corporation (Japan), Cemex, S.A.B. de C.V. (Mexico), Arkema SA (France), The Euclid Chemical Company (US), Mapei S.p.A. (Italy), Master Builders Solutions Holdings GmbH (Germany), MC-Bauchemie Muller GmbH & Co. KG (Germany), and Shandong Wotai Chemical Co., Ltd (China). The study includes an in-depth competitive analysis of these key players in the concrete superplasticizers market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This report segments the concrete superplasticizers market on the basis of product type, product form, application and region, and provides estimations for the overall value of the market across various regions. A detailed analysis of key industry players provides insights into their business overviews, products & services, key strategies, and expansions in the concrete superplasticizers market.
Key benefits of buying this report
This research report is focused on various levels of analysis-industry analysis (industry trends), market ranking analysis of top players, and company profiles, which together provide an overall view of the competitive landscape; emerging and high-growth segments of the concrete superplasticizers market; high-growth regions; and market drivers, restraints, opportunities, and challenges.
The report provides insights into the following points:
- Analysis of drivers (low-carbon concrete is accelerating demand for advanced PCE superplasticizers), restraints (price-sensitive construction markets continue to limit premium PCE penetration), opportunities (LC3 and calcined-clay concrete create a new high-margin compatibility frontier), and challenges (maintaining consistent performance across diverse regional cement chemistries remains technically demanding).
- Market Penetration: Comprehensive information on the concrete superplasticizers offered by top players in the global concrete superplasticizers market.
- Product Development/Innovation: Detailed insights on upcoming technologies, product launches, expansions, and acquisitions in the concrete superplasticizers market.
- Market Development: Comprehensive information about lucrative emerging markets; the report analyzes the markets for concrete superplasticizers across regions.
- Market Capacity: Production capacity of the companies is provided wherever available, with upcoming capacities for the concrete superplasticizers market.
- Competitive Assessment: In-depth assessment of market shares, strategies, products, and manufacturing capabilities of leading players in the concrete superplasticizers market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN CONCRETE SUPERPLASTICIZERS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN CONCRETE SUPERPLASTICIZERS MARKET
- 3.2 CONCRETE SUPERPLASTICIZERS MARKET, BY PRODUCT FORM AND REGION
- 3.3 CONCRETE SUPERPLASTICIZERS MARKET, BY PRODUCT TYPE
- 3.4 CONCRETE SUPERPLASTICIZERS MARKET, BY APPLICATION
- 3.5 CONCRETE SUPERPLASTICIZERS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rapid transition toward low-carbon concrete to advance sustainable construction
- 4.2.1.2 Evolving concrete placement logistics amid rapid urbanization
- 4.2.1.3 Growing emphasis on industrialized precast production
- 4.2.1.4 Increasing infrastructure durability compliance requirements
- 4.2.1.5 Mounting adoption of self-compacting and high-performance concrete
- 4.2.2 RESTRAINTS
- 4.2.2.1 Price sensitivity in developing countries
- 4.2.2.2 Variability in cement and SCM chemistry
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Emergence of LC3 and other calcined-clay-rich binders
- 4.2.3.2 Rising development of carbon-performance-based admixtures
- 4.2.3.3 Increasing interest in recycled aggregate concrete due to circular construction policies
- 4.2.3.4 Strong focus on digital admixture dosage optimization
- 4.2.4 CHALLENGES
- 4.2.4.1 Issues in maintaining consistent performance across diverse regional cement chemistries
- 4.2.4.2 Volatility in petrochemical and specialty-chemical feedstocks
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL INFRASTRUCTURE INDUSTRY
- 5.2.4 TRENDS IN GLOBAL CONSTRUCTION INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 PRICING ANALYSIS
- 5.4.1 AVERAGE SELLING PRICE TREND OF CONCRETE SUPERPLASTICIZERS, BY REGION, 2022-2025
- 5.4.2 AVERAGE SELLING PRICE TREND OF CONCRETE SUPERPLASTICIZERS, BY PRODUCT FORM, 2022-2025
- 5.4.3 AVERAGE SELLING PRICE TREND OF CONCRETE SUPERPLASTICIZERS, BY PRODUCT TYPE, 2022-2025
- 5.4.4 AVERAGE SELLING PRICE TREND OF CONCRETE SUPERPLASTICIZERS, BY APPLICATION, 2022-2025
- 5.4.5 AVERAGE SELLING PRICE OF CONCRETE SUPERPLASTICIZERS OFFERED BY KEY PLAYERS, BY PRODUCT FORM, 2025
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 382340)
- 5.6.2 EXPORT SCENARIO (HS CODE 382340)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 SIKA AG AND READY-MIX PRODUCERS COLLABORATION FOR LOW-CARBON HIGH-RETENTION CONCRETE
- 5.10.2 MASTER BUILDERS SOLUTIONS AND PRECAST MANUFACTURERS COLLABORATION FOR RAPID DEMOLDING SYSTEMS
- 5.10.3 CHRYSO, INFRASTRUCTURE CONTRACTORS, AND READY-MIX SUPPLIERS COLLABORATION FOR DURABLE METRO AND BRIDGE CONCRETE
- 5.11 IMPACT OF US TARIFFS - CONCRETE SUPERPLASTICIZERS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON REGIONS
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON APPLICATIONS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 POLYCARBOXYLATE ETHER POLYMER ARCHITECTURE
- 6.1.2 SULFONATED NAPHTHALENE FORMALDEHYDE CHEMICAL SYNTHESIS
- 6.1.3 CLAY-MITIGATING SACRIFICIAL POLYMER
- 6.1.4 VISCOSITY MODIFYING ADMIXTURE
- 6.1.5 CONTROLLED SLUMP-RETENTION ESTER HYDROLYSIS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 AUTOMATED IOT-ENABLED IN-TRANSIT DOSING
- 6.2.2 LIMESTONE CALCINED CLAY CEMENT ACTIVATION
- 6.2.3 NON-CHLORIDE HYDRATION ACCELERATOR
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 3D CONCRETE PRINTING EXTRUSION
- 6.3.2 CARBON CAPTURE, UTILIZATION, AND STORAGE MINERALIZATION
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 TAILOR-MADE PCE ARCHITECTURES
- 6.4.2 CONTROLLED ESTER HYDROLYSIS
- 6.4.3 CLAY-MITIGATING SACRIFICIAL POLYMERS
- 6.4.4 IOT-ENABLED AUTOMATED IN-TRANSIT DOSING PLATFORMS
- 6.4.5 HYPER-RESPONSIVE ADMIXTURE SYSTEMS FOR 3D CONCRETE PRINTING
- 6.5 PATENT ANALYSIS
- 6.5.1 METHODOLOGY
- 6.5.2 GRANTED PATENTS, 2016-2025
- 6.5.3 INSIGHTS
- 6.5.4 LEGAL STATUS
- 6.5.5 JURISDICTION ANALYSIS
- 6.5.6 TOP APPLICANTS
- 6.5.7 LIST OF MAJOR PATENTS
- 6.6 FUTURE APPLICATIONS
- 6.7 IMPACT OF AI/GEN AI ON CONCRETE SUPERPLASTICIZERS MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES FOLLOWED BY OEMS IN CONCRETE SUPERPLASTICIZERS MARKET
- 6.7.3 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN CONCRETE SUPERPLASTICIZERS MARKET
- 6.7.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENTS' READINESS TO ADOPT AI/GEN AI-INTEGRATED CONCRETE SUPERPLASTICIZERS
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.8.1 SIKA AG: SUSTAINABLE & HIGH-PERFORMANCE POLYCARBOXYLATE ETHER (PCE) SOLUTIONS FOR HIGH-RISE CONCRETE
- 6.8.2 MASTER BUILDERS SOLUTIONS: SPECIALTY SUPERPLASTICIZER INNOVATION FOR PRECAST CONCRETE AND HEAVY CIVIL INFRASTRUCTURE
- 6.8.3 MAPEI S.P.A.: HIGH-PERFORMANCE POLYMER ADMIXTURES FOR SELF-COMPACTING CONCRETE AND INDUSTRIAL APPLICATIONS
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 ENABLING LC3 AND LOW-CLINKER BINDERS
- 7.2.2 TRANSITIONING TO BIO-BASED AND RENEWABLE PCE FEEDSTOCKS
- 7.2.3 FACILITATING EXTREME CEMENT REDUCTION AND WATER CONSERVATION
- 7.2.4 OPTIMIZING CIRCULAR ECONOMY INTEGRATION AND MANUFACTURED AGGREGATES
- 7.2.5 ENHANCING LONG-TERM DURABILITY AND LIFECYCLE PERFORMANCE
- 7.3 IMPACT OF SUSTAINABILITY INITIATIVES ON REGULATORY POLICIES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS APPLICATIONS
- 8.5 MARKET PROFITABILITY
- 8.5.1 PREMIUM PRICING IN SPECIALTY FORMULATIONS
- 8.5.2 VALUE CREATION IN PRECAST MANUFACTURING
- 8.5.3 RAW MATERIAL VOLATILITY AND MARGIN COMPRESSION
- 8.5.4 TRANSITION TO HIGH-MARGIN DIGITAL SERVICE MODELS
- 8.5.5 REGULATORY COMPLIANCE AS ECONOMIC MOAT
9 CONCRETE SUPERPLASTICIZERS MARKET, BY PRODUCT FORM
- 9.1 INTRODUCTION
- 9.2 LIQUID
- 9.2.1 AUTOMATED DISPENSING EFFICIENCIES AND HIGH-WATER REDUCTION TO BOLSTER SEGMENTAL GROWTH
- 9.3 POWDER
- 9.3.1 DRY-MIX INTEGRATION AND LONG-DISTANCE LOGISTICAL ADVANTAGES TO FUEL SEGMENTAL GROWTH
10 CONCRETE SUPERPLASTICIZERS MARKET, BY PRODUCT TYPE
- 10.1 INTRODUCTION
- 10.2 POLYCARBOXYLATE DERIVATIVES (PCD)
- 10.2.1 STERIC HINDRANCE ARCHITECTURE DRIVING LOW-CARBON BINDER COMPATIBILITY AND WATER REDUCTION TO SPUR DEMAND
- 10.3 SULFONATED NAPHTHALENE FORMALDEHYDE (SNF)
- 10.3.1 COST-EFFECTIVENESS OF ELECTROSTATIC DISPERSION DESPITE TIGHTENING REGULATORY CONTROLS TO FUEL SEGMENTAL GROWTH
- 10.4 SULFONATED MELAMINE FORMALDEHYDE (SMF)
- 10.4.1 COLOURLESS, HIGH EARLY-STRENGTH PERFORMANCE TO ACCELERATE SEGMENTAL GROWTH
- 10.5 MELAMINE-LIGNOSULFONATE (MLS)
- 10.5.1 HYBRID PLASTICIZING CHEMISTRIES BALANCING BASE-LEVEL ECONOMY WITH WORKABILITY RETENTION TO BOOST SEGMENTAL GROWTH
- 10.6 OTHER PRODUCT TYPES
11 CONCRETE SUPERPLASTICIZERS MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 READY-MIX CONCRETE
- 11.2.1 EXTENDED SLUMP LIFE AND PUMPING RHEOLOGY TO CONTRIBUTE TO SEGMENTAL GROWTH
- 11.3 PRECAST CONCRETE
- 11.3.1 EARLY COMPRESSIVE STRENGTH OPTIMIZATION MAXIMIZING INDUSTRIAL PLANT THROUGHPUT TO FOSTER SEGMENTAL GROWTH
- 11.4 HIGH-PERFORMANCE CONCRETE
- 11.4.1 ULTRA-LOW WATER-TO-BINDER ENGINEERING ENABLING SUPER-TALL AND MARINE INFRASTRUCTURE TO SPUR DEMAND
- 11.5 OTHER APPLICATIONS
12 CONCRETE SUPERPLASTICIZERS MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 ASIA PACIFIC
- 12.2.1 CHINA
- 12.2.1.1 Increasing cement and precast concrete production to accelerate market growth
- 12.2.2 JAPAN
- 12.2.2.1 Rising urban high-rise redevelopment and maintenance of aging coastal protection structures to fuel market growth
- 12.2.3 INDIA
- 12.2.3.1 Expanding cement sector, highway expansions, railway modernization, and urban developments to drive market
- 12.2.4 SOUTH KOREA
- 12.2.4.1 Shifting preference toward precast and modular construction methodologies to boost market growth
- 12.2.5 REST OF ASIA PACIFIC
- 12.2.1 CHINA
- 12.3 NORTH AMERICA
- 12.3.1 US
- 12.3.1.1 Strong focus on modernization of aging highways, bridges, and critical water systems to foster market growth
- 12.3.2 CANADA
- 12.3.2.1 Rising funding for commercialization of bio-based polymers and pozzolanic materials to augment market growth
- 12.3.3 MEXICO
- 12.3.3.1 Strategic government-led infrastructure investments to contribute to market growth
- 12.3.1 US
- 12.4 EUROPE
- 12.4.1 GERMANY
- 12.4.1.1 Federal infrastructure initiatives and push toward circular construction economy to foster market growth
- 12.4.2 ITALY
- 12.4.2.1 Increasing funding dedicated to transport infrastructure modernization to accelerate market growth
- 12.4.3 FRANCE
- 12.4.3.1 Unprecedented metropolitan infrastructure expansion and green building legislation to support market growth
- 12.4.4 UK
- 12.4.4.1 Government-backed transport mega-projects and net-zero emission targets to expedite market growth
- 12.4.5 SPAIN
- 12.4.5.1 High emphasis on structural durability across coastal regions to bolster market growth
- 12.4.6 TURKEY
- 12.4.6.1 Rising reconstruction and urban transformation initiatives to support market growth
- 12.4.7 REST OF EUROPE
- 12.4.1 GERMANY
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC
- 12.5.1.1 Saudi Arabia
- 12.5.1.1.1 Rapid integration of low-carbon blended cements and eco-friendly admixture technologies to drive market
- 12.5.1.2 UAE
- 12.5.1.2.1 Implementation of green building frameworks to accelerate market growth
- 12.5.1.3 Rest of GCC
- 12.5.1.1 Saudi Arabia
- 12.5.2 SOUTH AFRICA
- 12.5.2.1 Mounting adoption of circular construction practices to contribute to market growth
- 12.5.3 REST OF MIDDLE EAST & AFRICA
- 12.5.1 GCC
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 Increasing investment in comprehensive infrastructure networks to augment market growth
- 12.6.2 ARGENTINA
- 12.6.2.1 Growing demand for high-performance, compliant ready-mix concrete to foster market growth
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.2 KEY PLAYER COMPETITIVE STRATEGIES/ RIGHT TO WIN, 2022-2026
- 13.3 MARKET SHARE ANALYSIS, 2025
- 13.4 REVENUE ANALYSIS, 2022-2025
- 13.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.5.1 STARS
- 13.5.2 EMERGING LEADERS
- 13.5.3 PERVASIVE PLAYERS
- 13.5.4 PARTICIPANTS
- 13.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.5.5.1 Company footprint
- 13.5.5.2 Region footprint
- 13.5.5.3 Product form footprint
- 13.5.5.4 Product type footprint
- 13.5.5.5 Application footprint
- 13.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.6.1 PROGRESSIVE COMPANIES
- 13.6.2 RESPONSIVE COMPANIES
- 13.6.3 DYNAMIC COMPANIES
- 13.6.4 STARTING BLOCKS
- 13.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES
- 13.6.5.1 Detailed list of key startups/SMEs
- 13.6.5.2 Competitive benchmarking of key startups/SMEs
- 13.7 BRAND/PRODUCT COMPARISON
- 13.7.1 SIKA AG (SWITZERLAND)
- 13.7.2 COMPAGNIE DE SAINT-GOBAIN S.A. (FRANCE)
- 13.7.3 MASTER BUILDERS SOLUTIONS GMBH (GERMANY)
- 13.7.4 MAPEI S.P.A. (ITALY)
- 13.7.5 THE EUCLID CHEMICAL COMPANY (US)
- 13.8 COMPANY VALUATION AND FINANCIAL METRICS
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
- 13.9.3 EXPANSIONS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 SIKA AG
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Deals
- 14.1.1.3.2 Expansions
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths/Right to win
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses/Competitive threats
- 14.1.2 COMPAGNIE DE SAINT-GOBAIN S.A.
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product launches
- 14.1.2.3.2 Deals
- 14.1.2.3.3 Expansions
- 14.1.2.4 MnM view
- 14.1.2.4.1 Key strengths/Right to win
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses/Competitive threats
- 14.1.3 THE EUCLID CHEMICAL COMPANY
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 MnM view
- 14.1.3.3.1 Key strengths/Right to win
- 14.1.3.3.2 Strategic choices
- 14.1.3.3.3 Weaknesses/Competitive threats
- 14.1.4 MAPEI S.P.A.
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product launches
- 14.1.4.3.2 Expansions
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths/Right to win
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses/Competitive threats
- 14.1.5 MASTER BUILDERS SOLUTIONS HOLDING GMBH
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Deals
- 14.1.5.3.2 Expansions
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths/Right to win
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses/Competitive threats
- 14.1.6 KAO CORPORATION
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 MnM view
- 14.1.6.3.1 Key strengths/Right to win
- 14.1.6.3.2 Strategic choices
- 14.1.6.3.3 Weaknesses/Competitive threats
- 14.1.7 CEMEX S.A.B. DE C.V.
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Product launches
- 14.1.7.3.2 Expansions
- 14.1.7.4 MnM view
- 14.1.7.4.1 Key strengths/Right to win
- 14.1.7.4.2 Strategic choices
- 14.1.7.4.3 Weaknesses/Competitive threats
- 14.1.8 ARKEMA
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.8.3 MnM view
- 14.1.8.3.1 Key strengths/Right to win
- 14.1.8.3.2 Strategic choices
- 14.1.8.3.3 Weaknesses/Competitive threats
- 14.1.9 MC-BAUCHEMIE MULLER GMBH & CO. KG
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.9.3 Recent developments
- 14.1.9.3.1 Product launches
- 14.1.9.3.2 Expansions
- 14.1.9.4 MnM view
- 14.1.9.4.1 Key strengths/Right to win
- 14.1.9.4.2 Strategic choices
- 14.1.9.4.3 Weaknesses/Competitive threats
- 14.1.10 SHANDONG WOTAI CHEMICAL CO., LTD.
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.10.3 MnM view
- 14.1.10.3.1 Key strengths/Right to win
- 14.1.10.3.2 Strategic choices
- 14.1.10.3.3 Weaknesses/Competitive threats
- 14.1.1 SIKA AG
- 14.2 OTHER PLAYERS
- 14.2.1 JIAHUA CHEMICALS INC.
- 14.2.2 HA-BE BETONCHEMIE GMBH
- 14.2.3 CONMIX
- 14.2.4 CICO GROUP
- 14.2.5 JIANGSU SUBOTE NEW MATERIAL CO., LTD.
- 14.2.6 KZJ NEW MATERIALS GROUP CO., LTD.
- 14.2.7 NIPPON SHOKUBAI CO., LTD
- 14.2.8 LIAONING KELONG FINE CHEMICAL CO., LTD.
- 14.2.9 ENASPOL A.S.
- 14.2.10 PIDILITE INDUSTRIES LTD.
- 14.2.11 NORMET
- 14.2.12 MUHU (CHINA) CONSTRUCTION MATERIALS CO., LTD.
- 14.2.13 SHANDONG ZHUOXING CHEMICAL CO., LTD.
- 14.2.14 SILKROAD GROUP
- 14.2.15 RHEIN-CHEMOTECHNIK GMBH
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 List of key secondary sources
- 15.1.1.2 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 List of primary interview participants
- 15.1.2.3 Breakdown of primary interviews
- 15.1.2.4 Key industry insights
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 BOTTOM-UP APPROACH
- 15.2.2 TOP-DOWN APPROACH
- 15.2.3 MARKET SIZE CALCULATION FOR BASE YEAR
- 15.3 MARKET FORECAST APPROACH
- 15.3.1 SUPPLY SIDE
- 15.3.2 DEMAND SIDE
- 15.4 DATA TRIANGULATION
- 15.5 FACTOR ANALYSIS
- 15.6 RESEARCH ASSUMPTIONS
- 15.7 RESEARCH LIMITATIONS AND RISK ANALYSIS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS