|
시장보고서
상품코드
2126793
Drug Discovery용 AI 시장 예측(-2031년) : 프로세스별, AI 툴별, 최종사용자별, 사용 사례별, 배포별, 치료 분야별, 참여 조직 유형별, 지역별AI in Drug Discovery Market by Process (Target, Lead), Use Case (Repurposing, DE Novo Drug Design [Vaccine] Optimization, Disease Understanding, PK/PD), Therapy (Cancer, CNS), Tool (DL [CNN, GAN]), End User - Global Forecast to 2031 |
||||||

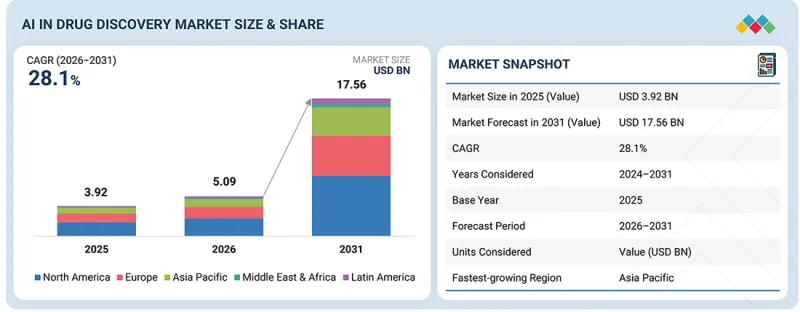
Drug Discovery 분야에서 AI 시장 규모는 2026년 50억 9,000만 달러에서 2031년까지 175억 6,000만 달러로 성장하며, 예측 기간 중 CAGR은 28.1%에 달할 것으로 전망되고 있습니다.
이 시장의 성장을 주도하는 요인은 연구개발(R&D) 생산성 향상을 위한 AI 도입 확대, 다중 모달 생물학적 데이터세트의 활용 확대, 그리고 정밀 의학 및 계산 기반 신약 개발에 대한 투자 확대입니다. 'Drug Discovery Today'지에 게재된 2025년 총설에 따르면 제약 연구개발의 생산성 저하는 바이오의약품 업계 전반에 걸쳐 혁신 전략의 재구성을 지속적으로 촉진하고 있으며, 각 기업은 연구 효율 향상과 신약 개발 가속화를 위해 AI를 활용한 플랫폼 도입을 더욱 적극적으로 추진하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 프로세스별, AI 툴별, 최종사용자별, 사용 사례별, 배포별, 치료 분야별, 참여 조직 유형별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
그러나 데이터 품질, 모델 검증, 규제상의 불확실성, 그리고 기존 제약 연구개발 워크플로우와의 통합과 관련된 과제들이 시장 도입 속도에 계속해서 영향을 미치고 있습니다.
2026-2031년에 기계학습이 AI 툴 부문에서 가장 빠르게 성장할 것으로 전망됩니다.
AI 툴별로는 제약 기업이 신약 개발 워크플로우 전반에 걸쳐 의사결정을 개선하기 위해 예측 알고리즘을 점점 더 많이 활용함에 따라 예측 기간 중 기계학습 부문이 가장 빠른 성장을 기록할 것으로 예상됩니다. 기계학습을 통해 복잡한 생물학적, 화학적, 임상적 데이터세트를 신속하게 분석할 수 있게 되어, 표적 식별, 유망 화합물의 우선순위 지정, 분자 특성 예측 및 선도 화합물의 최적화가 크게 향상됩니다. 딥러닝, 그래프 신경망, 생성형 AI의 지속적인 발전으로 인해 저분자 신약 개발, 생물제제 개발 및 정밀 의료 연구 분야에서 기계학습의 적용 범위는 더욱 확대되고 있습니다. 이러한 추세를 반영하여, 2026년 3월, NVIDIA는 생체 분자 연구 및 분자 설계를 가속화하기 위해 차세대 기반 모델과 에이전트형 AI 기능을 갖춘 BioNeMo 플랫폼을 확장했습니다. 제약사들이 더욱 신속한 신약 개발과 연구개발 효율 향상을 지속적으로 우선시하는 가운데, 머신러닝은 신약 개발 분야의 AI 시장에서 앞으로도 가장 빠르게 성장하는 기술 분야로 남을 것으로 예상됩니다.
2025년, 신약 개발 분야의 AI 시장에서 가장 큰 점유율을 차지한 것은 종양학 부문이었습니다.
치료 분야별로 보면 전 세계 암의 부담 규모, 광범위한 종양학 연구 파이프라인, 그리고 정밀 의학에 대한 수요 증가로 인해 2025년 신약 개발 AI 시장에서 종양학 분야가 가장 큰 점유율을 차지했습니다. 국제암연구소(IARC)에 따르면 전 세계 신규 암 환자 수는 2024년 2,060만 명에서 2050년까지 3,440만 명으로 증가할 것으로 예측되며, 이는 종양학 분야의 신약 개발을 가속화할 혁신적인 기술에 대한 수요가 높아지고 있음을 여실히 보여줍니다. AI는 새로운 치료 표적의 식별, 바이오마커 예측, 환자 계층화 최적화, 그리고 표적 치료제 및 면역종양학 치료제 신약 개발 가속화를 위해 폭넓게 활용되고 있습니다. 대규모 유전체, 전사체, 단백체 및 임상 데이터세트를 활용할 수 있게 됨에 따라 종양학은 가장 데이터가 풍부한 치료 분야 중 하나가 되었으며, AI 모델이 보다 정확하고 임상적으로 유용한 인사이트를 도출할 수 있게 되었습니다. 제약사들은 암 치료 분야의 막대한 상업적 잠재력과 맞춤형 암 치료에 대한 수요 증가를 배경으로, 연구개발 포트폴리오에서 계속해서 이 분야를 우선시하고 있습니다. AI 기업과 암 치료에 특화된 바이오의약품 기업 간의 협력이 확대됨에 따라 혁신이 더욱 가속화되고 있으며, 신약 개발 분야의 AI 시장에서 암 치료 분야가 주도적인 입지를 공고히 하고 있습니다.
예측 기간 중 유럽은 두 번째로 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다.
유럽은 제약 혁신에 대한 투자 증가, 생의학 연구에서의 AI 도입 확대, 그리고 신뢰할 수 있는 AI를 지원하는 견고한 규제 프레임워크에 힘입어 예측 기간 중 두 번째로 높은 성장률을 기록할 것으로 예상됩니다. 이 지역에는 표적 발견, 분자 설계, 정밀 의학에 대한 AI 통합을 가속화하고 있는 주요 제약 기업, 연구 기관 및 AI 기반 생명공학 기업이 거점을 두고 있습니다. 유럽 헬스 데이터 스페이스(EHDS) 및 EU AI 법의 도입으로 헬스 데이터에 대한 안전한 국경 간 접근이 촉진되는 동시에, 생명과학 분야의 AI 응용을 위한 통일된 거버넌스가 확립될 전망입니다. 이와 병행하여, 제안된 ‘클라우드·AI 개발법(CADA)’은 주권적 컴퓨팅 능력 확대, 고성능 컴퓨팅 리소스에 대한 접근성 개선, 그리고 의료·생명과학을 포함한 전략적 부문 전반에 걸친 AI 혁신 개발 지원을 통해 유럽의 클라우드 및 AI 인프라 강화를 목표로 하고 있습니다. 또한 ‘혁신적 헬스 구상(IHI)’와 같은 공동 프로그램에서는 LIGAND-AI를 포함한 AI 기반 신약 개발 프로젝트에 대한 자금 지원을 지속하고 있으며, 고품질의 생물학적 데이터세트와 첨단 AI 모델을 통해 치료법 연구를 가속화하고 있습니다. 이러한 노력들이 결합되어, 유럽은 신약 개발 분야의 AI 시장으로서 세계에서 두 번째로 빠른 성장 속도를 보이는 지역으로서의 위상을 더욱 공고히 할 것으로 기대됩니다.
주요 기업
신약 개발 분야의 AI 시장에서 사업을 운영하는 주요 기업으로는 NVIDIA Corporation(미국), Schrodinger, Inc.(미국), Recursion(미국), Insilico Medicine(미국),Google(미국), Microsoft Corporation(미국), Tempus AI, Inc.(미국), Illumina, Inc.(미국), XtalPi Inc.(중국), 그리고 Iktos(프랑스) 등이 있습니다. 이 기업은 시장내 입지를 강화하기 위해 전략적 제휴, 공동 연구, 제품 출시, 플랫폼 기능 강화, 기초 모델 및 생성형 AI에 대한 투자, 합병·인수, 그리고 사업 지역 확대와 같은 전략을 채택하고 있습니다.
조사 범위
이 보고서는 신약 개발 분야의 AI 시장을 분석합니다. 프로세스, 사용 사례, 치료 분야, 참여 조직 유형, AI 툴, 도입 모델, 최종사용자 및 지역을 기반으로 다양한 시장 부문 시장 규모와 향후 성장 가능성을 추정하는 것을 목적으로 합니다. 또한 시장 성장에 영향을 미치는 촉진요인, 제약 요인, 기회, 과제 등의 요인에 대해서도 분석하고 있습니다. 더불어, AI 주도 신약 개발 생태계 전반에 걸친 기회를 평가하고, 주요 이해관계자들의 경쟁 구도를 분석하고 있습니다. 아울러 이 보고서에서는 각 마이크로 시장의 성장 동향, 전망 및 신약 개발 분야에서 AI 시장 전체에 대한 기여도를 분석하고 있습니다. 주요 지역별 시장 매출을 예측하는 한편, 주요 시장 참여 기업에 대해 기업 개요, 제품 포트폴리오, 최근 동향, 주요 성장 전략을 포함한 포괄적인 경쟁 분석을 제공합니다.
이 보고서를 구매해야 하는 이유
이 보고서는 기존 기업뿐만 아니라 신규 진입 기업 및 중소기업에게도 시장 동향을 파악하기 위한 귀중한 정보원이 되며, 궁극적으로 시장 점유율 확대에 도움이 됩니다. 이 보고서를 구매한 기업은 다음 전략 중 하나 또는 이를 조합하여 활용함으로써 시장내 입지를 강화할 수 있습니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인 분석(신약 개발 및 연구 기간과 비용 절감에 대한 필요성 증가, 암 치료에서 약물-표적 상호작용 예측을 위한 AI 활용 확대),제약 요인(AI 인재 부족 및 AI를 활용한 신약 개발에 대한 규제 체계 부재, 전 세계적인 HBM/DRAM/NAND 부족에 따른 AI 컴퓨팅 인프라 비용 증가),기회(생명공학 기반 신약 개발 가속화, 바이오마커 및 질환 아형 식별을 위한 AI 기반 단일 세포 분석), 그리고 과제(고품질 훈련 데이터세트 확보의 한계, AI를 통해 도출된 신약 후보물질의 실제 임상 검증 범위가 제한적임)가 신약 개발 분야 AI 시장의 성장에 기여하는 요인으로 작용하고 있습니다
- 제품 개발/혁신: 신약 개발 분야 AI 시장의 향후 동향, 연구개발 활동 및 소프트웨어 출시에 대한 상세 인사이트
- 시장 개발: 프로세스, 사용 사례, 치료 분야, 기업 유형, AI 툴, 도입 모델, 최종사용자, 지역에 걸친 고성장 시장 부문에 대한 포괄적인 정보
- 시장 다각화: 신약 개발 분야의 AI 시장에서 제품 포트폴리오, 기술 발전, 지역적 확장, 전략적 제휴, 투자 및 최근 동향에 대한 포괄적인 정보
- 경쟁 분석: NVIDIA Corporation(미국), Schrodinger, Inc.(미국), Recursion(미국), Insilico Medicine(미국), Google(미국), Microsoft Corporation(미국),Tempus AI, Inc.(미국), Illumina, Inc.(미국), XtalPi Inc.(중국) 및 기타 주요 시장 참여 기업을 포함한 전 세계 신약 개발 분야 AI 시장의 주요 기업의 시장 점유율, 성장 전략, 제품 라인업, 기업 평가 쿼드런트,기술력 및 경쟁 우위에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 테크놀러지, 특허, 디지털 기술, AI 도입에 의한 전략적 파괴
제7장 규제 상황
제8장 고객 상황과 구매 행동
제9장 Drug Discovery용 AI 시장(프로세스별)
제10장 Drug Discovery용 AI 시장(AI 툴별)
제11장 Drug Discovery용 AI 시장(최종사용자별)
제12장 Drug Discovery용 AI 시장(사용 사례별)
제13장 Drug Discovery용 AI 시장(배포별)
제14장 Drug Discovery용 AI 시장(치료 분야별)
제15장 AI Drug Discovery 시장에 대한 활용(참여 조직 유형별)
제16장 Drug Discovery용 AI 시장(지역별)
제17장 경쟁 구도
제18장 기업 개요
제19장 조사 방법
제20장 부록
KSA 26.09.14The AI in drug discovery market is anticipated to grow from USD 5.09 billion in 2026 to USD 17.56 billion by 2031, at a CAGR of 28.1% during the forecast period. The market is driven by the increasing adoption of AI to improve R&D productivity, expanding use of multimodal biological datasets, and growing investments in precision medicine and computational drug discovery. According to a 2025 review published in Drug Discovery Today, declining pharmaceutical R&D productivity continues to reshape innovation strategies across the biopharmaceutical industry, prompting companies to increasingly adopt AI-driven platforms to improve research efficiency and accelerate drug discovery.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Process, Use Case, Therapeutic Area, Player Type, AI Tool, Deployment Model, and End User |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa |
However, challenges related to data quality, model validation, regulatory uncertainty, and integration with existing pharmaceutical R&D workflows continue to influence the pace of market adoption.
Machine learning to be the fastest-growing AI tool segment between 2026 and 2031
By AI tool, the machine learning segment is expected to register the fastest growth during the forecast period as pharmaceutical companies increasingly leverage predictive algorithms to improve decision-making across the drug discovery workflow. Machine learning enables rapid analysis of complex biological, chemical, and clinical datasets, significantly enhancing target identification, hit prioritization, molecular property prediction, and lead optimization. Continuous advancements in deep learning, graph neural networks, and generative AI have further expanded the application of machine learning across small molecule discovery, biologics development, and precision medicine research. Reflecting this trend, in March 2026, NVIDIA expanded its BioNeMo platform with next-generation foundation models and agentic AI capabilities to accelerate biomolecular research and molecular design. As pharmaceutical companies continue to prioritize faster drug development and improved R&D efficiency, machine learning is expected to remain the fastest-growing technology segment in the AI in drug discovery market.
Oncology segment accounted for the largest share of the AI in drug discovery market in 2025
By therapeutic area, the oncology segment accounted for the largest share of the AI in drug discovery market in 2025 due to the high global cancer burden, extensive oncology research pipelines, and increasing demand for precision therapeutics. According to the International Agency for Research on Cancer (IARC), global cancer incidence is projected to increase from 20.6 million new cases in 2024 to 34.4 million by 2050, highlighting the growing need for innovative technologies that can accelerate oncology drug discovery. AI is widely adopted to identify novel therapeutic targets, predict biomarkers, optimize patient stratification, and accelerate the discovery of targeted therapies and immuno-oncology drugs. The availability of large genomic, transcriptomic, proteomic, and clinical datasets has made oncology one of the most data-rich therapeutic areas, enabling AI models to generate more accurate and clinically relevant insights. Pharmaceutical companies continue to prioritize oncology within their R&D portfolios due to its significant commercial potential and the growing demand for personalized cancer therapies. Increasing collaborations between AI companies and oncology-focused biopharmaceutical organizations are further accelerating innovation and reinforcing oncology's leading position in the AI in drug discovery market.
Europe to exhibit the second-highest CAGR during the forecast period
Europe is expected to register the second-highest growth rate during the forecast period, driven by increasing investments in pharmaceutical innovation, expanding adoption of AI across biomedical research, and a strong regulatory framework supporting trustworthy AI. The region is home to leading pharmaceutical companies, research institutions, and AI-native biotechnology firms that are accelerating the integration of AI into target discovery, molecular design, and precision medicine. The implementation of the European Health Data Space (EHDS) and the EU AI Act is expected to facilitate secure cross-border access to health data while establishing harmonized governance for AI applications in life sciences. In parallel, the proposed Cloud and AI Development Act (CADA) aims to strengthen Europe's cloud and AI infrastructure by expanding sovereign computing capacity, improving access to high-performance computing resources, and supporting the development of AI innovation across strategic sectors, including healthcare and life sciences. In addition, collaborative programs such as the Innovative Health Initiative (IHI) continue to fund AI-enabled drug discovery projects, including LIGAND-AI, to accelerate therapeutic research through high-quality biological datasets and advanced AI models. Collectively, these initiatives are expected to reinforce its position as the second-fastest-growing regional market for AI in drug discovery.
The breakdown of primary participants is as mentioned below:
- By Company Type - Tier 1: 32%, Tier 2: 44%, and Tier 3: 24%
- By Designation - Directors: 30%, Managers: 34%, and Others: 36%
- By Region - North America: 40%, Europe: 28%, Asia Pacific: 20%, Latin America: 7%, and Middle East & Africa: 5%
Key Players
The key players operating in the AI in drug discovery market include NVIDIA Corporation (US), Schrodinger, Inc. (US), Recursion (US), Insilico Medicine (US), Google (US), Microsoft Corporation (US), Tempus AI, Inc. (US), Illumina, Inc. (US), XtalPi Inc. (China), and Iktos (France). These companies have adopted strategies such as strategic partnerships, collaborations, product launches, platform enhancements, investments in foundation models and generative AI, mergers and acquisitions, and geographic expansion to strengthen their market presence in the market.
Research Coverage
The report analyzes the AI in drug discovery market. It aims to estimate the market size and future growth potential of various market segments based on process, use case, therapeutic area, player type, AI tool, deployment model, end user, and region. The report also analyzes factors such as drivers, restraints, opportunities, and challenges influencing market growth. It evaluates opportunities across the AI-driven drug discovery ecosystem and assesses the competitive landscape for key stakeholders. The report further analyzes micro markets with respect to their growth trends, prospects, and contributions to the overall AI in drug discovery market. It forecasts market revenue across major regions and provides a comprehensive competitive analysis of leading market participants, including their company profiles, product portfolios, recent developments, and key growth strategies.
Reasons to Buy the Report
This report will enrich established firms as well as new entrants/smaller firms to gauge the pulse of the market, which, in turn, would help them garner a greater share of the market. Firms purchasing the report could use one or a combination of the following strategies to strengthen their positions in the market.
This report provides insights on:
- Analysis of key drivers (Rising need to reduce time and cost of drug discovery and development, Growing utilization of AI to predict drug-target interactions for cancer therapy), restraints (Shortage of AI workforce and regulatory frameworks for AI-enabled drug discovery, Increasing AI compute infrastructure costs amid global HBM/DRAM/NAND shortage), opportunities (Accelerating biotech drug discovery, AI-driven single-cell analysis for biomarker and disease-subtype identification), and challenges (Limited availability of high-quality training datasets, Limited real-world clinical validation of AI-derived drug candidates) are factors contributing the growth of the AI in drug discovery market
- Product Development/Innovation: Detailed insights on upcoming trends, research & development activities, and software launches in the AI in drug discovery market
- Market Development: Comprehensive information on high-growth market segments across process, use case, therapeutic area, player type, AI tool, deployment model, end user, and region
- Market Diversification: Exhaustive information on product portfolios, technology advancements, expanding geographic presence, strategic collaborations, investments, and recent developments in the AI in drug discovery market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, company evaluation quadrant, technology capabilities, and competitive strengths of leading players in the global AI in drug discovery market, including NVIDIA Corporation (US), Schrodinger, Inc. (US), Recursion (US), Insilico Medicine (US), Google (US), Microsoft Corporation (US), Tempus AI, Inc. (US), Illumina, Inc. (US), XtalPi Inc. (China), and other major market participants
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 REGIONAL SCOPE
- 1.3.3 INCLUSIONS & EXCLUSIONS
- 1.3.4 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 LIMITATIONS
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 AI IN DRUG DISCOVERY MARKET OVERVIEW
- 3.2 AI IN DRUG DISCOVERY MARKET, BY DEPLOYMENT & COUNTRY
- 3.3 AI IN DRUG DISCOVERY MARKET: GEOGRAPHIC SNAPSHOT
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing number of cross-industry collaborations and partnerships
- 4.2.1.2 Rising need to reduce time and cost of drug discovery and development
- 4.2.1.3 Patent expiry of drugs and need for effective new leads
- 4.2.1.4 Growing utilization of AI to predict drug-target interactions for cancer therapy
- 4.2.1.5 Integration of AI-assisted multiomics in drug discovery
- 4.2.1.6 Growing focus on rare disease treatments for orphan drug development
- 4.2.2 RESTRAINTS
- 4.2.2.1 Shortage of AI workforce and ambiguous regulatory guidelines for medical software
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Leveraging AI for accelerated biotech drug discovery
- 4.2.3.2 Increased focus on drug discovery in emerging economies
- 4.2.3.3 Focus on developing human-aware AI systems
- 4.2.3.4 Growing use of AI in single-cell analysis
- 4.2.3.5 Easy identification of biomarker and disease subtypes from single-cell data
- 4.2.3.6 High demand for precision and personalized medicines
- 4.2.4 CHALLENGES
- 4.2.4.1 Limited availability of quality data sets
- 4.2.4.2 Lack of advanced AI tools and training data sets
- 4.2.4.3 Computational constraints of advanced AI models
- 4.2.4.4 Lack of high-quality data sets for model training
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF SUBSTITUTES
- 5.1.4 THREAT OF NEW ENTRANTS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 GLOBAL PHARMACEUTICAL R&D EXPENDITURE AND PRODUCTIVITY TRENDS
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 RESEARCH, DATA GENERATION, AND SCIENTIFIC INPUTS
- 5.3.2 DATA ENGINEERING & AI INFRASTRUCTURE
- 5.3.3 AI MODEL & PLATFORM DEVELOPMENT
- 5.3.4 AI WORKFLOW INTEGRATION & DEPLOYMENT
- 5.3.5 DRUG DISCOVERY SERVICES & EXPERIMENTAL EXECUTION
- 5.3.6 VALIDATION, LAB-IN-THE-LOOP, AND CONTINUOUS OPTIMIZATION
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 INDICATIVE PRICE FOR AI IN DRUG DISCOVERY PLATFORMS, BY KEY PLAYERS (2025)
- 5.5.2 INDICATIVE PRICE FOR AI IN DRUG DISCOVERY SOFTWARE AND SERVICES, BY REGION (2025)
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.10 IMPACT OF 2025 US TARIFF - AI IN DRUG DISCOVERY MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRY/REGION
- 5.10.4.1 US
- 5.10.4.2 Europe
- 5.10.4.3 Asia-Pacific
- 5.10.5 IMPACT ON END-USE INDUSTRIES
- 5.10.5.1 Pharmaceutical companies
- 5.10.5.2 Biotechnology companies
- 5.10.5.3 CROs and CDMOs
- 5.10.5.4 Academic and research users
- 5.10.5.5 Other end users
6 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTION
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 GENERATIVE AND AGENTIC AI FOR DRUG DISCOVERY
- 6.1.2 MULTIMODAL AI AND FOUNDATION MODELS
- 6.1.3 AI-ENABLED AUTONOMOUS LABORATORIES
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 CLOUD COMPUTING AND HIGH-PERFORMANCE COMPUTING
- 6.2.2 HIGH-THROUGHPUT SCREENING AND LABORATORY AUTOMATION
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 MULTIOMICS AND SINGLE-CELL TECHNOLOGIES
- 6.3.2 DIGITAL TWINS AND IN-SILICO CLINICAL TECHNOLOGIES
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.5 PATENT ANALYSIS
- 6.5.1 PATENT PUBLICATION TRENDS FOR AI IN DRUG DISCOVERY MARKET
- 6.5.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AUTONOMOUS END-TO-END DRUG DISCOVERY
- 6.6.2 AI-DRIVEN PRECISION DRUG DISCOVERY AND PATIENT-SPECIFIC THERAPEUTICS
- 6.6.3 AI-ENABLED DIGITAL AND VIRTUAL DRUG DEVELOPMENT
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, & OTHER ORGANIZATIONS
- 7.1.2 REGULATORY FRAMEWORK
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.4 Latin America
- 7.1.2.5 Middle East & Africa
- 7.1.3 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.5 UNMET NEEDS FROM VARIOUS END USERS
- 8.5.1 UNMET NEEDS
- 8.5.2 END USER EXPECTATIONS
- 8.6 MARKET PROFITABILITY
9 AI IN DRUG DISCOVERY MARKET, BY PROCESS
- 9.1 INTRODUCTION
- 9.2 TARGET IDENTIFICATION & SELECTION
- 9.2.1 INCREASED DEMAND FOR PERSONALIZED MEDICINES AND HIGH INVESTMENT IN PHARMACEUTICAL R&D TO FUEL MARKET GROWTH
- 9.3 TARGET VALIDATION
- 9.3.1 RISING EMPHASIS ON AVOIDING LATE-STAGE FAILURE IN DRUG DISCOVERY TO BOOST MARKET GROWTH
- 9.4 HIT IDENTIFICATION & PRIORITIZATION
- 9.4.1 NEED FOR LARGE-SCALE DATA ANALYSIS TO DRIVE ADOPTION
- 9.5 HIT-TO-LEAD IDENTIFICATION/LEAD GENERATION
- 9.5.1 HIT-TO-LEAD IDENTIFICATION/LEAD GENERATION TO IMPROVE NEW DRUG POTENCY WITHOUT INCREASING LIPOPHILICITY
- 9.6 LEAD OPTIMIZATION
- 9.6.1 NEED FOR TRANSPARENT PRESENTATION AND ANALYSIS TO BOOST MARKET GROWTH
- 9.7 CANDIDATE SELECTION & VALIDATION
- 9.7.1 HIGH POSSIBILITY OF CLINICAL DRUG FAILURE TO SPUR ADOPTION OF CANDIDATE VALIDATION SERVICES
10 AI IN DRUG DISCOVERY MARKET, BY AI TOOL
- 10.1 INTRODUCTION
- 10.2 MACHINE LEARNING
- 10.2.1 INCREASING AVAILABILITY OF COMPLEX BIOLOGICAL AND CHEMICAL DATASETS DRIVES ADOPTION
- 10.2.2 DEEP LEARNING
- 10.2.2.1 Ability to capture complex nonlinear relationships across multimodal biological and molecular data - key driver
- 10.2.2.2 Transformer-based architectures
- 10.2.2.2.1 Growing volumes of sequential, multimodal, and unstructured scientific data drives market
- 10.2.2.3 Graph neural networks (GNN)
- 10.2.2.3.1 Need to understand molecular structure and complex biological relationships supports GNN adoption
- 10.2.2.4 Convolutional neural networks (CNN)
- 10.2.2.4.1 Expansion of image-based and 3D structural analysis boosts adoption
- 10.2.2.5 Diffusion and flow-based models
- 10.2.2.5.1 Increasing demand for controlled generation of novel molecules and proteins accelerates segment growth
- 10.2.2.6 Generative adversarial networks (GAN) & variational autoencoders (VAE)
- 10.2.2.6.1 Growing demand for computational exploration of chemical space supports growth
- 10.2.2.7 Recurrent & Sequence Models (RNN, LSTM)
- 10.2.2.7.1 Continued need to model sequential chemical and biological information sustains demand
- 10.2.2.8 Other deep learning technologies
- 10.2.2.8.1 Emergence of specialized neural architectures expands applications across complex discovery workflows
- 10.2.3 SUPERVISED LEARNING
- 10.2.3.1 Growing availability of experimentally validated datasets supports segment
- 10.2.4 SELF-SUPERVISED & REPRESENTATION LEARNING
- 10.2.4.1 Shortage of labeled biological data and growing availability of unlabeled datasets drive adoption
- 10.2.5 REINFORCEMENT LEARNING
- 10.2.5.1 Need to optimize molecules and experimental decisions across multiple objectives drives adoption
- 10.2.6 UNSUPERVISED LEARNING
- 10.2.6.1 Increasing complexity of biological datasets to boost segment
- 10.2.7 OTHER MACHINE LEARNING TECHNOLOGIES
- 10.2.7.1 Need to extract value from partially labeled and heterogeneous datasets supports segment
- 10.3 GENERATIVE AI
- 10.3.1 ABILITY TO DESIGN NOVEL MOLECULES AND BIOLOGICAL STRUCTURES ACCELERATES ADOPTION
- 10.3.2 MOLECULAR GENERATIVE MODELS
- 10.3.2.1 Need to explore larger chemical spaces and simultaneously optimize multiple molecular properties - segment driver
- 10.3.3 PROTEIN & BIOLOGICS GENERATIVE MODELS
- 10.3.3.1 Growing demand for engineered proteins, antibodies, and other biologics expands applications
- 10.3.4 LARGE LANGUAGE MODELS (LLMS)
- 10.3.4.1 Rapid growth of scientific literature and unstructured research data increases demand
- 10.4 FOUNDATION MODELS
- 10.4.1 NEED FOR REUSABLE AI MODELS TO LEARN FROM LARGE-SCALE, MULTIMODAL BIOLOGICAL DATASETS DRIVES ADOPTION
- 10.4.2 CHEMISTRY FOUNDATION MODELS
- 10.4.2.1 Increasing need for reusable molecular representation and scalable chemical intelligence drives segment
- 10.4.3 PROTEIN LANGUAGE MODELS
- 10.4.3.1 Growing demand for protein engineering and functional prediction accelerates adoption
- 10.4.4 BIOLOGY AND MULTIOMICS FOUNDATION MODELS
- 10.4.4.1 Increasing integration of genomic, transcriptomic, proteomic, and cellular data - key driver
- 10.5 AGENTIC AI & AI CO-SCIENTISTS
- 10.5.1 GROWTH DRIVEN BY DEMAND FOR AUTONOMOUS RESEARCH WORKFLOWS AND IMPROVED SCIENTIST PRODUCTIVITY
- 10.5.2 AUTONOMOUS RESEARCH AGENTS & WORKFLOW ORCHESTRATION
- 10.5.2.1 Need to automate complex multi-step research processes drives adoption
- 10.5.3 MULTI-AGENT REASONING SYSTEMS
- 10.5.3.1 Increasing complexity of scientific problems creates demand
- 10.5.4 LAB-IN-THE-LOOP & CLOSED-LOOP EXPERIMENTATION
- 10.5.4.1 Integration of AI with automated laboratories enables continuous design-build-test-learn workflows
- 10.6 KNOWLEDGE GRAPHS AND SEMANTIC REASONING
- 10.6.1 NEED TO CONNECT FRAGMENTED SCIENTIFIC INFORMATION AND IDENTIFY HIDDEN RELATIONSHIPS DRIVES SEGMENT
- 10.7 NATURAL LANGUAGE PROCESSING (NLP)
- 10.7.1 EXPLOSION OF SCIENTIFIC LITERATURE, PATENTS, AND UNSTRUCTURED R&D INFORMATION DRIVES NLP ADOPTION
- 10.8 COMPUTER VISION & IMAGE ANALYSIS
- 10.8.1 INCREASING USE OF HIGH-CONTENT SCREENING, MICROSCOPY, AND PHENOTYPIC ASSAYS EXPANDS APPLICATIONS
- 10.9 PHYSICS-BASED & HYBRID AI METHODS
- 10.9.1 NEED FOR MECHANISTIC UNDERSTANDING AND IMPROVED ACCURACY IN MOLECULAR MODELING DRIVES SEGMENT
11 AI IN DRUG DISCOVERY MARKET, BY END USER
- 11.1 INTRODUCTION
- 11.2 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 11.2.1 GROWING PRESSURE TO ACCELERATE R&D PRODUCTIVITY AND REDUCE DRUG DISCOVERY COSTS DRIVES SEGMENT
- 11.2.2 LARGE PHARMACEUTICAL COMPANIES
- 11.2.2.1 High R&D expenditure and increasing need to improve pipeline productivity accelerate AI adoption
- 11.2.3 SMALL & MID-SIZED BIOTECHNOLOGY COMPANIES
- 11.2.3.1 Limited internal resources and need for differentiated pipelines increase reliance on AI-enabled discovery
- 11.3 CONTRACT RESEARCH ORGANIZATIONS (CROS) & CDMOS
- 11.3.1 INCREASING OUTSOURCING OF DRUG DISCOVERY ACTIVITIES DRIVES GROWTH
- 11.4 RESEARCH CENTERS, ACADEMIC INSTITUTES, AND GOVERNMENT ORGANIZATIONS
- 11.4.1 GROWING AVAILABILITY OF RESEARCH FUNDING AND ADVANCED AI CAPABILITIES EXPANDS GROWTH
12 AI IN DRUG DISCOVERY MARKET, BY USE CASE
- 12.1 INTRODUCTION
- 12.2 UNDERSTANDING DISEASE BIOLOGY
- 12.2.1 INCREASED FOCUS ON UNDERSTANDING DISEASES TO IMPROVE RESEARCH DATA QUALITY AND QUANTITY
- 12.2.2 EVIDENCE SYNTHESIS AND SCIENTIFIC LITERATURE INTELLIGENCE
- 12.2.2.1 Rapid data analysis - key demand driver
- 12.2.3 MULTIOMICS INTEGRATION & TARGET-DISEASE ASSOCIATION
- 12.2.3.1 Growing integration of genomic, transcriptomic, proteomic, metabolomic, and other biological datasets to drive market
- 12.2.4 EXPERIMENT DESIGN & REAGENT/MODEL SELECTION
- 12.2.4.1 Growing complexity of disease biology and experiment design boosts demand
- 12.3 PROTEIN STRUCTURE & INTERACTION PREDICTION
- 12.3.1 ADVANCES IN AI-POWERED PROTEIN INTERACTION PREDICTION ACCELERATE STRUCTURE-BASED DRUG DISCOVERY
- 12.4 DRUG REPURPOSING
- 12.4.1 INCREASING ADOPTION OF AI PLATFORMS FOR SYSTEMATIC DRUG REPURPOSING
- 12.5 DE NOVO DRUG DESIGN
- 12.5.1 SMALL MOLECULE DESIGN
- 12.5.1.1 Increasing use of virtual screening and simulation techniques to drive growth
- 12.5.2 VACCINE DESIGN
- 12.5.2.1 Availability of well-validated AI tools to boost market growth
- 12.5.3 ANTIBODY & OTHER BIOLOGICS DESIGN
- 12.5.3.1 Advancements in protein modeling to propel segment growth
- 12.5.4 PROTEIN & ENZYME DESIGN
- 12.5.4.1 Protein designing to propel segment growth
- 12.5.1 SMALL MOLECULE DESIGN
- 12.6 DRUG OPTIMIZATION
- 12.6.1 SMALL MOLECULE OPTIMIZATION
- 12.6.1.1 Generative models for potential modifications in molecular structures to aid market growth
- 12.6.2 VACCINE OPTIMIZATION
- 12.6.2.1 Effective prediction of vaccine formulations and adjustment of delivery vectors to drive growth
- 12.6.3 ANTIBODY & OTHER BIOLOGICS OPTIMIZATION
- 12.6.3.1 Increasing adoption of machine learning to predict protein structures to augment segment growth
- 12.6.1 SMALL MOLECULE OPTIMIZATION
- 12.7 SAFETY & TOXICITY
- 12.7.1 FOCUS ON ADVANCED OFF-TARGET EFFECT PREDICTION, PK/PD SIMULATION, AND QSP MODELING TO DRIVE MARKET
13 AI IN DRUG DISCOVERY MARKET, BY DEPLOYMENT
- 13.1 INTRODUCTION
- 13.2 ON-PREMISE SOLUTIONS
- 13.2.1 GROWING DEMAND FOR DATA SOVEREIGNTY, IP PROTECTION, AND CONTROL OVER PROPRIETARY R&D DATA SUPPORTS GROWTH DEPLOYMENT
- 13.3 CLOUD-BASED SOLUTIONS
- 13.3.1 NEED FOR SCALABLE COMPUTING, RAPID AI DEPLOYMENT, AND COST-EFFICIENT ACCESS TO ADVANCED INFRASTRUCTURE - KEY DRIVERS
- 13.3.2 PUBLIC CLOUD
- 13.3.2.1 Elastic computing capacity and access to advanced AI infrastructure drive adoption
- 13.3.3 PRIVATE CLOUD/VPC/SOVEREIGN DEPLOYMENT
- 13.3.3.1 Increasing data-security, IP-protection, and data-residency requirements strengthen demand
- 13.4 HYBRID SOLUTIONS
- 13.4.1 NEED TO BALANCE COMPUTATIONAL SCALABILITY WITH CONTROL OVER SENSITIVE R&D DATA ACCELERATES ADOPTION
14 AI IN DRUG DISCOVERY MARKET, BY THERAPEUTIC AREA
- 14.1 INTRODUCTION
- 14.2 ONCOLOGY
- 14.2.1 HIGH PREVALENCE OF ONCOLOGY AND SHORTAGE OF EFFECTIVE ONCOLOGY DRUGS TO DRIVE MARKET GROWTH
- 14.3 INFECTIOUS DISEASES
- 14.3.1 RISING ANTIMICROBIAL RESISTANCE AND NEED FOR NOVEL ANTI-INFECTIVE THERAPIES TO DRIVE GROWTH
- 14.4 NEUROLOGY
- 14.4.1 HIGH DISEASE COMPLEXITY AND LIMITED TREATMENT OPTIONS DRIVE DEMAND FOR AI-ENABLED DISCOVERY
- 14.5 CARDIOVASCULAR DISEASES
- 14.5.1 GROWING CARDIOVASCULAR DISEASE BURDEN AND NEED FOR NOVEL THERAPEUTIC TARGETS BOOST GROWTH
- 14.6 METABOLIC DISEASES
- 14.6.1 RISING PREVALENCE OF OBESITY AND METABOLIC DISORDERS ACCELERATES DEMAND FOR INNOVATIVE THERAPIES
- 14.7 IMMUNOLOGY
- 14.7.1 COMPLEX IMMUNE MECHANISMS AND GROWING DEMAND FOR TARGETED THERAPIES DRIVE AI ADOPTION
- 14.8 RARE & GENETIC DISORDERS
- 14.8.1 LIMITED TREATMENT OPTIONS AND FRAGMENTED DISEASE DATA DRIVE AI-ENABLED DRUG DISCOVERY
- 14.9 MENTAL HEALTH DISORDERS
- 14.9.1 HIGH UNMET NEED AND LIMITED UNDERSTANDING OF DISEASE MECHANISMS DRIVE SEGMENT GROWTH
- 14.10 OTHER THERAPEUTIC AREAS
- 14.10.1 EXPANDING APPLICATION OF AI ACROSS UNDEREXPLORED DISEASE AREAS DRIVES MARKET GROWTH
15 AI IN DRUG DISCOVERY MARKET, BY PLAYER TYPE
- 15.1 INTRODUCTION
- 15.2 END-TO-END SOLUTION PROVIDERS
- 15.2.1 INCREASING ADOPTION OF INTEGRATED AI PLATFORMS ACROSS DRUG DISCOVERY WORKFLOW DRIVES GROWTH
- 15.3 NICHE/POINT SOLUTION PROVIDERS
- 15.3.1 GROWING DEMAND FOR SPECIALIZED AI CAPABILITIES TARGETING COMPLEX DISCOVERY CHALLENGES TO DRIVE GROWTH
- 15.4 AI TECHNOLOGY PROVIDERS
- 15.4.1 RAPID ADVANCES IN GENERATIVE AI, FOUNDATION MODELS, AND AGENTIC AI ACCELERATE DEMAND
- 15.5 COMPUTE & INFRASTRUCTURE PROVIDERS
- 15.5.1 GROWING COMPUTATIONAL REQUIREMENTS OF ADVANCED AI MODELS DRIVE DEMAND
- 15.6 BUSINESS PROCESS SERVICE PROVIDERS
- 15.6.1 INCREASING OUTSOURCING OF SPECIALIZED AI-ENABLED DISCOVERY ACTIVITIES DRIVES GROWTH
16 AI IN DRUG DISCOVERY MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 16.2.2 US
- 16.2.2.1 Strong pharma-AI ecosystem and high R&D investment drives demand
- 16.2.3 CANADA
- 16.2.3.1 Strong AI research base and growing biopharma innovation - key drivers
- 16.3 EUROPE
- 16.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 16.3.2 GERMANY
- 16.3.2.1 Availability of advanced computing and research infrastructure - key market driver
- 16.3.3 UK
- 16.3.3.1 Increasing investment in AI-based molecular design drives demand
- 16.3.4 SWITZERLAND
- 16.3.4.1 Strong pharmaceutical and biotechnology ecosystem to boost market
- 16.3.5 FRANCE
- 16.3.5.1 Large-scale AI investment by pharmaceutical companies - key driver
- 16.3.6 ITALY
- 16.3.6.1 Market driven by country's strong pharmaceutical and life sciences ecosystem
- 16.3.7 SPAIN
- 16.3.7.1 Expansion of AI-enabled biotechnology research drives demand
- 16.3.8 REST OF EUROPE
- 16.3.8.1 Growing pharmaceutical R&D and public-sector AI adoption to drive market
- 16.4 ASIA PACIFIC
- 16.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 16.4.2 JAPAN
- 16.4.2.1 Increasing pharmaceutical investment in AI and robotics drives demand
- 16.4.3 CHINA
- 16.4.3.1 Growth of AI-native biotech companies boosts demand
- 16.4.4 INDIA
- 16.4.4.1 Large pharmaceutical and biotechnology ecosystem to propel market
- 16.4.5 SOUTH KOREA
- 16.4.5.1 Government support for AI-based drug discovery to boost market
- 16.4.6 AUSTRALIA
- 16.4.6.1 Market driven by strong government support for AI and medical research
- 16.4.7 REST OF ASIA PACIFIC
- 16.4.7.1 Growth of regional pharmaceutical and biotechnology capabilities to boost market
- 16.5 LATIN AMERICA
- 16.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 16.5.2 BRAZIL
- 16.5.2.1 Expanding pharmaceutical R&D and emerging AI-biotech ecosystem act as major drivers
- 16.5.3 MEXICO
- 16.5.3.1 Multinational pharmaceutical activity and government-backed research to drive market
- 16.5.4 REST OF LATIN AMERICA
- 16.5.4.1 Growing research base for AI to drive market
- 16.6 MIDDLE EAST & AFRICA
- 16.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 16.6.2 GCC COUNTRIES
- 16.6.2.1 National AI strategies and growing technology partnerships act as major drivers
- 16.6.3 SAUDI ARABIA
- 16.6.3.1 Government investment in biotechnology and life sciences propels market
- 16.6.4 UAE
- 16.6.4.1 Government-led AI and biotechnology investment boosts market
- 16.6.5 REST OF GCC
- 16.6.5.1 International AI-drug discovery partnerships drive demand
- 16.6.6 SOUTH AFRICA
- 16.6.6.1 Strong domestic drug-discovery research base drives market
- 16.6.7 REST OF MIDDLE EAST & AFRICA
- 16.6.7.1 Expansion of local pharmaceutical and biomanufacturing capabilities drives demand
17 COMPETITIVE LANDSCAPE
- 17.1 OVERVIEW
- 17.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 17.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN AI IN DRUG DISCOVERY MARKET
- 17.3 REVENUE SHARE ANALYSIS OF TOP MARKET PLAYERS
- 17.4 MARKET SHARE ANALYSIS, 2025
- 17.5 BRAND COMPARISON
- 17.6 VALUATION & FINANCIAL METRICS
- 17.6.1 FINANCIAL METRICS
- 17.6.2 COMPANY VALUATION
- 17.7 COMPANY EVALUATION MATRIX
- 17.7.1 STARS
- 17.7.2 EMERGING LEADERS
- 17.7.3 PERVASIVE PLAYERS
- 17.7.4 PARTICIPANTS
- 17.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 17.7.5.1 Company footprint
- 17.7.5.2 Region footprint
- 17.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 17.8.1 PROGRESSIVE COMPANIES
- 17.8.2 RESPONSIVE COMPANIES
- 17.8.3 DYNAMIC COMPANIES
- 17.8.4 STARTING BLOCKS
- 17.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 17.8.5.1 Detailed list of key startups/SMEs
- 17.8.5.2 Competitive benchmarking of startups/SMEs
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 PRODUCT/SERVICE LAUNCHES
- 17.9.2 DEALS
- 17.9.3 EXPANSIONS
- 17.9.4 OTHER DEVELOPMENTS
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 NVIDIA CORPORATION
- 18.1.1.1 Business overview
- 18.1.1.2 Products/Services offered
- 18.1.1.3 Recent developments
- 18.1.1.3.1 Product/Service launches & approvals
- 18.1.1.3.2 Deals
- 18.1.1.3.3 Other developments
- 18.1.1.4 MnM view
- 18.1.1.4.1 Right to win
- 18.1.1.4.2 Strategic choices
- 18.1.1.4.3 Weaknesses & competitive threats
- 18.1.2 ALPHABET INC.
- 18.1.2.1 Business overview
- 18.1.2.2 Products/Services offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Product launches & approvals
- 18.1.2.3.2 Deals
- 18.1.2.3.3 Other developments
- 18.1.2.4 MnM view
- 18.1.2.4.1 Right to win
- 18.1.2.4.2 Strategic choices
- 18.1.2.4.3 Weaknesses & competitive threats
- 18.1.3 RECURSION
- 18.1.3.1 Business overview
- 18.1.3.2 Products/Services offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product/Service launches
- 18.1.3.3.2 Deals
- 18.1.3.3.3 Expansions
- 18.1.3.4 MnM view
- 18.1.3.4.1 Right to win
- 18.1.3.4.2 Strategic choices
- 18.1.3.4.3 Weaknesses & competitive threats
- 18.1.4 INSILICO MEDICINE
- 18.1.4.1 Business overview
- 18.1.4.2 Products/Services offered
- 18.1.4.3 Recent developments
- 18.1.4.3.1 Product/Service launches
- 18.1.4.3.2 Deals
- 18.1.4.3.3 Other developments
- 18.1.4.3.4 expansions
- 18.1.4.4 MnM view
- 18.1.4.4.1 Right to win
- 18.1.4.4.2 Strategic choices
- 18.1.4.4.3 Weaknesses & competitive threats
- 18.1.5 SCHRODINGER, INC.
- 18.1.5.1 Business overview
- 18.1.5.2 Products/Services offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Deals
- 18.1.5.3.2 Other developments
- 18.1.5.4 MnM view
- 18.1.5.4.1 Right to win
- 18.1.5.4.2 Strategic choices
- 18.1.5.4.3 Weaknesses & competitive threats
- 18.1.6 BENEVOLENTAI
- 18.1.6.1 Business overview
- 18.1.6.2 Products/Services offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Deals
- 18.1.7 MICROSOFT CORPORATION
- 18.1.7.1 Business overview
- 18.1.7.2 Products /Services offered
- 18.1.7.3 Recent developments
- 18.1.7.3.1 Product/Service launches & approvals
- 18.1.7.3.2 Deals
- 18.1.8 NUMERION LABS
- 18.1.8.1 Business overview
- 18.1.8.2 Products/Services offered
- 18.1.9 ILLUMINA, INC.
- 18.1.9.1 Business overview
- 18.1.9.2 Products/Services offered
- 18.1.9.3 Recent developments
- 18.1.9.3.1 Product/Service launches
- 18.1.9.3.2 Deals
- 18.1.10 XTALPI INC.
- 18.1.10.1 Business overview
- 18.1.10.2 Products/Services offered
- 18.1.10.3 Recent developments
- 18.1.10.3.1 Deals
- 18.1.11 IKTOS
- 18.1.11.1 Business overview
- 18.1.11.2 Products/Services offered
- 18.1.11.3 Recent developments
- 18.1.11.3.1 Deals
- 18.1.11.3.2 Other developments
- 18.1.12 TEMPUS AI, INC.
- 18.1.12.1 Business overview
- 18.1.12.2 Products/Services offered
- 18.1.12.3 Recent developments
- 18.1.12.3.1 Product/Service launches
- 18.1.12.3.2 Deals
- 18.1.13 DEEP GENOMICS, INC.
- 18.1.13.1 Business overview
- 18.1.13.2 Products/Services offered
- 18.1.13.3 Recent developments
- 18.1.13.3.1 Product/Service launches & approvals
- 18.1.14 VERGE LABS
- 18.1.14.1 Business overview
- 18.1.14.2 Products /Services offered
- 18.1.14.3 Recent developments
- 18.1.14.3.1 Deals
- 18.1.15 BENCHSCI
- 18.1.15.1 Business overview
- 18.1.15.2 Products/Services offered
- 18.1.15.3 Recent developments
- 18.1.15.3.1 Product/Service launches & approvals
- 18.1.15.3.2 Deals
- 18.1.15.3.3 Other developments
- 18.1.16 INSITRO
- 18.1.16.1 Business overview
- 18.1.16.2 Products/Services offered
- 18.1.16.3 Recent developments
- 18.1.16.3.1 Deals
- 18.1.16.3.2 Other developments
- 18.1.17 VALO HEALTH
- 18.1.17.1 Business overview
- 18.1.17.2 Products/Services offered
- 18.1.17.3 Recent developments
- 18.1.17.3.1 Deals
- 18.1.17.3.2 Other developments
- 18.1.18 BPGBIO, INC.
- 18.1.18.1 Business overview
- 18.1.18.2 Products/Services offered
- 18.1.18.3 Recent developments
- 18.1.18.3.1 Deals
- 18.1.19 GENERATE:BIOMEDICINES
- 18.1.19.1 Business overview
- 18.1.19.2 Products/Services offered
- 18.1.19.3 Recent developments
- 18.1.19.3.1 Product/Service launches
- 18.1.19.3.2 Deals
- 18.1.19.3.3 Expansions
- 18.1.20 CERTARA, INC.
- 18.1.20.1 Business overview
- 18.1.20.2 Products/Services offered
- 18.1.20.3 Recent developments
- 18.1.20.3.1 Product/Service launches & approvals
- 18.1.20.3.2 Deals
- 18.1.1 NVIDIA CORPORATION
- 18.2 OTHER EMERGING PLAYERS
- 18.2.1 XAIRA THERAPEUTICS
- 18.2.2 IAMBIC THERAPEUTICS, INC.
- 18.2.3 GENESIS MOLECULAR AI
- 18.2.4 CRADLE BIO
- 18.2.5 ISOMORPHIC LABS
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH APPROACH
- 19.1.1 SECONDARY RESEARCH
- 19.1.1.1 Key data from secondary sources
- 19.1.2 PRIMARY RESEARCH
- 19.1.2.1 Primary sources
- 19.1.2.2 Key data from primary sources
- 19.1.2.3 Breakdown of primaries
- 19.1.2.4 Insights from primary experts
- 19.1.1 SECONDARY RESEARCH
- 19.2 RESEARCH METHODOLOGY DESIGN
- 19.3 MARKET SIZE ESTIMATION
- 19.4 MARKET BREAKDOWN DATA TRIANGULATION
- 19.5 MARKET SHARE ESTIMATION
- 19.6 STUDY ASSUMPTIONS
- 19.7 RESEARCH LIMITATIONS
- 19.7.1 METHODOLOGY-RELATED LIMITATIONS
- 19.8 RISK ASSESSMENT
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS