
|
시장보고서
상품코드
2129350
데이터센터용 공조기 시장 예측(-2032년) : 유형별, 용량별, 데이터센터 유형별, 지역별Data Center Air Handling Units Market by Type, Capacity, Data Center Type (Hyperscale, Enterprise, Colocation Providers), and Region - Global Forecast to 2032 |
||||||

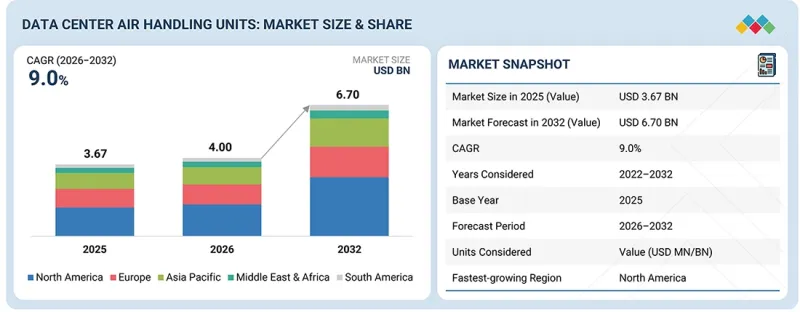
데이터센터용 공조기 시장 규모는 2026년 40억 달러에서 2032년까지 67억 달러로 확대하며, 예측 기간 중 CAGR은 9.0%에 달할 것으로 전망되고 있습니다.
인공지능(AI), 생성형 AI, 고성능 컴퓨팅(HPC) 및 클라우드 컴퓨팅의 도입 확대가 전 세계 데이터센터용 공조기 시장의 주요 성장 동인으로 작용하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2032년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2032년 |
| 산정 단위 | 금액(100만/10억 달러) |
| 부문 | 데이터센터 유형, 유형, 용량 및 지역 |
| 대상 지역 | 아시아태평양, 유럽, 북미, 중동 및 아프리카 및 남미 |
NVIDIA, AMD, Intel 등의 기업이 제공하는 첨단 GPU 및 가속기를 탑재한 AI 서버는 기존 서버 아키텍처에 비해 훨씬 더 높은 열 부하를 발생시킵니다. 이로 인해 랙의 전력 밀도는 기존의 5-15kW에서 50-100kW로 상승하며, 일부 AI 도입 사례에서는 랙당 150kW를 초과하는 경우도 있습니다. 이러한 높은 열 부하에 대응하기 위해서는 시스템의 신뢰성과 성능을 지속적으로 확보하면서 효율적으로 열을 방출할 수 있는 첨단 열 관리 솔루션이 필요합니다.
"유형별로는 냉수 시스템과 통합된 AHU 부문이 예측 기간 중 금액 기준으로 가장 큰 점유율을 차지할 것으로 추정됩니다."
냉수 시스템과 통합된 AHU 부문은 하이퍼스케일, 코로케이션 및 기업 데이터센터에서 냉수 기반 냉각의 채택이 확대됨에 따라 최대 시장 점유율을 차지할 것으로 예측됩니다. 냉수 기반 냉각은 고효율이며 대규모 냉각을 실현합니다.
현재 진행 중인 동향으로는 하이퍼스케일 데이터센터 및 AI 지원 컴퓨팅 인프라의 보급이 꼽히며, 이는 AHU와 결합된 냉수 시스템의 도입을 지원하고 있습니다. 데이터센터 전체의 랙 전력 밀도가 증가함에 따라 사업자들은 시설 전체에서 열을 효과적으로 제거할 수 있는 집중형 냉수 냉각 아키텍처 도입을 추진하고 있습니다. 또한 이러한 시스템에는 가변 속도 펌프, 지능형 제어, 프리쿨링 방식, 고효율 칠러 등의 신기술을 도입함으로써 효율을 더욱 높일 수 있습니다.
"데이터센터 유형별로 보면 하이퍼스케일 데이터센터 부문은 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다."
데이터센터 유형별로 보면 하이퍼스케일 데이터센터 부문은 예측 기간 중 전 세계 데이터센터용 공조기 시장에서 가장 빠른 성장을 기록할 것으로 전망됩니다. 주요 클라우드 서비스 제공업체와 기술 기업은 디지털 워크로드에 대한 급증하는 수요에 대응하기 위해 하이퍼스케일 데이터센터를 빠르게 구축하고 있습니다. AI/ML, HPC 및 클라우드 기반 애플리케이션의 사용이 증가함에 따라 더욱 정교한 냉각 인프라가 요구되고 있습니다. AHU는 냉수 시스템, 프리쿨링, 지능형 제어, 가변 속도 팬과 함께 전반적인 에너지 소비를 억제하면서도 증가하는 BTU 부하를 제어하기 위해 활용되고 있습니다. 또한 수소나 메탄을 연료로 하는 연료전지로 운영되는 하이퍼스케일 사업자들은 1.2 PUE 기준을 달성하기 위해 고에너지 효율의 HVAC 구성 요소 및 시스템을 도입함으로써, 데이터센터의 개발 및 운영에 있으며, 환경적으로 지속가능한 접근 방식을 제공하고 있습니다.
"처리 용량별로는 50,000 m³/h 이상의 부문이 예측 기간 중 가장 높은 성장률을 보일 것으로 전망됩니다."
처리 용량 측면에서 앞서 언급한 50,000 m³/h 이상의 부문은 예측 기간 중 데이터센터용 공기 처리 장치(AHU) 시장 전체에서 가장 높은 연평균 성장률(CAGR)을 기록하며 성장할 것으로 전망됩니다. 이 부문의 성장은 하이퍼스케일 데이터센터, 대규모 코로케이션 시설 및 AI에 중점을 둔 컴퓨팅 인프라의 급속한 확장에 따라 풍량 용량이 5만 m³/h를 초과하는 AHU에 대한 수요가 증가하고 있기 때문입니다.
AI/ML/HPC 및 클라우드 기반 애플리케이션의 활용이 확대됨에 따라 대용량 공조기(AHU)의 사용이 더욱 촉진되고 있습니다. 이 용량대의 AHU에는 냉수 냉각, 프리쿨링, EC 팬, 냉난방용 가변 풍량 제어, 그리고 지능형 모니터링 시스템이 점점 더 많이 채택되고 있습니다.
"예측 기간 중 북미는 금액 기준으로 데이터센터용 공조기의 최대 시장이 될 것으로 전망됩니다."
예측 기간 중 북미는 데이터센터용 공기조화 장치의 최대 시장이 될 것으로 추정됩니다. 이러한 성장은 주로 확립된 디지털 인프라, 하이퍼스케일 클라우드 제공업체의 두드러진 입지, 그리고 인공지능(AI) 및 고성능 컴퓨팅(HPC) 워크로드의 급속한 증가에 의해 주도되고 있습니다. 미국과 캐나다에서는 하이퍼스케일, 코로케이션 및 기업 데이터센터에 대한 막대한 투자가 지속적으로 이루어지고 있습니다. Amazon Web Services(AWS), Microsoft, Google, Meta, Oracle, CoreWeave 등의 기업은 AI 지원 인프라 확충을 추진하고 있습니다. 고밀도 서버 랙 및 GPU 클러스터 도입이 늘어남에 따라 열 부하가 증가하고 있으며, 그 결과 해당 지역 전체에서 첨단 열 관리 솔루션에 대한 수요가 높아지고 있습니다.
또한 이 지역은 차세대 냉각 기술 개발에서도 최첨단을 달리고 있습니다. 여기에는 다이렉트-투-칩(Direct-to-Chip) 수냉, 침지 냉각, 정밀 공조, 컴퓨터실용 에어 핸들러(CRAH), 컴퓨터실용 에어컨(CRAC), 냉각수 분배 장치(CDU),열교환기, 스마트 열 모니터링 시스템 등이 포함됩니다. 이러한 첨단 툴을 활용함으로써 데이터센터 운영 팀은 냉각 효율 향상, 최적의 온도 유지, 에너지 소비량 절감, 전력 사용 효율(PUE) 개선을 실현할 수 있을 뿐만 아니라, 전력을 대량으로 소비하는 AI 애플리케이션의 증가하는 수요에도 대응할 수 있게 됩니다.
데이터센터용 에어 핸들링 유닛 시장에서 사업을 운영하는 주요 기업으로는 STULZ GMBH(독일), 삼성전자(한국), Systemair AB(스웨덴), Vertiv Group Corp(미국), Swegon Group AB(스웨덴), Munters Group AB(스웨덴),Johnson Controls(미국), Trane(아일랜드), Carrier(미국), Daikin(일본), Mitsubishi Electric Corporation(일본), LG Electronics(한국), Trox SE(독일), Airedale International Air Conditioning Ltd(Modine)(영국),AL-KO THERM GMBH(독일), AAON(미국), Zeco Aircon(인도), GD Midea Heating & Ventilating Equipment(중국) 등이 있습니다. 이러한 주요 기업은 데이터센터용 공조기 시장에서 중요한 역할을 하고 있습니다. 이 기업은 시장 점유율과 매출을 확대하기 위해 제휴, 합작 투자, 사업 확장 등 다양한 전략을 채택하고 있습니다.
조사 범위:
이 보고서에서는 데이터센터 유형, 용량, 유형 및 지역을 기준으로 데이터센터용 공조기 시장 규모를 정의, 세분화 및 예측하고 있습니다. 주요 기업의 전략적 프로필을 작성하고, 해당 기업의 시장 점유율과 핵심 경쟁력을 포괄적으로 분석하고 있습니다. 또한 시장내 각 기업의 사업 확장, 제휴, 인수합병(M&A) 등 경쟁 동향을 추적·분석하고 있습니다.
이 보고서를 구매해야 하는 이유:
이 보고서는 데이터센터용 공조기 시장 및 각 부문의 매출에 대해 가장 정확한 추정치를 제공함으로써, 시장을 선도하는 기업과 신규 진입 기업에 도움이 될 것으로 기대됩니다. 또한 이 보고서는 이해관계자들이 시장의 경쟁 구도를 더 깊이 이해하고, 비즈니스 상의 입지를 강화하기 위한 귀중한 인사이트를 얻어 효과적인 시장 진입 전략을 수립하는 데 도움이 될 것으로 기대됩니다. 더불어, 이해관계자들이 시장 동향을 파악할 수 있도록 지원하는 동시에 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 촉진요인 분석(데이터센터 시장의 급속한 확대, 에너지 효율이 높고 지속가능한 데이터센터 냉각에 대한 관심 증가, 서버 랙의 전력 밀도 증가에 따른 첨단 기류 관리에 대한 수요 확대), 제약 요인(고밀도 컴퓨팅을 위한 액체 냉각 기술 채택 확대, 첨단 AHU 시스템에 대한 높은 설비 투자 및 수명 주기 비용),기회(AI 지원 데이터센터에서의 하이브리드 냉각 아키텍처 채택 확대, 레거시 데이터센터 냉각 인프라의 개조 및 현대화 진전), 그리고 과제(하이브리드 냉각 아키텍처의 통합 관련 과제) 등, 데이터센터용 공조기 시장의 성장에 영향을 미치는 요인
- 제품 개발/혁신: 데이터센터용 공기 처리 장치 시장의 향후 기술 동향 및 연구개발 활동에 대한 상세 인사이트
- 시장 개발: 수익성이 높은 시장에 대한 포괄적인 정보 - 이 보고서에서는 다양한 지역의 데이터센터용 공기 처리 장치 시장을 분석하고 있습니다.
- 시장 다각화: 데이터센터용 공조기 시장의 신제품, 다양한 유형, 미개발 지역, 최근 동향 및 투자에 관한 포괄적인 정보
- 경쟁 분석: STULZ GMBH(독일), Samsung Electronics(한국), Systemair AB(스웨덴), Vertiv Group Corp(미국), Swegon Group AB(스웨덴), Munters Group AB(스웨덴),Johnson Controls(미국), Trane(아일랜드), Carrier(미국), Daikin(일본), Mitsubishi Electric Corporation(일본), LG Electronics(한국),Trox SE(독일), Airedale International Air Conditioning Ltd(Modine)(영국), AL-KO THERM GMBH(독일), AAON(미국), Zeco Aircon(인도), GD Midea Heating & Ventilating Equipment(중국) 등
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 주요 신규 기술
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 데이터센터용 공조기 시장(유형별)
제10장 데이터센터용 공조기 시장(용량별)
제11장 데이터센터용 공조기 시장(데이터센터 유형별)
제12장 데이터센터용 공조기 시장(지역별)
제13장 경쟁 구도
제14장 기업 개요
제15장 조사 방법
제16장 부록
KSA 26.09.17The data center air handling units market is projected to grow from USD 4.00 billion in 2026 to USD 6.70 billion by 2032, at a CAGR of 9.0% during the forecast period. The increasing adoption of artificial intelligence (AI), generative AI, high-performance computing (HPC), and cloud computing is the primary driver of the global data center air handling units market.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Million/Billion) |
| Segments | Data Center Type, Type, Capacity, and Region |
| Regions covered | Asia Pacific, Europe, North America, Middle East & Africa, and South America |
AI servers equipped with advanced GPUs and accelerators from companies such as NVIDIA, AMD, and Intel generate substantially higher heat loads than conventional server architectures, pushing rack power densities from traditional 5-15 kW to 50-100 kW and, in some AI deployments, beyond 150 kW per rack. These elevated thermal loads require advanced thermal management solutions that can efficiently dissipate heat while ensuring continuous system reliability and performance.
"By type, the AHU integrated with chilled water systems segment is estimated to account for the largest, in terms of value, during the forecast period."
The AHU integrated with chilled water systems segment is projected to account for the largest market share due to increasing adoption of chilled water-based cooling in hyperscale, colocation, and enterprise data centers. Chilled water-based cooling provides high efficiency and high-scale cooling.
An ongoing trend is the proliferation of hyperscale data centers and AI-enabled computing infrastructure, which is also driving the use of chilled water systems with AHUs. Higher rack power densities across data centers are prompting operators to embrace a centralized chilled water-cooling architecture that can effectively remove heat from the entire facility. Furthermore, such systems can incorporate other emerging technologies such as variable-speed pumps, intelligent controls, free cooling schemes, and highly efficient chillers for enhanced efficiency.
"By data center type, the hyperscale data centers segment is projected to witness the highest CAGR during the forecast period."
Based on data center type, the hyperscale data centers segment is projected to register the fastest growth in the global data center air handling units market during the forecast period. Large cloud service providers and technology companies are rapidly deploying hyperscale data centers to cater to the soaring demand for digital workloads. As the utilization of AI/ML, HPC and cloud-based applications increases, there is a need for more sophisticated cooling infrastructures. AHUs, along with chilled water systems, free cooling, intelligent controls and variable-speed fans, are all being employed to control increased BTU loads with lower overall energy consumption. Hydrogen and methane-based nuclear cell-powered hyperscale operators are also offering an environmentally sustainable approach to data center development and operation via the deployment of highly energy-efficient HVAC components and systems to achieve 1.2PUE standards.
"By capacity, the >=50,000 M3/H segment is the highest growth during the forecast period."
In terms of capacity, the above >=50,000 m3/h segment is projected to grow at the highest CAGR in the overall data center air handling units market during the forecast period. The growth of this segment can be attributed to high demand for AHUs having airflow capacity of above 50,000 m 3/h due to the rapid growth of hyperscale data centers, large colocation facilities, and AI-focused computing infrastructure.
With increasing applications to AI/ML/HPC and cloud-based applications, the use of large-capacity air handling units (AHUs) is being further promoted. AHUs of this capacity increasingly feature chilled water cooling, free cooling, EC fans, variable air volume for cooling/heating, and intelligent monitoring systems.
"North America is projected to be the largest data center air handling units market, in terms of value, during the forecast period."
North America is estimated to be the largest market for data center air handling units during the forecast period. This growth is primarily driven by its established digital infrastructure, a significant presence of hyperscale cloud providers, and the rapid increase in artificial intelligence (AI) and high-performance computing (HPC) workloads. The US and Canada continue to experience significant investment in hyperscale, colocation, and enterprise data centers. Companies like Amazon Web Services (AWS), Microsoft, Google, Meta, Oracle, and CoreWeave are expanding their AI-ready infrastructures. As more high-density server racks and GPU clusters are implemented, thermal loads are increasing, which in turn raises the demand for enhanced thermal management solutions across the region.
Moreover, the region is at the forefront of developing next-generation cooling technologies. These include direct-to-chip liquid cooling, immersion cooling, precision air conditioning, computer room air handlers (CRAHs), computer room air conditioners (CRACs), coolant distribution units (CDUs), heat exchangers, and smart thermal monitoring systems. With these advanced tools, data center teams can improve cooling efficiency, maintain optimal temperatures, reduce energy consumption, and achieve better Power Usage Effectiveness (PUE) outcomes, all while managing the growing demands of power-hungry AI applications.
Profile break-up of primary participants for the report:
- By Company Type: Tier 1 - 45%, Tier 2 - 22%, and Tier 3 - 33%
- By Designation: C-Level Executives- 50%, Directors- 10%, and Others - 40%
- By Region: North America - 17%, Asia Pacific - 17%, Europe - 33%, Middle East & Africa - 25%, and South America - 8%
Leading players operating in the data center air handling units market include STULZ GMBH (Germany), Samsung Electronics (South Korea), Systemair AB (Sweden), Vertiv Group Corp (US), Swegon Group AB, (Sweden), Munters Group AB (Sweden), Johnson Controls (US), Trane (Ireland), Carrier (US), Daikin (Japan), Mitsubishi Electric Corporation (Japan), LG Electronics (South Korea), Trox SE (Germany), Airedale International Air Conditioning Ltd (Modine) (UK), AL-KO THERM GMBH (Germany), AAON (US), Zeco Aircon (India), GD Midea Heating & Ventilating Equipment Co., Ltd. (China), and others. These key players are significant contributors to the data center air handling units market. These players have adopted various strategies, including agreements, joint ventures, and expansions, to increase their market share and business revenue.
Research Coverage:
The report defines, segments, and projects the size of the data center air handling units market based on data center type, capacity, type, and region. It strategically profiles the key players and comprehensively analyzes their market shares and core competencies. It also tracks and analyzes competitive developments, such as expansions, partnerships, and acquisitions undertaken by them in the market.
Reasons to Buy the Report:
The report is expected to help market leaders/new entrants by providing them with the closest approximations of revenue numbers for the data center air handling units market and its segments. This report is also expected to help stakeholders gain a deeper understanding of the market's competitive landscape, acquire valuable insights to enhance their business positions, and develop effective go-to-market strategies. It also enables stakeholders to understand the market's pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of drivers (Rapid expansion of data center market, Growing emphasis on energy efficient and sustainable data center cooling, Increasing server rack power density driving demand for advanced airflow management), restraints (Growing adoption of liquid cooling technologies for high density computing, High capital investment and lifecycle costs of advanced AHU systems), opportunities (Increasing adoption of hybrid cooling architectures in AI ready data centers, Growing retrofit and modernization of legacy data center cooling infrastructure), and challenges (Integration challenges in hybrid cooling architectures) influencing the growth of the data center air handling units market
- Product Development/Innovation: Detailed insights into upcoming technologies and research & development activities in the data center air handling units market
- Market Development: Comprehensive information about lucrative markets - the report analyzes the data center air handling units market across varied regions.
- Market Diversification: Exhaustive information about new products, various types, untapped geographies, recent developments, and investments in the data center air handling units market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and product offerings of leading players such as STULZ GMBH (Germany), Samsung Electronics (South Korea), Systemair AB (Sweden), Vertiv Group Corp (US), Swegon Group AB, (Sweden), Munters Group AB (Sweden), Johnson Controls (US), Trane (Ireland), Carrier (US), Daikin (Japan), Mitsubishi Electric Corporation (Japan), LG Electronics (South Korea), Trox SE (Germany), Airedale International Air Conditioning Ltd (Modine) (UK), AL-KO THERM GMBH (Germany), AAON (US), Zeco Aircon (India), GD Midea Heating & Ventilating Equipment Co., Ltd. (China), and others
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 LIMITATIONS
- 1.6 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN DATA CENTER AHU MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN DATA CENTER AHU MARKET
- 3.2 DATA CENTER AHU MARKET, BY DATA CENTER TYPE
- 3.3 DATA CENTER AHU MARKET, BY AHU TYPE
- 3.4 DATA CENTER AHU MARKET, BY CAPACITY
- 3.5 DATA CENTER AHU MARKET, BY REGION
- 3.6 DATA CENTER AHU MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rapid expansion of data center market
- 4.2.1.2 Growing emphasis on energy-efficient and sustainable data center cooling
- 4.2.1.3 Increasing server rack power density driving demand for advanced airflow management
- 4.2.2 RESTRAINTS
- 4.2.2.1 Growing adoption of liquid cooling technologies for high-density computing
- 4.2.2.2 High capital investment and lifecycle costs of advanced AHU systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing adoption of hybrid cooling architectures in AI-ready data centers
- 4.2.3.2 Growing retrofit and modernization of legacy data center cooling infrastructure
- 4.2.4 CHALLENGES
- 4.2.4.1 Integration challenges in hybrid cooling architectures
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN DATA CENTER AHU MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF SUBSTITUTES
- 5.1.4 THREAT OF NEW ENTRANTS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMICS INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 DATA CENTER INDUSTRY
- 5.2.4 MANUFACTURING INDUSTRY
- 5.2.5 TRENDS IN GLOBAL HYPERSCALE AND AI DATA CENTER INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 PROMINENT COMPANIES
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 KEY CONFERENCES & EVENTS IN 2026-2027
- 5.6 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.7 INVESTMENT AND FUNDING SCENARIO
- 5.8 CASE STUDY ANALYSIS
- 5.8.1 CASE STUDY 1: JOHNSON CONTROLS (SILENT-AIRE) - MODULAR DATA CENTER AIR HANDLING UNIT SOLUTION
- 5.8.2 CASE STUDY 2: BESPOKE AIR HANDLING UNIT DEPLOYMENT FOR A HYPERSCALE DATA CENTER IN BELGIUM BY DAIKIN APPLIED UK
6 KEY EMERGING TECHNOLOGIES
- 6.1 KEY TECHNOLOGIES
- 6.1.1 INTELLIGENT AHU CONTROL AND MONITORING SYSTEMS
- 6.1.2 HIGH EFFICIENCY EC FAN AND VARIABLE AIRFLOW TECHNOLOGY
- 6.2 ADJACENT TECHNOLOGY ANALYSIS
- 6.2.1 MODULAR AND PREFABRICATED AHU SYSTEMS
- 6.2.2 WASTE HEAT RECOVERY AND REUSE SYSTEMS
- 6.3 COMPLEMENTARY TECHNOLOGY ANALYSIS
- 6.3.1 HYBRID AIR-LIQUID COOLING INTEGRATION SYSTEMS
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT TERM (2026 TO 2028) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID TERM (2028 TO 2032) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG TERM (2032 TO 2035+) | MASS COMMERCIALIZATION & AUTONOMOUS THERMAL MANAGEMENT
- 6.5 PATENT ANALYSIS
- 6.5.1 INTRODUCTION
- 6.5.2 METHODOLOGY
- 6.5.3 DOCUMENT TYPE
- 6.5.4 INSIGHTS
- 6.5.5 LEGAL STATUS OF PATENTS
- 6.5.6 JURISDICTION ANALYSIS
- 6.5.7 TOP APPLICANTS
- 6.5.7.1 List of major patents
- 6.6 FUTURE APPLICATIONS
- 6.6.1 INTELLIGENT AUTONOMOUS AHU CONTROL SYSTEMS: INTELLIGENT AHUS THAT CONTINUOUSLY OPTIMIZE AIRFLOW, TEMPERATURE, HUMIDITY, AND ENERGY CONSUMPTION THROUGH ADAPTIVE CONTROLS AND PREDICTIVE ANALYTICS
- 6.6.2 HYBRID COOLING COMPATIBLE AHUS: AHUS DESIGNED FOR SEAMLESS INTEGRATION WITH HYBRID COOLING ARCHITECTURES IN HIGH DENSITY DATA CENTER ENVIRONMENTS
- 6.6.3 MODULAR AND SCALABLE AHU PLATFORMS: FACTORY-ASSEMBLED MODULAR AHUS THAT ENABLE RAPID DEPLOYMENT, STANDARDIZED EXPANSION, AND SCALABLE COOLING INFRASTRUCTURE FOR HYPERSCALE AND EDGE DATA CENTERS
- 6.6.4 HEAT RECOVERY COMPATIBLE AHUS: AHUS ENGINEERED FOR COMPATIBILITY WITH FACILITY LEVEL HEAT RECOVERY SYSTEMS TO SUPPORT SUSTAINABLE DATA CENTER COOLING STRATEGIES
- 6.7 IMPACT OF AI/GEN AI ON DATA CENTER AHU MARKET
- 6.7.1 INTRODUCTION
- 6.7.2 TOP USE CASES AND MARKET POTENTIAL
- 6.7.3 BEST PRACTICES: COMPANIES/ INSTITUTIONS USE CASES
- 6.7.4 CASE STUDIES OF DATA CENTER AHU MARKET
- 6.7.5 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.6 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN DATA CENTER AHU MARKET
- 6.7.7 JOHNSON CONTROLS (SILENT-AIRE): CUSTOM AIR HANDLING FOR AI READY HYPERSCALE DATA CENTERS
- 6.7.8 DAIKIN: INTEGRATED AIR HANDLING FOR AI-READY DATA CENTERS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT AND ECO APPLICATIONS OF DATA CENTER AHU MARKET
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION MAKING PROCESS
- 8.2 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 DATA CENTER AHU MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 CHILLED WATER (CHW) AHU
- 9.2.1 EXPANSION OF HYPERSCALE DATA CENTERS AND AI-READY INFRASTRUCTURE DRIVES DEMAND FOR CHILLED WATER AHUS
- 9.3 DX (DIRECT EXPANSION) AHU
- 9.3.1 GROWING DEMAND FOR EDGE AND MODULAR DATA CENTERS DRIVES ADOPTION OF DX AHUS
- 9.4 EVAPORATIVE/ADIABATIC AHU
- 9.4.1 INCREASING FOCUS ON ENERGY EFFICIENCY AND SUSTAINABILITY DRIVES ADOPTION OF EVAPORATIVE/ADIABATIC AHUS
- 9.5 OUTSIDE AIR/AIR SIDE ECONOMIZER AHU
- 9.5.1 INCREASING EMPHASIS ON ENERGY EFFICIENT COOLING DRIVES ADOPTION OF OUTSIDE AIR/AIR SIDE ECONOMIZER AHUS
- 9.6 HYBRID (DUAL MEDIUM NATIVE) AHU
- 9.6.1 INCREASING ADOPTION OF FLEXIBLE COOLING ARCHITECTURES DRIVES DEMAND FOR HYBRID AHUS
10 DATA CENTER AHU MARKET, BY CAPACITY
- 10.1 INTRODUCTION
- 10.2 <= 5,000 M3/H
- 10.2.1 GROWING DEPLOYMENT OF EDGE AND MODULAR DATA CENTERS SUPPORTS DEMAND FOR AHUS WITH CAPACITIES UP TO 5,000 M3/H
- 10.3 5,001-15,000 M3/H
- 10.3.1 GROWING EXPANSION OF ENTERPRISE AND REGIONAL COLOCATION DATA CENTERS SUPPORTS DEMAND FOR AHUS WITH CAPACITIES OF 5,001-15,000 M3/H
- 10.4 15,001-30,000 M3/H
- 10.4.1 INCREASING DEPLOYMENT OF MODULAR HYPERSCALE AND LARGE COLOCATION DATA CENTERS DRIVES DEMAND FOR AHUS WITH CAPACITIES OF 15,001-30,000 M3/H
- 10.5 30,001-50,000 M3/H
- 10.5.1 INCREASING RACK POWER DENSITIES DRIVE DEMAND FOR AHUS WITH CAPACITIES OF 30,001-50,000 M3/H
- 10.6 >= 50,001 M3/H
- 10.6.1 EXPANSION OF AI MEGA CAMPUSES DRIVES DEMAND FOR AHUS WITH CAPACITIES OF >= 50,001 M3/H
11 DATA CENTER AHU MARKET, BY DATA CENTER TYPE
- 11.1 INTRODUCTION
- 11.2 HYPERSCALE
- 11.2.1 EXPANSION OF AI INFRASTRUCTURE AND HYPERSCALE DATA CENTERS DRIVES DEMAND FOR HIGH-CAPACITY AIR HANDLING UNITS
- 11.3 COLOCATION PROVIDERS
- 11.3.1 GROWING DEMAND FOR AI-READY INFRASTRUCTURE DRIVES AHU ADOPTION IN COLOCATION DATA CENTERS
- 11.4 ENTERPRISES
- 11.4.1 MODERNIZATION OF LEGACY DATA CENTER INFRASTRUCTURE SUPPORTS AHU ADOPTION IN ENTERPRISE DATA CENTERS
12 DATA CENTER AIR HANDLING UNITS MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 US
- 12.2.1.1 Hyperscale expansion, liquid cooling integration, and AI-driven infrastructure investment to sustain market leadership
- 12.2.2 CANADA
- 12.2.2.1 Cold-climate free cooling and renewable power pricing to anchor sustainable AHU demand
- 12.2.3 MEXICO
- 12.2.3.1 Nearshoring-led digital investment and hyperscale market entry to drive demand for heat-tolerant AHU systems
- 12.2.1 US
- 12.3 EUROPE
- 12.3.1 GERMANY
- 12.3.1.1 EnEfG efficiency mandates and record hyperscale capital deployment to reshape Frankfurt's air handling standards
- 12.3.2 UK
- 12.3.2.1 AI growth zones and critical national infrastructure status to unlock a new wave of AHU-equipped capacity
- 12.3.3 FRANCE
- 12.3.3.1 Nuclear-backed low-carbon power and sovereign cloud investment to fuel hyperscale AHU demand
- 12.3.4 ITALY
- 12.3.4.1 Milan's rise to tier-one status and Mediterranean connectivity to drive new AHU-equipped campus construction
- 12.3.5 SPAIN
- 12.3.5.1 Solar-rich power availability and fast-tracked mega-campuses to position Spain as a leading growth market
- 12.3.6 RUSSIA
- 12.3.6.1 Import substitution and data localization mandates to sustain a domestically oriented AHU market
- 12.3.7 REST OF EUROPE
- 12.3.1 GERMANY
- 12.4 ASIA PACIFIC
- 12.4.1 CHINA
- 12.4.1.1 East-west data computing program and sovereign AI buildout to anchor the region's largest AHU market
- 12.4.2 JAPAN
- 12.4.2.1 Sovereign AI investment and severe power constraints to elevate demand for high-efficiency, space-optimized AHU systems
- 12.4.3 INDIA
- 12.4.3.1 Infrastructure-status incentives and record hyperscaler commitments to drive Asia's fastest-growing AHU demand
- 12.4.4 SOUTH KOREA
- 12.4.4.1 18.4 GW national AI data center megaproject to reshape long-term demand for high-density AHU infrastructure
- 12.4.5 THAILAND
- 12.4.5.1 BOI incentives and regional diversification beyond Singapore to accelerate new AHU-equipped capacity
- 12.4.6 TAIWAN
- 12.4.6.1 Semiconductor leadership and AI chipmaker R&D investment to drive precision, high-density AHU requirements
- 12.4.7 AUSTRALIA
- 12.4.7.1 Record capital inflows and OpenAI-NEXTDC partnership to underpin strong AHU demand through 2030
- 12.4.8 REST OF ASIA PACIFIC
- 12.4.1 CHINA
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.5.1.1 Saudi Arabia
- 12.5.1.1.1 HUMAIN's multi-gigawatt sovereign AI buildout to drive the region's most aggressive AHU demand growth
- 12.5.1.2 UAE
- 12.5.1.2.1 Stargate UAE and G42's international partnerships to cement the country's position as a regional AI hub
- 12.5.1.3 Qatar
- 12.5.1.3.1 Brookfield-QAI partnership and national digital transformation strategy to expand Doha's AHU-equipped capacity
- 12.5.1.4 Rest of GCC Countries
- 12.5.1.1 Saudi Arabia
- 12.5.2 SOUTH AFRICA
- 12.5.2.1 Sub-Saharan Africa's leading connectivity hub status to drive steady, grid-resilient AHU investment
- 12.5.3 TURKEY
- 12.5.3.1 Istanbul's Europe-Asia connectivity bridge and Google's regional investment to support steady AHU growth
- 12.5.4 REST OF MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 ByteDance's record USD 39 billion campus and hyperscale cloud expansion to anchor South America's largest AHU market
- 12.6.2 ARGENTINA
- 12.6.2.1 Digital banking growth and government modernization programs to sustain incremental AHU demand despite macro headwinds
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 INTRODUCTION
- 13.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 13.3 REVENUE ANALYSIS, 2025
- 13.3.1 TOP PLAYERS' REVENUE ANALYSIS
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.4.1 RANKING ANALYSIS OF KEY MARKET PLAYERS
- 13.4.2 MARKET SHARE ANALYSIS, 2025
- 13.5 BRAND/PRODUCT COMPARISON
- 13.6 COMPANY VALUATION AND FINANCIAL METRICS
- 13.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.7.5.1 Company footprint
- 13.7.6 REGION FOOTPRINT
- 13.7.7 TYPE FOOTPRINT
- 13.7.8 CAPACITY FOOTPRINT
- 13.7.9 DATA CENTER TYPE FOOTPRINT
- 13.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.8.1 PROGRESSIVE COMPANIES
- 13.8.2 RESPONSIVE COMPANIES
- 13.8.3 DYNAMIC COMPANIES
- 13.8.4 STARTING BLOCKS
- 13.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 13.8.5.1 Detailed list of key startups/SMEs
- 13.8.5.2 Competitive benchmarking of key startups/SMEs
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
14 COMPANY PROFILES
- 14.1 MAJOR PLAYERS
- 14.1.1 VERTIV GROUP CORP.
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Product Launches
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 STULZ GMBH
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 MnM view
- 14.1.2.3.1 Key strengths
- 14.1.2.3.2 Strategic choices
- 14.1.2.3.3 Weaknesses and competitive threats
- 14.1.3 SAMSUNG ELECTRONICS CO., LTD. (FLAKTGROUP)
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 Recent developments
- 14.1.3.4 MnM view
- 14.1.3.4.1 Key strengths
- 14.1.3.4.2 Strategic choices
- 14.1.3.4.3 Weaknesses and competitive threats
- 14.1.4 SYSTEMAIR AB
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product Launches
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 SWEGON GROUP AB
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 MUNTERS GROUP AB
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.7 JOHNSON CONTROLS
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.8 TRANE
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.9 CARRIER
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.10 DAIKIN INDUSTRIES LTD.
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.10.3 Recent developments
- 14.1.10.3.1 Deals
- 14.1.11 MITSUBISHI ELECTRIC CORPORATION
- 14.1.11.1 Business overview
- 14.1.11.2 Products/Solutions/Services offered
- 14.1.11.3 Recent developments
- 14.1.11.3.1 Deals
- 14.1.11.3.2 Expansions
- 14.1.12 LG ELECTRONICS
- 14.1.12.1 Business overview
- 14.1.12.2 Products/Solutions/Services offered
- 14.1.13 TROX SE
- 14.1.13.1 Business overview
- 14.1.13.2 Products/Solutions/Services offered
- 14.1.14 AIREDALE INTERNATIONAL AIR CONDITIONING LTD.
- 14.1.14.1 Business overview
- 14.1.14.2 Products/Solutions/Services offered
- 14.1.14.3 Recent developments
- 14.1.14.3.1 Product Launches
- 14.1.14.3.2 Deals
- 14.1.15 AL-KO THERM GMBH
- 14.1.15.1 Business overview
- 14.1.15.2 Products/Solutions/Services offered
- 14.1.16 AAON
- 14.1.16.1 Business overview
- 14.1.16.2 Products/Solutions/Services offered
- 14.1.17 GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.
- 14.1.17.1 Business overview
- 14.1.17.2 Products/Solutions/Services offered
- 14.1.18 ZECO AIRCON
- 14.1.18.1 Business overview
- 14.1.18.2 Products/Solutions/Services offered
- 14.1.1 VERTIV GROUP CORP.
- 14.2 OTHER PLAYERS
- 14.2.1 ROSENBERG VENTILATOREN GMBH
- 14.2.2 MENERGA GMBH
- 14.2.3 CHAT UNION CLIMAVENETA
- 14.2.4 NORTEK AIR SOLUTIONS, LLC
- 14.2.5 HAAKON INDUSTRIES
- 14.2.6 MAMMOTH INC.
- 14.2.7 ENTROPIC
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 List of key secondary sources
- 15.1.1.2 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Key industry insights
- 15.1.2.3 List of primary participants
- 15.1.2.4 Breakdown of primary interviews
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 BOTTOM-UP APPROACH
- 15.2.2 TOP-DOWN APPROACH
- 15.3 MARKET FORECAST APPROACH
- 15.3.1 DEMAND-SIDE ANALYSIS
- 15.3.2 SUPPLY-SIDE ANALYSIS
- 15.3.3 CALCULATIONS FOR SUPPLY-SIDE ANALYSIS
- 15.4 GROWTH FORECAST
- 15.5 DATA TRIANGULATION
- 15.6 RESEARCH ASSUMPTIONS
- 15.7 RESEARCH LIMITATIONS
- 15.8 RISK ASSESSMENT
- 15.9 FACTOR ANALYSIS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


