

|
시장보고서
상품코드
2125449
에어 핸들링 유닛(AHU) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Air Handling Units (AHU) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
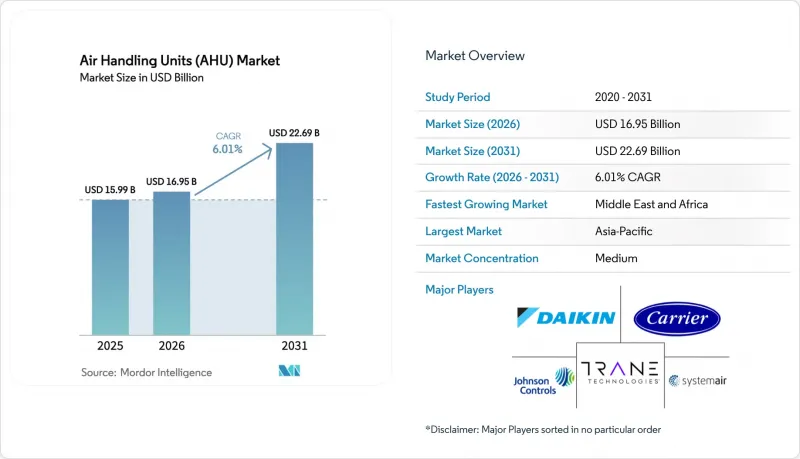
에 의하면, 2026년 에어 핸들링 유닛 시장 규모는 169억 5,000만 달러로 추정되고, 2025년 159억 9,000만 달러에서 확대해, 2031년에는 226억 9,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 6.01%가 될 것으로 전망됩니다.
본 보고서는 유형별(맞춤형, 패키지형, 모듈형 등), 용량별(5,000 미만, 5, 001-15,000, 기타), 설치 장소별(실내, 실외/옥상), 기술별(히트파이프, 런어라운드 코일, 판형 열교환기, 기타), 용도별(쾌적 공조, 공정 환기), 최종 사용자별(주거, 상업, 산업), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 에어 핸들링 유닛(AHU) 시장 동향 및 인사이트
아시아 의료 및 제약 분야의 클린룸용 여과 장치 수요 증가
아시아 내 제약 시설의 확장에 따라, 에너지 소비의 균형을 유지하면서 ISO 14644-1 클래스 5-8의 환경을 유지하는 AHU에 대한 수요가 증가하고 있습니다. 각 제조업체는 국경을 초월한 생산 요건을 충족하기 위해 FDA 및 EU GMP 부속서 1의 서로 다른 기류 속도 기준에 맞추어 장치를 맞춤 제작하고 있습니다. 중국과 인도에서는 현재 생명공학 및 반도체 팹을 대상으로 HEPA 필터가 장착된 공기 시스템이 규정되어 있으며, 규정 준수 및 효율성을 확보하기 위해 실시간 입자 모니터링 및 빌딩 관리 시스템이 통합되어 있습니다.
EU 에코디자인 지침 2023/813 : SFP 저감 및 열회수 효율 향상 의무화
규정 2024/1781에 따라 에어 핸들링 유닛(AHU)는 팬의 전력 소비를 억제하고 열 회수 효율을 73% 이상으로 높여야 하며, 이에 따라 에너지 휠은 옵션에서 표준 사양으로 전환되고 있습니다. 125 W에서 500 kW에 이르는 산업용 팬도 더욱 엄격한 효율 기준을 충족해야 하며, 이러한 변경으로 2030년까지 31 TWh의 전력 절감이 예상됩니다. 라이프사이클 디지털 패스포트의 도입으로 규정 준수 대상이 최초 판매 이후로도 확대되어, 사후 서비스에서의 차별화가 도모됩니다.
알루미늄·구리 가격 변동이 코일/팬 비용을 상승시키고 있습니다.
관세의 영향으로 알루미늄 및 철강 비용이 25% 급등하여, 2025년에는 AHU의 이익률이 압박받고 프로젝트가 연기되는 사태가 발생했습니다. 구리 가격 변동은 유닛 재료비의 30%를 차지하기도 하는 열교환기 예산에 위험 요인을 초래하고 있습니다. 각 제조업체는 구매 헤지, 자재 사용량 감축을 목적으로 한 설계 변경, 공급 계약 재협상을 진행하고 있지만, 한편으로는 엔지니어링 주기가 장기화되고 있습니다.
부문 분석
표준 사무실에서는 예측 가능한 제품 선정이 선호되기 때문에 2025년 매출의 41.35%를 패키지형 유닛이 차지했습니다. 한편, 데이터센터 개발자들이 신속하게 설치할 수 있고 가동 중단 시간 없이 확장 가능한 용량 블록을 요구함에 따라, 모듈식 시스템은 연평균 성장률(CAGR) 8.52%로 성장을 지속하고 있습니다. 맞춤형 구성은 제약 및 전자기기 제조 업계에서 활발히 활용되고 있습니다. 이러한 업계에서는 특수한 여과 및 습도 목표가 설정되어 있어 카탈로그 제품으로는 대응할 수 없습니다. 에어 핸들링 유닛 시장에서는 공급업체들이 맞춤형 기능을 유지하면서도 리드 타임을 단축할 수 있는 구성 가능한 프레임으로 전환하고 있습니다. 또한 모듈식 구조를 통해 조립 작업의 상당 부분을 공장 내에서 수행함으로써 숙련된 인력에 대한 의존도를 낮출 수 있어, 인력 부족이 심각한 시장에서 중요한 이점이 되고 있습니다.
성장의 원동력은 하이퍼스케일 데이터 처리 분야이며, 이곳에서는 간접 단열 모듈과 액체 냉각 대응 코일이 주류를 이루고 있습니다. 유연한 설치 면적 덕분에 랙 도입 일정에 맞추어 설비 투자를 단계적으로 진행할 수 있습니다. 그 결과, 에어 핸들링 유닛 시장에서는 스키드 탑재형 팬, 코일, 제어 장치를 통합한 플러그 앤 플레이형 패키지가 출하 전에 사내에서 검증된 상태로 제공되고 있습니다.
5,001-15,000 m3/h 부문은 2025년 매출의 47.40%를 차지했으며, 병원, 고등교육 기관, 복합 애플리케이션 개발 시설에 서비스를 제공합니다. 한편, 15,000 m³/h를 초과하는 유닛은 전기화된 공정 열 및 지역 열 공급 네트워크에 힘입어 연평균 성장률(CAGR) 9.25%로 확대되고 있습니다. 15,000 m3/h를 초과하는 설치를 위한 에어 핸들링 유닛(AHU) 시장 규모는 총 잠재 용량 23 GW, 총액 46억-115억 유로에 달하는 유럽의 산업용 히트 펌프 프로젝트에 의해 뒷받침되고 있습니다. MAN사의 20-33 MW CO2 히트 펌프는 열 루프와 통합된 메가 스케일 AHU로의 전환을 여실히 보여주고 있습니다.
소용량 유닛(5,000 m3/h 미만)은 중앙 집중식 처리를 통해 실내 공기질이 개선되는 고급 주거용 타워에서 여전히 중요한 역할을 하고 있습니다. 가변 속도 EC 팬과 소형 열회수 휠은 엄격한 소음 및 공간 제약에 대응하는 데 도움이 되지만, 시장 성장은 대형 시스템에 비해 더딘 임베디드니다.
지역별 분석
아시아태평양은 2025년 매출 점유율 31.55%로 에어 핸들링 유닛 시장을 주도했습니다. 중국의 1억 8,500만 대에 달하는 에어컨 생산 기반이 이 지역공급망을 뒷받침하는 한편, 인도의 HVAC 지출은 2030년까지 연평균 성장률(CAGR) 15.8%로 300억 달러에 달할 전망이며, 이는 국내 공조기 수요를 끌어올리고 있습니다. 일본과 한국에서는 엄격한 실내 공기질(IAQ) 기준 개정과 라돈 농도를 98% 감축한 지하 시설에서의 실증 실험 성공에 힘입어 개보수 공사가 진행되고 있습니다. 현지 기업들은 세계 OEM과 제휴하여 다양한 프로젝트 일정을 충족시키는 모듈식 시스템을 공급하고 있습니다.
유럽의 성숙한 규제 환경은 기술 혁신을 가속화하고 있습니다. ‘에코디자인’ 프레임워크는 열회수 효율과 디지털 제품 여권을 촉진하여 고효율 모델의 에어 핸들링 유닛(AHU) 시장 점유율을 확대되고 있습니다. 스칸디나비아에서 독일에 이르는 산업용 히트펌프 도입이 15,000 m3/h를 초과하는 유닛 수요를 견인하고 있습니다. 공급업체들은 A2L 냉매에 대한 장기적인 적합성 평가를 진행 중이며, 최종 승인을 통해 노후화된 설비의 교체 주기가 촉진될 전망입니다.
중동에서는 사우디아라비아, 카타르, 아랍에미리트(UAE)의 메가 프로젝트 덕분에 연평균 성장률(CAGR)이 9.02%로 가장 높은 성장세를 기록하고 있습니다. 지역 냉방 네트워크에서는 50℃의 환경에서도 문제없이 가동되는 사막 대응형 옥상 설치형 공조기(AHU)가 지정되어 있습니다. 정부의 비전에서는 지속가능성이 우선시되고 있으며, 피크 시간대의 전력 부하를 줄이는 설비에 우대 조치가 적용되고 있습니다. 한편, 북미에서는 원자재 가격 상승과 기술자 부족에 직면해 있음에도 불구하고, 하이퍼스케일 데이터센터를 통해 해당 지역에서 전례 없는 규모의 모듈형 열 관리 시스템이 대량 발주되고 있습니다. 데이터센터 건설 확대에 따른 에어 핸들링 유닛 시장 규모는 2031년까지 두 자릿수 성장률을 기록하며 확대될 것으로 예측됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the air handling units market size in 2026 is estimated at USD 16.95 billion, growing from 2025 value of USD 15.99 billion with 2031 projections showing USD 22.69 billion, growing at 6.01% CAGR over 2026-2031.
This report is Segmented by Type (Custom, Packaged, Modular, and More), Capacity (Less Than 5, 000, 5, 001-15, 000, and More), Installation (Indoor, Outdoor/Rooftop), Technology (Heat-Pipe, Run-Around Coil, Plate Heat Exchanger, and More), Application (Comfort, Process Ventilation), End-User (Residential, Commercial, Industrial), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Air Handling Units (AHU) Market Trends and Insights
Healthcare & Pharma Clean-room Filtration Uptick in Asia
Asia's pharmaceutical build-out is boosting demand for AHUs that maintain ISO 14644-1 Class 5-to-8 spaces while balancing energy use. Manufacturers tailor units to divergent FDA and EU GMP Annex 1 velocity criteria to serve cross-border production requirements. China and India now specify HEPA-filtered air systems for biotech and semiconductor fabs, integrating real-time particle monitoring with building controls for compliance and efficiency.
EU Ecodesign 2023/813 Mandating Lower SFP & Higher Heat-Recovery
Regulation 2024/1781 requires AHUs to curb fan power and exceed 73% heat-recovery effectiveness, pushing energy wheels from option to baseline. Industrial fans from 125 W to 500 kW must also meet tighter efficiency rules, a change forecast to save 31 TWh by 2030. Lifecycle digital passports extend compliance beyond first sale and create after-sales differentiation.
Volatile Aluminium & Copper Prices Inflating Coil/Fan Costs
Tariffs drove 25% spikes in aluminum and steel costs, compressing AHU margins and deferring projects in 2025. Copper volatility adds risk to heat-exchanger budgets that can represent 30% of unit material value. Manufacturers hedge purchases, redesign for reduced material intensity and renegotiate supply contracts, but engineering cycles lengthen.
Other drivers and restraints analyzed in the detailed report include:
- Hyperscale Data-Centre Build-outs Requiring Modular Indirect Adiabatic AHUs
- Retrofit Demand for Energy-Recovery Ventilation in Japan & South Korea
- Skilled-Labour Shortages Delaying On-site Assembly of Large Custom AHUs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Packaged units held 41.35% 2025 revenue as standard offices favored predictable selection. Modular systems, however, show 8.52% CAGR as data-center developers demand capacity blocks that install quickly and expand without downtime. Custom configurations thrive in pharmaceuticals and electronics manufacturing where bespoke filtration and humidity targets preclude catalog solutions. The air handling units market sees suppliers shifting to configurable frames that shorten lead times while preserving customization. Modular construction also limits skilled-labor exposure by transferring more assembly to the factory, a key advantage in tight labor markets.
Growth momentum stems from hyperscale data processing, where indirect adiabatic modules and liquid-cooling ready coils dominate. Flexible footprints permit phasing that aligns capital spending with rack deployment. As a result, the air handling units market integrates skid-mounted fans, coils and controls into plug-and-play packages validated in-house before shipment.
The 5,001-15,000 m3/h tier accounts for 47.40% 2025 revenues, serving hospitals, higher-education and mixed-use developments. Yet units exceeding 15,000 m3/h expand at 9.25% CAGR driven by electrified process heat and district networks. The air handling units market size for >15,000 m3/h installations is supported by European industrial heat-pump projects totaling 23 GW potential, worth EUR 4.6-11.5 billion. MAN's 20-33 MW CO2 heat-pump illustrates momentum toward mega-scale AHUs integrated with thermal loops.
Smaller capacity units (<5,000 m3/h) stay relevant in premium residential towers where central treatment improves indoor air quality. Variable-speed EC fans and compact heat-recovery wheels help meet tight acoustical and spatial constraints, though market growth lags larger systems.
Complete Report Scope:
- By Type
- Custom
- Packaged
- Modular
- DX Integrated
- Heat-Recovery Units
- By Capacity
- Less than 5,000
- 5,001 - 15,000
- Greater than 15,000
- By Installation Type
- Indoor
- Outdoor / Rooftop
- By Technology
- Heat-Pipe
- Run-Around Coil
- Plate Heat Exchanger
- Desiccant-Based
- Thermodynamic Heat Pump AHU
- By Application
- Comfort Ventilation
- Process Ventilation and Dehumidification
- By End-user
- Residential
- Commercial
- Offices
- Hospitality and Leisure
- Healthcare Facilities
- Educational Institutions
- Retail and Shopping Malls
- Industrial
- Food and Beverage
- Pharmaceuticals and Biotech
- Oil and Gas / Petrochemicals
- Automotive and Machinery
- Other Industrial
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific leads the air handling units market with 31.55% 2025 revenue. China's 185 million-unit air-conditioner production base anchors the regional supply chain, while India's HVAC spending trajectory toward USD 30 billion by 2030 at 15.8% CAGR boosts domestic AHU demand. Japan and South Korea advance retrofit activity through stringent IAQ revisions and successful underground-facility demonstrations that cut radon 98%. Local players collaborate with global OEMs to supply modular systems that satisfy diverse project timelines.
Europe's mature regulatory environment accelerates technology turnover. The Ecodesign framework pushes heat-recovery effectiveness and digital product passports, enlarging the air handling units market share of high-efficiency models. Industrial heat-pump deployment from Scandinavia to Germany drives >15,000 m3/h unit demand. Suppliers navigate extended conformity assessments for A2L refrigerants, but eventual approvals unlock a replacement cycle across aging installations.
The Middle East records the fastest 9.02% CAGR thanks to mega-projects in Saudi Arabia, Qatar and the UAE. District-cooling networks specify desert-ready rooftop AHUs that thrive at 50 °C. Government visions prioritize sustainability, rewarding equipment that reduces peak electricity loads. Meanwhile North America faces raw-material surcharges and technician shortages, yet hyperscale data centers are ordering modular thermal-management systems in volumes unprecedented for the region. The air handling units market size linked to data-center build-outs is projected to expand at double-digit rates through 2031.
- Daikin Industries Ltd.
- Carrier Global Corp.
- Trane Technologies plc
- Lennox International Inc.
- Johnson Controls International plc
- Systemair AB
- TROX GmbH
- Swegon Group AB
- Hitachi Ltd.
- Blue Star Ltd.
- FlaktGroup
- Greenheck Fan Corp.
- Nortek Air Solutions
- GEA Group AG
- Mitsubishi Electric Hydronics (Climaveneta)
- Dantherm A/S
- VTS Group
- Munters AB
- Howden Group
- Modine Manufacturing Co.
- CIAT Group (Carrier)
- TICA Industries
- Trosten Industries Co. LLC
- Johnson Controls-Hitachi Air Conditioning
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Healthcare and Pharma Clean-room Filtration Uptick in Asia
- 4.2.2 EU Ecodesign 2023/813 Mandating Lower SFP and Higher Heat-Recovery
- 4.2.3 Hyperscale Data-Centre Build-outs Requiring Modular Indirect Adiabatic AHUs (N. America)
- 4.2.4 Retrofit Demand for Energy-Recovery Ventilation in Japan and South Korea
- 4.2.5 GCC District-Cooling Projects Spurring Custom High-Ambient Rooftop AHUs
- 4.2.6 Electrification of Industrial Heat Loads Driving Heat-Pump AHUs Greater than15 000 m3/h (Europe)
- 4.3 Market Restraints
- 4.3.1 Volatile Aluminium and Copper Prices Inflating Coil/Fan Costs
- 4.3.2 Skilled-Labour Shortages Delaying On-site Assembly of Large Custom AHUs (US)
- 4.3.3 Decentralised DOAS Adoption as Substitute in Small Commercial Spaces
- 4.3.4 Lengthy EU Approvals for Low-GWP Refrigerant Equipment
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macro Trends on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Custom
- 5.1.2 Packaged
- 5.1.3 Modular
- 5.1.4 DX Integrated
- 5.1.5 Heat-Recovery Units
- 5.2 By Capacity
- 5.2.1 Less than 5,000
- 5.2.2 5,001 - 15,000
- 5.2.3 Greater than 15,000
- 5.3 By Installation Type
- 5.3.1 Indoor
- 5.3.2 Outdoor / Rooftop
- 5.4 By Technology
- 5.4.1 Heat-Pipe
- 5.4.2 Run-Around Coil
- 5.4.3 Plate Heat Exchanger
- 5.4.4 Desiccant-Based
- 5.4.5 Thermodynamic Heat Pump AHU
- 5.5 By Application
- 5.5.1 Comfort Ventilation
- 5.5.2 Process Ventilation and Dehumidification
- 5.6 By End-user
- 5.6.1 Residential
- 5.6.2 Commercial
- 5.6.2.1 Offices
- 5.6.2.2 Hospitality and Leisure
- 5.6.2.3 Healthcare Facilities
- 5.6.2.4 Educational Institutions
- 5.6.2.5 Retail and Shopping Malls
- 5.6.3 Industrial
- 5.6.3.1 Food and Beverage
- 5.6.3.2 Pharmaceuticals and Biotech
- 5.6.3.3 Oil and Gas / Petrochemicals
- 5.6.3.4 Automotive and Machinery
- 5.6.3.5 Other Industrial
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 United Kingdom
- 5.7.2.2 Germany
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Rest of Asia-Pacific
- 5.7.4 Middle East
- 5.7.4.1 Israel
- 5.7.4.2 Saudi Arabia
- 5.7.4.3 United Arab Emirates
- 5.7.4.4 Turkey
- 5.7.4.5 Rest of Middle East
- 5.7.5 Africa
- 5.7.5.1 South Africa
- 5.7.5.2 Egypt
- 5.7.5.3 Rest of Africa
- 5.7.6 South America
- 5.7.6.1 Brazil
- 5.7.6.2 Argentina
- 5.7.6.3 Rest of South America
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Daikin Industries Ltd.
- 6.4.2 Carrier Global Corp.
- 6.4.3 Trane Technologies plc
- 6.4.4 Lennox International Inc.
- 6.4.5 Johnson Controls International plc
- 6.4.6 Systemair AB
- 6.4.7 TROX GmbH
- 6.4.8 Swegon Group AB
- 6.4.9 Hitachi Ltd.
- 6.4.10 Blue Star Ltd.
- 6.4.11 FlaktGroup
- 6.4.12 Greenheck Fan Corp.
- 6.4.13 Nortek Air Solutions
- 6.4.14 GEA Group AG
- 6.4.15 Mitsubishi Electric Hydronics (Climaveneta)
- 6.4.16 Dantherm A/S
- 6.4.17 VTS Group
- 6.4.18 Munters AB
- 6.4.19 Howden Group
- 6.4.20 Modine Manufacturing Co.
- 6.4.21 CIAT Group (Carrier)
- 6.4.22 TICA Industries
- 6.4.23 Trosten Industries Co. LLC
- 6.4.24 Johnson Controls-Hitachi Air Conditioning
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


