
|
시장보고서
상품코드
2129351
네트워크 결합 스토리지(NAS) 시장 : 구성요소별, 서비스별, 제품 유형별, 스토리지 솔루션별, 도입 형태별, 최종 이용 산업별, 지역별 - 세계 예측(-2032년)Network-attached Storage Market, by Component & Service, Product Type, Storage Solution, Deployment Type, End-use Industry, & Region - Global Forecast to 2032 |
||||||

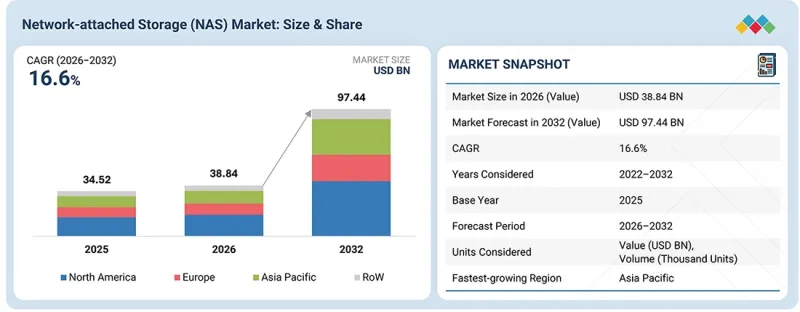
네트워크 결합 스토리지(NAS) 시장 규모는 2026년 388억 4,000만 달러에서 2032년에는 974억 4,000만 달러로 성장하여, CAGR은 16.6%를 기록할 것으로 예측됩니다.
이 시장은 기업 내 데이터 생성량 증가, 하이브리드 클라우드 환경 도입 확대, 중앙 집중화되고 확장성이 높으며 안전한 파일 스토리지 솔루션에 대한 수요 증가를 배경으로, 예측 기간 동안 강력한 성장을 이룰 것으로 전망됩니다. 기업들은 데이터 접근성을 향상시키고, 백업 및 재해 복구 기능을 강화하며, 분산된 기업 환경 전반에 걸쳐 비즈니스 연속성을 지원하기 위해 NAS 플랫폼에 대한 투자를 점점 더 늘리고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2032년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2032년 |
| 단위 | 금액(달러) |
| 부문 | 구성요소, 제품 유형, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 기타 지역 |
또한, AI, 빅데이터 분석, 가상화, 엣지 컴퓨팅의 채택 확대에 따라 기업들은 지능적이고 고성능의 NAS 솔루션을 활용하여 스토리지 인프라의 현대화를 추진하고 있습니다. 사이버 복원력, 규제 준수, 비용 효율적인 데이터 관리에 대한 관심이 높아지고 있는 점도 전 세계 네트워크 결합 스토리지(NAS) 시장의 장기적인 성장을 더욱 뒷받침하고 있습니다.
“설치 유형별로는 2026년에 랙 마운트가 가장 큰 시장 점유율을 차지할 것으로 추정됩니다.”
대용량이면서 확장 가능한 스토리지 인프라, 통합된 데이터 관리, 신뢰성 높은 백업 및 재해 복구 솔루션에 대한 기업의 수요가 높아짐에 따라 랙 마운트 부문이 가장 큰 점유율을 차지할 것으로 전망됩니다. 기업들은 데이터센터 공간을 최적화하고, 스토리지 효율을 향상시키며, 분산형 IT 환경 전반에서 고성능 워크로드를 지원하기 위해 랙 마운트 NAS 시스템 도입을 점점 더 확대하고 있습니다. 클라우드 컴퓨팅, 가상화, AI, 데이터 집약적 애플리케이션의 채택 확대 또한 랙 마운트 스토리지 솔루션에 대한 수요를 더욱 부추기고 있습니다. 또한 랙 마운트 NAS 시스템은 더 높은 스토리지 용량, 확장성, 중앙 집중식 관리, 기업 IT 인프라와의 효율적인 통합을 제공할 수 있다는 점에서 폭넓게 채택되고 있습니다. 데이터센터, 사이버 보안, 기업의 디지털 전환에 대한 투자 확대도 랙 마운트 부문의 성장에 더욱 기여하고 있습니다.
“도입 형태별로 보면 하이브리드 NAS 솔루션이 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 추정됩니다.”
이는 하이브리드 클라우드 전략의 채택 확대와 온프레미스 환경 및 클라우드 기반 환경을 아우르는 유연한 데이터 관리에 대한 수요에 힘입은 결과입니다. 조직들은 온프레미스 스토리지와 클라우드 기반 기능을 결합하기 위해 하이브리드 NAS 솔루션 도입을 점점 더 확대하고 있으며, 이를 통해 확장 가능한 용량, 데이터 접근성 향상, 효율적인 스토리지 관리가 가능해졌습니다. 기업 데이터의 증가, 비즈니스 연속성 및 재해 복구 수요의 증가, 클라우드 인프라에 대한 투자 확대가 하이브리드 NAS 솔루션 도입을 더욱 가속화하고 있습니다. 또한, AI, 가상화, 분석, 데이터 집약형 기업 애플리케이션의 활용 확대에 따라 분산 환경 전반에 걸친 워크로드를 지원할 수 있는 유연한 스토리지 플랫폼에 대한 수요가 발생하고 있습니다. 이러한 기능들이 전 세계 하이브리드 부문의 급속한 성장을 뒷받침하고 있습니다.
“아시아태평양은 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다.”
이 지역에서는 디지털 전환(DX) 노력의 확산, 클라우드 인프라의 급속한 확장, 전사적 차원의 AI, 빅데이터 분석, 엣지 컴퓨팅에 대한 투자 증가로 인해 2026년부터 2032년까지 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 기업에서는 통합 파일 스토리지, 비즈니스 연속성, 안전한 데이터 공유, 고성능 데이터 관리를 지원하기 위해 NAS 솔루션 도입이 점점 더 확대되고 있습니다. 또한, 하이브리드 클라우드 아키텍처의 채택 확대, 기업 데이터 생성량 증가, 데이터센터에 대한 투자 확대에 힘입어 해당 지역 전체에서 첨단 NAS 솔루션에 대한 강력한 수요가 발생하고 있습니다. 디지털 인프라 개발을 지원하는 정부의 노력에 더해, 기업의 IT 현대화 및 사이버 보안에 대한 투자 증가가 맞물려 아시아태평양의 급속한 성장에 더욱 기여하고 있습니다.
본 보고서에서는 전 세계 네트워크 결합 스토리지(NAS) 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추정 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 정리하고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신, 향후 용도
제7장 규제 상황
제8장 고객 상황과 구매 행동
제9장 네트워크 결합 스토리지(NAS) 시장 : 구성요소별
제10장 네트워크 결합 스토리지(NAS) 시장 : 스토리지 솔루션별
제11장 네트워크 결합 스토리지(NAS) 시장 : 도입 형태별
제12장 네트워크 결합 스토리지(NAS) 시장 : 장착 유형별
제13장 네트워크 결합 스토리지(NAS) 시장 : 베이수별
제14장 네트워크 결합 스토리지(NAS) 시장 : 제품별
제15장 네트워크 결합 스토리지(NAS) 시장 : 최종 이용 산업별
제16장 네트워크 결합 스토리지(NAS) 시장 : 지역별
제17장 경쟁 구도
제18장 기업 개요
제19장 조사 방법
제20장 부록
KSM 26.09.17The network-attached storage (NAS) market is projected to grow from USD 38.84 billion in 2026 to USD 97.44 billion by 2032, registering a CAGR of 16.6%. The market is expected to witness strong growth during the forecast period, driven by increasing enterprise data generation, rising adoption of hybrid cloud environments, and growing demand for centralized, scalable, and secure file storage solutions. Organizations are increasingly investing in NAS platforms to improve data accessibility, strengthen backup and disaster recovery capabilities, and support business continuity across distributed enterprise environments.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Billion) |
| Segments | By Component, Product Type and Region |
| Regions covered | North America, Europe, APAC, RoW |
In addition, the growing adoption of artificial intelligence (AI), big data analytics, virtualization, and edge computing is encouraging enterprises to modernize their storage infrastructure with intelligent, high-performance NAS solutions. The increasing focus on cyber resilience, regulatory compliance, and cost-effective data management is further supporting the long-term expansion of the network-attached storage (NAS) market globally.
"By mount type, rackmount is estimated to hold the largest market share in 2026."
The rackmount segment is likely to hold the largest share of the network-attached storage (NAS) market due to increasing enterprise demand for high-capacity, scalable storage infrastructure, centralized data management, and reliable backup and disaster recovery solutions. Organizations are increasingly deploying rackmount NAS systems to optimize data center space, improve storage efficiency, and support high-performance workloads across distributed IT environments. The growing adoption of cloud computing, virtualization, artificial intelligence (AI), and data-intensive applications is further driving demand for rackmount storage solutions. In addition, the ability of rackmount NAS systems to provide higher storage capacity, scalability, centralized management, and efficient integration with enterprise IT infrastructure is supporting their widespread adoption. Growing investments in data centers, cybersecurity, and enterprise digital transformation are further contributing to the expansion of the rackmount segment.
"Based on deployment type, hybrid NAS solutions are estimated to record the highest CAGR during the forecast period."
The hybrid segment is expected to register the highest CAGR from 2026 to 2032 in the network-attached storage (NAS) market, driven by the growing adoption of hybrid cloud strategies and the need for flexible data management across on-premises and cloud-based environments. Organizations are increasingly deploying hybrid NAS solutions to combine on-premises storage with cloud-based capabilities, enabling scalable capacity, improved data accessibility, and efficient storage management. The growing volume of enterprise data, rising demand for business continuity and disaster recovery, and increasing investments in cloud infrastructure are further accelerating the adoption of hybrid NAS solutions. In addition, the growing use of artificial intelligence (AI), virtualization, analytics, and data-intensive enterprise applications is creating demand for flexible storage platforms that can support workloads across distributed environments. These capabilities are supporting the rapid growth of the hybrid segment globally.
"Asia Pacific is expected to register the highest CAGR during the forecast period."
Asia Pacific (APAC) is expected to register the highest CAGR from 2026 to 2032 in the network-attached storage (NAS) market due to the increasing adoption of digital transformation initiatives, rapid expansion of cloud infrastructure, and growing investments in artificial intelligence (AI), big data analytics, and edge computing across enterprises. Organizations are increasingly deploying NAS solutions to support centralized file storage, business continuity, secure data sharing, and high-performance data management. In addition, the growing adoption of hybrid cloud architectures, rising enterprise data generation, and expanding investments in data centers are creating strong demand for advanced NAS solutions across the region. Government initiatives supporting digital infrastructure development, together with increasing investments in enterprise IT modernization and cybersecurity, are further contributing to the rapid growth of the network-attached storage (NAS) market in Asia Pacific.
Extensive primary interviews were conducted with key industry experts in the network-attached storage (NAS) ecosystem to determine and verify the market size for various segments and subsegments gathered through secondary research. The breakdown of primary participants for the report is provided below:
The study contains insights from various industry experts, including NAS hardware manufacturers, storage software providers, system integrators, cloud service providers, value-added resellers (VARs), distributors, enterprise end users, and technology consultants. The break-up of the primaries is as follows:
- By Company Type: Tier 1-50%, Tier 2-20%, and Tier 3-30%
- By Designation: C-level-10%, Directors-10%, and Others-70%
- By Region: North America-15%, Europe-55%, Asia Pacific-20%, and RoW-10%
The report profiles key players in the network-attached storage (NAS) market with their respective market ranking analysis. Prominent players profiled in this report are NetApp, Inc. (US), Dell Technologies Inc. (US), Western Digital Corporation (US), Hewlett Packard Enterprise Company (US), and Huawei Technologies Co., Ltd. (China).
Apart from these, Everpure, Inc. (US), Seagate Technology LLC (Ireland), IBM Corporation (US), Synology, Inc. (Taiwan), QNAP Systems, Inc. (Taiwan), iXsystems, Inc. (US), Buffalo Americas, Inc. (US), Infortrend Technology, Inc. (Taiwan), PROMISE Technology, Inc. (Taiwan), QSAN Technology, Inc. (Taiwan), ASUSTOR Inc. (Taiwan), TerraMaster Technology Co., Ltd. (China), Thecus Technology Corp. (Taiwan) are among the few other companies in the network-attached storage market.
Research Coverage:
This research report categorizes the network-attached storage (NAS) market based on component & service, storage solution, deployment type, mount type, design, product type, end-use industry, and region. The report describes the major drivers, restraints, challenges, and opportunities pertaining to the network-attached storage (NAS) market and forecasts the market through 2032. Apart from this, the report also consists of leadership mapping and analysis of all the companies included in the network-attached storage (NAS) market ecosystem.
Key Benefits of Buying the Report
The report will help the leaders/new entrants in this market with information on the closest approximations of the numbers for the overall network-attached storage (NAS) market and its subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. It also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (Increasing demand for centralized file storage solutions due to growing enterprise data volumes), restraints (High initial deployment and infrastructure costs associated with enterprise NAS solutions), opportunities (Increasing adoption of all-flash NAS solutions for high-performance workloads), and challenges (Managing exponential growth of unstructured data across enterprises).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & software launches in the network-attached storage (NAS) market.
- Market Development: Comprehensive information about lucrative markets-the report analyzes the network-attached storage (NAS) market across varied regions.
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the network-attached storage (NAS) market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and product offerings of leading players such as NetApp, Inc. (US), Dell Technologies Inc. (US), Huawei Technologies Co., Ltd. (China), Everpure, Inc. (US), and Hewlett Packard Enterprise Company (US) in the network-attached storage (NAS) market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 LIMITATIONS
- 1.7 STAKEHOLDERS
- 1.8 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN NETWORK ATTACHED STORAGE (NAS) MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN NETWORK ATTACHED STORAGE (NAS) MARKET
- 3.2 NETWORK ATTACHED STORAGE (NAS) MARKET, BY DESIGN
- 3.3 NETWORK ATTACHED STORAGE (NAS) MARKET, BY DEVELOPMENT TYPE
- 3.4 NETWORK ATTACHED STORAGE (NAS) MARKET, BY STORAGE SOLUTION
- 3.5 NETWORK ATTACHED STORAGE (NAS) MARKET, BY PRODUCT
- 3.6 NETWORK ATTACHED STORAGE (NAS) MARKET, BY END-USE INDUSTRY
- 3.7 NETWORK ATTACHED STORAGE (NAS) MARKET, BY MOUNT TYPE
- 3.8 NETWORK ATTACHED STORAGE (NAS) MARKET, BY GEOGRAPHY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing volume of enterprise data generation due to digitalization
- 4.2.1.2 Rising adoption of hybrid cloud and multi-cloud storage architectures
- 4.2.1.3 Increasing deployment of AI, ML, HPC, and advanced analytics
- 4.2.1.4 Strong focus on cyber resilience and data loss prevention
- 4.2.2 RESTRAINTS
- 4.2.2.1 High initial deployment and infrastructure costs
- 4.2.2.2 Performance limitations associated with network bandwidth and latency
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Transition toward all-flash NAS systems to support high-performance workloads
- 4.2.3.2 Proliferation of edge computing
- 4.2.3.3 Integration of NAS with cloud-native and hybrid IT platforms
- 4.2.4 CHALLENGES
- 4.2.4.1 Issues in managing unstructured data across enterprises
- 4.2.4.2 Data governance, compliance, and cybersecurity challenges
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 INTRODUCTION
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 THREAT OF NEW ENTRANTS
- 5.2.2 THREAT OF SUBSTITUTES
- 5.2.3 BARGAINING POWER OF SUPPLIERS
- 5.2.4 BARGAINING POWER OF BUYERS
- 5.2.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.3 MACROECONOMIC OUTLOOK
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.3.3 TRENDS IN GLOBAL DATA GENERATION INDUSTRY
- 5.3.4 TRENDS IN GLOBAL DATA CENTER INDUSTRY
- 5.4 SUPPLY CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 PRICING RANGE OF NAS SYSTEMS OFFERED BY KEY PLAYERS, BY END-USE INDUSTRY, 2025
- 5.6.2 AVERAGE SELLING PRICE TREND OF NAS SYSTEMS, BY REGION, 2022-2025
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 847170)
- 5.7.2 EXPORT SCENARIO (HS CODE 847170)
- 5.8 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 INVESTMENT AND FUNDING SCENARIO
- 5.11 CASE STUDY ANALYSIS
- 5.11.1 DREAMWORKS ANIMATION ADOPTS NETAPP ENTERPRISE STORAGE SOLUTIONS TO ENABLE AI-READY DIGITAL CONTENT CREATION
- 5.11.2 SAMSUNG SDS DEPLOYS DELL AI FACTORY WITH NVIDIA TO DELIVER HIGH-PERFORMANCE, SCALABLE AI STORAGE AND COMPUTING INFRASTRUCTURE
- 5.11.3 SUBARU LEVERAGES DELL POWERSCALE STORAGE TO EXPAND DATA STORAGE AND ANALYTICS CAPABILITIES
- 5.12 IMPACT OF US TARIFFS - NETWORK ATTACHED STORAGE (NAS) MARKET
- 5.12.1 INTRODUCTION
- 5.12.2 KEY TARIFF RATES
- 5.12.3 PRICE IMPACT ANALYSIS
- 5.12.4 IMPACT ON COUNTRIES/REGIONS
- 5.12.4.1 US
- 5.12.4.2 Europe
- 5.12.4.3 Asia Pacific
- 5.12.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 SCALE-OUT AND CLUSTERED NAS
- 6.1.2 ALL-FLASH NAS
- 6.1.3 CLOUD-INTEGRATED AND HYBRID NAS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 SOFTWARE-DEFINED STORAGE
- 6.2.2 VIRTUALIZATION AND CONTAINER STORAGE
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 AI-DRIVEN STORAGE MANAGEMENT AND PREDICTIVE ANALYTICS
- 6.3.2 OBJECT STORAGE
- 6.4 PATENT ANALYSIS
- 6.5 IMPACT OF AI/GEN AI ON NETWORK ATTACHED STORAGE (NAS) MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL
- 6.5.2 BEST PRACTICES FOLLOWED BY OEMS IN NETWORK ATTACHED STORAGE (NAS) MARKET
- 6.5.3 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN NETWORK ATTACHED STORAGE (NAS) MARKET
- 6.5.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT AI/GEN AI-INTEGRATED NAS SOLUTIONS
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATORY STANDARDS
- 7.1.2.1 NIST Special Publication 800-53
- 7.1.2.2 Critical Infrastructure Protection Standards
- 7.1.2.3 ISO/IEC 24775
- 7.1.2.4 ISO 14001:2015
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
9 NETWORK ATTACHED STORAGE (NAS) MARKET, BY COMPONENT
- 9.1 INTRODUCTION
- 9.2 HARDWARE
- 9.2.1 HDDS
- 9.2.1.1 High storage capacity and cost-effectiveness to accelerate segmental growth
- 9.2.2 SSDS
- 9.2.2.1 Superior performance, low latency, high IOPS, and energy efficiency to foster segmental growth
- 9.2.3 OTHER HARDWARE
- 9.2.1 HDDS
- 9.3 SOFTWARE
- 9.3.1 RELIANCE ON INTELLIGENT PLATFORMS TO MANAGE GROWING DATA VOLUMES TO AUGMENT SEGMENTAL GROWTH
- 9.4 SERVICES
- 9.4.1 FOCUS ON EFFICIENT OPERATION AND LONG-TERM PERFORMANCE OPTIMIZATION TO EXPEDITE SEGMENTAL GROWTH
10 NETWORK ATTACHED STORAGE (NAS) MARKET, BY STORAGE SOLUTION
- 10.1 INTRODUCTION
- 10.2 SCALE-UP NAS
- 10.2.1 CENTRALIZED STORAGE WITH SCALABLE CAPACITY TO ACCELERATE SEGMENTAL GROWTH
- 10.3 SCALE-OUT NAS
- 10.3.1 SCALABLE ARCHITECTURE WITH COST-EFFICIENT EXPANSION TO BOLSTER SEGMENTAL GROWTH
11 NETWORK ATTACHED STORAGE (NAS) MARKET, BY DEPLOYMENT TYPE
- 11.1 INTRODUCTION
- 11.2 ON-PREMISES
- 11.2.1 HIGH SECURITY AND CONTROL OVER APPLICATIONS, SYSTEMS, AND DATA TO EXPEDITE SEGMENTAL GROWTH
- 11.3 CLOUD
- 11.3.1 LOW OWNERSHIP COST AND CUSTOMIZATION OPTIONS TO AUGMENT SEGMENTAL GROWTH
- 11.4 HYBRID
- 11.4.1 PERFORMANCE EFFICIENCY, SCALABILITY, MANAGEABILITY, AND COST REDUCTION TO FOSTER SEGMENTAL GROWTH
12 NETWORK ATTACHED STORAGE (NAS) MARKET, BY MOUNT TYPE
- 12.1 INTRODUCTION
- 12.2 DESKTOP
- 12.2.1 EASE OF DEPLOYMENT, LOW POWER CONSUMPTION, AND SIMPLIFIED MANAGEMENT TO SPUR DEMAND
- 12.3 RACKMOUNT
- 12.3.1 REQUIREMENT FOR HIGH STORAGE DENSITY, SUPERIOR PERFORMANCE, AND CONTINUOUS AVAILABILITY TO DRIVE MARKET
13 NETWORK ATTACHED STORAGE (NAS) MARKET, BY DESIGN
- 13.1 INTRODUCTION
- 13.2 1 TO 4 BAY
- 13.2.1 COMPACT FORM FACTOR, LOW POWER CONSUMPTION, AND SIMPLIFIED DEPLOYMENT TO FUEL SEGMENTAL GROWTH
- 13.3 5 TO 8 BAY
- 13.3.1 STORAGE SCALABILITY, OPERATIONAL EFFICIENCY, AND COST-EFFECTIVENESS TO CONTRIBUTE TO SEGMENTAL GROWTH
- 13.4 9 TO 16 BAY
- 13.4.1 HIGH-CAPACITY, PERFORMANCE STORAGE PLATFORMS FOR BUSINESS-CRITICAL WORKLOADS TO DRIVE MARKET
- 13.5 ABOVE 16 BAY
- 13.5.1 HIGH STORAGE DENSITY AND SCALABILITY TO EXPEDITE SEGMENTAL GROWTH
14 NETWORK ATTACHED STORAGE (NAS) MARKET, BY PRODUCT
- 14.1 INTRODUCTION
- 14.2 ENTRY-LEVEL NAS
- 14.2.1 AFFORDABILITY, EASE OF DEPLOYMENT, AND USER-FRIENDLY MANAGEMENT INTERFACES TO BOLSTER SEGMENTAL GROWTH
- 14.3 ENTERPRISE NAS
- 14.3.1 ABILITY TO PROVIDE CENTRALIZED STORAGE, ADVANCED SECURITY, AND INTELLIGENT DATA MANAGEMENT TO FACILITATE SEGMENTAL GROWTH
- 14.4 MID-RANGE NAS
- 14.4.1 NEED FOR HIGH PERFORMANCE, SCALABILITY, AND DATA PROTECTION TO AUGMENT SEGMENTAL GROWTH
15 NETWORK ATTACHED STORAGE (NAS) MARKET, BY END-USE INDUSTRY
- 15.1 INTRODUCTION
- 15.2 BFSI
- 15.2.1 RISING DIGITAL BANKING AND DEMAND FOR CUSTOMER-CENTRIC FINANCIAL SERVICES TO AUGMENT SEGMENTAL GROWTH
- 15.3 TELECOMMUNICATIONS & ITES
- 15.3.1 MOUNTING DEMAND FOR DIGITAL SERVICES, CLOUD COMPUTING, AND ENTERPRISE DATA MANAGEMENT TO FUEL SEGMENTAL GROWTH
- 15.4 CONSUMER GOODS & RETAIL
- 15.4.1 STRONG FOCUS ON MANAGING DATA GENERATED THROUGH OMNICHANNEL RETAIL OPERATIONS AND ONLINE TRANSACTIONS TO DRIVE MARKET
- 15.5 HEALTHCARE
- 15.5.1 INCREASING ELECTRONIC HEALTH RECORDS (EHRS), AI-ASSISTED DIAGNOSTICS, AND PRECISION MEDICINES TO AUGMENT SEGMENTAL GROWTH
- 15.6 GOVERNMENT
- 15.6.1 ACCELERATING DIGITAL TRANSFORMATION TO IMPROVE PUBLIC SERVICE DELIVERY AND ADMINISTRATIVE EFFICIENCY TO FOSTER SEGMENTAL GROWTH
- 15.7 MEDIA & ENTERTAINMENT
- 15.7.1 GROWING DEMAND FOR DIGITAL ASSET MANAGEMENT, REMOTE CONTENT CREATION, AND AI-ENABLED MEDIA WORKFLOWS TO DRIVE MARKET
- 15.8 EDUCATION & RESEARCH
- 15.8.1 INCREASING RELIANCE ON DIGITAL LABORATORIES AND HYBRID LEARNING ENVIRONMENTS TO ACCELERATE SEGMENTAL GROWTH
- 15.9 MANUFACTURING
- 15.9.1 RISING ADOPTION OF INDUSTRY 4.0 TECHNOLOGIES TO IMPROVE PRODUCTION EFFICIENCY TO BOLSTER SEGMENTAL GROWTH
- 15.10 ENERGY
- 15.10.1 INCREASING DEPLOYMENT OF SMART GRIDS, RENEWABLE PROJECTS, AND DIGITAL SUBSTATIONS TO FOSTER SEGMENTAL GROWTH
- 15.11 OTHER END-USE INDUSTRIES
16 NETWORK ATTACHED STORAGE (NAS) MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 US
- 16.2.1.1 Rapid advances in digital infrastructure and high enterprise IT spending to contribute to market growth
- 16.2.2 CANADA
- 16.2.2.1 Increasing investment in digital infrastructure, cloud computing, AI, and enterprise data management to expedite market growth
- 16.2.3 MEXICO
- 16.2.3.1 Growing emphasis on manufacturing expansion and enterprise digital transformation to support market growth
- 16.2.1 US
- 16.3 EUROPE
- 16.3.1 UK
- 16.3.1.1 Strong focus on enterprise digital transformation and cloud adoption to accelerate market growth
- 16.3.2 GERMANY
- 16.3.2.1 Mounting deployment of Industry 4.0 and Industry 5.0 technologies to accelerate market growth
- 16.3.3 FRANCE
- 16.3.3.1 High investment in cloud infrastructure, AI, and enterprise cybersecurity to bolster market growth
- 16.3.4 ITALY
- 16.3.4.1 Increasing investment in cloud computing, digital transformation, and data-intensive applications to drive market
- 16.3.5 REST OF EUROPE
- 16.3.1 UK
- 16.4 ASIA PACIFIC
- 16.4.1 CHINA
- 16.4.1.1 Rapid digital transformation and investments in cloud computing and enterprise IT modernization to expedite market growth
- 16.4.2 JAPAN
- 16.4.2.1 Increasing smart manufacturing and digital government initiatives to boost market growth
- 16.4.3 INDIA
- 16.4.3.1 Rapid digital transformation, cloud adoption, and enterprise IT investments to contribute to market growth
- 16.4.4 SOUTH KOREA
- 16.4.4.1 Thriving semiconductor industry, high digital connectivity, and focus on smart manufacturing to drive market
- 16.4.5 REST OF ASIA PACIFIC
- 16.4.1 CHINA
- 16.5 ROW
- 16.5.1 SOUTH AMERICA
- 16.5.1.1 Expanding digital infrastructure and enterprise IT modernization to augment market growth
- 16.5.2 MIDDLE EAST
- 16.5.2.1 Rising hyperscale data centers, smart-city infrastructure, and digital government initiatives to fuel market growth
- 16.5.3 AFRICA
- 16.5.3.1 Increasing investment in digital infrastructure, enterprise digitalization, and data center development to fuel market growth
- 16.5.1 SOUTH AMERICA
17 COMPETITIVE LANDSCAPE
- 17.1 OVERVIEW
- 17.2 KEY PLAYER COMPETITIVE STRATEGIES, RIGHT TO WIN, 2023-2026
- 17.3 MARKET SHARE ANALYSIS, 2025
- 17.4 REVENUE ANALYSIS, 2021-2025
- 17.5 COMPANY VALUATION AND FINANCIAL METRICS
- 17.6 BRAND/PRODUCT COMPARISON
- 17.6.1 NETAPP. (US)
- 17.6.2 DELL INC. (US)
- 17.6.3 HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP (US)
- 17.6.4 WESTERN DIGITAL CORPORATION (US)
- 17.6.5 HUAWEI TECHNOLOGIES CO., LTD. (CHINA)
- 17.7 COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- 17.7.1 STARS
- 17.7.2 EMERGING LEADERS
- 17.7.3 PERVASIVE PLAYERS
- 17.7.4 PARTICIPANTS
- 17.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 17.7.5.1 Company footprint
- 17.7.5.2 Region footprint
- 17.7.5.3 Storage solution footprint
- 17.7.5.4 Mount type footprint
- 17.7.5.5 End-use industry footprint
- 17.7.5.6 Product footprint
- 17.8 COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- 17.8.1 PROGRESSIVE COMPANIES
- 17.8.2 RESPONSIVE COMPANIES
- 17.8.3 DYNAMIC COMPANIES
- 17.8.4 STARTING BLOCKS
- 17.8.4.1 Detailed list of key startups/SMEs
- 17.8.4.2 Competitive benchmarking of key startups/SMEs
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 PRODUCT LAUNCHES/ENHANCEMENTS
- 17.9.2 DEALS
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 NETAPP
- 18.1.1.1 Business overview
- 18.1.1.2 Products/Solutions/Services offered
- 18.1.1.3 Recent developments
- 18.1.1.3.1 Product launches/enhancements
- 18.1.1.3.2 Deals
- 18.1.1.4 MnM view
- 18.1.1.4.1 Key strengths/Right to win
- 18.1.1.4.2 Strategic choices made
- 18.1.1.4.3 Weaknesses/Competitive threats
- 18.1.2 DELL INC.
- 18.1.2.1 Business overview
- 18.1.2.2 Products/Solutions/Services offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Product launches/enhancements
- 18.1.2.3.2 Deals
- 18.1.2.4 MnM view
- 18.1.2.4.1 Key strengths/Right to win
- 18.1.2.4.2 Strategic choices made
- 18.1.2.4.3 Weaknesses/Competitive threats
- 18.1.3 HUAWEI TECHNOLOGIES CO., LTD.
- 18.1.3.1 Business overview
- 18.1.3.2 Products/Solutions/Services offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product launches/enhancements
- 18.1.3.4 MnM view
- 18.1.3.4.1 Key strengths/Right to win
- 18.1.3.4.2 Strategic choices made
- 18.1.3.4.3 Weaknesses/Competitive threats
- 18.1.4 HEWLETT PACKARD ENTERPRISE DEVELOPMENT LP
- 18.1.4.1 Business overview
- 18.1.4.2 Products/Solutions/Services offered
- 18.1.4.3 Recent developments
- 18.1.4.3.1 Product launches/enhancements
- 18.1.4.3.2 Deals
- 18.1.4.4 MnM view
- 18.1.4.4.1 Key strengths/Right to win
- 18.1.4.4.2 Strategic choices made
- 18.1.4.4.3 Weaknesses/Competitive threats
- 18.1.5 WESTERN DIGITAL CORPORATION
- 18.1.5.1 Business overview
- 18.1.5.2 Products/Solutions/Services offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Product launches/enhancements
- 18.1.5.4 MnM view
- 18.1.5.4.1 Key strengths/Right to win
- 18.1.5.4.2 Strategic choices made
- 18.1.5.4.3 Weaknesses/Competitive threats
- 18.1.6 EVERPURE, INC
- 18.1.6.1 Business overview
- 18.1.6.2 Products/Solutions/Services offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Product launches/enhancements
- 18.1.6.3.2 Other developments
- 18.1.7 SEAGATE TECHNOLOGY LLC
- 18.1.7.1 Business overview
- 18.1.7.2 Products/Solutions/Services offered
- 18.1.7.3 Recent developments
- 18.1.7.3.1 Product launches/enhancements
- 18.1.8 IBM CORPORATION
- 18.1.8.1 Business overview
- 18.1.8.2 Products/Solutions/Services offered
- 18.1.8.3 Recent developments
- 18.1.8.3.1 Product launches/enhancements
- 18.1.8.3.2 Deals
- 18.1.9 SYNOLOGY INC.
- 18.1.9.1 Business overview
- 18.1.9.2 Products/Solutions/Services offered
- 18.1.9.3 Recent developments
- 18.1.9.3.1 Product launches/enhancements
- 18.1.9.3.2 Deals
- 18.1.10 QNAP SYSTEMS, INC.
- 18.1.10.1 Business overview
- 18.1.10.2 Products/Solutions/Services offered
- 18.1.10.3 Recent developments
- 18.1.10.3.1 Product launches/enhancements
- 18.1.1 NETAPP
- 18.2 OTHER PLAYERS
- 18.2.1 IXSYSTEMS, INC.
- 18.2.2 BUFFALO AMERICAS, INC.
- 18.2.3 INFORTREND TECHNOLOGY, INC.
- 18.2.4 PROMISE TECHNOLOGY INC.
- 18.2.5 NETGEAR
- 18.2.6 QSAN TECHNOLOGY, INC.
- 18.2.7 ASUSTOR, INC.
- 18.2.8 TERRAMASTER
- 18.2.9 THECUS
- 18.2.10 BUURST
- 18.2.11 NASUNI
- 18.2.12 HITACHI VANTARA LLC
- 18.2.13 DATADIRECT NETWORKS (DDN)
- 18.2.14 OPEN-E
- 18.2.15 CTERA NETWORKS LTD.
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH DATA
- 19.1.1 SECONDARY DATA
- 19.1.1.1 List of key secondary sources
- 19.1.1.2 Key data from secondary sources
- 19.1.2 PRIMARY DATA
- 19.1.2.1 List of primary interview participants
- 19.1.2.2 Key data from primary sources
- 19.1.2.3 Key industry insights
- 19.1.2.4 Breakdown of primary interviews
- 19.1.3 SECONDARY AND PRIMARY RESEARCH
- 19.1.1 SECONDARY DATA
- 19.2 MARKET SIZE ESTIMATION
- 19.2.1 BOTTOM-UP APPROACH
- 19.2.1.1 Approach to arrive at market size using bottom-up analysis (demand side)
- 19.2.2 TOP-DOWN APPROACH
- 19.2.2.1 Approach to arrive at market size using top-down analysis (supply side)
- 19.2.1 BOTTOM-UP APPROACH
- 19.3 DATA TRIANGULATION
- 19.4 RESEARCH ASSUMPTIONS
- 19.5 RESEARCH LIMITATIONS
- 19.6 RISK ANALYSIS
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS


