
|
시장보고서
상품코드
2130443
DDoS 보호 및 완화 시장 : 제공 제품별, 솔루션 유형별, 응용 영역별, 도입 모드별, 조직 규모별, 업계별, 지역별 예측(-2031년)DDoS Protection and Mitigation Market by Solution Type (Network Traffic Analyzers, Botnet Detection & Management), Application Area (Network & IP, Web Applications & API, DNS Infrastructure), Vertical (BFSI, Energy & Utilities) - Global Forecast to 2031 |
||||||

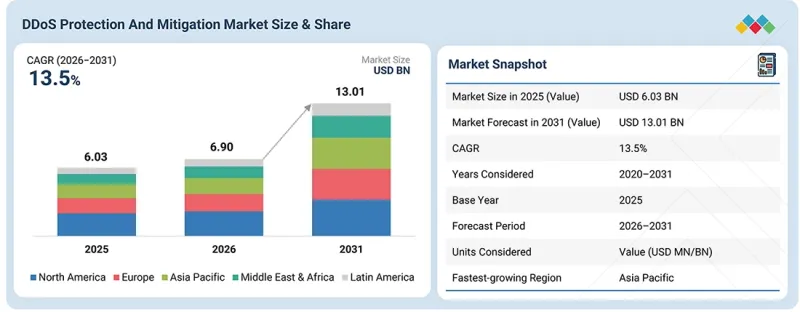
DDoS 보호 및 완화 시장 규모는 2026년 69억 달러에서 2031년에는 130억 1,000만 달러에 이를 것으로 예상되며, 예측 기간 동안 CAGR 13.5%를 나타낼 전망입니다.
기업들이 디지털 복원력과 서비스의 지속적인 가용성을 우선시함에 따라 이 시장의 전략적 중요성이 높아지고 있습니다. 주요 성장 요인으로는 DDoS 공격의 빈도와 고도화가 진행되고 있는 점, 클라우드 전환, IoT, API, 5G로 인한 공격 노출 증가, 그리고 디지털 서비스 및 온라인 거래의 급속한 확대 등을 들 수 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2020-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(100만 달러/10억 달러) |
| 부문 | 제공 제품별, 솔루션 유형별, 응용 영역별, 도입 모드별, 조직 규모별, 업계별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카 |
AI를 활용한 자동화된 공격 기법의 대두로 인해 실시간 감지 및 대응의 필요성이 더욱 높아지고 있습니다. 한편, 규제 압력의 강화, 평판 리스크, 그리고 관리형 보안 서비스 및 클라우드 기반 보호에 대한 수요 증가가 기업의 투자를 가속화하고 있습니다.
“2026년에는 네트워크 트래픽 분석기 부문이 가장 큰 시장 점유율을 차지할 것으로 전망됩니다.”
솔루션 유형별로는 네트워크 트래픽 분석기 부문이 2026년에 DDoS 보호 및 완화 시장에서 가장 큰 점유율을 차지할 것으로 예측됩니다. 이는 네트워크 트래픽을 지속적으로 모니터링하고 DDoS 공격과 관련된 비정상적인 패턴을 식별하려는 수요가 증가하고 있기 때문입니다. 네트워크 트래픽 분석기는 트래픽 양, 발신 및 수신처의 행동 양상, 프로토콜 활동, 확립된 트래픽 패턴으로부터의 급격한 일탈에 대한 가시성을 제공하여, 조직이 잠재적인 공격을 조기에 식별할 수 있도록 지원합니다. 대용량 및 다중 벡터형 DDoS 공격의 규모와 복잡성이 증가함에 따라 기업, 통신 사업자, 클라우드 서비스 제공업체, 데이터센터 운영자는 전용 트래픽 분석 기능을 도입하고 있습니다. 이러한 솔루션은 대량의 네트워크 트래픽을 분석하고, 자동화 또는 협업적인 완화 조치를 지원하는 경고를 제공할 수 있습니다. 또한, 하이브리드 및 분산형 네트워크 환경의 도입이 확대됨에 따라 여러 인프라 거점에 걸친 통합된 트래픽 가시성에 대한 필요성도 높아지고 있습니다. 각 벤더는 정교한 공격 패턴의 감지 정확도를 높이기 위해 행동 분석, 머신 러닝, 위협 인텔리전스, 자동 감지 기능을 네트워크 트래픽 분석 솔루션에 통합하고 있습니다. 또한, 소프트웨어 기반 트래픽 분석 플랫폼의 도입 확대에 따라 조직은 모니터링 기능을 기존 네트워크 및 보안 인프라와 통합할 수 있게 되어, 이 분야의 보급이 가속화되고 있습니다. 조직이 서비스 중단을 최소화하기 위해 지속적인 가시성과 조기 감지를 우선시함에 따라, 네트워크 트래픽 분석기에 대한 수요는 계속해서 견조할 것으로 예상되며, 이는 해당 부문 시장에서 선도적인 입지를 뒷받침할 것으로 전망됩니다.
“예측 기간 동안 웹 용도 및 API 부문이 가장 높은 성장률을 보일 것으로 전망됩니다.”
응용 분야별로는 디지털 서비스, API 주도 아키텍처, 클라우드 네이티브 애플리케이션, 온라인 고객 플랫폼의 급속한 확장에 힘입어 웹 용도 및 API 부문이 2026년부터 2031년까지 가장 높은 성장률을 나타낼 것으로 예측됩니다. 조직들은 금융 서비스, 전자상거래, 디지털 헬스케어, 행정 서비스 및 엔터프라이즈 용도를 제공하기 위해 웹사이트, 웹 용도, API 및 애플리케이션 프로그래밍 인터페이스에 대한 의존도를 높이고 있습니다. 이러한 의존도 증가로 인해 용도 계층 DDoS 공격의 영향이 확대되고 있습니다. 이러한 유형의 공격은 기존의 볼륨형 공격에서 볼 수 있는 트래픽 패턴을 반드시 생성하지는 않으면서도, 언뜻 보기에 정상적으로 보이는 대량의 요청을 통해 용도 리소스를 고갈시킬 가능성이 있습니다. 용도, 클라우드 서비스, 모바일 애플리케이션 및 타사 플랫폼 간의 연결 계층으로서 API의 활용이 확대되고 있는 점도 추가적인 취약점을 야기하고 있습니다. 아카마이(Akamai)는 지난 2년 동안 레이어 7 DDoS 공격이 104% 증가했다고 보고하며, 용도 환경에 대한 위협이 커지고 있음을 여실히 보여주고 있습니다. 이에 대응하여 각 벤더들은 용도를 인식하는 트래픽 분석, 행동 감지, 봇 관리, API 보호, 속도 제한 및 자동 완화 기능을 DDoS 방어 플랫폼에 통합하여 대응하고 있습니다. 마이크로서비스, 컨테이너, 멀티클라우드 환경, AI 지원 용도의 도입 확대에 따라 인터넷에 공개되는 용도 엔드포인트의 수는 더욱 증가할 것으로 예측됩니다. 그 결과, 조직들은 웹 용도과 API에 대한 전문적인 보호를 점점 더 우선시하게 되어, 이 응용 분야의 급속한 성장을 뒷받침하고 있습니다.
“2026년부터 2031년에 걸쳐 아시아태평양이 가장 높은 성장률을 기록할 전망”
아시아태평양은 급속한 디지털화, 클라우드 인프라의 확대, 인터넷 보급률 향상, 그리고 전자상거래 및 디지털 결제 생태계의 성장에 힘입어 예측 기간 동안 DDoS 보호 및 완화 시장에서 가장 높은 성장률을 보일 것으로 예측됩니다. 중국, 인도, 일본, 한국, 싱가포르, 호주 등의 국가에서는 데이터센터, 5G 네트워크, 클라우드 서비스, 디지털 플랫폼에 막대한 투자가 이루어지고 있어 DDoS 위협에 대한 공격 표면이 확대되고 있습니다. 또한, 해당 지역에서는 금융 서비스, 통신, 정부 기관, 디지털 비즈니스를 표적으로 한 사이버 공격이 증가하고 있습니다. 그 결과, 조직들은 회복탄력성을 강화하고 디지털 서비스를 중단 없이 유지하기 위해 클라우드 기반 DDoS 방어, 자동화된 완화 조치, 트래픽 분석 및 용도 계층 보안을 점점 더 많이 도입하고 있습니다.
DDoS 보호 및 완화 시장의 주요 벤더로는 NETSCOUT(미국), Akamai(미국), Radware(이스라엘),Huawei(중국), Fortinet(미국), Thales(Imperva)(프랑스), F5(미국), Cloudflare(미국), BT(영국), A10 Networks(미국) 등이 있습니다.
본 조사에서는 DDoS 방어·완화 시장의 주요 업체에 대한 상세한 경쟁 분석, 기업 프로파일, 최근 동향 및 주요 시장 전략을 종합적으로 다루고 있습니다.
조사 범위
본 보고서에서는 DDoS 공격 대응·경감 시장을 세분화하고 있습니다. 제공 내용(솔루션 및 서비스), 솔루션 유형(네트워크 트래픽 분석기, 위협 완화 시스템, 봇넷 감지·관리 시스템, 기타 솔루션 유형), 적용 분야(네트워크 및 IP 인프라, 웹 용도 및 API, DNS 인프라), 도입 형태(On-Premise, 클라우드, 하이브리드),조직 규모(대기업 및 중소기업), 업종(은행, 금융서비스 및 보험(BFSI), 정부·국방, 의료, IT·ITeS, 통신, 제조, 에너지 및 유틸리티, 소매, 교육, 기타 업종), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카)을 기준으로 시장 규모를 예측했습니다.
또한, 본 조사에서는 시장의 주요 업체에 대한 상세한 경쟁 분석, 각 기업프로파일, 제품 및 사업 제공 내용에 관한 주요 소견, 최근 동향, 그리고 주요 시장 전략에 대해서도 다루고 있습니다.
본 보고서를 구매할 때의 주요 이점
본 보고서는 DDoS 보호 및 완화 시장 전체 및 그 하위 부문의 매출액에 대한 가장 정확한 추정치 정보를 제공함으로써, 시장을 선도하는 기업과 신규 진출기업을 지원합니다. 본 보고서는 이해관계자들이 경쟁 구도를 이해하고, 자사의 비즈니스를 더 나은 위치로 이끌며, 적절한 시장 진출 전략을 수립하는 데 필요한 귀중한 인사이트를 얻는 데 도움이 됩니다. 또한, 본 보고서는 이해관계자들이 시장 동향을 파악할 수 있도록 지원하는 동시에, 주요 시장 성장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다.
- 주요 성장 촉진요인 분석(DDoS 공격의 빈도 및 복잡성 증가, IoT 봇넷 및 DDoS-for-hire 서비스의 확산), 제약 요인(다중 벤더 환경에서의 통합 한계, 규제 및 데이터 주권 관련 제약),기회(AI 기반 및 자율형 DDoS 감지·완화 서비스 채택 확대, API, AI 용도, 클라우드 네이티브 워크로드를 위한 DDoS 방어 확대), 그리고 과제(숙련된 사이버 보안 전문가 부족, 솔루션의 비용 및 복잡성) 등, DDoS 공격 대응·완화 시장의 성장에 영향을 미치는 요인에 대해
- 제품 개발/혁신 : 시장의 향후 기술 동향, 연구개발 활동, 신제품 및 서비스 출시에 관한 상세한 인사이트
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보(본 보고서에서는 다양한 지역에 걸친 시장을 분석하고 있습니다)
- 시장 다각화 : 시장의 새로운 솔루션 및 서비스, 미개척 지역, 최근 동향 및 투자에 관한 종합적인 정보
- 경쟁사 평가 : 주요 기업인 NETSCOUT(미국), Akamai(미국), Radware(이스라엘),Huawei(중국), Fortinet(미국), Thales(Imperva)(프랑스), F5(미국), Cloudflare(미국), BT(영국), A10 Networks(미국),Corero(영국), Nexusguard(싱가포르), Link11(독일), F5(미국), NSFOCUS(중국), Fastly(미국), Huawei(중국), Lumen Technologies(미국), AIIot(이스라엘) 등, 시장 내 주요 기업
자주 묻는 질문
목차
제1장 서론
제2장 주요 요약
제3장 프리미엄 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 규제 상황
제8장 고객 현황과 구매 행동
제9장 DDoS 보호 및 완화 시장(제공 제품별)
제10장 DDoS 보호 및 완화 시장(솔루션 유형별)
제11장 DDoS 보호 및 완화 시장(응용 영역별)
제12장 DDoS 보호 및 완화 시장(도입 모드별)
제13장 DDoS 보호 및 완화 시장(조직 규모별)
제14장 DDoS 보호 및 완화 시장(업계별)
제15장 DDoS 보호 및 완화 시장(지역별)
제16장 경쟁 구도
제17장 기업 개요
제18장 조사 방법
제19장 부록
KTH 26.09.28The DDoS protection and mitigation market is expected to reach USD 13.01 billion by 2031 from USD 6.90 billion in 2026, exhibiting a CAGR of 13.5% during the forecast period. The market is gaining strategic importance as enterprises prioritize digital resilience and uninterrupted service availability. Key growth drivers include the rising frequency and sophistication of DDoS attacks, increasing exposure from cloud migration, IoT, APIs, and 5G, and the rapid expansion of digital services and online transactions.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2020-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/USD Billion) |
| Segments | Offering, Solution Type, Application Area, Deployment Mode, Organization Size, Vertical, and Region |
| Regions covered | North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America |
The emergence of AI-driven and automated attack techniques is further increasing the need for real-time detection and mitigation. Meanwhile, growing regulatory pressure, reputational risk, and demand for managed security services and cloud-based protection are accelerating enterprise investments.
"Network traffic analyzers segment to account for the largest market share in 2026"
In terms of solution type, the network traffic analyzers segment is projected to hold the largest share of the DDoS protection and mitigation market in 2026, supported by the growing requirement to continuously monitor network traffic and identify abnormal patterns associated with DDoS attacks. Network traffic analyzers provide visibility into traffic volumes, source and destination behavior, protocol activity, and sudden deviations from established traffic patterns, enabling organizations to identify potential attacks at an early stage. The increasing scale and complexity of volumetric and multi-vector DDoS attacks are encouraging enterprises, telecommunications providers, cloud service providers, and data center operators to deploy dedicated traffic analysis capabilities. These solutions can analyze large volumes of network traffic and provide alerts that support automated or coordinated mitigation. The growing adoption of hybrid and distributed network environments is also increasing the need for centralized traffic visibility across multiple infrastructure locations. Vendors are incorporating behavioral analytics, machine learning, threat intelligence, and automated detection into network traffic analysis solutions to improve identification of sophisticated attack patterns. The increasing deployment of software-based traffic analysis platforms is also supporting the adoption by enabling organizations to integrate monitoring capabilities with existing network and security infrastructure. As organizations prioritize continuous visibility and early detection to minimize service disruption, demand for network traffic analyzers is expected to remain strong, supporting the segment's leading market position.
"Web applications & APIs segment to be the fastest-growing during the forecast period"
In terms of application area, the web applications & APIs segment is expected to register the fastest growth rate from 2026 to 2031, driven by the rapid expansion of digital services, API-driven architectures, cloud-native applications, and online customer platforms. Organizations increasingly rely on websites, web applications, APIs, and application programming interfaces to deliver financial services, e-commerce, digital healthcare, government services, and enterprise applications. This growing dependence is increasing the consequences of application-layer DDoS attacks, which can exhaust application resources through large volumes of seemingly legitimate requests without necessarily generating the traffic patterns associated with traditional volumetric attacks. The growing use of APIs as the connectivity layer between applications, cloud services, mobile applications, and third-party platforms is creating additional exposure. Akamai reported a 104% increase in Layer 7 DDoS attacks over two years, highlighting the increasing threat to application environments. Vendors are responding by integrating application-aware traffic analysis, behavioral detection, bot management, API protection, rate limiting, and automated mitigation into DDoS protection platforms. The increasing adoption of microservices, containers, multi-cloud environments, and AI-enabled applications is expected to further expand the number of Internet-facing application endpoints. Consequently, organizations are increasingly prioritizing specialized protection for web applications and APIs, supporting rapid growth of this application area.
"Asia Pacific to register the highest growth rate between 2026 and 2031"
Asia Pacific is expected to be the fastest-growing in the DDoS protection and mitigation market during the forecast period, driven by rapid digitalization, expanding cloud infrastructure, increasing internet penetration, and the growth of e-commerce and digital payment ecosystems. Countries such as China, India, Japan, South Korea, Singapore, and Australia are witnessing significant investments in data centers, 5G networks, cloud services, and digital platforms, expanding the attack surface for DDoS threats. The region is also experiencing increasing cyberattacks targeting financial services, telecommunications, government, and digital businesses. Consequently, organizations are increasingly adopting cloud-based DDoS protection, automated mitigation, traffic analysis, and application-layer security to strengthen resilience and maintain uninterrupted digital services.
Breakdown of Primaries
The study draws insights from a range of industry experts, including component suppliers, Tier 1 companies, and OEMs. The breakdown of the primaries is as follows:
- By Company Type: Tier 1 - 40%, Tier 2 - 25%, and Tier 3 - 35%
- By Designation: Directors - 25%, Managers - 35%, and Others - 40%
- By Region: North America - 35%, Europe - 30%, Asia Pacific - 25%, Middle East & Africa - 5%, Latin America - 5%
Major vendors in the DDoS protection and mitigation market include NETSCOUT (US), Akamai (US), Radware (Israel), Huawei (China), Fortinet (US), Thales (Imperva) (France), F5 (US), Cloudflare (US), BT (UK), and A10 Networks (US), among others.
The study includes an in-depth competitive analysis of the key players in the DDoS protection and mitigation market, their company profiles, recent developments, and key market strategies.
Research Coverage
The report segments the DDoS protection and mitigation market. It forecasts its size based on offering (solution and service), solution type (network traffic analyzers, threat mitigation systems, botnet detection & management systems, and other solution types), application area (network & IP infrastructure, web applications & APIs, and DNS infrastructure), deployment mode (on-premises, cloud, and hybrid), organization size (large-sized enterprises and SMEs), vertical (BFSI, government & defense, healthcare, IT & ITeS, telecommunications, manufacturing, energy & utilities, retail, education, and other verticals), and region (North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America).
The study also includes an in-depth competitive analysis of the market's key players, their company profiles, key observations related to product and business offerings, recent developments, and key market strategies.
Key Benefits of Buying the Report
The report will help market leaders/new entrants with information on the closest approximations of revenue numbers for the overall DDoS protection and mitigation market and its subsegments. This report will help stakeholders understand the competitive landscape and gain valuable insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of critical drivers (Increasing frequency and complexity of DDoS attacks, Proliferation of IoT botnets and DDoS-for-hire services), restraints (Limited integration across multi-vendor environments, Regulatory and data sovereignty constraints), opportunities (Mounting adoption of AI-driven and autonomous DDoS detection and mitigation services, Expansion of DDoS protection for APIs, AI applications, and cloud-native workloads), and challenges (Lack of skilled cybersecurity professionals, Cost and complexity of solutions) influencing the DDoS protection and mitigation market growth
- Product Development/Innovation: Detailed insights on upcoming technologies, research and development activities, new products, and service launches in the market
- Market Development: Comprehensive information about lucrative markets (the report analyzes the market across varied regions)
- Market Diversification: Exhaustive information about new solutions and services, untapped geographies, recent developments, and investments in the market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players NETSCOUT (US), Akamai (US), Radware (Israel), Huawei (China), Fortinet (US), Thales (Imperva) (France), F5 (US), Cloudflare (US), BT (UK), A10 Networks (US), Corero (UK), Nexusguard (Singapore), Link11 (Germany), F5 (US), NSFOCUS (China), Fastly (US), Huawei (China), Lumen Technologies (US), and AIIot (Israel), among others, in the market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE AND SEGMENTATION
- 1.3.1 MARKET SEGMENTATION AND REGIONS COVERED
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIONS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN DDOS PROTECTION & MITIGATION MARKET
- 3.2 DDOS PROTECTION & MITIGATION MARKET, BY OFFERING
- 3.3 DDOS PROTECTION & MITIGATION MARKET, BY SOLUTION
- 3.4 DDOS PROTECTION & MITIGATION MARKET, BY SOLUTION TYPE
- 3.5 DDOS PROTECTION & MITIGATION MARKET, BY SERVICE
- 3.6 DDOS PROTECTION & MITIGATION MARKET, BY APPLICATION AREA
- 3.7 DDOS PROTECTION & MITIGATION MARKET, BY VERTICAL
- 3.8 DDOS PROTECTION & MITIGATION MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising frequency and complexity of DDoS attacks
- 4.2.1.2 Proliferation of IoT botnets and DDoS-for-hire services
- 4.2.1.3 Growing dependence on internet-facing applications, APIs, cloud services, and digital infrastructure
- 4.2.1.4 Increasing targeting of critical infrastructure through geopolitical and hacktivist-driven DDoS campaigns
- 4.2.2 RESTRAINTS
- 4.2.2.1 Limited integration across multi-vendor environments
- 4.2.2.2 Regulatory and data sovereignty constraints
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growing adoption of AI-driven and autonomous DDoS detection and mitigation
- 4.2.3.2 Expansion of DDoS protection for APIs, AI applications, and cloud-native workloads
- 4.2.3.3 Increasing demand for integrated, hybrid, and managed DDoS protection
- 4.2.4 CHALLENGES
- 4.2.4.1 Lack of skilled cybersecurity professionals
- 4.2.4.2 Cost and complexity of solutions
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 CROSS-TIER STRATEGIC PATTERNS
- 4.5.2 STRATEGIC TRENDS
- 4.5.2.1 AI-Driven and Autonomous DDoS Detection and Mitigation
- 4.5.2.2 Increasing Focus on Application, API, and DNS Protection
- 4.5.2.3 Shift Toward Cloud-Native and Hybrid DDoS Protection
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMICS INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL DDOS PROTECTION & MITIGATION INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 TRAFFIC MONITORING & ANALYSIS
- 5.3.2 DDOS PROTECTION SOLUTIONS
- 5.3.3 SYSTEM INTEGRATION & DEPLOYMENT
- 5.3.4 MANAGED SERVICES & DISTRIBUTION
- 5.3.5 END USERS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY OFFERING, 2025
- 5.5.2 INDICATIVE PRICING ANALYSIS OF DDOS PROTECTION AND MITIGATION, BY OFFERING, 2025
- 5.6 KEY CONFERENCES AND EVENTS
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 NEXUSGUARD EMPOWERED IRIX AND SAINS TO OVERCOME DDOS THREATS
- 5.9.2 XTEL COMMUNICATIONS CHOSE NETSCOUT TO IMPROVE VISIBILITY INTO NETWORK TRAFFIC
- 5.9.3 PENTELEDATA SELECTED RADWARE'S AMS FOR TECHNICAL INTEGRATION WITH KENTIK TECHNOLOGIES
- 5.9.4 CNI CHOSE CORERO TO PROTECT ITS CUSTOMERS FROM DDOS ATTACKS
- 5.10 DDOS PREVENTION TECHNIQUES
- 5.11 IMPACT OF 2025 US TARIFF - DDOS PROTECTION AND MITIGATION MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRY/REGION
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.1.1.1 Traffic filtering
- 6.1.1.2 Rate limiting
- 6.1.1.3 Web application firewall (WAF)
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Artificial intelligence (AI)
- 6.1.2.2 Machine learning (ML)
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Load balancers
- 6.1.3.2 Content delivery networks (CDNs)
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.2 TECHNOLOGY ROADMAP
- 6.2.1 SHORT-TERM (2026-2027) | FOUNDATION & CLOUD-BASED PROTECTION
- 6.2.2 MID-TERM (2027-2030) | INTELLIGENT AUTOMATION & UNIFIED DDOS PROTECTION
- 6.2.3 LONG-TERM (2030-2035+) | AUTONOMOUS, ADAPTIVE & AI-DRIVEN DDOS DEFENSE
- 6.3 PATENT ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 AUTONOMOUS AND AI-DRIVEN DDOS PROTECTION
- 6.4.2 APPLICATION-LAYER AND API-BASED DDOS PROTECTION
- 6.4.3 ADAPTIVE MULTI-LAYER AND MULTI-VECTOR DDOS MITIGATION
- 6.4.4 CLOUD, EDGE AND MULTI-CLOUD DDOS RESILIENCE
- 6.4.5 IOT AND BOTNET-BASED DDOS PROTECTION
- 6.5 IMPACT OF AI/GEN AI ON DDOS PROTECTION AND MITIGATION MARKET
- 6.5.1 BEST PRACTICES IN DDOS PROTECTION & MITIGATION MARKET
- 6.5.2 CASE STUDIES OF AI IMPLEMENTATION IN DDOS PROTECTION & MITIGATION MARKET
- 6.5.3 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN DDOS PROTECTION & MITIGATION MARKET
- 6.6 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.6.1 CLOUDFLARE: DDOS PROTECTION FOR A GLOBAL RETAILER
- 6.6.2 NETSCOUT: DDOS PROTECTION FOR A GLOBAL MANUFACTURER
7 REGULATORY LANDSCAPE
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.2.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.3 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.3.1 REVENUE POTENTIAL
- 8.3.2 COST DYNAMICS
- 8.3.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 DDOS PROTECTION AND MITIGATION MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 OFFERING: DDOS PROTECTION AND MITIGATION MARKET DRIVERS
- 9.2 SOLUTIONS
- 9.2.1 HARDWARE
- 9.2.1.1 Firewalls
- 9.2.1.1.1 Hardware firewalls filter and block malicious traffic to enable efficient server access for legitimate requests
- 9.2.1.2 Intrusion Detection and Prevention Systems (IDPS)
- 9.2.1.2.1 IDPS prevents DDoS attacks by continuously monitoring network traffic and actively blocking malicious requests
- 9.2.1.3 Load Balancers
- 9.2.1.3.1 Load balancers protect against DDoS attacks by distributing traffic across multiple servers
- 9.2.1.4 Other hardware
- 9.2.1.1 Firewalls
- 9.2.2 SOFTWARE/PLATFORMS
- 9.2.2.1 Global rise in IoT devices to drive market
- 9.2.1 HARDWARE
- 9.3 SERVICES
- 9.3.1 PROFESSIONAL SERVICES
- 9.3.1.1 Design and implementation
- 9.3.1.1.1 Increase in need to improve network performance and reliability
- 9.3.1.2 Consulting and advisory
- 9.3.1.2.1 Growing concerns for cybersecurity and adoption of advanced technologies
- 9.3.1.3 Training and education
- 9.3.1.3.1 Rising need for training and creating awareness of DDoS attacks
- 9.3.1.4 Support and maintenance
- 9.3.1.4.1 Rising need for support for technical issues and guidance
- 9.3.1.5 DDoS testing and validation
- 9.3.1.5.1 Identify vulnerabilities and evaluate the effectiveness, capacity, and responsiveness of existing DDoS mitigation mechanisms
- 9.3.1.1 Design and implementation
- 9.3.2 MANAGED SERVICES
- 9.3.2.1 Need to increase business efficiency and operations
- 9.3.1 PROFESSIONAL SERVICES
10 DDOS PROTECTION AND MITIGATION MARKET, BY SOLUTION TYPE
- 10.1 INTRODUCTION
- 10.1.1 SOLUTION TYPE: DDOS PROTECTION AND MITIGATION MARKET DRIVERS
- 10.2 NETWORK TRAFFIC ANALYZERS
- 10.2.1 NETWORK LAYER ATTACKS TO INCREASE ADOPTION OF DDOS PROTECTION SOLUTIONS
- 10.3 THREAT MITIGATION SYSTEMS
- 10.3.1 RISE IN LAYER 7 ATTACKS TO INCREASE DEMAND FOR DDOS PROTECTION AND MITIGATION SOLUTIONS
- 10.4 BOTNET DETECTION & MANAGEMENT
- 10.4.1 EVOLVING DISRUPTIVE TECHNOLOGIES AND EASY AVAILABILITY OF CLOUD-BASED APPLICATIONS TO DRIVE MARKET
- 10.5 OTHER SOLUTION TYPES
11 DDOS PROTECTION AND MITIGATION MARKET, BY APPLICATION AREA
- 11.1 INTRODUCTION
- 11.1.1 APPLICATION AREA: DDOS PROTECTION AND MITIGATION MARKET DRIVERS
- 11.2 NETWORK & IP INFRASTRUCTURE
- 11.2.1 INCREASING NEED FOR HIGH-CAPACITY, ALWAYS-ON PROTECTION CAPABLE OF ABSORBING AND FILTERING MALICIOUS TRAFFIC
- 11.3 WEB APPLICATIONS & APIS
- 11.3.1 RISING NEED TO MITIGATE DDOS ATTACKS AND MAINTAIN PROTECTION
- 11.4 DNS INFRASTRUCTURE
- 11.4.1 INCREASING DEPENDENCE ON ONLINE APPLICATIONS AND DISTRIBUTED DIGITAL INFRASTRUCTURE IS DRIVING MARKET
12 DDOS PROTECTION AND MITIGATION MARKET, BY DEPLOYMENT MODE
- 12.1 INTRODUCTION
- 12.1.1 DEPLOYMENT MODE: DDOS PROTECTION AND MITIGATION MARKET DRIVERS
- 12.2 ON-PREMISES
- 12.2.1 ON-PREMISE SERVICES PROVIDE FULL CONTROL OF DEPLOYED SOLUTIONS TO IT STAFF
- 12.3 CLOUD
- 12.3.1 CLOUD DEPLOYMENT HELPS MANAGE DNS, REROUTE TRAFFIC, AND SAFEGUARD WEBSITE TRAFFIC
- 12.4 HYBRID
- 12.4.1 ENABLE ORGANIZATIONS TO DISTRIBUTE PROTECTION ACCORDING TO THE CHARACTERISTICS AND SCALE OF THEIR INFRASTRUCTURE
13 DDOS PROTECTION AND MITIGATION MARKET, BY ORGANIZATION SIZE
- 13.1 INTRODUCTION
- 13.1.1 ORGANIZATION SIZE: DDOS PROTECTION AND MITIGATION MARKET DRIVERS
- 13.2 LARGE ENTERPRISES
- 13.2.1 INCREASING SEVERITY OF DDOS DAMAGE CAUSED BY SINGLE ATTACK TO DRIVE MARKET
- 13.3 SMALL & MEDIUM-SIZED ENTERPRISES
- 13.3.1 GROWING NEED TO MITIGATE SECURITY ATTACKS TO ENHANCE MARKET GROWTH
14 DDOS PROTECTION AND MITIGATION MARKET, BY VERTICAL
- 14.1 INTRODUCTION
- 14.1.1 VERTICAL: DDOS PROTECTION AND MITIGATION MARKET DRIVERS
- 14.2 BANKING, FINANCIAL SERVICES, AND INSURANCE (BFSI)
- 14.2.1 FRAGILE DATA CENTER SECURITY AND RISK OF CLOUD STORAGE DATA LEAKS TO DRIVE MARKET
- 14.3 GOVERNMENT & DEFENSE
- 14.3.1 INCREASING NEED FOR DDOS PROTECTION AND MITIGATION SOLUTIONS AND SERVICES TO HELP MARKET GROWTH
- 14.4 MANUFACTURING
- 14.4.1 EVOLVING VOLUMETRIC DDOS ATTACKS ON MANUFACTURING PROCESSES TO CONTRIBUTE TO MARKET GROWTH
- 14.5 ENERGY & UTILITIES
- 14.5.1 INCREASING ADOPTION OF SMART SYSTEMS AND APPLICATIONS TO DRIVE MARKET
- 14.6 IT AND ITES
- 14.6.1 RISE OF ADVANCED TECHNOLOGIES TO FUEL MARKET
- 14.7 TELECOMMUNICATIONS
- 14.7.1 RISE IN NUMBER OF WEB AND MOBILE APPLICATIONS TO FUEL MARKET
- 14.8 HEALTHCARE
- 14.8.1 REGULATORY NORMS TO INCREASE DEPLOYMENT OF DDOS PROTECTION AND MITIGATION SOLUTIONS
- 14.9 EDUCATION
- 14.9.1 NEED FOR CONFIDENTIALITY, INTEGRITY, AND EASY AVAILABILITY OF DATA AND RESOURCES TO AUGMENT MARKET GROWTH
- 14.10 RETAIL
- 14.10.1 GROWING CYBERATTACKS AND DATA THEFT TO INCREASE ADOPTION OF DDOS PROTECTION AND MITIGATION SOLUTIONS
- 14.11 OTHER VERTICALS
15 DDOS PROTECTION AND MITIGATION MARKET, BY REGION
- 15.1 INTRODUCTION
- 15.2 NORTH AMERICA
- 15.2.1 US
- 15.2.1.1 Presence of major vendors in US driving market growth
- 15.2.2 CANADA
- 15.2.2.1 Rapid technological advancements and increasing DDoS attacks on network infrastructure to drive market
- 15.2.1 US
- 15.3 EUROPE
- 15.3.1 UK
- 15.3.1.1 Increasing demand for monitoring solutions among SMEs to drive market
- 15.3.2 GERMANY
- 15.3.2.1 Increasing investments in DDoS protection and mitigation solutions to drive market
- 15.3.3 FRANCE
- 15.3.3.1 Market is driven by the growing exposure of critical sectors to cyber threats
- 15.3.4 ITALY
- 15.3.4.1 The market is driven by increasing cyber threats in critical infrastructure
- 15.3.5 REST OF EUROPE
- 15.3.1 UK
- 15.4 ASIA PACIFIC
- 15.4.1 CHINA
- 15.4.1.1 Development of cybersecurity safeguard system to fuel market
- 15.4.2 JAPAN
- 15.4.2.1 Stringent laws and regulations for cybersecurity to drive market
- 15.4.3 INDIA
- 15.4.3.1 Increasing DDoS attacks leading to adoption of DDoS protection and mitigation solutions
- 15.4.4 REST OF ASIA PACIFIC
- 15.4.1 CHINA
- 15.5 MIDDLE EAST & AFRICA
- 15.5.1 GCC
- 15.5.1.1 KSA
- 15.5.1.1.1 Increasing investments in mitigation and growth in number of startups to drive market
- 15.5.1.2 UAE
- 15.5.1.2.1 Growing reliance on cloud-based applications to boost market
- 15.5.1.3 Rest of GCC
- 15.5.1.1 KSA
- 15.5.2 SOUTH AFRICA
- 15.5.2.1 Government initiatives and substantial foreign investments to drive market
- 15.5.3 REST OF MIDDLE EAST & AFRICA
- 15.5.1 GCC
- 15.6 LATIN AMERICA
- 15.6.1 BRAZIL
- 15.6.1.1 Increasing focus on establishing effective cybersecurity strategies to drive market
- 15.6.2 MEXICO
- 15.6.2.1 Rising adoption of cloud-based services to drive market
- 15.6.3 REST OF LATIN AMERICA
- 15.6.1 BRAZIL
16 COMPETITIVE LANDSCAPE
- 16.1 INTRODUCTION
- 16.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2022-2025
- 16.3 REVENUE ANALYSIS, 2021-2025
- 16.4 MARKET SHARE ANALYSIS, 2025
- 16.5 BRAND COMPARISON
- 16.6 COMPANY VALUATION AND FINANCIAL METRICS, 2025
- 16.6.1 COMPANY VALUATION
- 16.6.2 FINANCIAL METRICS
- 16.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 16.7.1 STARS
- 16.7.2 EMERGING LEADERS
- 16.7.3 PERVASIVE PLAYERS
- 16.7.4 PARTICIPANTS
- 16.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 16.7.5.1 Company footprint
- 16.7.5.2 Regional footprint
- 16.7.5.3 Offering footprint
- 16.7.5.4 Vertical footprint
- 16.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 16.8.1 PROGRESSIVE COMPANIES
- 16.8.2 RESPONSIVE COMPANIES
- 16.8.3 DYNAMIC COMPANIES
- 16.8.4 STARTING BLOCKS
- 16.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 16.8.5.1 Detailed list of key startups/SMEs
- 16.8.5.2 Competitive benchmarking of key startups/SMEs
- 16.9 COMPETITIVE SCENARIO & TRENDS
- 16.9.1 PRODUCT LAUNCHES & ENHANCEMENTS
- 16.9.2 DEALS
- 16.9.3 EXPANSIONS
17 COMPANY PROFILES
- 17.1 KEY PLAYERS
- 17.1.1 AKAMAI
- 17.1.1.1 Business overview
- 17.1.1.2 Products/Solutions/Services offered
- 17.1.1.3 Recent developments
- 17.1.1.3.1 Product launches & enhancements
- 17.1.1.3.2 Deals
- 17.1.1.4 MnM view
- 17.1.1.4.1 Right to win
- 17.1.1.4.2 Strategic choices
- 17.1.1.4.3 Weaknesses and competitive threats
- 17.1.2 CLOUDFLARE
- 17.1.2.1 Business overview
- 17.1.2.2 Products/Solutions/Services offered
- 17.1.2.3 Recent developments
- 17.1.2.3.1 Product launches & enhancements
- 17.1.2.3.2 Deals
- 17.1.2.4 MnM view
- 17.1.2.4.1 Key strengths
- 17.1.2.4.2 Strategic choices
- 17.1.2.4.3 Weaknesses and competitive threats
- 17.1.3 RADWARE
- 17.1.3.1 Business overview
- 17.1.3.2 Products/Solutions/Services offered
- 17.1.3.3 Recent developments
- 17.1.3.3.1 Product launches & enhancements
- 17.1.3.3.2 Deals
- 17.1.3.4 MnM view
- 17.1.3.4.1 Right to win
- 17.1.3.4.2 Strategic choices
- 17.1.3.4.3 Weaknesses and competitive threats
- 17.1.4 FORTINET
- 17.1.4.1 Business overview
- 17.1.4.2 Products/Solutions/Services offered
- 17.1.4.3 Recent developments
- 17.1.4.3.1 Product launches & enhancements
- 17.1.4.4 MnM view
- 17.1.4.4.1 Key strengths
- 17.1.4.4.2 Strategic choices
- 17.1.4.4.3 Weaknesses and competitive threats
- 17.1.5 NETSCOUT
- 17.1.5.1 Business overview
- 17.1.5.2 Products/Solutions/Services offered
- 17.1.5.3 Recent developments
- 17.1.5.3.1 Product launches & enhancements
- 17.1.5.3.2 Expansions
- 17.1.5.4 MnM view
- 17.1.5.4.1 Right to win
- 17.1.5.4.2 Strategic choices
- 17.1.5.4.3 Weaknesses and competitive threats
- 17.1.6 NEXUSGUARD
- 17.1.6.1 Business overview
- 17.1.6.2 Products/Solutions/Services offered
- 17.1.6.3 Recent developments
- 17.1.6.3.1 Product launches & enhancements
- 17.1.6.3.2 Deals
- 17.1.7 HUAWEI
- 17.1.7.1 Business overview
- 17.1.7.2 Products/Solutions/Services offered
- 17.1.7.3 Recent developments
- 17.1.7.3.1 Product launches & enhancements
- 17.1.8 LINK11
- 17.1.8.1 Business overview
- 17.1.8.2 Products/Solutions/Services offered
- 17.1.8.3 Recent developments
- 17.1.8.3.1 Product launches & enhancements
- 17.1.8.3.2 Deals
- 17.1.9 THALES (IMPERVA)
- 17.1.9.1 Business overview
- 17.1.9.2 Products/Solutions/Services offered
- 17.1.9.3 Recent developments
- 17.1.9.3.1 Product launches & enhancements
- 17.1.10 BT
- 17.1.10.1 Business overview
- 17.1.10.2 Products/Solutions/Services offered
- 17.1.11 A10 NETWORKS
- 17.1.11.1 Business overview
- 17.1.11.2 Products/Solutions/Services offered
- 17.1.11.3 Recent developments
- 17.1.11.3.1 Product launches & enhancements
- 17.1.11.3.2 Deals
- 17.1.12 NSFOCUS
- 17.1.12.1 Business overview
- 17.1.12.2 Products/Solutions/Services offered
- 17.1.13 MICROSOFT
- 17.1.13.1 Business overview
- 17.1.13.2 Products/Solutions/Services offered
- 17.1.13.3 Recent developments
- 17.1.13.3.1 Product launches & enhancements
- 17.1.14 F5
- 17.1.14.1 Business overview
- 17.1.14.2 Products/Solutions/Services offered
- 17.1.14.3 Recent developments
- 17.1.14.3.1 Product launches & enhancements
- 17.1.14.3.2 Deals
- 17.1.15 ALIBABA CLOUD
- 17.1.15.1 Business overview
- 17.1.15.2 Products/Solutions/Services offered
- 17.1.15.3 Recent developments
- 17.1.15.3.1 Product launches & enhancements
- 17.1.16 CORERO
- 17.1.16.1 Business Overview
- 17.1.16.2 Products/Solutions/Services offered
- 17.1.16.3 Recent developments
- 17.1.16.3.1 Product launches & enhancements
- 17.1.16.3.2 Deals
- 17.1.17 AWS
- 17.1.17.1 Business Overview
- 17.1.17.2 Products/Solutions/Services offered
- 17.1.17.3 Recent developments
- 17.1.17.3.1 Product launches & enhancements
- 17.1.1 AKAMAI
- 17.2 OTHER KEY PLAYERS
- 17.2.1 FASTLY
- 17.2.2 ALLOT
- 17.2.3 STRATACORE
- 17.2.4 SUCURI (GODADDY)
- 17.2.5 LUMEN TECHNOLOGIES
- 17.2.6 SECEON
- 17.2.7 HALTDOS
- 17.2.8 DDOS-GUARD
- 17.2.9 INDUSFACE
- 17.2.10 MLYTICS
- 17.2.11 RIOREY
- 17.2.12 PHOENIXNAP
- 17.2.13 XCITIUM
- 17.2.14 MAZEBOLT
- 17.2.15 QRATOR LABS
- 17.2.16 GCORE
18 RESEARCH METHODOLOGY
- 18.1 RESEARCH DATA
- 18.1.1 SECONDARY DATA
- 18.1.2 PRIMARY DATA
- 18.1.2.1 Breakup of primary profiles
- 18.1.2.2 Key industry insights
- 18.2 DATA TRIANGULATION
- 18.3 MARKET SIZE ESTIMATION
- 18.3.1 TOP-DOWN APPROACH
- 18.3.2 BOTTOM-UP APPROACH
- 18.4 MARKET FORECAST
- 18.5 RESEARCH ASSUMPTIONS
- 18.6 RESEARCH LIMITATIONS
19 APPENDIX
- 19.1 DISCUSSION GUIDE
- 19.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.3 CUSTOMIZATION OPTIONS
- 19.4 RELATED REPORTS
- 19.5 AUTHOR DETAILS


