
|
시장보고서
상품코드
2130446
수의용 모니터링 장비 시장(-2031년) : 유형(마취기·카프노그래피시스템·ECG&홀터 모니터링·텔레메트리·바이탈 사인 모니터), 기술(무선 환자 모니터·유선 모니터링 시스템), 최종 사용자별Veterinary Monitoring Equipment Market by Type (Anesthesia Machine, Capnography System, ECG & Holter Monitoring, Telemetry, Vital Signs Monitor), Technology (Wireless Patient Monitor, Wired Monitoring System), End User - Global Forecast to 2031 |
||||||

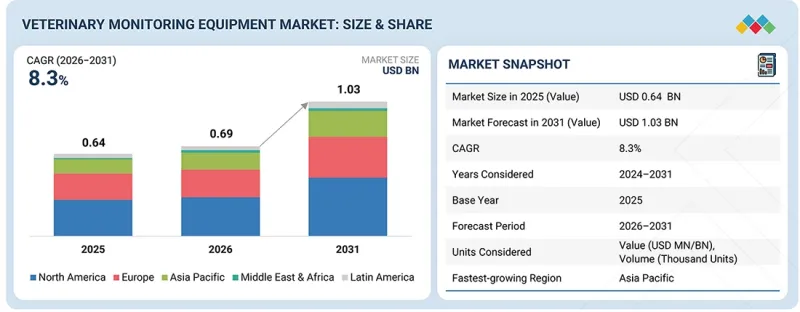
세계의 수의용 모니터링 장비 시장 규모는 2026년 6억 9,000만 달러에서 2031년까지 10억 3,000만 달러에 이를 것으로 예상되며, 예측 기간 동안 CAGR 8.30%로 성장할 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러) |
| 부문 | 유형, 대상 영역, 대상 동물, 기술, 최종 사용자, 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
시장 성장은 반려동물 사육 마릿수 증가와 반려동물의 ‘인간화’, 고령의 개와 고양이에서 심장 질환 및 신장 질환 등 만성 질환과 노화에 따른 질환의 발생률 상승, 지속적인 생체 신호 모니터링이 필요한 외과 수술 건수 증가에 의해 주도되고 있습니다. 고급 다중 매개변수 시스템의 높은 도입 비용은 여전히 장벽으로 작용하여, 소규모 독립 동물 병원의 도입을 저해하고 있습니다.
“기술별로는 웨어러블 모니터링 부문이 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다.”
웨어러블 및 비접촉식 센서를 통해 동물을 구속하지 않고도 심박수, 호흡수, 체온을 추적할 수 있으므로, 접촉을 싫어하는 환자의 스트레스를 줄일 수 있을 뿐만 아니라 회복 케이지, 쉼터, 이동 진료 시에도 모니터링이 가능해집니다. 또한 센서의 소형화와 배터리 수명 연장으로 인해 웨어러블 기기는 수술실뿐만 아니라 일상적인 증례 관리 현장으로도 그 활용 범위가 확대되고 있습니다.
“최종 사용자별로는 일반 동물 진료 부문이 예측 기간 동안 가장 큰 점유율을 차지할 전망”
일반 동물병원에서는 정기적인 건강검진, 치과 시술, 경미한 외과 수술을 주로 다루고 있으며, 어느 경우든 진정 또는 마취 중에 최소한 기본적인 생체 신호 모니터링이 필요합니다. 일반 동물병원은 전 세계적으로 수가 많을 뿐만 아니라 계속 증가하고 있어, 기기 도입 대수 면에서는 전문 진료 시설이나 응급 시설을 웃돌고 있습니다.
예측 기간 동안 북미가 가장 큰 점유율을 차지할 것으로 예상되는 반면, 아시아태평양은 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다.
북미는 반려동물 사육 마리 수가 많고, 확립된 전문 진료 및 의뢰 병원 네트워크가 있으며, 모니터링 장비가 동물병원에 도입되기 전에 공식적인 시판 전 승인이 필요하지 않은 수의학 기기 규제 환경 덕분에 2026년에도 시장의 대부분을 차지했습니다. 반면, 아시아태평양은 반려동물 사육 마릿수 증가와 병원 인프라 확장을 배경으로 중국, 인도, 일본이 주도적인 역할을 하며, 2026년부터 2031년에 걸쳐 다른 어떤 지역보다 높은 연평균 성장률(CAGR)로 성장할 것으로 예상되며, 예측됩니다.
본 보고서에서는 세계의 수의용 모니터링 장비 시장을 조사했으며, 시장 개요, 시장 성장에 영향을 미치는 각종 요인 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 예측, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 프로파일 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 서론
제2장 주요 요약
제3장 프리미엄 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI의 영향, 특허, 혁신, 향후 용도
제7장 규제 상황과 지속가능성 이니셔티브
제8장 고객 현황과 구매 행동
제9장 수의용 모니터링 장비 시장 : 유형별
제10장 수의용 모니터링 장비 시장 : 대상 지역별
제11장 수의용 모니터링 장비 시장 : 동물 유형별
제12장 수의용 모니터링 장비 시장 : 기술별
제13장 수의용 모니터링 장비 시장 : 최종 사용자별
제14장 수의용 모니터링 장비 시장 : 지역별
제15장 경쟁 구도
제16장 기업 개요
제17장 조사 방법
제18장 부록
KTH 26.09.28The global veterinary monitoring equipment market is projected to reach USD 1.03 billion by 2031 from USD 0.69 billion in 2026, growing at a CAGR of 8.30% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Type, Target Area, Animal type, Technology, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
Growth is driven by rising pet ownership and pet humanization, a rising incidence of chronic and age-related conditions such as cardiac and renal disease in aging dogs and cats, and increasing surgical case volumes that require continuous vital sign monitoring. The high capital cost of advanced multiparameter systems remains a barrier, limiting adoption among small and independent veterinary practices.
"Wearable monitoring technology segment is projected to register the highest CAGR in the veterinary monitoring equipment market during the forecast period."
By technology, the wearable monitoring segment is set to grow fastest between 2026 and 2031. Wearable and contactless sensors allow clinics to track heart rate, respiration and temperature without restraining the animal, reducing stress for patients that resist handling and extending monitoring into recovery cages, shelters and mobile practices. Smaller sensors and longer battery life are moving wearable formats beyond the surgical suite into everyday case management.
"Veterinary general practice segment is expected to account for the largest share of the veterinary monitoring equipment market during the forecast period."
By end user, veterinary general practice held the largest share of the market in 2025. General practices handle most routine wellness exams, dental work, and minor surgical procedures, and each case requires at least basic vital sign monitoring during sedation or anesthesia. The large and still-growing number of general practice clinics worldwide keeps this segment ahead of specialty and emergency facilities in equipment volume.
North America is expected to account for the largest share of the veterinary monitoring equipment market, while Asia Pacific is projected to register the highest CAGR during the forecast period.
North America held a major share of the market in 2026, supported by a large companion animal population, an established specialty and referral hospital network, and a veterinary device pathway that does not require formal premarket approval before a monitor reaches clinics. Asia Pacific is projected to grow at the highest CAGR from 2026 to 2031, the fastest of any region, led by China, India, and Japan as pet ownership rises and hospital infrastructure expands.
A breakdown of the primary participants referred to for this report is provided below:
- By Company Type: Tier 1-40%, Tier 2-35%, and Tier 3- 25%
- By Designation: Directors-23%, Managers-30%, and Others-47%
- By Region: North America-25%, Europe-35%, the Asia Pacific-20%, Latin America-13%, and the Middle East & Africa- 7%
Midmark Corporation (US); Shenzhen Mindray Bio-Medical Electronics (China); Covetrus (US); SunTech Medical (US); Nonin Medical (US); EDAN Instruments (China); Bionet (South Korea); Guangdong Biolight Meditech (China); Burtons Medical Equipment (UK); Eickemeyer Veterinary Equipment (UK); Masimo (US); ICU Medical (US); and Medtronic (Ireland) are some of the key players in the veterinary monitoring equipment market.
Research Coverage
This report studies the veterinary monitoring equipment market by type, target area, animal type, technology, end user, and region. It also covers the factors affecting market growth, analyzes the opportunities and challenges in the market, and provides details of the competitive landscape for market leaders. Furthermore, the report analyzes micromarkets with respect to their individual growth trends and forecasts the revenue of the market segments with respect to five main regions (and the respective countries in these regions).
Reasons to Buy the Report
The report will enable established firms as well as entrants and smaller firms to gauge the pulse of the market, which, in turn, would help them to garner a larger market share. Firms purchasing the report could use one or more of the strategies mentioned below to strengthen their market presence.
This report provides insights into the following pointers:
- Analysis of Key Drivers: Understand the drivers (pet humanization, chronic disease incidence, rising surgical volumes), restraints (high capital cost limiting adoption among small practices), opportunities (expanding veterinary infrastructure in emerging economies, technological advancements in monitoring equipment), and challenges (veterinary workforce shortage and limited technical expertise) shaping this market
- Market Development: Gain insight into the fastest-growing regions and segments, including Asia Pacific and wearable monitoring technology, to prioritize expansion plans
- Market Diversification: Explore new product types, target areas, and end user segments that present untapped revenue opportunities
- Competitive Assessment: Review the strategies of leading players including Midmark Corporation, Shenzhen Mindray Bio-Medical Electronics, Covetrus, SunTech Medical, and Masimo to benchmark competitive positioning
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.4 INCLUSIONS AND EXCLUSIONS
- 1.4.1 YEARS CONSIDERED
- 1.4.2 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 LIMITATIONS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN VETERINARY MONITORING EQUIPMENT MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 VETERINARY MONITORING EQUIPMENT MARKET OVERVIEW
- 3.2 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER AND COUNTRY
- 3.3 VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing pet ownership and pet humanization
- 4.2.1.2 Increasing incidence of chronic diseases and age-related conditions
- 4.2.1.3 Increasing veterinary surgical procedures
- 4.2.2 RESTRAINTS
- 4.2.2.1 High capital cost of advanced monitoring systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expanding veterinary infrastructure and rising animal healthcare expenditure in emerging economies
- 4.2.3.2 Technological advancements in veterinary monitoring equipment
- 4.2.4 CHALLENGES
- 4.2.4.1 Veterinary workforce shortage and limited technical expertise in emerging economies
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN VETERINARY MONITORING EQUIPMENT MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 STRATEGIC MOVES IN VETERINARY MONITORING EQUIPMENT MARKET
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL VETERINARY HEALTHCARE INDUSTRY
- 5.2.4 TRENDS IN GLOBAL MEDICAL DEVICE INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 MANUFACTURERS
- 5.5.2 END USERS
- 5.5.3 REGULATORY BODIES
- 5.6 PRICING ANALYSIS
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT DATA (HS CODE 9018)
- 5.7.2 EXPORT DATA FOR (HS CODE 9018)
- 5.8 REIMBURSEMENT SCENARIO
- 5.9 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.10 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.11 INVESTMENT AND FUNDING SCENARIO
- 5.12 CASE STUDY ANALYSIS
- 5.13 IMPACT OF 2025 US TARIFF - VETERINARY MONITORING EQUIPMENT MARKET
- 5.13.1 INTRODUCTION
- 5.13.2 KEY TARIFF RATES
- 5.13.3 PRICE IMPACT ANALYSIS
- 5.13.4 IMPACT ON COUNTRIES/REGIONS
- 5.13.5 IMPACT ON END-USE SEGMENTS
- 5.13.5.1 Veterinary general practice
- 5.13.5.2 ER/urgent care
- 5.13.5.3 Veterinary specialty
- 5.13.5.4 Other end users
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.1.1.1 AI-enabled remote patient monitoring and wearable veterinary devices
- 6.1.1.2 Non-contact remote vital sign monitoring
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Connected telemetry and central monitoring platforms
- 6.1.2.2 Advanced capnography and multiparameter anesthesia monitoring
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Veterinary telemedicine and digital health platforms
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 NEAR-TERM (2025-2027)
- 6.2.2 MID-TERM (2028-2030)
- 6.2.3 LONG-TERM (2030+)
- 6.3 PATENT ANALYSIS
- 6.3.1 JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 AI-ASSISTED CLINICAL DECISION SUPPORT
- 6.4.2 REMOTE & CONTINUOUS ANIMAL MONITORING
- 6.4.3 CONNECTED & PERSONALIZED VETERINARY CARE
- 6.5 IMPACT OF AI/GEN AI ON VETERINARY MONITORING EQUIPMENT
- 6.5.1 INTRODUCTION
- 6.5.2 MARKET POTENTIAL OF AI IN VETERINARY MONITORING EQUIPMENT
- 6.5.3 AI USE CASES
- 6.5.4 KEY COMPANIES IMPLEMENTING AI
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATORY FRAMEWORK
- 7.1.1.1 North America
- 7.1.1.2 Europe
- 7.1.1.3 Asia Pacific
- 7.1.1.4 Latin America
- 7.1.1.5 Middle East & Africa
- 7.1.2 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.3 INDUSTRY STANDARDS
- 7.1.1 REGULATORY FRAMEWORK
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 REDUCING MEDICAL WASTE & USE OF LOWER-IMPACT MATERIALS AND PACKAGING
- 7.2.2 WATER, ENERGY, & RESOURCE EFFICIENCY
- 7.2.3 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
9 VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 MULTI-PARAMETER VETERINARY MONITORS
- 9.2.1 VOLUME ANALYSIS OF MULTI-PARAMETER VETERINARY MONITORS, 2024-2031
- 9.2.2 PORTABLE MULTI-PARAMETER MONITORS
- 9.2.2.1 Portability and cross-department deployment to support adoption
- 9.2.3 TABLETOP MULTI-PARAMETER MONITORS
- 9.2.3.1 Large displays and fixed workflow integration to sustain demand
- 9.2.4 MODULAR MULTI-PARAMETER MONITORS
- 9.2.4.1 Expandable parameter capability to increase use in referral and critical-care settings
- 9.2.5 OTHER MULTI-PARAMETER VETERINARY MONITORS
- 9.3 CAPNOGRAPHY & OXIMETRY SYSTEMS
- 9.3.1 VOLUME ANALYSIS OF CAPNOGRAPHY & OXIMETRY SYSTEMS, 2024-2031
- 9.3.2 CAPNOGRAPHY SYSTEMS
- 9.3.2.1 Greater emphasis on ventilation monitoring to accelerate capnography adoption
- 9.3.3 PULSE OXIMETRY SYSTEMS
- 9.3.3.1 Non-invasive oxygenation assessment and portable formats to sustain use
- 9.4 ANESTHESIA MACHINES & CONSUMABLES
- 9.4.1 VOLUME ANALYSIS OF ANESTHESIA MACHINES & CONSUMABLES, 2024-2031
- 9.4.2 ANESTHESIA MACHINES
- 9.4.2.1 Anesthesia machines without integrated ventilators
- 9.4.2.1.1 Lower capital requirements and established general-practice workflows to support demand
- 9.4.2.2 Advanced anesthesia machines with integrated ventilators
- 9.4.2.2.1 Integrated ventilation and connected safety functions to accelerate premium adoption
- 9.4.2.1 Anesthesia machines without integrated ventilators
- 9.4.3 ANESTHESIA CONSUMABLES
- 9.4.3.1 Sodasorb
- 9.4.3.1.1 Recurring replacement and carbon-dioxide absorption requirements to sustain demand
- 9.4.3.2 Vaporizers
- 9.4.3.2.1 Growing need for accurate anesthetic delivery and equipment replacement to maintain market growth
- 9.4.3.3 Scavengers
- 9.4.3.3.1 Increasing focus on workplace safety and operating room upgrades to drive adoption
- 9.4.3.1 Sodasorb
- 9.5 ECG & HOLTER MONITORING SYSTEMS
- 9.5.1 VOLUME ANALYSIS OF ECG & HOLTER MONITORING SYSTEMS, 2024-2031
- 9.5.2 RESTING ECG SYSTEMS
- 9.5.2.1 Increasing demand for rapid cardiac screening and diagnostic assessment to expand adoption
- 9.5.3 CONTINUOUS ECG SYSTEMS
- 9.5.3.1 Growing need for continuous cardiac surveillance in critical care to drive market growth
- 9.5.4 HOLTER ECG SYSTEMS
- 9.5.4.1 Increasing demand for long-term rhythm monitoring to improve market adoption
- 9.6 TELEMETRY & CENTRAL MONITORING SYSTEMS
- 9.6.1 VOLUME ANALYSIS OF TELEMETRY & CENTRAL MONITORING SYSTEMS, 2024-2031
- 9.6.2 CENTRAL MONITORING SYSTEMS
- 9.6.2.1 Growing need for multi-patient surveillance and workflow efficiency to support adoption
- 9.6.3 WIRELESS TELEMETRY SYSTEMS
- 9.6.3.1 Increasing demand for mobility-enabled inpatient monitoring to drive market growth
- 9.6.4 REMOTE PATIENT MONITORING SYSTEMS
- 9.6.4.1 Home-based data capture and chronic-care follow-up to accelerate market development
- 9.7 OTHER VETERINARY MONITORING EQUIPMENT
- 9.7.1 VOLUME ANALYSIS OF OTHER VETERINARY MONITORING EQUIPMENT, 2024-2031
10 VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA
- 10.1 INTRODUCTION
- 10.2 CARDIOLOGY
- 10.2.1 ECG MONITORING
- 10.2.1.1 Increasing adoption of cardiac screening and remote interpretation capabilities to support market growth
- 10.2.2 BLOOD PRESSURE MONITORING
- 10.2.2.1 Increasing demand for accurate cardiovascular assessment and veterinary-specific monitoring solutions to drive market growth
- 10.2.3 CARDIAC RHYTHM MONITORING
- 10.2.3.1 Increasing need for continuous cardiac surveillance and advanced arrhythmia detection to support market growth
- 10.2.4 HOLTER MONITORING
- 10.2.4.1 Increasing adoption of wearable cardiac monitoring and AI-assisted rhythm analysis to support market growth
- 10.2.1 ECG MONITORING
- 10.3 NEUROLOGY
- 10.3.1 EEG MONITORING
- 10.3.1.1 Increasing demand for objective neurological assessment and AI-enabled monitoring to support market growth
- 10.3.2 NEUROMUSCULAR MONITORING
- 10.3.2.1 Increasing focus on anesthesia safety and objective recovery assessment to support market growth
- 10.3.3 INTRACRANIAL PRESSURE MONITORING
- 10.3.3.1 Increasing demand for advanced neurological assessment and non-invasive monitoring approaches to support market growth
- 10.3.1 EEG MONITORING
- 10.4 RESPIRATORY DISORDERS
- 10.5 WEIGHT & TEMPERATURE MONITORING
- 10.5.1 BODY WEIGHT MONITORING
- 10.5.1.1 Increasing demand for accurate dosing and longitudinal health tracking to sustain market growth
- 10.5.2 BODY TEMPERATURE MONITORING
- 10.5.2.1 Increasing emphasis on perioperative safety and continuous physiological monitoring to support market growth
- 10.5.3 CONTINUOUS TEMPERATURE MONITORING
- 10.5.3.1 Increasing adoption of continuous trend monitoring and connected devices to expand market growth
- 10.5.4 WEARABLE WEIGHT & TEMPERATURE MONITORING
- 10.5.4.1 Increasing adoption of connected health monitoring and wearable technologies to support market growth
- 10.5.1 BODY WEIGHT MONITORING
- 10.6 MULTI-PARAMETER MONITORING
- 10.6.1 SURGICAL MONITORING
- 10.6.1.1 Increasing focus on anesthesia safety and integrated surgical monitoring to sustain market growth
- 10.6.2 CRITICAL CARE MONITORING
- 10.6.2.1 Increasing demand for advanced ICU monitoring and centralized patient surveillance to support market growth
- 10.6.3 EMERGENCY MONITORING
- 10.6.3.1 Increasing demand for rapid response monitoring and portable emergency-care solutions to drive market growth
- 10.6.4 RECOVERY MONITORING
- 10.6.4.1 Increasing focus on post-anesthetic safety and continuous recovery monitoring to support market growth
- 10.6.1 SURGICAL MONITORING
- 10.7 OTHER TARGET AREAS
11 VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE
- 11.1 INTRODUCTION
- 11.2 COMPANION ANIMALS
- 11.2.1 DOGS
- 11.2.1.1 Large dog population and expanding advanced-care applications to support market growth
- 11.2.2 CATS
- 11.2.2.1 Increasing feline ownership and specialized monitoring requirements to support market growth
- 11.2.3 HORSES
- 11.2.3.1 High-value equine procedures and specialized monitoring requirements to support market growth
- 11.2.4 OTHER COMPANION ANIMALS
- 11.2.1 DOGS
- 11.3 LIVESTOCK
- 11.3.1 CATTLE
- 11.3.1.1 Large cattle population and AI-enabled herd monitoring solutions to support market growth
- 11.3.2 PIGS
- 11.3.2.1 Increasing focus on herd health surveillance and automated disease detection to support market growth
- 11.3.3 POULTRY
- 11.3.3.1 Increasing adoption of automated flock monitoring and precision-production technologies to support market growth
- 11.3.4 OTHER LIVESTOCK ANIMALS
- 11.3.1 CATTLE
12 VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY
- 12.1 INTRODUCTION
- 12.2 WIRED MONITORING SYSTEMS
- 12.2.1 STABLE CONNECTIVITY AND ESTABLISHED CLINICAL WORKFLOWS TO SUSTAIN WIRED MONITORING ADOPTION
- 12.3 WIRELESS MONITORING SYSTEMS
- 12.3.1 INCREASING NEED FOR MOBILITY AND CONNECTED PATIENT SURVEILLANCE TO DRIVE WIRELESS MONITORING DEMAND
- 12.4 REMOTE PATIENT MONITORING
- 12.4.1 INCREASING ADOPTION OF CONNECTED HEALTH PLATFORMS AND LONGITUDINAL MONITORING TO SUPPORT MARKET GROWTH
- 12.5 WEARABLE MONITORING TECHNOLOGY
- 12.5.1 INCREASING ADOPTION OF CONTINUOUS BIOSENSING AND LESS RESTRICTIVE MONITORING SOLUTIONS TO SUPPORT MARKET GROWTH
- 12.6 POINT-OF-CARE MONITORING
- 12.6.1 INCREASING DEMAND FOR RAPID ASSESSMENT AND PORTABLE MONITORING SOLUTIONS TO SUPPORT MARKET GROWTH
13 VETERINARY MONITORING EQUIPMENT MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 VETERINARY GENERAL PRACTICE
- 13.2.1 INCREASING PRACTICE MODERNIZATION AND ROUTINE CARE VOLUMES TO SUPPORT MARKET GROWTH
- 13.3 ER/URGENT CARE
- 13.3.1 INCREASING DEMAND FOR EMERGENCY RESPONSE CAPABILITIES AND CONTINUOUS CRITICAL MONITORING TO SUPPORT MARKET GROWTH
- 13.4 SPECIALTY CENTERS
- 13.4.1 INCREASING SPECIALTY-CARE DEMAND AND ADVANCED MONITORING ADOPTION TO SUPPORT MARKET GROWTH
- 13.5 OTHER END USERS
14 VETERINARY MONITORING EQUIPMENT MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 14.2.2 NORTH AMERICA: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.2.3 US
- 14.2.3.1 Large pet-owning base and advanced specialty infrastructure to sustain market leadership
- 14.2.4 CANADA
- 14.2.4.1 High pet ownership and need for accessible veterinary care to support adoption
- 14.3 EUROPE
- 14.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 14.3.2 EUROPE: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.3.3 GERMANY
- 14.3.3.1 Large veterinary workforce and dual companion-animal and livestock demand to support market leadership
- 14.3.4 UK
- 14.3.4.1 Corporate practice expansion and strong referral networks to support market growth
- 14.3.5 FRANCE
- 14.3.5.1 Extensive veterinary network and specialty care development to drive market
- 14.3.6 ITALY
- 14.3.6.1 Expanding companion-animal care and livestock monitoring applications to support market growth
- 14.3.7 SPAIN
- 14.3.7.1 Strong livestock production and growing urban pet care to support market expansion
- 14.3.8 NORWAY
- 14.3.8.1 High companion-animal ownership and strong animal healthcare standards to support market growth
- 14.3.9 DENMARK
- 14.3.9.1 Strong livestock base and advanced veterinary standards to support market growth
- 14.3.10 REST OF EUROPE
- 14.4 ASIA PACIFIC
- 14.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 14.4.2 ASIA PACIFIC: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.4.3 CHINA
- 14.4.3.1 Domestic manufacturing, urban pet care, and livestock modernization to drive market
- 14.4.4 JAPAN
- 14.4.4.1 Aging pet population and high clinical standards to support market growth
- 14.4.5 INDIA
- 14.4.5.1 Expanding animal-health infrastructure and need for portable equipment to support market growth
- 14.4.6 AUSTRALIA
- 14.4.6.1 High pet ownership and demand for connected veterinary care to support market growth
- 14.4.7 SOUTH KOREA
- 14.4.7.1 Rising pet ownership and digital adoption to support market growth
- 14.4.8 REST OF ASIA PACIFIC
- 14.5 LATIN AMERICA
- 14.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 14.5.2 LATIN AMERICA: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.5.3 BRAZIL
- 14.5.3.1 Large livestock base and expanding urban pet care to support market leadership
- 14.5.4 MEXICO
- 14.5.4.1 Veterinary-access expansion and livestock biosecurity to support market growth
- 14.5.5 REST OF LATIN AMERICA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 14.6.2 MIDDLE EAST & AFRICA: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.6.3 GCC COUNTRIES
- 14.6.3.1 Kingdom of Saudi Arabia
- 14.6.3.1.1 Food security investment and specialized animal care to support market growth
- 14.6.3.2 United Arab Emirates
- 14.6.3.2.1 Advanced veterinary infrastructure and premium animal care to drive market
- 14.6.3.3 Rest of GCC countries
- 14.6.3.1 Kingdom of Saudi Arabia
- 14.6.4 REST OF MIDDLE EAST & AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2023-2026
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY MARKET PLAYERS
- 15.3 REVENUE ANALYSIS, 2023-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.4.1 GLOBAL: VETERINARY MONITORING EQUIPMENT MARKET SHARE ANALYSIS, 2025
- 15.4.1.1 US: Veterinary monitoring equipment market share analysis, 2025
- 15.4.1.2 Europe: Veterinary monitoring equipment market share analysis, 2025
- 15.4.1 GLOBAL: VETERINARY MONITORING EQUIPMENT MARKET SHARE ANALYSIS, 2025
- 15.5 BRAND/PRODUCT COMPARISON
- 15.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.6.1 STARS
- 15.6.2 EMERGING LEADERS
- 15.6.3 PERVASIVE PLAYERS
- 15.6.4 PARTICIPANTS
- 15.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.6.5.1 Company footprint
- 15.6.5.2 Region footprint
- 15.6.5.3 Type footprint
- 15.6.5.4 Target area footprint
- 15.6.5.5 Animal type footprint
- 15.6.5.6 Technology footprint
- 15.6.5.7 End user footprint
- 15.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.7.1 PROGRESSIVE COMPANIES
- 15.7.2 RESPONSIVE COMPANIES
- 15.7.3 DYNAMIC COMPANIES
- 15.7.4 STARTING BLOCKS
- 15.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.7.5.1 Detailed list of key startups/SMEs
- 15.7.5.2 Competitive benchmarking of key startups/SMEs
- 15.8 COMPANY VALUATION AND FINANCIAL METRICS
- 15.8.1 FINANCIAL METRICS
- 15.8.2 COMPANY VALUATION
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
- 15.9.4 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 MIDMARK CORPORATION
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Solutions/Services offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses & competitive threats
- 16.1.2 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Solutions/Services offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches
- 16.1.2.3.2 Expansions
- 16.1.2.4 MnM view
- 16.1.2.4.1 Key Strengths
- 16.1.2.4.2 Strategic Choices
- 16.1.2.4.3 Weaknesses & Competitive Threats
- 16.1.3 COVETRUS, INC.
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Solutions/Services offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Deals
- 16.1.3.3.2 Expansions
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key Strengths
- 16.1.3.4.2 Strategic Choices
- 16.1.3.4.3 Weaknesses & Competitive Threats
- 16.1.4 SUNTECH MEDICAL, INC.
- 16.1.4.1 Business overview
- 16.1.4.2 Products/Solutions/Services offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Product launches
- 16.1.4.3.2 Expansions
- 16.1.4.4 MnM view
- 16.1.4.4.1 Key Strengths
- 16.1.4.4.2 Strategic Choices
- 16.1.4.4.3 Weaknesses & Competitive Threats
- 16.1.5 LEADING EDGE VETERINARY EQUIPMENT
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Solutions/Services offered
- 16.1.5.3 MnM view
- 16.1.5.3.1 Key Strengths
- 16.1.5.3.2 Strategic Choices
- 16.1.5.3.3 Weaknesses & Competitive Threats
- 16.1.6 EICKEMEYER VETERINARY EQUIPMENT LTD.
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Solutions/Services offered
- 16.1.7 NONIN MEDICAL, INC.
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Solutions/Services offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.8 DIGICARE BIOMEDICAL
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Solutions/Services offered
- 16.1.9 BIONET CO., LTD.
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Solutions/Services offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Other developments
- 16.1.10 EDAN INSTRUMENTS, INC.
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Solutions/Services offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Expansions
- 16.1.11 SHENZHEN COMEN MEDICAL INSTRUMENTS CO., LTD.
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Solutions/Services offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Expansions
- 16.1.12 GUANGDONG BIOLIGHT MEDITECH CO., LTD.
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Solutions/Services offered
- 16.1.13 VETLAND MEDICAL SALES & SERVICES, LLC
- 16.1.13.1 Business overview
- 16.1.13.2 Products/Solutions/Services offered
- 16.1.14 BURTONS MEDICAL EQUIPMENT LTD.
- 16.1.14.1 Business overview
- 16.1.14.2 Products/Solutions/Services offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Deals
- 16.1.15 AVANTE ANIMAL HEALTH
- 16.1.15.1 Business overview
- 16.1.15.2 Products/Solutions/Services offered
- 16.1.1 MIDMARK CORPORATION
- 16.2 OTHER PLAYERS
- 16.2.1 SINO-HERO
- 16.2.2 DISPOMED LTD.
- 16.2.3 BMV ANIMAL TECHNOLOGY CO., LTD.
- 16.2.4 SHENZHEN MED-LINK ELECTRONICS TECH CO., LTD.
- 16.2.5 VETSPECS, INC.
- 16.2.6 CONTEC MEDICAL SYSTEMS CO., LTD.
- 16.2.7 INFINIUM MEDICAL, INC.
- 16.2.8 DEXTRONIX, INC.
- 16.2.9 MASIMO CORPORATION
- 16.2.10 MEDTRONIC
- 16.2.11 ICU MEDICAL, INC.
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Primary sources
- 17.1.2.2 Key data from primary sources
- 17.1.2.3 Key industry insights
- 17.1.2.4 Breakdown of primaries
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 APPROACH 1: COMPANY REVENUE ANALYSIS APPROACH
- 17.2.2 APPROACH 2: CUSTOMER-BASED MARKET ESTIMATION
- 17.2.3 APPROACH 3: TOP-DOWN APPROACH
- 17.2.4 APPROACH 4: BOTTOM-UP APPROACH
- 17.2.5 APPROACH 4: PRIMARY INTERVIEWS
- 17.2.6 APPROACH 5: DEMAND-SIDE APPROACH
- 17.2.7 APPROACH 6: VOLUME DATA ANALYSIS
- 17.3 DATA TRIANGULATION AND MARKET BREAKDOWN
- 17.4 MARKET SHARE ASSESSMENT
- 17.5 RESEARCH ASSUMPTIONS
- 17.5.1 RESEARCH ASSUMPTIONS
- 17.5.2 GROWTH RATE ASSUMPTIONS
- 17.6 RISK ASSESSMENT
- 17.7 RESEARCH LIMITATIONS
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.3.1 PRODUCT ANALYSIS
- 18.3.2 COMPANY INFORMATION
- 18.3.3 GEOGRAPHIC ANALYSIS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS


