
|
시장보고서
상품코드
2130451
살선충제 시장 : 유형별, 선충 유형별, 시용 방법별, 제제 형태별, 작물 유형별, 지역별 예측(-2031년)Nematicide Market by Type (Chemical, Biologicals), Nematode Type (Root-Knot, Cyst, Lesion), Mode of Application (Drenching, Soil Dressing, Seed Treatment, Fumigation), Formulation, Crop Type, and Region - Global Forecast to 2031 |
||||||

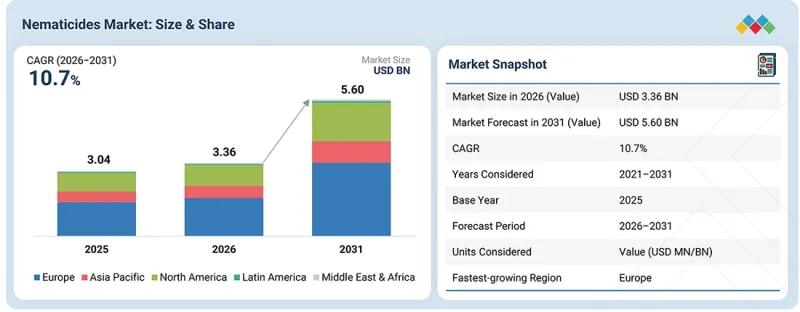
살선충제 시장 규모는 2026년에 33억 6,000만 달러로 추정되며, 2031년까지 56억 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 10.7%로 확대될 것으로 전망됩니다. 이 시장의 성장을 견인하고 있는 요인은 식물 기생 선충에 의한 작물 피해 증가입니다. 이러한 선충은 대두, 옥수수, 면화, 채소 등 주요 작물의 수확량을 크게 감소시키고 있습니다. 전 세계 식량 수요 증가와 경작지 감소에 따라 농가들은 헥타르당 생산성을 극대화해야 한다는 압박을 점점 더 강하게 받고 있으며, 효과적인 선충 관리가 필수적입니다. 과일, 채소, 플랜테이션 작물 등 고부가가치 작물은 특히 피해를 입기 쉬우며, 이로 인해 살선충제 수요가 더욱 증가하고 있습니다. 또한, 대규모 상업 농업 및 보호 재배 시스템의 확대로 인해 신뢰할 수 있는 선충 방제 솔루션에 대한 필요성이 높아지고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(100만/10억 달러) 및 수량(톤) |
| 부문 | 유형별, 선충 유형별, 시용 방법별, 제제 형태별, 작물 유형별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 남미 및 세계 기타 지역 |
또 다른 주요 성장 촉진요인은 종자 처리용 선충 구제제, 정밀 농업, 통합 해충 관리(IPM)와 같은 첨단 기술의 급속한 보급입니다. 이러한 기술들은 살포 효율을 높이고 투입 비용을 절감합니다. 기존 훈증제에 대한 규제적 제한 또한 정부의 이니셔티브와 지속가능성 목표에 힘입어, 보다 안전한 바이오 선충 방제제로의 전환을 가속화하고 있습니다. 또한, 전 세계 농약 기업들의 지속적인 제품 혁신, 전략적 제휴 및 투자를 통해 화학적 및 생물학적 선충 방제 솔루션의 가용성이 확대되고 있으며, 이는 시장 성장을 뒷받침하고 있습니다.
“예측 기간 동안 종자 처리 부문은 상당한 성장률을 보일 것으로 전망됩니다.”
시용 방법별로 보면, 종자 처리 부문은 그 효율성, 비용 대비 효과, 그리고 작물의 초기 단계에서의 보호 능력에 힘입어 선충 방제제 시장에서 상당한 성장률을 보일 것으로 예측됩니다. 기존의 토양 살포나 엽면 살포와 달리, 종자 처리에서는 선충 방제제를 종자에 직접적이고 정밀하게 시용할 수 있으므로 균일한 피복이 보장되고 필요한 화학 약품의 총량을 줄일 수 있습니다. 이러한 표적화된 접근 방식은 환경에 미치는 영향을 최소화하고, 발아율을 높이며, 작물의 정착을 강화함으로써 작물의 수확량 잠재력을 향상시킵니다. 지속 가능한 농업 실천에 대한 수요 증가와 과도한 화학 물질 사용을 줄이도록 요구하는 규제적 압력으로 인해 종자 처리 기술의 도입은 더욱 가속화되고 있습니다. 또한, 제제 기술의 발전과 생물 유래 선충 구제제를 종자 처리 과정에 통합함으로써, 특히 통합 해충 관리(IPM) 솔루션을 추구하는 농가들 사이에서 그 매력이 더욱 확대되고 있습니다. 전 세계 기업들이 혁신적인 종자 처리 솔루션에 투자하고 있는 만큼, 이 시용 방식은 선충 구제제 시장에서 앞으로도 강력한 성장 궤도를 유지할 것으로 예측됩니다.
“예측 기간 동안 뿌리혹선충 부문이 가장 큰 시장 점유율을 차지할 것으로 전망됩니다.”
선충 유형별로는 뿌리혹선충이 광범위한 분포와 농업 생산성에 미치는 심각한 영향으로 인해 선충 방제제 시장에서 가장 큰 점유율을 차지할 것으로 예측됩니다. 이 선충은 과일, 채소, 곡물, 콩류 등 광범위한 작물에 감염되어 뿌리에 혹을 형성하고 생육 부진 및 심각한 수확량 손실을 초래합니다. 다양한 농업 기후 조건에서 번식할 수 있는 능력을 갖추고 있어, 뿌리혹선충은 전 세계적으로 가장 파괴적인 식물 기생 선충군 중 하나가 되었습니다. 뿌리혹선충의 피해를 입기 쉬운 고부가가치 작물의 재배가 증가함에 따라, 효과적인 방제 수단에 대한 수요가 더욱 가속화되고 있습니다. 농가들은 종자 처리 기술과 통합 해충 관리(IPM) 기법의 발전에 힘입어, 이러한 해충을 관리하기 위해 화학적 및 생물학적 선충 살충제에 대한 의존도를 높이고 있습니다. 지속적인 제품 혁신과 바이오 유래 대체재의 도입은 내성 및 환경 안전성에 대한 우려를 해소하고 있으며, 선충 유형별 부문에서 뿌리혹선충의 우위를 더욱 공고히 하고 있습니다.
“유럽이 가장 큰 시장 점유율을 차지할 것으로 추정됩니다.”
유럽은 고도로 상업화된 농업 부문과 채소, 과일, 옥수수, 대두 등 고부가가치 작물의 광범위한 재배에 힘입어 전 세계 선충 구제제 시장에서 가장 큰 점유율을 차지할 것으로 추정됩니다. 이 지역의 농가들은 식물 기생 선충, 특히 뿌리혹선충과 낭선충으로 인한 심각한 수확량 손실에 직면해 있으며, 이는 효과적인 방제책에 대한 강력한 수요를 부추기고 있습니다. 종자 처리용 선충 구제제와 통합 해충 관리(IPM) 시스템 등 첨단 농업 기술의 도입이 시장 성장을 더욱 촉진하고 있습니다. 또한, 강력한 제품 포트폴리오와 지속적인 혁신을 갖춘 주요 농약 기업의 존재가 이 지역의 우위를 뒷받침하고 있습니다. 화학 농약 사용에 대한 엄격한 규제도 잔류물이 없는 농산물에 대한 소비자 수요와 맞물려, 생물 유래 선충 방제제로의 전환을 가속화하고 있습니다. 이러한 요인들로 인해, 생산 규모와 첨단 작물 보호 기법 양면에서 유럽은 선충 방제제의 주요 시장으로서의 입지를 확고히 하고 있습니다.
또한, 지속 가능한 농업에 대한 강력한 규제적 지원과 생물 유래 작물 보호 솔루션의 채택 확대에 힘입어, 유럽은 선충 구제제 시장에서 가장 빠르게 성장하는 지역 시장이 될 것으로 예측됩니다. 유럽연합(EU)의 기존 화학 농약에 대한 엄격한 규제로 인해, 생물 유래의 친환경 선충 방제제에 대한 의존도가 높아지면서 혁신과 시장 확대를 견인하고 있습니다. 스페인, 이탈리아, 프랑스 등 대규모 과일 및 채소 재배가 이루어지는 국가들은 심각한 선충 피해를 겪고 있어, 효과적이고 더 안전한 대체 수단에 대한 수요가 높아지고 있습니다. 또한, 이 지역에서는 정밀 농업의 실천이 급속히 보급되고 있어, 이를 통해 선충 구제제를 표적에 맞추어 살포할 수 있게 되어 환경에 미치는 영향을 최소화할 수 있습니다. 게다가 유기농 식품이나 잔류물이 없는 식품에 대한 소비자의 선호도가 높아짐에 따라, 생산자들은 생물 유래 선충 구제제에 대한 투자를 확대되고 있습니다. 정부의 적극적인 정책 지원과 지속적인 연구 개발 투자로 인해, 유럽은 선충 구제제 시장에서 가장 빠르게 성장하는 지역 시장으로 부상할 전망입니다.
1차 조사 내역
시장의 주요 기업으로는 BASF SE(독일), Bayer AG(독일), UPL(인도), T. Stanes and Company Limited(인도), Corteva(미국), Koppert(네덜란드), FMC Corporation(미국), Nufarm(호주),신젠타(스위스), 아메리칸 뱅가드 코퍼레이션(미국), 스미토모 화학(일본), 랄레만드(캐나다), 노보네시스 그룹(덴마크), 바이오베스트 그룹 NV(벨기에), PI 인더스트리즈(인도) 등이 있습니다.
그 밖의 주요 기업으로는 IPL Biologicals(인도), Bioceres Crop Solutions(아르헨티나), Rovensa Next(스페인), Bionema(영국), BioConsortia(미국), Certis USA L.L.C.(미국), Futureco Bioscience(스페인),Gowan Company(미국), AgriLife(인도), 그리고 Andermatt Group AG(스위스) 등이 있습니다.
조사 범위
본 조사 보고서에서는 살선충제 시장을 유형(화학 제제 및 생물 제제), 선충 유형(뿌리혹선충, 낭선충, 병반선충 및 기타 선충 유형), 제형(입제 및 액제), 시용 방법(훈증, 토양 살포, 관주, 종자 처리 및 기타 시용 방법), 작물 유형(곡물, 유지종자·콩류, 과일 및 채소 및 기타 작물), 그리고 지역(북미, 유럽,아시아태평양, 남미 및 기타 지역)별로 분류하고 있습니다. 본 보고서의 조사 범위에는 선충 구제제 시장의 성장에 영향을 미치는 촉진요인, 제약 요인, 과제 및 기회에 대한 상세한 정보가 포함되어 있습니다.
주요 업계 참여 기업에 대한 상세한 분석을 수행하여, 해당 기업의 사업 개요, 서비스, 주요 전략, 계약, 파트너십, 협정, 신규 서비스 출시, 합병·인수, 그리고 살선충제 시장과 관련된 최근 동향에 대한 인사이트를 제공합니다. 본 보고서에서는 선충 구제제 시장 생태계에서 두각을 나타내고 있는 스타트업 기업들에 대한 경쟁 분석도 다루고 있습니다. 또한, 본 조사에서는 기술 분석, 생태계 및 시장 매핑, 특허 및 규제 현황 등 업계 특유의 동향에 대해서도 다루고 있습니다.
본 보고서를 구매해야 하는 이유
본 보고서는 이 시장 시장 선도 기업 및 신규 진출기업에게 살선충제 시장 전체 및 각 하위 부문의 매출에 관한 가장 정확한 추정치를 제공합니다. 이를 통해 이해관계자는 경쟁 구도를 이해하고, 자사의 비즈니스를 더 유리한 위치에 놓으며, 적절한 시장 진출 전략을 수립하기 위한 추가적인 인사이트를 얻을 수 있습니다. 또한, 본 보고서는 이해관계자가 시장 동향을 파악하는 데 도움을 주며, 주요 시장 성장 촉진요인, 제약 요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다.
- 선충 구제제 시장의 성장에 영향을 미치는 주요 성장 촉진요인(고부가가치 작물에 대한 수요 증가), 제약 요인(국가별 규제 차이), 기회(유기 농업에서 식물 유래 선충 구제제 사용), 그리고 과제(내성 발생)에 대한 분석
- 신제품 출시 및 혁신 : 선충 구제제 시장의 연구 개발 활동 및 신제품 출시에 대한 상세한 분석
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보 - 다양한 지역의 선충 구제제 시장 분석
- 시장 다각화 : 선충 구제제 시장의 신규 서비스, 미개척 지역, 최근 동향 및 투자에 대한 종합적인 정보
- 경쟁 분석 : BASF(독일), Syngenta(스위스),바이엘 AG(독일), UPL(인도), 코르테바(미국), FMC 코퍼레이션(미국) 등, 선충 구제제 시장의 주요 기업별 시장 점유율, 성장 전략, 제품 라인업, 브랜드/제품 비교 및 제품 출시 현황에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 주요 요약
제3장 프리미엄 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 이니셔티브
제8장 고객 현황과 구매 행동
제9장 살선충제 시장(유형별)
제10장 살선충제 시장(선충 유형별)
제11장 살선충제 시장(시용 방법별)
제12장 살선충제 시장(제제 형태별)
제13장 살선충제 시장(작물 유형별)
제14장 살선충제 시장(지역별)
제15장 경쟁 구도
제16장 기업 개요
제17장 조사 방법
제18장 인접 시장 및 관련 시장
제19장 부록
KTH 26.09.28The nematicides market is estimated to be USD 3.36 billion in 2026 and is projected to reach USD 5.60 billion by 2031, expanding at a CAGR of 10.7% from 2026 to 2031. The market is being driven by rising crop losses caused by plant-parasitic nematodes, which significantly reduce yields in major crops such as soybeans, corn, cotton, and vegetables. With growing global food demand and shrinking arable land, farmers are under increasing pressure to maximize productivity per hectare, making effective nematode management essential. High-value crops like fruits, vegetables, and plantation crops are particularly vulnerable, further boosting the demand for nematicides. In addition, the expansion of large-scale commercial farming and protected cultivation systems has heightened the need for reliable nematode control solutions.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) and Volume (Tons) |
| Segments | Type, Formulation, Nematode Type, Mode of Application, Crop Type, and Region |
| Regions covered | North America, Europe, Asia Pacific, South America, and Rest of the World |
Another key driver is the rapid adoption of advanced technologies such as seed-applied nematicides, precision agriculture, and integrated pest management (IPM), which improve application efficiency and reduce input costs. Regulatory restrictions on traditional fumigants have also accelerated the shift toward safer, bio-based nematicides, supported by government initiatives and sustainability goals. Furthermore, continuous product innovations, strategic partnerships, and investments by global agrochemical companies are expanding the availability of both chemical and biological nematicide solutions, thereby reinforcing market growth.
"The seed treatment segment will grow at a significant rate during the forecast period"
By mode of application, the seed treatment segment is expected to exhibit a significant growth rate in the nematicides market, driven by its efficiency, cost-effectiveness, and ability to provide early-stage protection to crops. Unlike traditional soil or foliar applications, seed treatment enables precise application of nematicides directly onto seeds, ensuring uniform coverage and reducing the overall quantity of chemicals required. This targeted approach minimizes environmental impact, enhances germination rates, and strengthens plant establishment, thereby improving crop yield potential. Rising demand for sustainable agricultural practices and regulatory pressures to reduce excessive chemical usage have further accelerated the adoption of seed-applied technologies. Additionally, advancements in formulation technology and the integration of biological nematicides into seed treatments have broadened their appeal, particularly among farmers seeking integrated pest management solutions. With global players investing in innovative seed treatment solutions, this mode of application is expected to continue its strong growth trajectory in the nematicides market.
"The root-knot nematodes segment will hold the largest market share during the forecast period"
By nematode type, root-knot nematodes are expected to hold the largest share of the nematicides market due to their wide distribution and severe impact on agricultural productivity. These nematodes infect a broad range of crops, including fruits, vegetables, cereals, and pulses, causing gall formation on roots, stunted growth, and significant yield losses. Their ability to thrive in diverse agro-climatic conditions makes them one of the most destructive groups of plant-parasitic nematodes globally. The rising cultivation of high-value crops that are highly susceptible to root-knot nematode infestations has further accelerated the demand for effective control solutions. Farmers are increasingly relying on both chemical and biological nematicides to manage these pests, supported by advancements in seed treatments and integrated pest management practices. Continuous product innovations and the introduction of bio-based alternatives are also addressing concerns over resistance and environmental safety, reinforcing root-knot nematodes' dominance in the nematode type segment.
"Europe is estimated to account for the largest market share"
Europe is estimated to hold the largest share of the global nematicides market, driven by its highly commercialized agriculture sector and extensive cultivation of high-value crops such as vegetables, fruits, corn, and soybeans. Farmers in the region face significant yield losses from plant-parasitic nematodes, particularly root-knot and cyst nematodes, which have fueled strong demand for effective control solutions. The adoption of advanced farming technologies, including seed-applied nematicides and integrated pest management systems, has further strengthened the market's growth. Additionally, the presence of leading agrochemical companies with strong product portfolios and continuous innovations supports regional dominance. Stringent regulations on chemical pesticide use have also accelerated the shift toward biological nematicides, aligning with consumer demand for residue-free produce. These factors position Europe as the leading market for nematicides, reflecting both scale of production and advanced crop protection practices.
Europe is also projected to be the fastest-growing regional market for nematicides, supported by strong regulatory backing for sustainable agriculture and rising adoption of biological crop protection solutions. The European Union's strict restrictions on conventional chemical pesticides have increased reliance on bio-based and environmentally friendly nematicides, driving innovation and market expansion. Countries such as Spain, Italy, and France, with large-scale fruit and vegetable cultivation, face significant nematode infestations, creating high demand for effective and safer alternatives. The region is also witnessing rapid integration of precision agriculture practices, enabling targeted nematicide application and minimizing environmental impact. Furthermore, increasing consumer preference for organic and residue-free food products is encouraging growers to invest in biological nematicide solutions. With active support from government policies and continuous R&D investments, Europe is positioned to emerge as the fastest-growing regional market for nematicides.
Break-up of Primaries
In-depth interviews were conducted with chief executive officers (CEOs), directors, and other executives from various key organizations operating in the nematicides market:
- By Company Type: Tier 1 - 25%, Tier 2 - 45%, and Tier 3 - 30%
- By Designation: Directors- 20%, Managers - 50%, Executives - 30%
- By Region: North America - 25%, Europe - 30%, Asia Pacific - 20%, South America - 15%, and Rest of the World - 10%
Prominent companies in the market include BASF SE (Germany), Bayer AG (Germany), UPL (India), T. Stanes and Company Limited (India), Corteva (US), Koppert (Netherlands), FMC Corporation (US), Nufarm (Australia), Syngenta (Switzerland), American Vanguard Corporation (US), Sumitomo Chemicals (Japan), Lallemand Inc. (Canada), Novonesis Group (Denmark), Biobest Group NV (Belgium), and PI Industries (India).
Other players include IPL Biologicals (India), Bioceres Crop Solutions (Argentina), Rovensa Next (Spain), Bionema (UK), BioConsortia (US), Certis USA L.L.C. (US), Futureco Bioscience (Spain), Gowan Company (US), AgriLife (India), and Andermatt Group AG (Switzerland).
Research Coverage
This research report categorizes the nematicides market by type (chemicals and biologicals), nematode type (root-knot nematodes, cyst nematodes, lesion nematodes, and other nematode types), formulation (granular and liquid), mode of application (fumigation, soil dressing, drenching, seed treatment, and other modes of application), crop type (cereals & grains, oilseeds & pulses, fruits & vegetables, and other crop types), and region (North America, Europe, Asia Pacific, South America, and the Rest of the World). The scope of the report covers detailed information regarding drivers, restraints, challenges, and opportunities influencing the growth of the nematicides market.
A detailed analysis of the key industry players was done to provide insights into their business overview, services, key strategies, contracts, partnerships, agreements, new service launches, mergers and acquisitions, and recent developments associated with the nematicides market. This report covers competitive analysis of upcoming startups in the nematicides market ecosystem. Furthermore, the study also covers industry-specific trends such as technology analysis, ecosystem and market mapping, and patent and regulatory landscape, among others.
Reasons to Buy this Report
The report will help market leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the overall nematicides and the subsegments. It will help stakeholders understand the competitive landscape and gain more insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
It provides insights into the following pointers:
- Analysis of key drivers (high demand for high-value crops), restraints (varying government regulations), opportunities (use of plant-based nematicides in organic agriculture), and challenges (resistance development) influencing the growth of the nematicides market
- New Product Launch/Innovation: Detailed insights into research & development activities and new product launches in the nematicides market
- Market Development: Comprehensive information about lucrative markets - analysis of the nematicides market across varied regions
- Market Diversification: Exhaustive information about new services, untapped geographies, recent developments, and investments in the nematicides market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, brand/product comparisons, and product footprints of leading players such as BASF (Germany), Syngenta (Switzerland), Bayer AG (Germany), UPL (India), Corteva (US), FMC Corporation (US), and others in the nematicides market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.4 YEARS CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.5.1 CURRENCY/VALUE UNIT
- 1.5.2 VOLUME CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN NEMATICIDES MARKET
- 3.2 NEMATICIDES MARKET, BY FORMULATION AND REGION
- 3.3 NEMATICIDES MARKET, BY TYPE
- 3.4 NEMATICIDES MARKET, BY NEMATODE TYPE
- 3.5 NEMATICIDES MARKET, BY CROP TYPE
- 3.6 NEMATICIDES MARKET, BY MODE OF APPLICATION
- 3.7 NEMATICIDES MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Strong demand for high-value crops
- 4.2.1.2 Demand for low-cost crop protection solutions
- 4.2.1.3 Increasing damage to crop production due to nematode infestations
- 4.2.1.4 Integration with modern farming practices
- 4.2.2 RESTRAINTS
- 4.2.2.1 Technological limitations in use of biological products
- 4.2.2.2 Varying government regulations
- 4.2.2.3 Accumulation of nematicide residues during fumigation
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Use of plant-based nematicides in organic agriculture and horticulture
- 4.2.3.2 Rising nematodes resistance to conventional chemicals to drive demand for novel nematicide solutions
- 4.2.3.3 Rising demand for biological solutions
- 4.2.4 CHALLENGES
- 4.2.4.1 Expanding adoption of GM crops reducing dependence on conventional crop protection chemicals
- 4.2.4.2 Lack of awareness and low utilization of biologicals
- 4.2.4.3 Inconsistent field performance
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN NEMATICIDES MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.4.1 EMERGING BUSINESS MODELS
- 4.4.2 ECOSYSTEM SHIFTS
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.3 GLOBAL CROP LOSSES DUE TO NEMATODES
- 5.3.1 ADOPTION OF PESTICIDES FOR DEFENSE AGAINST PEST ATTACKS
- 5.4 VALUE CHAIN ANALYSIS
- 5.4.1 RESEARCH & DEVELOPMENT
- 5.4.2 MANUFACTURING
- 5.4.3 DISTRIBUTION
- 5.4.4 MARKETING & SALES
- 5.4.5 POST-SALE SERVICES
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 DEMAND SIDE
- 5.5.2 SUPPLY SIDE
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE BY KEY PLAYERS, FUNCTION
- 5.6.2 AVERAGE SELLING PRICE TREND, BY REGION
- 5.6.3 AVERAGE SELLING PRICE TREND, BY TYPE
- 5.7 TRADE ANALYSIS
- 5.7.1 EXPORT SCENARIO OF HS CODE 3808
- 5.7.2 IMPORT SCENARIO OF HS CODE 3808
- 5.8 KEY CONFERENCES AND EVENTS, 2026
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.11 CASE STUDY ANALYSIS
- 5.11.1 CORTEVA AGRISCIENCE: LAUNCH NOVEL NON-FUMIGANT NEMATICIDE TO STRENGTHEN ROOT-KNOT NEMATODE CONTROL
- 5.11.2 BAYER: EXPANDING BIOLOGICAL NEMATODE MANAGEMENT WITH VELSINUM
- 5.11.3 SYNGENTA: INTRODUCING VICTRATO COMPLETE FOR SOYBEAN SEED TREATMENT
- 5.12 IMPACT OF 2026 US TARIFF - NEMATICIDES MARKET
- 5.12.1 INTRODUCTION
- 5.12.2 PRICE IMPACT ANALYSIS
- 5.12.3 IMPACT ON COUNTRIES/REGIONS
- 5.12.3.1 India
- 5.12.3.2 China
- 5.12.3.3 European Union
- 5.12.4 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 RNA-BASED NEMATICIDES
- 6.1.2 MICROBIAL CONSORTIA & ENGINEERED BIOLOGICAL NEMATICIDES
- 6.1.3 AI-ENABLED PRECISION NEMATICIDE APPLICATION
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 SOIL NEMATODE DETECTION & MOLECULAR DIAGNOSTICS
- 6.2.2 PRECISION SOIL MAPPING & VARIABLE-RATE APPLICATION
- 6.2.3 BIOLOGICAL SOIL HEALTH & MICROBIOME MANAGEMENT
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 SEED TREATMENT & SEED-DELIVERED PROTECTION
- 6.3.2 BIOSTIMULANTS & PLANT DEFENSE ACTIVATORS
- 6.3.3 CONTROLLED-RELEASE & ENCAPSULATION TECHNOLOGIES
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 6.5 PATENT ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AI-POWERED NEMATICIDE DISCOVERY
- 6.6.2 ADVANCED COMBINATION NEMATICIDES
- 6.6.3 PRECISION NEMATODE-BASED APPLICATION
- 6.6.4 SMART FORMULATION & CONTROLLED DELIVERY
- 6.6.5 FULLY INTEGRATED DIGITAL NEMATODE FARMING
- 6.7 IMPACT OF GENERATIVE AI ON NEMATICIDES MARKET
- 6.7.1 INTRODUCTION
- 6.7.2 USE OF GENERATIVE AI ON NEMATICIDES MARKET
- 6.7.3 TOP USE CASES AND MARKET POTENTIAL
- 6.7.4 BEST PRACTICES IN NEMATICIDES INDUSTRY
- 6.7.5 CASE STUDIES OF AI IMPLEMENTATION IN NEMATICIDES MARKET
- 6.7.6 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.7 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN NEMATICIDES MARKET
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USER/END-USE INDUSTRIES
- 8.4.1 COMMERCIAL FARMING
- 8.4.2 HORTICULTURE & HIGH-VALUE CROPS
- 8.4.3 PLANTATION & PERENNIAL CROPS
- 8.4.3.1 Smallholder Farming
- 8.4.4 ORGANIC FARMING
- 8.4.5 AGRICULTURAL COOPERATIVES
- 8.5 MARKET PROFITABILITY
9 NEMATICIDES MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 CHEMICALS
- 9.2.1 LONGER RESIDUAL ACTIVITY AND QUICK MODE OF ACTION AGAINST NEMATODES TO DRIVE SEGMENT
- 9.2.2 FUMIGANTS
- 9.2.2.1 Broad-spectrum functionality of fumigants against nematodes to positively drive market
- 9.2.2.1.1 Methyl bromide
- 9.2.2.1.2 Metam sodium
- 9.2.2.1.3 1-3-Dichloropropene
- 9.2.2.1.4 Other fumigants
- 9.2.2.1 Broad-spectrum functionality of fumigants against nematodes to positively drive market
- 9.2.3 NON-FUMIGANTS
- 9.2.3.1 Carbamates
- 9.2.3.2 Organophosphates
- 9.2.3.3 Abamectin (Next-gen)
- 9.2.3.4 SDHI (Next-gen)
- 9.2.3.5 Fluopyram
- 9.2.3.6 Cyclobutrifluram
- 9.2.4 OTHER CHEMICALS
- 9.2.4.1 Fluoroalkenyl Compounds
- 9.2.4.2 Tioxazafen
- 9.2.4.3 Fluazaindolizine
- 9.3 BIOLOGICALS
- 9.3.1 STRINGENT REGULATORY POLICIES ON CONVENTIONAL AGROCHEMICALS TO PROPEL SEGMENT GROWTH
- 9.3.2 MICROBIALS
- 9.3.2.1 High adoption of sustainable agricultural techniques to fuel growth
- 9.3.3 BIOCHEMICALS
- 9.3.3.1 Residue-free nematode management by biochemicals to propel growth
10 NEMATICIDES MARKET, BY NEMATODE TYPE
- 10.1 INTRODUCTION
- 10.2 ROOT-KNOT NEMATODES
- 10.2.1 BROAD HOST RANGE AND SEVERE ROOT DAMAGE CAUSED BY ROOT-KNOT NEMATODES TO PROPEL SEGMENT GROWTH
- 10.3 CYST NEMATODES
- 10.3.1 LARGE-SCALE ECONOMIC LOSSES AND LOWER YIELD QUALITY DUE TO CYST NEMATODE INFESTATION TO INCREASE DEMAND
- 10.4 LESION NEMATODES
- 10.4.1 WIDE HOST RANGE AND PRESENCE IN TEMPERATE AND TROPICAL ENVIRONMENTS TO DRIVE MARKET
- 10.5 OTHER NEMATODE TYPES
11 NEMATICIDES MARKET, BY MODE OF APPLICATION
- 11.1 INTRODUCTION
- 11.2 FUMIGATION
- 11.2.1 LOWER COSTS INVOLVED IN FUMIGATION FOR NEMATODE CONTROL TO PROPEL GROWTH
- 11.3 DRENCHING
- 11.3.1 PRECISE APPLICATION AND DEEP PENETRATION OF NEMATICIDES ON TARGET NEMATODES TO DRIVE DEMAND
- 11.4 SOIL DRESSING
- 11.4.1 EFFECTIVE MANAGEMENT OF EARLY SEASON NEMATODE TO DRIVE DEMAND
- 11.5 SEED TREATMENT
- 11.5.1 SAFER APPLICATION AND EARLY SEASON PROTECTION AGAINST NEMATODES TO AUGMENT DEMAND
- 11.6 OTHER MODES OF APPLICATION
12 NEMATICIDES MARKET, BY FORMULATION
- 12.1 INTRODUCTION
- 12.2 GRANULAR
- 12.2.1 GOOD STORAGE VIABILITY TO DRIVE SEGMENT GROWTH
- 12.3 LIQUID
- 12.3.1 GREATER DEGREE OF DISPERSION PROPERTY OFFERED BY LIQUID NEMATICIDES TO DRIVE DEMAND
13 NEMATICIDES MARKET, BY CROP TYPE
- 13.1 INTRODUCTION
- 13.2 CEREALS & GRAINS
- 13.2.1 RISE IN CONSUMPTION OF CEREALS & GRAINS TO DRIVE MARKET
- 13.2.2 CORN
- 13.2.3 WHEAT
- 13.2.4 RICE
- 13.2.5 OTHER CEREALS & GRAINS
- 13.3 OILSEEDS & PULSES
- 13.3.1 INCREASE IN CONSUMPTION OF PROTEIN- AND HEALTHY FAT-RICH MEALS TO DRIVE SEGMENT
- 13.3.2 SOYBEAN
- 13.3.3 SUNFLOWER
- 13.3.4 OTHER OILSEEDS & PULSES
- 13.4 FRUITS & VEGETABLES
- 13.4.1 RISE IN EXPORTS OF FRESH, FROZEN, AND PROCESSED FRUITS & VEGETABLES FROM SOUTH ASIA TO DRIVE DEMAND
- 13.4.2 POME FRUITS
- 13.4.3 CITRUS FRUITS
- 13.4.4 LEAFY VEGETABLES
- 13.4.5 BERRIES
- 13.4.6 ROOTS & TUBERS VEGETABLES
- 13.4.7 OTHER FRUITS & VEGETABLES
- 13.5 OTHER CROP TYPES
14 NEMATICIDES MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Research undertaken to introduce nematode-resistant vegetables and field crops
- 14.2.2 CANADA
- 14.2.2.1 Losses in high-value cash crops to drive adoption of nematicides
- 14.2.3 MEXICO
- 14.2.3.1 Increase in root-knot and root-lesion nematode infestation in wheat to fuel market
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 GERMANY
- 14.3.1.1 Major players investing in agricultural solutions to cater to nematode attacks in field crops
- 14.3.2 UK
- 14.3.2.1 High demand for nematicides since farmers still use traditional farming methods
- 14.3.3 FRANCE
- 14.3.3.1 Extensive government funds in R&D to devise various sustainable methods for nematode control
- 14.3.4 SPAIN
- 14.3.4.1 Increase in government initiatives to encourage use of biological nematicides
- 14.3.5 ITALY
- 14.3.5.1 Changes across the entire supply chain with the goal of sustainable farming to drive the market
- 14.3.6 REST OF EUROPE
- 14.3.1 GERMANY
- 14.4 ASIA PACIFIC
- 14.4.1 CHINA
- 14.4.1.1 Rise in infestation by root-knot nematodes in crops to propel market
- 14.4.2 JAPAN
- 14.4.2.1 Various products catering to long-term viability of crops to drive growth
- 14.4.3 INDIA
- 14.4.3.1 Protected environment in polyhouses to create a favorable environment for root-knot nematodes
- 14.4.4 AUSTRALIA & NEW ZEALAND
- 14.4.4.1 Increase in canola losses due to nematode attacks to support adoption of nematicides
- 14.4.5 REST OF ASIA PACIFIC
- 14.4.1 CHINA
- 14.5 SOUTH AMERICA
- 14.5.1 ARGENTINA
- 14.5.1.1 Increase in focus on cultivating soybean and corn to boost demand for nematicides
- 14.5.2 BRAZIL
- 14.5.2.1 High adoption of GM crops to increase usage of nematicides
- 14.5.3 REST OF SOUTH AMERICA
- 14.5.1 ARGENTINA
- 14.6 REST OF THE WORLD (ROW)
- 14.6.1 MIDDLE EAST
- 14.6.1.1 Rise in population, high dependency on imports, and yield loss due to nematodes to fuel market
- 14.6.2 AFRICA
- 14.6.2.1 Growth in demand for vegetable crops to drive growth
- 14.6.1 MIDDLE EAST
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 15.3 REVENUE ANALYSIS, 2021-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.4.1 SYNGENTA
- 15.4.2 CORTEVA
- 15.4.3 BAYER AG
- 15.4.4 BASF SE
- 15.4.5 UPL
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.5.5.1 Company footprint
- 15.5.5.2 Region footprint
- 15.5.5.3 Type footprint
- 15.5.5.4 Formulation footprint
- 15.5.5.5 Crop type footprint
- 15.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.6.1 PROGRESSIVE COMPANIES
- 15.6.2 RESPONSIVE COMPANIES
- 15.6.3 DYNAMIC COMPANIES
- 15.6.4 STARTING BLOCKS
- 15.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.6.5.1 Detailed list of key startups/SMEs
- 15.6.5.2 Competitive benchmarking of key startups/SMEs
- 15.7 COMPANY VALUATION AND FINANCIAL METRICS
- 15.8 BRAND/PRODUCT COMPARISON
- 15.9 COMPETITIVE SCENARIO AND TRENDS
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 BASF SE
- 16.1.1.1 Business overview
- 16.1.1.2 Products offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches
- 16.1.1.3.2 Deals
- 16.1.1.3.3 Expansions
- 16.1.1.4 MnM view
- 16.1.1.4.1 Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses and competitive threats
- 16.1.2 SYNGENTA
- 16.1.2.1 Business overview
- 16.1.2.2 Products offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches
- 16.1.2.3.2 Deals
- 16.1.2.3.3 Expansions
- 16.1.2.4 MnM view
- 16.1.2.4.1 Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses and competitive threats
- 16.1.3 CORTEVA
- 16.1.3.1 Business overview
- 16.1.3.2 Products offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Product launches
- 16.1.3.3.2 Deals
- 16.1.3.3.3 Expansions
- 16.1.3.4 MnM view
- 16.1.3.4.1 Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses and competitive threats
- 16.1.4 UPL
- 16.1.4.1 Business overview
- 16.1.4.2 Products offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Product launches
- 16.1.4.3.2 Deals
- 16.1.4.4 MnM view
- 16.1.4.4.1 Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses and competitive threats
- 16.1.5 BAYER AG
- 16.1.5.1 Business overview
- 16.1.5.2 Products offered
- 16.1.5.3 Recent development
- 16.1.5.3.1 Product launches
- 16.1.5.3.2 Deals
- 16.1.5.4 MnM view
- 16.1.5.4.1 Right to win
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses and competitive threats
- 16.1.6 FMC CORPORATION
- 16.1.6.1 Business overview
- 16.1.6.2 Products offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Deals
- 16.1.6.4 MnM view
- 16.1.7 SUMITOMO CHEMICAL CO., LTD.
- 16.1.7.1 Business overview
- 16.1.7.2 Products offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.7.3.2 Expansions
- 16.1.7.4 MnM view
- 16.1.8 NUFARM
- 16.1.8.1 Business overview
- 16.1.8.2 Products offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.8.3.2 Other developments
- 16.1.8.4 MnM view
- 16.1.9 AMERICAN VANGUARD CORPORATION
- 16.1.9.1 Business overview
- 16.1.9.2 Products offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Deals
- 16.1.9.4 MnM view
- 16.1.10 NOVONESIS GROUP
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Solutions/Services offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Deals
- 16.1.10.4 MnM view
- 16.1.11 BIOCERES CROP SOLUTIONS
- 16.1.11.1 Business overview
- 16.1.11.2 Products offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Product launches
- 16.1.11.3.2 Deals
- 16.1.11.4 MnM view
- 16.1.12 GOWAN COMPANY
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Solutions/Services offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Deals
- 16.1.12.4 MnM view
- 16.1.13 CERTIS USA L.L.C.
- 16.1.13.1 Business overview
- 16.1.13.2 Products offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 Deals
- 16.1.13.3.2 Other developments
- 16.1.13.4 MnM view
- 16.1.14 LALLEMAND INC
- 16.1.14.1 Business overview
- 16.1.14.2 Products/Solutions/Services offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Product launches
- 16.1.14.4 MnM view
- 16.1.15 AECI PLANT HEALTH
- 16.1.15.1 Business overview
- 16.1.15.2 Product offered
- 16.1.15.3 MnM view
- 16.1.1 BASF SE
- 16.2 OTHER PLAYERS (SMES/STARTUPS)
- 16.2.1 ANDERMATT GROUP AG
- 16.2.1.1 Business overview
- 16.2.1.2 Products offered
- 16.2.2 IPL BIOLOGICALS
- 16.2.2.1 Business overview
- 16.2.2.2 Products offered
- 16.2.2.3 Recent developments
- 16.2.2.3.1 Expansions
- 16.2.3 PHERONYM, INC.
- 16.2.3.1 Business overview
- 16.2.3.2 Products offered
- 16.2.4 AGRILIFE
- 16.2.4.1 Business overview
- 16.2.4.2 Product offered
- 16.2.5 CROP IQ TECHNOLOGY LTD
- 16.2.5.1 Business overview
- 16.2.5.2 Products offered
- 16.2.5.3 Recent developments
- 16.2.5.3.1 Expansions
- 16.2.1 ANDERMATT GROUP AG
- 16.3 OTHER KEY PLAYERS
- 16.3.1 ROVENSA NEXT
- 16.3.2 BIONEMA
- 16.3.3 BIOCONSORTIA
- 16.3.4 VIVE CROP PROTECTION INC.
- 16.3.5 VEGALAB SA
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 List of major secondary sources
- 17.1.1.2 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.2.3 Breakdown of primaries
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 BOTTOM-UP APPROACH
- 17.2.2 TOP-DOWN APPROACH
- 17.2.2.1 Approach to estimate market size using top-down analysis
- 17.3 DATA TRIANGULATION
- 17.4 RESEARCH ASSUMPTIONS
- 17.5 RESEARCH LIMITATIONS AND RISK ASSESSMENT
18 ADJACENT AND RELATED MARKETS
- 18.1 INTRODUCTION
- 18.2 LIMITATIONS
- 18.3 CROP PROTECTION CHEMICALS MARKET
- 18.3.1 MARKET DEFINITION
- 18.3.2 MARKET OVERVIEW
- 18.4 BIORATIONAL PESTICIDES MARKET
- 18.4.1 MARKET DEFINITION
- 18.4.2 MARKET OVERVIEW
19 APPENDIX
- 19.1 DISCUSSION GUIDE
- 19.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.3 AVAILABLE CUSTOMIZATION
- 19.4 RELATED REPORTS
- 19.5 AUTHOR DETAILS


