
|
시장보고서
상품코드
2132649
치과 서비스 조직 시장 : 서비스 유형별, 최종사용자별, 지역별 - 세계 예측(-2031년)Dental Service Organization Market by Service Type (Human Resources, Marketing and Branding, Accounting, Medical Supplies Procurement, and Other Services), by End User (Oral Surgeons, Endodontists, and Other Dental Specialists) - Global Forecast to 2031 |
||||||

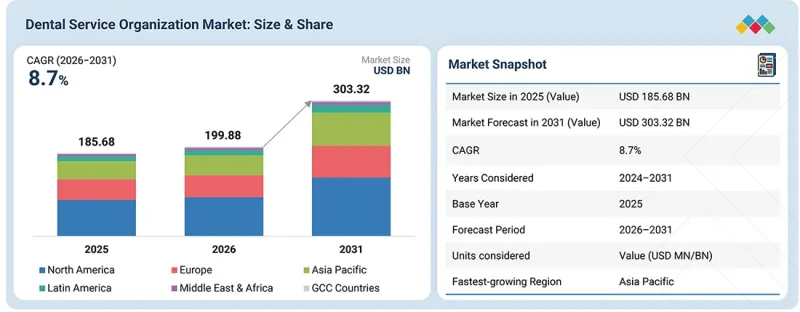
치과 서비스 조직 시장 규모는 2026년 1,998억 8,000만 달러에서 2031년까지 3,033억 2,000만 달러에 달할 것으로 예측되며, 예측 기간 동안 CAGR은 8.7%가 될 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 서비스 유형별, 최종사용자별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카(GCC 국가, 기타 중동 및 아프리카 국가) |
세계 치과 서비스 조직 시장은 주로 치과의사의 치과 서비스 조직 가입 증가, 관리 업무의 복잡화 심화, 그리고 독립형 치과 진료소 전반에 걸친 인재 확보 과제에 의해 주도되고 있습니다. 치과 의료에 대한 수요 증가, 치과 의료비 상승, 그리고 대상 치과 의료 시장의 확대로 인해 효율적인 진료소 운영과 통합된 비즈니스 지원 서비스의 필요성이 크게 높아지고 있습니다. 치과 서비스 조직은 인사, 마케팅 및 브랜딩, 회계, 의료용품 조달, 사무 지원 등 폭넓은 비임상 서비스를 제공하며, 이를 통해 가맹 치과의사는 운영상의 부담을 줄이고 환자 치료에 전념할 수 있게 됩니다.
치과 기술의 발전과 디지털 덴티스트리, 인공지능(AI), 클라우드형 진료 관리 시스템, 전자 차트, 디지털 영상 진단의 보급이 확대됨에 따라, 진료 효율 향상에 있어 치과 서비스 조직의 역할은 더욱 강화되고 있습니다. 이러한 기술을 통해 치과 서비스 조직은 관리 프로세스의 표준화, 환자와의 관계 강화, 예약·청구 업무의 최적화, 그리고 가맹 치과 병원 간의 연계 강화를 실현할 수 있습니다. 또한, 일원화된 조달과 규모의 경제에 대한 수요가 증가함에 따라, 치과 병원은 운영 비용 절감과 자원 활용도 향상을 도모하기 위해 치과 서비스 조직에 가입하는 추세를 보이고 있습니다.
또한, 관리 업무에 대한 전문 지식, 인재 관리, 기술 인프라, 마케팅 지원, 협상을 통한 조달 계약 체결 기회 등 제휴의 이점에 대한 치과의사의 인식이 높아진 점도 시장 성장에 긍정적인 영향을 미치고 있습니다. 치과 병원 네트워크의 확대, 세분화된 치과 서비스 업계의 통합, 그리고 치과 병원에 대한 투자 확대는 치과 서비스 조직 모델의 도입을 더욱 뒷받침하고 있습니다. 치과 의료에 대한 수요 증가, 운영상의 과제 확대, 기술 발전, 그리고 효율적인 치과 운영에 대한 요구 증가가 맞물려 전 세계 치과 서비스 조직 시장의 확장을 견인하고 있습니다.
“서비스 유형별로는 2025년 전 세계 치과 서비스 조직 시장에서 인사 서비스가 가장 큰 시장 점유율을 차지했습니다.”
이러한 우위는 치과 병원이 직면한 인재 확보 과제의 증가와 일원화된 인재 관리에 대한 수요 증가에 기인합니다. 치과 서비스 조직이 제공하는 인사 서비스에는 채용, 직원 입사 절차, 급여 및 복리후생 관리, 인재 계획, 연수, 그리고 직원 정착 지원이 포함되어 있으며, 이를 통해 제휴하는 치과 병원은 사무적 부담을 줄이면서 인재를 효율적으로 관리할 수 있게 됩니다. 치과 의사의 치과 서비스 조직 가입이 증가하고 있는 것이 통합된 인사 서비스에 대한 수요를 더욱 가속화하고 있습니다. 치과 서비스 조직이 진료소의 가입이나 인수를 통해 네트워크를 확대함에 따라, 여러 거점에 걸쳐 있는 치과 의사, 치과 위생사, 치과 조무사 및 사무 직원을 채용·관리·유지할 필요성이 높아지고 있습니다. 또한, 자격을 갖춘 치과 전문 인력을 둘러싼 경쟁 심화와 인건비 급등으로 인해 치과 병원은 치과 서비스 조직의 인재 관리 능력을 활용하고 있습니다. 이러한 요인들에 더해, 치과 병원의 사무 처리 복잡성 증가와 업무 효율성 향상에 대한 수요가 높아지고 있는 점이 맞물려, 전 세계 치과 서비스 조직 시장에서 인사 부문이 주도적인 위치를 차지하는 한 요인이 되고 있습니다.
“최종사용자별로는 2025년 전 세계 치과 서비스 조직 시장에서 구강외과 의사가 가장 큰 점유율을 차지했습니다.”
이 부문이 우위를 점하고 있는 주요 이유는 구강외과 및 악안면외과 진료소에서 전문 인력, 수술 시설, 장비, 환자 조정 등 막대한 자원이 필요하기 때문입니다. 이러한 진료소에서는 고도의 치과 및 안면 수술을 받는 전원 환자를 다루는 경우가 많아, 이에 따라 운영 및 관리상의 부담이 가중됩니다. DSO는 중앙 집중화된 구매, 인력 배치, 재무 관리, 일정 관리 및 기술 지원을 통해 이러한 요구 사항을 충족시킬 수 있습니다. 제휴한 모든 진료소에서 이러한 기능을 통합할 수 있다는 점이 바로 구강외과 및 악안면외과 진료소에 있어 DSO 모델을 특히 매력적으로 만드는 요소입니다.
“예측 기간 동안 북미 치과 서비스 조직(DSO) 시장에서 미국이 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다.”
예측 기간 동안 북미 치과 서비스 조직 시장에서 미국은 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 이러한 성장은 치과의사의 치과 서비스 조직 가입 증가, 관리 업무의 복잡화, 그리고 치과 진료소 전반에 걸친 인력 확보 문제의 심화 등 몇 가지 주요 요인에 의해 주도되고 있습니다. 미국의 대규모이자 고도로 발달된 치과 의료 시장, 치과 의료비 증가, 그리고 확고히 자리 잡은 치과 서비스 조직의 강력한 존재감이 시장 확대를 더욱 뒷받침하고 있습니다. 또한, 독립 치과 병원의 통합이 진행되고 있으며, 진료 관리, 인사, 마케팅,회계, 조달 서비스의 일원화가 확산되고 있는 점이 미국 내 치과 서비스 조직 모델에 대한 수요를 가속화하고 있습니다. 또한, 디지털 덴티스트리, 인공지능(AI), 클라우드 기반 진료 관리 시스템 및 기타 기술을 활용한 솔루션의 이용 확대에 따라 업무 효율이 향상되어 치과 서비스 조직 네트워크의 확장이 뒷받침되고 있습니다. 치과의사들 사이에서 사무 업무 부담 경감, 일원화된 사업 지원에 대한 접근성, 규모의 경제 실현, 그리고 인력 부족에 대한 대응에 대한 수요가 높아지고 있는 것이 치과 서비스 조직 가입 증가를 뒷받침하고 있습니다. 이러한 요인들이 복합적으로 작용하여, 미국은 북미 내 치과 서비스 조직 시장에서 가장 크고 가장 빠르게 성장하는 시장으로서의 입지를 확고히 하고 있습니다.
세계 치과 서비스 조직 시장의 주요 기업으로는 Heartland Dental(미국), The Aspen Group - TAG(미국), Q and M Dental Group(싱가포르), PDS Health(미국) 등이 있습니다.
조사 범위:
본 보고서에서는 치과 서비스 조직 시장을 분석하고, 서비스 유형별, 최종사용자별, 지역별 부문별로 시장 규모 및 향후 성장 가능성을 추정하고 있습니다. 또한, 시장의 주요 업체에 대한 경쟁 분석도 수록되어 있으며, 각 기업 개요, 제공 제품, 최근 동향 및 주요 시장 전략에 대해 해설하고 있습니다.
본 보고서를 구매해야 하는 이유
본 보고서는 치과 서비스 조직 시장의 시장 선도 기업과 신규 진입 기업 모두에게 유용한 인사이트를 제공하며, 가장 정확한 시장 수익 추정치를 제시합니다. 이해관계자가 경쟁 구도를 이해하고, 자사의 비즈니스를 적절히 포지셔닝하며, 효과적인 시장 진입 전략을 수립하는 데 도움이 됩니다. 또한, 본 보고서는 시장의 주요 촉진요인, 억제요인, 과제 및 기회를 밝혀내어, 이해관계자가 현재의 시장 동향을 포괄적으로 파악할 수 있도록 지원합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인(치과 의사의 DSO 가입 증가, 치과 진료소의 관리 업무 복잡화 및 인재 확보 과제, 치과 의료비 증가 및 대상 치과 의료 시장의 확대), 제약요인(규제상의 제한 및 주별 DSO 소유권에 대한 차이, 임상적 자율성이나 치과 의사의 관리권에 대한 우려), 기회(DSO가 치과 업계에 미치는 영향, AI 및 디지털 기술 도입 확대가 집중형 DSO 플랫폼에 기회를 가져다줌), 그리고 과제(인건비 상승, 상환 압력, 진료소 수준의 이익률 압박 속에서 수익성 유지)
- 시장 침투율 : 본 보고서에는 전 세계 치과 서비스 조직(DSO) 시장에서 주요 기업이 제공하는 제품에 대한 상세한 정보가 포함되어 있습니다. 본 보고서는 서비스 유형별, 최종사용자, 지역 등의 부문을 포괄하고 있습니다.
- 제품 강화 및 혁신 : 전 세계 치과 서비스 조직(DSO) 시장의 신제품 출시 및 예상되는 동향에 대한 종합적인 세부 정보
- 시장 개발 : 서비스 유형별, 최종사용자별, 지역별로 수익성이 높은 성장 시장에 대한 상세한 인사이트와 분석을 제공합니다.
- 시장 다각화 : 전 세계 치과 서비스 조직 시장에서 신제품 출시, 시장 확대, 최신 동향 및 투자에 관한 종합적인 정보.
- 경쟁 평가 : 전 세계 치과 서비스 조직 시장에서 주요 경쟁사의 시장 점유율, 성장 전략, 제품 라인업 및 역량에 대한 종합적인 평가.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제6장 규제 상황
제7장 업계 동향
제8장 고객 상황과 구매 행동
제9장 치과 서비스 조직 시장(서비스 유형별)
제10장 치과 서비스 조직 시장(최종사용자별)
제11장 치과 서비스 조직 시장(지역별)
제12장 경쟁 구도
제13장 기업 개요
제14장 조사 방법
제15장 부록
KSM 26.09.29The dental service organization market is projected to reach USD 303.32 billion by 2031 from USD 199.88 billion in 2026, at a CAGR of 8.7% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | By service type, end user, and region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa (GCC Countries, Rest of Middle East & Africa) |
The global dental service organization market is largely driven by the growing affiliation of dentists with dental service organizations, rising administrative complexity, and staffing challenges across independent dental practices. Increasing demand for dental care, rising dental care expenditures, and the expansion of the addressable dental care market have significantly increased the need for efficient practice management and centralized business support services. Dental service organizations provide a broad range of non-clinical services, including human resources, marketing and branding, accounting, medical supplies procurement, and administrative support, enabling affiliated dentists to reduce operational burdens and focus on patient care.
Advancements in dental technology and the growing adoption of digital dentistry, artificial intelligence, cloud-based practice management systems, electronic health records, and digital imaging have further strengthened the role of dental service organizations in improving practice efficiency. These technologies enable dental service organizations to standardize administrative processes, enhance patient engagement, optimize scheduling and billing, and improve coordination among affiliated dental practices. Furthermore, the growing need for centralized procurement and economies of scale has encouraged dental practices to affiliate with dental service organizations to reduce operating costs and improve resource utilization.
Additionally, raising dentists' awareness of the benefits of affiliation, including access to administrative expertise, workforce management, technology infrastructure, marketing support, and negotiated procurement arrangements, has positively influenced market growth. The expansion of dental practice networks, the consolidation of the fragmented dental services industry, and growing investments in dental practices have further supported the adoption of dental service organization models. The combination of rising demand for dental care, increasing operational challenges, technological advancements, and the growing need for efficient practice management is driving the global expansion of the dental service organization market.
"By service type, human resources held the largest market share in the global dental service organization market in 2025".
This dominance stems from the rising staffing challenges faced by dental practices and the growing need for centralized workforce management. Human resource services provided by dental service organizations include recruitment, employee onboarding, payroll and benefits administration, workforce planning, training, and employee retention, enabling affiliated dental practices to manage their workforce efficiently while reducing administrative burdens. The growing affiliation of dentists with dental service organizations has further accelerated demand for centralized human resource services. As dental service organizations expand their networks through practice affiliations and acquisitions, the need to recruit, manage, and retain dentists, dental hygienists, dental assistants, and administrative staff across multiple locations has increased. Additionally, growing competition for qualified dental professionals and rising labor costs have encouraged dental practices to leverage the workforce management capabilities of dental service organizations. These factors, combined with the increasing administrative complexity of dental practices and the need to improve operational efficiency, have contributed to the leading position of the Human Resources segment in the global dental service organization market.
"By end user, oral surgeons held the largest share in the global dental service organization market in 2025"
The dominance of this segment is largely due to the high resource requirements of oral and maxillofacial practices, including specialized personnel, surgical facilities, equipment, and patient coordination. These practices often handle referrals for advanced dental and facial procedures, which increase operational and administrative demands. DSOs can address these needs through centralized purchasing, staffing, financial management, scheduling, and technology support. The ability to consolidate these functions across affiliated practices makes the DSO model particularly attractive to oral and maxillofacial practices.
"The US is expected to grow at the highest CAGR in the North American dental service organization market during the forecast period."
The US is expected to post the highest CAGR in the North American dental service organization market over the forecast period. This growth is driven by several key factors, including the increasing affiliation of dentists with dental service organizations, rising administrative complexity, and growing staffing challenges across dental practices. The country's large, highly developed dental care market, rising dental care expenditures, and the strong presence of established dental service organizations further support market expansion. Additionally, the growing consolidation of independent dental practices and the increasing adoption of centralized practice management, human resources, marketing, accounting, and procurement services are accelerating demand for dental service organization models across the US. Furthermore, the growing use of digital dentistry, artificial intelligence, cloud-based practice management systems, and other technology-enabled solutions is improving operational efficiency and supporting the expansion of dental service organization networks. The growing need among dentists to reduce administrative workloads, access centralized business support, achieve economies of scale, and address workforce shortages is driving increased affiliation with dental service organizations. Collectively, these factors position the US as the leading and fastest-growing market for dental service organizations in North America.
A breakdown of the primary participants (on the supply side) in the dental service organization market referenced in this report is provided below:
- By Company Type: Tier 1 (35%), Tier 2 (40%), and Tier 3 (25%)
- By Designation: C-level Executives (45%), Directors (35%), and Others (20%)
- By Region: North America (27%), Europe (25%), Asia Pacific (30%), Latin America (8%), and the Middle East & Africa (10%)
The leading players in the global dental service organization market include Heartland Dental (US), The Aspen Group - TAG (US), Q and M Dental Group (Singapore), and PDS Health (US).
Research Coverage:
The report analyzes the dental service organization market, estimating its size and future growth potential across segments by service type, end user, and region. Additionally, the report features a competitive analysis of key players in the market, including their company profiles, product offerings, recent developments, and key market strategies.
Reasons to Buy the Report
The report provides valuable insights for both market leaders and new entrants in the dental service organization market, offering the most accurate revenue estimates. It helps stakeholders understand the competitive landscape, enabling them to better position their businesses and develop effective go-to-market strategies. Additionally, the report highlights key market drivers, restraints, challenges, and opportunities, giving stakeholders a comprehensive understanding of current market trends.
This report provides insights into the following pointers:
- Analysis of key drivers (increasing affiliation of dentists with dental service organizations, rising administrative complexity and staffing challenges in dental practices, growing dental care expenditure and expansion of the addressable dental care market), restraints (regulatory restrictions and state-level variations in DSO ownership, concerns regarding clinical autonomy and dentist control), opportunities (impact of DSOs on dental industry, Increasing Adoption of AI and digital technologies creates opportunities for centralized DSO platforms), and challenges (maintaining profitability amid rising labor costs, reimbursement pressure, and practice-level margin compression)
- Market Penetration: It includes extensive information on the products offered by the major players in the global dental service organization market. The report covers segments such as service type, end user, and region.
- Product Enhancement/Innovation: Comprehensive details about new product launches and anticipated trends in the global dental service organization market
- Market Development: Thorough knowledge and analysis of the profitable rising markets by service type, end user, and region
- Market Diversification: Comprehensive information about newly launched products, expanding markets, current advancements, and investments in the global dental service organization market.
- Competitive Assessment: A comprehensive assessment of market shares, growth strategies, product offerings, and capabilities of key competitors in the global dental service organization market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.4 YEARS CONSIDERED
- 1.5 CURRENCY CONSIDERED
- 1.6 KEY STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND DEVELOPMENTS
- 2.2 DISRUPTIVE TRENDS SHAPING MARKET
- 2.3 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.4 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN DENTAL SERVICE ORGANIZATION MARKET
- 3.2 ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE AND COUNTRY
- 3.3 DENTAL SERVICE ORGANIZATION MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.4 REGIONAL MIX: DENTAL SERVICE ORGANIZATION MARKET (2024-2031)
- 3.5 DENTAL SERVICE ORGANIZATION MARKET: DEVELOPED VS. DEVELOPING MARKETS
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing affiliation of dentists with dental service organizations
- 4.2.1.2 Rising administrative complexity and staffing challenges in dental practices
- 4.2.1.3 Growing dental care expenditure and expansion of addressable dental care market
- 4.2.2 RESTRAINTS
- 4.2.2.1 Regulatory restrictions and state-level variations in DSO ownership
- 4.2.2.2 Concerns regarding clinical autonomy and dentist control
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Impact of DSOs on dental industry
- 4.2.3.2 Increasing adoption of AI and digital technologies creates opportunities for centralized DSO platforms
- 4.2.4 CHALLENGES
- 4.2.4.1 Maintaining profitability amid rising labor costs, reimbursement pressure, and practice-level margin compression
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER- 1/2/3 PLAYERS
5 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 5.1 KEY EMERGING TECHNOLOGIES
- 5.1.1 ARTIFICIAL INTELLIGENCE (AI)-ENABLED PRACTICE MANAGEMENT & PREDICTIVE ANALYTICS
- 5.1.2 AI-ENABLED REVENUE CYCLE & ADMINISTRATIVE AUTOMATION
- 5.2 COMPLEMENTARY TECHNOLOGIES
- 5.2.1 DIGITAL IMAGING & INTRAORAL SCANNING TECHNOLOGIES
- 5.3 ADJACENT TECHNOLOGIES
- 5.3.1 3D PRINTING & DIGITAL MANUFACTURING TECHNOLOGIES
- 5.3.2 TELEDENTISTRY & REMOTE PATIENT MONITORING
- 5.4 TECHNOLOGY/PRODUCT ROADMAP
- 5.4.1 SHORT-TERM | RECENT TECHNOLOGIES | FOUNDATION & EARLY COMMERCIALIZATION
- 5.4.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 5.4.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 5.5 PATENT ANALYSIS
- 5.5.1 PATENT PUBLICATION TRENDS FOR DENTAL SERVICE ORGANIZATION
- 5.5.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 5.6 IMPACT OF AI/GEN AI ON DENTAL SERVICE ORGANIZATION MARKET
- 5.6.1 TOP USE CASES AND MARKET POTENTIAL
- 5.6.2 INTERCONNECTED ADJACENT ECOSYSTEMS AND IMPACT ON MARKET PLAYERS
- 5.6.3 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN DENTAL SERVICE ORGANIZATION MARKET
- 5.7 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 5.7.1 HEARTLAND DENTAL: AI-ENABLED CLINICAL WORKFLOW
- 5.7.2 DENTAL CARE ALLIANCE: STANDARDIZED DIGITAL PREVENTIVE CARE WORKFLOW
- 5.7.3 PDS HEALTH: SCALED DIGITAL DENTISTRY & SAME-DAY RESTORATIVE WORKFLOW
6 REGULATORY LANDSCAPE
- 6.1 REGIONAL REGULATIONS AND COMPLIANCE
- 6.1.1 US
- 6.1.2 EUROPEAN UNION
- 6.1.3 CHINA
- 6.1.4 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 6.2 SUSTAINABILITY INITIATIVES
- 6.2.1 ENVIRONMENTAL SUSTAINABILITY IN DENTAL SERVICE ORGANIZATIONS
- 6.2.2 DIGITAL-EFFICIENT DSO INFRASTRUCTURE
- 6.2.3 CIRCULAR ECONOMY AND SUSTAINABLE PROCUREMENT IN DSO OPERATIONS
- 6.2.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
7 INDUSTRY TRENDS
- 7.1 PORTER'S FIVE FORCES ANALYSIS
- 7.1.1 THREAT FROM NEW ENTRANTS
- 7.1.2 THREAT FROM SUBSTITUTES
- 7.1.3 BARGAINING POWER OF SUPPLIERS
- 7.1.4 BARGAINING POWER OF BUYERS
- 7.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 7.2 MACROECONOMIC OUTLOOK
- 7.2.1 INTRODUCTION
- 7.2.2 GDP TRENDS AND FORECAST
- 7.2.3 TRENDS IN DENTAL SERVICE ORGANIZATION MARKET
- 7.3 VALUE CHAIN ANALYSIS
- 7.4 ECOSYSTEM ANALYSIS
- 7.5 SUPPLY CHAIN ANALYSIS
- 7.6 PRICING ANALYSIS
- 7.6.1 AVERAGE SYSTEM COST - DENTAL SERVICE ORGANIZATION (DSO)
- 7.6.2 AVERAGE COST RANGE OF DENTAL SERVICE ORGANIZATION (DSO), BY REGION, 2023-2025 (USD)
- 7.6.3 AVERAGE SELLING PRICE OF DENTAL SERVICE ORGANIZATION, BY KEY PLAYERS, 2023-2025
- 7.7 KEY CONFERENCES & EVENTS, 2026-2027
- 7.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 7.9 INVESTMENT & FUNDING SCENARIO
- 7.10 CASE STUDY ANALYSIS
- 7.11 IMPACT OF 2025 US TARIFF - OVERVIEW
- 7.11.1 INTRODUCTION
- 7.11.2 KEY TARIFF RATES
- 7.11.3 PRICE IMPACT ANALYSIS
- 7.11.4 IMPACT ON REGION
- 7.11.4.1 US
- 7.11.4.2 Europe
- 7.11.4.3 Asia Pacific
- 7.11.5 IMPACT ON END-USE INDUSTRIES
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 INFLUENCE OF KEY STAKEHOLDERS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
9 DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE
- 9.1 INTRODUCTION
- 9.2 HUMAN RESOURCES
- 9.2.1 RISING DENTAL WORKFORCE REQUIREMENTS STRENGTHENING DEMAND FOR CENTRALIZED HUMAN RESOURCE SERVICES
- 9.3 MARKETING & BRANDING
- 9.3.1 GROWING DENTAL SERVICE SPENDING AND INCREASING COMPETITION STRENGTHENING DEMAND
- 9.4 ACCOUNTING
- 9.4.1 INCREASING FINANCIAL COMPLEXITY ACROSS DENTAL PRACTICES FUELING DEMAND FOR CENTRALIZED ACCOUNTING SERVICES
- 9.5 MEDICAL SUPPLIES PROCUREMENT
- 9.5.1 CENTRALIZED PROCUREMENT AND GROWING DENTAL SERVICE ACTIVITY STRENGTHENING DEMAND
- 9.6 OTHERS
- 9.6.1 INCREASING DIGITALIZATION AND WORKFORCE DEVELOPMENT TO SUPPORT MARKET GROWTH
- 9.7 DSO SCALE DRIVEN BY BOTH PRACTICE FOOTPRINT AND DENTIST NETWORK DEPTH
10 DENTAL SERVICE ORGANIZATION MARKET, BY END USER
- 10.1 INTRODUCTION
- 10.2 ORAL SURGEONS
- 10.2.1 GROWING DEMAND FOR COMPLEX DENTAL PROCEDURES STRENGTHENS ORAL SURGEONS' AFFILIATION WITH DSOS
- 10.3 ENDODONTISTS
- 10.3.1 RISING DEMAND FOR SPECIALIZED ROOT CANAL CARE SUPPORTING MARKET GROWTH
- 10.4 OTHER DENTAL SPECIALISTS
- 10.4.1 GROWING DEMAND FOR SPECIALIZED DENTAL CARE INCREASING DSO AFFILIATION ACROSS KEY DENTAL SPECIALTIES
11 DENTAL SERVICE ORGANIZATION MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 EUROPE
- 11.2.1 GERMANY
- 11.2.1.1 Expanding dental practice scale and rising operating costs creating opportunities for DSO Expansion
- 11.2.2 ITALY
- 11.2.2.1 Large private dental provider base and growing healthcare expenditure to support market growth
- 11.2.3 SPAIN
- 11.2.3.1 Large private dental workforce and high out-of-pocket dental spending create opportunities for market players
- 11.2.4 FRANCE
- 11.2.4.1 High dental care spending and established private practice base to propel market growth
- 11.2.5 UK
- 11.2.5.1 Large dental workforce and rising healthcare expenditure to support growth
- 11.2.6 REST OF EUROPE
- 11.2.1 GERMANY
- 11.3 NORTH AMERICA
- 11.3.1 US
- 11.3.1.1 Dentist affiliation, workforce challenges, and rising dental spending to drive market
- 11.3.2 CANADA
- 11.3.2.1 Expanding dental coverage to drive market growth
- 11.3.1 US
- 11.4 ASIA PACIFIC
- 11.4.1 SOUTH KOREA
- 11.4.1.1 Rising dental care demand to support market growth
- 11.4.2 JAPAN
- 11.4.2.1 Rising dental care needs and workforce pressures to support market growth
- 11.4.3 CHINA
- 11.4.3.1 Expanding dental care access to propel market growth
- 11.4.4 INDIA
- 11.4.4.1 Expanding dental care access to support market expansion
- 11.4.5 AUSTRALIA
- 11.4.5.1 Rising dental care demand to drive market growth
- 11.4.6 REST OF ASIA PACIFIC
- 11.4.1 SOUTH KOREA
- 11.5 LATIN AMERICA
- 11.5.1 BRAZIL
- 11.5.1.1 Expanding oral healthcare infrastructure to favor market growth
- 11.5.2 MEXICO
- 11.5.2.1 Expanding oral healthcare access to fuel market
- 11.5.3 REST OF LATIN AMERICA
- 11.5.1 BRAZIL
- 11.6 MIDDLE EAST & AFRICA
- 11.6.1 RISING HEALTHCARE INVESTMENTS TO AID MARKET GROWTH
- 11.7 GCC COUNTRIES
- 11.7.1 PRIVATE HEALTHCARE EXPANSION TO SUPPORT MARKET GROWTH
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 12.3 DENTAL SERVICE ORGANIZATION MARKET SHARE ANALYSIS, BY NUMBER OF PRACTICES
- 12.4 BRAND/PRODUCT COMPARISON
- 12.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.5.1 STARS
- 12.5.2 EMERGING LEADERS
- 12.5.3 PERVASIVE PLAYERS
- 12.5.4 PARTICIPANTS
- 12.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.5.5.1 Company footprint
- 12.5.5.2 Region footprint
- 12.5.5.3 Service type footprint
- 12.5.5.4 End user footprint
- 12.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES (2025)
- 12.6.1 PROGRESSIVE COMPANIES
- 12.6.2 RESPONSIVE COMPANIES
- 12.6.3 DYNAMIC COMPANIES
- 12.6.4 STARTING BLOCKS
- 12.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.6.5.1 Detailed list of key startups/SMEs
- 12.6.5.2 Dental service organization market: Competitive benchmarking of key startups/SMEs
- 12.7 COMPETITIVE SCENARIO
- 12.7.1 SERVICE LAUNCHES AND APPROVALS
- 12.7.2 DEALS
- 12.7.3 EXPANSIONS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 HEARTLAND DENTAL
- 13.1.1.1 Business overview
- 13.1.1.2 Services offered
- 13.1.1.3 Recent developments
- 13.1.1.3.1 Product launches & approvals
- 13.1.1.3.2 Deals
- 13.1.1.3.3 Expansions
- 13.1.1.4 MnM view
- 13.1.1.4.1 Right to win
- 13.1.1.4.2 Strategic choices
- 13.1.1.4.3 Weaknesses and competitive threats
- 13.1.2 THE ASPEN GROUP - TAG
- 13.1.2.1 Business overview
- 13.1.2.2 Services offered
- 13.1.2.3 Recent developments
- 13.1.2.3.1 Service launches & approvals
- 13.1.2.3.2 Deals
- 13.1.2.3.3 Expansions
- 13.1.2.4 MnM view
- 13.1.2.4.1 Right to win
- 13.1.2.4.2 Strategic choices
- 13.1.2.4.3 Weaknesses and competitive threats
- 13.1.3 PDS HEALTH
- 13.1.3.1 Business overview
- 13.1.3.2 Services offered
- 13.1.3.3 Recent developments
- 13.1.3.3.1 Product launches & approvals
- 13.1.3.3.2 Deals
- 13.1.3.3.3 Expansions
- 13.1.3.4 MnM view
- 13.1.3.4.1 Right to win
- 13.1.3.4.2 Strategic choices
- 13.1.3.4.3 Weaknesses and competitive threats
- 13.1.4 MB2 DENTAL
- 13.1.4.1 Business overview
- 13.1.4.2 Services offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Service launches & approvals
- 13.1.4.3.2 Deals
- 13.1.4.4 MnM view
- 13.1.4.4.1 Right to win
- 13.1.4.4.2 Strategic choices
- 13.1.4.4.3 Weaknesses and competitive threats
- 13.1.5 SMILE BRANDS INC.
- 13.1.5.1 Business overview
- 13.1.5.2 Services offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Deals
- 13.1.5.4 MnM view
- 13.1.5.4.1 Right to win
- 13.1.5.4.2 Strategic choices
- 13.1.5.4.3 Weaknesses and competitive threats
- 13.1.6 Q & M DENTAL GROUP
- 13.1.6.1 Business overview
- 13.1.6.2 Services offered
- 13.1.6.3 Recent developments
- 13.1.6.3.1 Service launches & approvals
- 13.1.6.3.2 Deals
- 13.1.7 COLOSSEUM DENTAL GROUP
- 13.1.7.1 Business overview
- 13.1.7.2 Products offered
- 13.1.7.3 Recent developments
- 13.1.7.3.1 Deals
- 13.1.8 AFFORDABLE CARE
- 13.1.8.1 Business overview
- 13.1.8.2 Services offered
- 13.1.8.3 Recent developments
- 13.1.8.3.1 Expansions
- 13.1.9 DENTAL CARE ALLIANCE
- 13.1.9.1 Business overview
- 13.1.9.2 Services offered
- 13.1.9.3 Recent developments
- 13.1.9.3.1 Service launches & approvals
- 13.1.9.3.2 Deals
- 13.1.9.3.3 Expansions
- 13.1.10 SGA DENTAL PARTNERS
- 13.1.10.1 Business overview
- 13.1.10.2 Services offered
- 13.1.10.3 Recent developments
- 13.1.10.3.1 Deals
- 13.1.1 HEARTLAND DENTAL
- 13.2 OTHER PLAYERS
- 13.2.1 NORTH AMERICAN DENTAL GROUP
- 13.2.2 SPECIALTY DENTAL BRANDS
- 13.2.3 U.S. ORAL SURGERY MANAGEMENT
- 13.2.4 SPECIALTY1 PARTNERS
- 13.2.5 D4C DENTAL BRANDS
- 13.2.6 GREAT EXPRESSIONS DENTAL CENTERS
- 13.2.7 SONRAVA HEALTH
- 13.2.8 SAGE DENTAL
- 13.2.9 MORTENSON DENTAL PARTNERS
- 13.2.10 DENTAL365/PREMIER CARE DENTAL MANAGEMENT
- 13.2.11 GUARDIAN DENTISTRY PARTNERS
- 13.2.12 PEPPERPOINTE PARTNERSHIPS
- 13.2.13 42 NORTH DENTAL
- 13.2.14 ROCK DENTAL BRANDS
- 13.2.15 BENEVIS
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH APPROACH
- 14.1.1 SECONDARY DATA
- 14.1.1.1 Key data from secondary sources
- 14.1.2 PRIMARY DATA
- 14.1.2.1 Key data from primary sources
- 14.1.2.2 Key industry insights
- 14.1.1 SECONDARY DATA
- 14.2 MARKET SIZE ESTIMATION
- 14.3 MARKET BREAKDOWN AND DATA TRIANGULATION
- 14.4 MARKET SHARE ESTIMATION
- 14.5 ASSUMPTIONS
- 14.6 LIMITATIONS
- 14.6.1 METHODOLOGY-RELATED LIMITATIONS
- 14.6.2 SCOPE-RELATED LIMITATIONS
- 14.7 RISK ASSESSMENT
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS


