
|
시장보고서
상품코드
2132652
치과용 봉합사 시장 : 유형별, 소재별, 필라멘트 유형별, 용도별, 최종사용자별, 지역별 - 세계 예측(-2031년)Dental Sutures Market by Type (Absorbable, Non-absorbable), Material (Synthetic (Polyglactin 910, PGA, PTFE, Nylon), Natural), Filament Type (Monofilament, Multifilament), & End User (Dental Clinics, Hospitals & ASCs) - Global Forecast to 2031 |
||||||

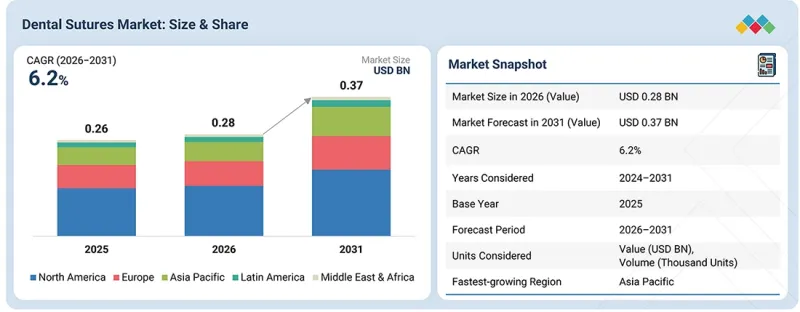
세계의 치과용 봉합사 시장 규모는 2026년 2억 8,000만 달러에서 2031년까지 3억 7,000만 달러에 달할 것으로 예측되며, CAGR은 6.2%가 될 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 유형별, 소재별, 필라멘트 유형별, 용도별, 최종사용자별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
구강 위생 불량, 흡연, 불건강한 식습관, 당뇨병 유병률 증가와 같은 생활 습관 관련 요인에 더해 고령화가 진행되면서 치주질환, 치아 상실 및 외과적 처치가 필요한 기타 구강 질환의 부담이 증가하고 있습니다. 그 결과, 발치, 치주 외과 수술, 치과 임플란트 식립, 골 이식, 기타 구강·악안면 수술을 포함한 치과 시술 건수가 증가하고 있으며, 이는 효과적인 상처 봉합과 수술 후 치유를 목적으로 하는 치과용 봉합사의 수요를 견인하고 있습니다. 치과용 봉합사 시장은 치과 임플란트의 보급 확대, 구강 보건에 대한 인식 제고, 치과 관광의 성장, 그리고 신흥 경제국에서의 치과 치료 접근성 개선에 힘입어 더욱 성장하고 있습니다. 또한, 합성 흡수성 봉합사, 모노필라멘트 소재, 항균 코팅, 비외상성 바늘 및 봉합사의 조합과 같은 기술적 진보로 인해 취급이 용이해지고 조직 반응이 완화되며 더 우수한 임상 결과를 얻을 수 있게 됨에 따라, 치과 및 구강외과 센터에서의 채택이 촉진되고 있습니다.
“2025년 시점에서 유형별로 살펴보면, 비흡수성 치과용 봉합사 부문이 치과용 봉합사 시장에서 가장 큰 점유율을 차지했습니다.”
유형별로 보면 치과용 봉합사 시장은 흡수성 및 비흡수성 치과용 봉합사로 분류됩니다. 2025년에는 비흡수성 치과용 봉합사가 시장에서 가장 큰 점유율을 차지했습니다. 이는 주로 구강외과 수술에서 상처의 지지 기간을 보다 세밀하게 조절할 수 있기 때문입니다. 임상적으로 제거될 때까지 인장 강도를 유지할 수 있으므로, 초기 치유 기간 동안 상처의 안정화가 극히 중요한 임플란트 수술, 치주 플랩 수술, 치조골 증대술 및 골이식술에 특히 적합합니다. 또한, 비흡수성 봉합사를 사용하면 치과 의료진은 봉합사 제거 시 수술 부위를 평가할 수 있어, 수술 후 상처 모니터링에 도움이 됩니다. 비단, 나일론, 폴리프로필렌, PTFE 등 일반적으로 사용되는 소재가 계속해서 선호되고 있는 점도 치과 및 악안면 외과 수술에서 비흡수성 봉합사의 확고한 위상을 더욱 뒷받침하고 있습니다.
“2025년에는 소재별로 볼 때, 합성 치과용 봉합사 부문이 가장 큰 시장 점유율을 차지했습니다.”
소재별로 보면 치과용 봉합사 시장은 합성계와 천연계 치과용 봉합사로 분류됩니다. 합성 치과용 봉합사는 제어된 제조 특성, 낮은 편차, 그리고 광범위한 흡수성 및 비흡수성 제형에서의 입수 가능성을 바탕으로 2025년에 가장 큰 시장 점유율을 차지했습니다. 천연 소재와 비교하여 합성 봉합사는 보다 예측 가능한 인장 강도 유지, 제어된 분해 특성 및 조직 반응성 감소를 제공할 수 있으며, 이는 민감한 구강 조직을 다루는 시술에서 중요한 고려 사항이 됩니다. PGA, 폴리글리콜라이드 910, PDO, 폴리프로필렌, 나일론,PTFE 등의 소재는 치주 치료, 임플란트, 재생 치료, 구강 외과 수술에서 점점 더 널리 사용되고 있습니다. 치과 외과 의사들 사이에서 첨단 모노필라멘트 및 합성 흡수성 봉합사에 대한 선호도가 높아지고 있는 점도 이 부문의 채택을 촉진하고 있습니다.
“2025년에는 지역별 기준으로 북미가 가장 큰 시장 점유율을 차지했습니다.”
지역별로 보면 치과용 봉합사 시장은 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카로 구분됩니다. 2025년에는 치과 임플란트, 치주 치료, 발치 및 구강 재건 수술의 시술 건수가 비교적 많은 것을 배경으로 북미가 가장 큰 시장 점유율을 차지했습니다. 이 지역에는 다수의 치과의사 및 치과 전문의가 있으며, 첨단 외과 수술 기술의 도입이 활발히 이루어지고 있을 뿐만 아니라, 임플란트 치료 및 치주 외과에서 사용되는 고품질 봉합사에 대한 접근성도 널리 보급되어 있습니다. 고령화의 진전도 수요를 뒷받침하고 있으며, 치주질환 및 치아 상실이라는 지속적인 과제와, 수복 치료의 대안으로서 치과 임플란트 이용 확대가 주요 요인으로 작용하고 있습니다. 또한, 유서 깊은 치과 제품 제조업체의 존재, 잘 구축된 유통망, 그리고 기술적으로 선진적인 치과용 소모품의 보급이 확대되고 있는 점도 세계 치과용 봉합사 시장에서 북미의 위상을 지속적으로 뒷받침하고 있습니다.
치과용 봉합사 시장에서 사업을 전개하는 주요 기업으로는 Johnson & Johnson(미국), B. Braun SE(독일), Advanced Medical Solutions Group plc(영국), DemeTECH Corporation(미국), Hu-Friedy Mfg. Co., LLC(미국), Envista(미국), Corza Medical(미국), SMI AG(벨기에), Henry Schein(미국), Futura Surgicare Pvt. Ltd.(인도), MANI, INC.(일본), Young Innovations, Inc.(미국), Assut Europ(이탈리아), KATSAN Katgut Sanayi ve Tic. A.S.(튀르키예), Dogsan TIbbi Malzeme Sanayi A.S.(튀르키예), HYGITECH(프랑스), ZimVie Inc.(미국), MEDIPAC SA(그리스), Lux Sutures(프랑스), Bentley Healthcare Pvt. Ltd.(인도), Boz Medical(튀르키예), Golnit(우크라이나), GDT Dental Implants(이스라엘), DSI LTD(이스라엘), 및 Qubix Medicare Private Limited(인도)입니다.
조사 범위
본 보고서에서는 치과용 봉합사 시장을 유형, 필라멘트 유형, 소재, 최종사용자 및 지역별로 조사하고 있습니다. 또한 시장 성장에 영향을 미치는 요인(촉진요인, 제약요인, 기회, 과제 등)에 대해서도 분석하고 있습니다. 이해관계자들에게 시장 내 기회와 과제를 평가함과 동시에, 시장을 선도하는 기업들에 대한 상세한 경쟁 구도를 제공합니다. 또한, 본 보고서에서는 각 마이크로 시장의 성장 동향, 전망 및 치과용 봉합사 시장 전체에 대한 기여도에 대해서도 조사하고 있습니다. 더불어, 5개 주요 지역별 시장 세분화에 따른 매출 예측도 수록하고 있습니다.
본 보고서를 구매해야 하는 이유
본 보고서는 치과용 봉합사 시장 전체 및 각 하위 부문의 매출에 대한 가장 정확한 추정치를 제공함으로써, 이 시장의 시장 선도 기업과 신규 진입 기업을 지원합니다. 또한 이해관계자가 경쟁 구도를 이해하고, 비즈니스 위치를 최적화하며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻는 데 도움이 됩니다. 더불어 본 보고서는 이해관계자가 시장 동향을 파악할 수 있도록 지원하며, 주요 시장 촉진요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인(치과 치료를 받는 환자 수 증가, 첨단 심미 치과 시술에 대한 수요 증가, 치과 의료 인프라 및 전문 진료소의 확대), 제약요인(비흡수성 봉합사의 경우 수술 후 제거 및 경과 관찰의 필요성, 기존 치과용 봉합사의 가격 압박 및 상품화), 과제(숙련된 치과 의료 인력 부족), 그리고 기회(치과 서비스 조직의 지속적인 확대, 치과 관광 활동 활성화) 등, 치과용 봉합사 시장의 성장에 기여하는 요인에 대한 인사이트를 제공합니다.
- 제품 개발 및 혁신 : 치과용 봉합사 시장의 향후 동향 및 연구 개발 활동에 대한 상세한 인사이트
- 시장 개발 : 유형, 필라멘트 유형, 소재, 최종사용자, 지역별로 본 수익성 높은 신흥 시장에 대한 종합적인 정보
- 시장 다각화 : 치과용 봉합사 시장의 성장 지역, 최근 동향 및 투자에 관한 종합적인 정보
- 경쟁 분석 : 세계 치과용 봉합사 시장의 주요 기업별 시장 점유율, 성장 전략, 제품 라인업, 기업 평가 쿼드런트 및 역량에 대한 상세한 분석
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI에 의한 영향, 특허, 혁신
제7장 규제 상황
제8장 고객 상황과 구매 행동
제9장 치과용 봉합사 시장(유형별)
제10장 치과용 봉합사 시장(소재별)
제11장 치과용 봉합사 시장(필라멘트 유형별)
제12장 치과용 봉합사 시장(용도별)
제13장 치과용 봉합사 시장(최종사용자별)
제14장 치과용 봉합사 시장(지역별)
제15장 경쟁 구도
제16장 기업 개요
제17장 조사 방법
제18장 부록
KSM 26.09.29The global dental sutures market size is projected to reach USD 0.37 billion by 2031 from USD 0.28 billion in 2026, at a CAGR of 6.2%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | By Type, Material, Filament type, End User, and Region |
| Regions covered | North America, Europe, APAC, LATAM, MEA |
Lifestyle-related factors, including poor oral hygiene, tobacco consumption, unhealthy dietary habits, and the growing prevalence of diabetes, together with an aging population, are contributing to a higher burden of periodontal diseases, tooth loss, and other oral conditions that often require surgical intervention. Consequently, the increasing number of dental procedures, including tooth extractions, periodontal surgeries, dental implant placement, bone grafting, and other oral and maxillofacial procedures, is driving the demand for dental sutures for effective wound closure and post-operative healing. The dental sutures market is further supported by the rising adoption of dental implants, increasing awareness regarding oral healthcare, growth in dental tourism, and improving access to dental treatment in emerging economies. In addition, technological advancements such as synthetic absorbable sutures, monofilament materials, antibacterial coatings, and atraumatic needle-suture combinations are improving handling, reducing tissue reaction, and supporting better clinical outcomes, thereby encouraging their adoption across dental clinics and oral surgery centers.
"The Non-absorbable dental sutures segment accounted for the largest share of the dental sutures market, by type, in 2025."
By type, the dental sutures market is categorized into absorbable and non-absorbable dental sutures. Non-absorbable dental sutures held the largest share of the market in 2025, primarily due to the greater control they provide over the duration of wound support in oral surgical procedures. Their ability to maintain tensile strength until clinical removal makes them particularly suitable for implant surgery, periodontal flap procedures, ridge augmentation, and bone grafting, where wound stabilization is critical during the initial healing period. In addition, non-absorbable sutures allow dental professionals to assess the surgical site at the time of suture removal, which can support post-operative wound monitoring. The continued preference for commonly used materials such as silk, nylon, polypropylene, and PTFE further contributes to their strong position in dental and maxillofacial procedures.
"The synthetic dental sutures segment accounted for the largest market share, by material, in 2025."
By material, the dental sutures market is divided into synthetic and natural dental sutures. Synthetic dental sutures accounted for the largest market share in 2025, supported by their controlled manufacturing characteristics, lower variability, and availability across a broad range of absorbable and non-absorbable formulations. Compared to natural materials, synthetic sutures can offer more predictable tensile-strength retention, controlled degradation characteristics, and reduced tissue reactivity, which are important considerations in procedures involving sensitive oral tissues. Materials such as PGA, polyglycolide 910, PDO, polypropylene, nylon, and PTFE are increasingly utilized across periodontal, implant, regenerative, and oral surgical procedures. The growing preference for advanced monofilament and synthetic absorbable sutures among dental surgeons is also strengthening the adoption of this segment.
"North America accounted for the largest market share, by region, in 2025."
Geographically, the dental sutures market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America accounted for the largest market share in 2025, driven by a comparatively high volume of dental implant, periodontal, extraction, and reconstructive oral procedures. The region has a large base of dentists and dental specialists, strong adoption of advanced surgical techniques, and widespread access to premium suture materials used in implantology and periodontal surgery. The increasing elderly population also supports demand, the continuing burden of periodontal disease and tooth loss, and the growing use of dental implants as a restorative treatment option. In addition, the presence of established dental product manufacturers, well-developed distribution networks, and strong adoption of technologically advanced dental consumables continues to support the position of North America in the global dental sutures market.
The break-up of the profile of primary participants in the dental sutures market:
- By Company Type: Tier 1 - 40%, Tier 2 - 30%, and Tier 3 - 30%
- By Designation: C-level Executives - 27%, Directors - 18%, and Others - 55%
- By Region: North America - 51%, Europe - 21%, Asia Pacific - 18%, Latin America - 6%, and Middle East & Africa - 4%
The major players operating in the dental sutures market include Johnson & Johnson (US), B. Braun SE (Germany), Advanced Medical Solutions Group plc (UK), DemeTECH Corporation (US), Hu-Friedy Mfg. Co., LLC (US), Envista (US), Corza Medical (US), SMI AG (Belgium), Henry Schein (US), Futura Surgicare Pvt. Ltd. (India), MANI, INC. (Japan), Young Innovations, Inc. (US), Assut Europe (Italy), KATSAN Katgut Sanayi ve Tic. A.S. (Turkey), Dogsan TIbbi Malzeme Sanayi A.S. (Turkey), HYGITECH (France), ZimVie Inc. (US), MEDIPAC SA (Greece), Lux Sutures (France), Bentley Healthcare Pvt. Ltd. (India), Boz Medical (Turkey), Golnit (Ukraine), GDT Dental Implants (Israel), DSI LTD (Israel), and Qubix Medicare Private Limited (India).
Research Coverage
This report studies the dental sutures Market based on types, filament types, materials, end users, and regions. The report also analyzes factors (such as drivers, restraints, opportunities and challenges) affecting market growth. It evaluates the opportunities and challenges in the market for stakeholders and provides details of the competitive landscape for market leaders. The report also studies micro markets concerning their growth trends, prospects, and contributions to the total dental sutures Market. The report forecasts the revenue of the market segments in five major regions.
Reasons to Buy the Report
The report will help the market leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the overall dental sutures market and the subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
This report provides insights into the following pointers:
- Analysis of key drivers (Increasing patient pool for dental treatments, Rising demand for advanced cosmetic dental procedures, Expanding dental care infrastructure and specialist practices), restraints (Need for post-operative removal and follow-up for non-absorbable sutures, Pricing pressure and commoditization of conventional dental sutures), challenges (Dearth of trained dental practitioners), and opportunities (Continued expansion of dental service organizations, Rising dental tourism activity) contributing to the growth of the dental sutures market.
- Product Development/Innovation: Detailed insights on upcoming trends, research & development activities, in the dental sutures market
- Market Development: Comprehensive information on the lucrative emerging markets by types, filament types, materials, end users and region
- Market Diversification: Exhaustive information about the growing geographies, recent developments, and investments in the dental sutures market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, company evaluation quadrant, and capabilities of leading players in the global dental sutures market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED & REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY
- 1.5 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS & MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: INSIGHTS & DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET GROWTH
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 DENTAL SUTURES MARKET OVERVIEW
- 3.2 DENTAL SUTURES MARKET, BY REGION, 2026 VS. 2031 (USD MILLION)
- 3.3 ASIA PACIFIC: DENTAL SUTURES MARKET, BY END USER AND COUNTRY, 2025 (USD MILLION)
- 3.4 GEOGRAPHIC SNAPSHOT OF DENTAL SUTURES MARKET
- 3.5 DENTAL SUTURES MARKET: EMERGING VS. DEVELOPED MARKETS
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing patient pool for dental treatments
- 4.2.1.1.1 Geriatric population and edentulism
- 4.2.1.1.2 Periodontal diseases
- 4.2.1.1.3 Changing lifestyles and unhealthy food habits
- 4.2.1.2 Increasing adoption of periodontal plastic surgery and soft-tissue grafting procedures
- 4.2.1.3 Expanding dental care infrastructure and specialist practices
- 4.2.1.1 Increasing patient pool for dental treatments
- 4.2.2 RESTRAINTS
- 4.2.2.1 Need for post-operative removal and follow-up for non-absorbable sutures
- 4.2.2.2 Pricing pressure and commoditization of conventional dental sutures
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Continued growth of dental service organizations
- 4.2.3.2 Growing focus on emerging economies and rising disposable income levels
- 4.2.4 CHALLENGES
- 4.2.4.1 Shortage and uneven distribution of skilled dental professionals
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS & WHITE SPACES
- 4.3.1 UNMET NEEDS IN DENTAL SUTURES MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 BARGAINING POWER OF SUPPLIERS
- 5.1.5 THREAT OF SUBSTITUTES
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS & FORECAST
- 5.2.3 TRENDS IN SURGICAL SUTURES INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF DENTAL SUTURE PRODUCTS, BY KEY PLAYER, 2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF NON-ABSORBABLE DENTAL SUTURES, BY REGION, 2023-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), 2021-2025
- 5.6.2 EXPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), 2021-2025
- 5.7 KEY CONFERENCES & EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 CASE STUDY 1: STRATAFIX KNOTLESS BARBED PDS SUTURE REDUCES INTRAORAL CLOSURE TIME IN MAXILLOFACIAL SURGERY
- 5.9.2 CASE STUDY 2: B. BRAUN DAFILON(R) DEMONSTRATES SAFE AND EFFECTIVE MUCOSAL CLOSURE IN ROUTINE ORAL SURGERY.
- 5.9.3 CASE STUDY 3: SMI DACLON SHOWS LOWER BACTERIAL COLONIZATION AND MILDER TISSUE REACTION IN THIRD-MOLAR SURGERY
- 5.10 IMPACT OF 2025 US TARIFFS ON DENTAL SUTURES MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRIES/REGIONS
- 5.10.4.1 US
- 5.10.4.2 Europe
- 5.10.4.3 Asia Pacific
- 5.10.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 ANTIMICROBIAL & BIOACTIVE COATING TECHNOLOGIES
- 6.3 TECHNOLOGY/PRODUCT ROADMAP
- 6.3.1 SHORT-TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.3.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 6.3.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 6.4 PATENT ANALYSIS
- 6.4.1 PATENT PUBLICATION TRENDS FOR DENTAL SUTURES MARKET
- 6.4.2 TOP APPLICANTS (COMPANIES) OF DENTAL SUTURE PATENTS
- 6.4.3 JURISDICTION ANALYSIS: TOP APPLICANTS (COUNTRIES) FOR PATENTS IN DENTAL SUTURES MARKET
- 6.5 IMPACT OF AI/GEN AI ON DENTAL SUTURES MARKET
- 6.5.1 TOP USE CASES & MARKET POTENTIAL
- 6.5.2 INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS
- 6.6 SUCCESS STORIES & REAL-WORLD APPLICATIONS
- 6.6.1 ENVISTA/OSTEOGENICS: CYTOPLAST PTFE SUTURES - DENTAL-SPECIFIC MONOFILAMENT CLOSURE FOR BONE GRAFTING AND IMPLANT SURGERY
- 6.6.2 JOHNSON & JOHNSON MEDTECH/ETHICON: VICRYL RAPIDE - FAST-ABSORBING CLOSURE IN ORAL AND IMPLANT SURGERY
- 6.6.3 HUFRIEDYGROUP: PERMA SHARP SUTURES - DENTAL-SPECIFIC NEEDLE-SUTURE CONFIGURATIONS FOR PRECISE SOFT-TISSUE CLOSURE
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS & COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.1.2.1 North America
- 7.1.2.1.1 US
- 7.1.2.1.2 Canada
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.3.1 China
- 7.1.2.3.2 Japan
- 7.1.2.4 Latin America
- 7.1.2.4.1 Brazil
- 7.1.2.4.2 Mexico
- 7.1.2.5 Middle East
- 7.1.2.6 Africa
- 7.1.2.1 North America
- 7.2 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
- 7.2.1 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN DENTAL SUTURES MARKET
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 KEY BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 DENTAL SUTURES MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 ABSORBABLE DENTAL SUTURES
- 9.2.1 ELIMINATION OF POSTOPERATIVE SUTURE REMOVAL TO SUPPORT MARKET GROWTH
- 9.3 NON-ABSORBABLE DENTAL SUTURES
- 9.3.1 GROWING ADOPTION OF NON-ABSORBABLE SUTURES IN IMPLANT AND PERIODONTAL PROCEDURES TO DRIVE GROWTH
10 DENTAL SUTURES MARKET, BY MATERIAL
- 10.1 INTRODUCTION
- 10.2 SYNTHETIC DENTAL SUTURES
- 10.2.1 POLYGLACTIN 910 DENTAL SUTURES
- 10.2.1.1 Excellent handling characteristics and knot security of polyglactin 910 dental sutures to support adoption
- 10.2.2 POLYGLYCOLIC ACID (PGA) DENTAL SUTURES
- 10.2.2.1 Suitability of polyglycolic acid (PGA) dental sutures for broad range of routine and advanced dental procedures to fuel growth
- 10.2.3 POLYTETRAFLUOROETHYLENE (PTFE) DENTAL SUTURES
- 10.2.3.1 Advantages such as low bacterial retention and prolonged wound-support characteristics to drive demand for PTFE dental sutures
- 10.2.4 NYLON (POLYAMIDE) DENTAL SUTURES
- 10.2.4.1 High tensile strength and smooth tissue passage of nylon to drive demand in procedures requiring precise tissue approximation
- 10.2.5 OTHER SYNTHETIC DENTAL SUTURES
- 10.2.1 POLYGLACTIN 910 DENTAL SUTURES
- 10.3 NATURAL DENTAL SUTURES
- 10.3.1 SILK DENTAL SUTURES
- 10.3.1.1 Favorable handling characteristics, clinician familiarity, and broad availability to continue to drive demand for silk dental sutures
- 10.3.2 PLAIN GUT DENTAL SUTURES
- 10.3.2.1 Wide usage of plain gut sutures in oral mucosal closure and other short-healing procedures to support growth
- 10.3.3 CHROMIC GUT DENTAL SUTURES
- 10.3.3.1 Growing use of chromic gut dental sutures in tooth extractions and implant procedures to drive growth
- 10.3.1 SILK DENTAL SUTURES
11 DENTAL SUTURES MARKET, BY FILAMENT TYPE
- 11.1 INTRODUCTION
- 11.2 MONOFILAMENT DENTAL SUTURES
- 11.2.1 LOW CAPILLARITY AND BACTERIAL RETENTION TO DRIVE ADOPTION OF MONOFILAMENT DENTAL SUTURES
- 11.3 MULTIFILAMENT DENTAL SUTURES
- 11.3.1 FLEXIBILITY AND EASE OF HANDLING TO DRIVE USE OF MULTIFILAMENT DENTAL SUTURES
12 DENTAL SUTURES MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 ORAL SURGERY & TOOTH EXTRACTION
- 12.2.1 HIGH VOLUME OF TOOTH EXTRACTIONS PERFORMED FOR DENTAL CARIES AND OTHER DENTAL CONDITIONS TO BOOST MARKET
- 12.3 PERIODONTAL SURGERY
- 12.3.1 GROWING CLINICAL EMPHASIS ON ESTHETIC PERIODONTAL TREATMENT TO SUPPORT GROWTH
- 12.4 DENTAL IMPLANTOLOGY
- 12.4.1 GROWTH IN IMPLANT-SUPPORTED DENTAL REHABILITATION TO SUPPORT DEMAND FOR DENTAL SUTURES IN THIS APPLICATION
- 12.5 MAXILLOFACIAL SURGERY
- 12.5.1 GROWTH IN CORRECTIVE MAXILLOFACIAL PROCEDURES TO SUSTAIN DEMAND FOR SPECIALIZED SUTURES
- 12.6 OTHER APPLICATIONS
13 DENTAL SUTURES MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 DENTAL CLINICS & SPECIALTY DENTAL CENTERS
- 13.2.1 INCREASING VOLUME OF TOOTH EXTRACTIONS, PERIODONTAL SURGERIES, AND OTHER OUTPATIENT DENTAL PROCEDURES TO DRIVE SUTURE UTILIZATION
- 13.3 HOSPITALS & AMBULATORY SURGICAL CENTERS
- 13.3.1 RISING NUMBER OF COMPLEX ORAL AND MAXILLOFACIAL SURGERIES AND HOSPITAL-BASED DENTAL PROCEDURES TO DRIVE DEMAND
- 13.4 ACADEMIC & RESEARCH INSTITUTIONS
- 13.4.1 GROWING DENTAL EDUCATION, SURGICAL TRAINING, AND RESEARCH ACTIVITIES TO SUPPORT DEMAND
14 DENTAL SUTURES MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 EUROPE
- 14.2.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 14.2.2 GERMANY
- 14.2.2.1 Favorable government policies for reimbursement to drive demand for dental sutures
- 14.2.3 UK
- 14.2.3.1 High dental procedure volumes and oral disease burden to drive market
- 14.2.4 FRANCE
- 14.2.4.1 Large dental workforce and extensive health-insurance coverage to support demand for dental surgical procedures and associated sutures
- 14.2.5 SPAIN
- 14.2.5.1 Presence of well-established dental healthcare infrastructure to propel market
- 14.2.6 ITALY
- 14.2.6.1 Predominantly private dental-care financing to support procedural base for dental sutures
- 14.2.7 REST OF EUROPE
- 14.3 NORTH AMERICA
- 14.3.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 14.3.2 US
- 14.3.2.1 High per capita income and high quality of treatment to support market growth
- 14.3.3 CANADA
- 14.3.3.1 Rising healthcare expenditure to drive market
- 14.4 ASIA PACIFIC
- 14.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 14.4.2 JAPAN
- 14.4.2.1 Rising geriatric population and favorable reimbursement scenario to support market growth
- 14.4.3 CHINA
- 14.4.3.1 Growing prevalence of dental diseases and increasing geriatric population to drive market
- 14.4.4 INDIA
- 14.4.4.1 Growing dental tourism to support market growth
- 14.4.5 AUSTRALIA
- 14.4.5.1 Growing number of registered dental practitioners to support market growth
- 14.4.6 SOUTH KOREA
- 14.4.6.1 High senior population to support market demand
- 14.4.7 REST OF ASIA PACIFIC
- 14.5 LATIN AMERICA
- 14.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 14.5.2 BRAZIL
- 14.5.2.1 Improving access and affordability to drive market
- 14.5.3 MEXICO
- 14.5.3.1 Focus on improving healthcare infrastructure and availability of skilled dentists to drive the market
- 14.5.4 REST OF LATIN AMERICA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 14.6.2 GCC COUNTRIES
- 14.6.3 REST OF MIDDLE EAST & AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 INTRODUCTION
- 15.2 KEY PLAYER STRATEGY/RIGHT TO WIN
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN DENTAL SUTURES MARKET
- 15.3 REVENUE ANALYSIS, 2021-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.5.5.1 Company footprint
- 15.5.5.2 Region footprint
- 15.5.5.3 Type footprint
- 15.5.5.4 Material footprint
- 15.5.5.5 Filament type footprint
- 15.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.6.1 PROGRESSIVE COMPANIES
- 15.6.2 RESPONSIVE COMPANIES
- 15.6.3 DYNAMIC COMPANIES
- 15.6.4 STARTING BLOCKS
- 15.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.6.5.1 Detailed list of startups/SMEs
- 15.6.5.2 Competitive benchmarking of startups/SMEs
- 15.7 BRAND/PRODUCT COMPARISON
- 15.8 COMPANY VALUATION & FINANCIAL METRICS
- 15.8.1 FINANCIAL METRICS
- 15.8.2 COMPANY VALUATION
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 DEALS
- 15.9.2 EXPANSIONS
- 15.9.3 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 JOHNSON & JOHNSON
- 16.1.1.1 Business overview
- 16.1.1.2 Products offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Deals
- 16.1.1.3.2 Other developments
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses & competitive threats
- 16.1.2 B. BRAUN SE
- 16.1.2.1 Business overview
- 16.1.2.2 Products offered
- 16.1.2.3 MnM view
- 16.1.2.3.1 Key strengths
- 16.1.2.3.2 Strategic choices
- 16.1.2.3.3 Weaknesses & competitive threats
- 16.1.3 ADVANCED MEDICAL SOLUTIONS GROUP PLC
- 16.1.3.1 Business overview
- 16.1.3.2 Products offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Deals
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key strengths
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses & competitive threats
- 16.1.4 DEMETECH CORPORATION
- 16.1.4.1 Business overview
- 16.1.4.2 Products offered
- 16.1.4.3 MnM view
- 16.1.4.3.1 Key strengths
- 16.1.4.3.2 Strategic choices
- 16.1.4.3.3 Weaknesses & competitive threats
- 16.1.5 HU-FRIEDY MFG. CO., LLC
- 16.1.5.1 Business overview
- 16.1.5.2 Products offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Deals
- 16.1.5.3.2 Expansions
- 16.1.5.4 MnM view
- 16.1.5.4.1 Key strengths
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses & competitive threats
- 16.1.6 ENVISTA
- 16.1.6.1 Business overview
- 16.1.6.2 Products offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Deals
- 16.1.7 HENRY SCHEIN
- 16.1.7.1 Business overview
- 16.1.7.2 Products offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.7.3.2 Expansions
- 16.1.7.3.3 Other developments
- 16.1.8 FUTURA SURGICARE PVT. LTD.
- 16.1.8.1 Business overview
- 16.1.8.2 Products offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.9 MANI, INC.
- 16.1.9.1 Business overview
- 16.1.9.2 Products offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Other developments
- 16.1.10 CORZA MEDICAL
- 16.1.10.1 Business overview
- 16.1.10.2 Products offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Expansions
- 16.1.10.3.2 Other developments
- 16.1.11 SMI AG
- 16.1.11.1 Business overview
- 16.1.11.2 Products offered
- 16.1.12 YOUNG INNOVATIONS, INC.
- 16.1.12.1 Business overview
- 16.1.12.2 Products offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Deals
- 16.1.13 ASSUT EUROPE
- 16.1.13.1 Business overview
- 16.1.13.2 Products offered
- 16.1.14 KATSAN KATGUT SANAYI VE TIC. A.S.
- 16.1.14.1 Business overview
- 16.1.14.2 Products offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Other developments
- 16.1.15 DOGSAN TIBBI MALZEME SANAYI A.S.
- 16.1.15.1 Business overview
- 16.1.15.2 Products offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Other developments
- 16.1.1 JOHNSON & JOHNSON
- 16.2 OTHER PLAYERS
- 16.2.1 HYGITECH
- 16.2.2 ZIMVIE INC.
- 16.2.3 MEDIPAC SA
- 16.2.4 LUX SUTURES
- 16.2.5 BENTLEY HEALTHCARE PVT. LTD.
- 16.2.6 BOZ MEDICAL
- 16.2.7 DSI LTD.
- 16.2.8 GDT DENTAL IMPLANTS
- 16.2.9 GOLNIT
- 16.2.10 QUBIX MEDICARE PRIVATE LIMITED
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 BOTTOM-UP APPROACH
- 17.2.2 TOP-DOWN APPROACH
- 17.2.3 BASE NUMBER ESTIMATION
- 17.2.3.1 Supply-side Analysis (Revenue Share Analysis)
- 17.2.3.2 Company presentations & primary interviews
- 17.3 MARKET FORECAST APPROACH
- 17.4 MARKET SEGMENT ASSESSMENT (BY TYPE, MATERIAL, FILAMENT TYPE, APPLICATION, AND END USER)
- 17.5 GEOGRAPHIC MARKET ASSESSMENT (BY REGION AND COUNTRY)
- 17.6 DATA TRIANGULATION
- 17.7 MARKET SHARE ESTIMATION
- 17.8 STUDY ASSUMPTIONS
- 17.9 FACTOR ANALYSIS
- 17.10 RESEARCH LIMITATIONS
- 17.10.1 SCOPE-RELATED LIMITATIONS
- 17.10.2 METHODOLOGY-RELATED LIMITATIONS
- 17.11 RISK ASSESSMENT
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS


