
|
시장보고서
상품코드
2132662
의료 영상 분석 소프트웨어 시장 예측(-2031년) : 기능, 기술, 영상, 모달리티, 적응증, 최종사용자별Medical Image Analysis Software Market by Function, Tech, Image, Modality, Indication, End User - Global Forecast to 2031 |
||||||

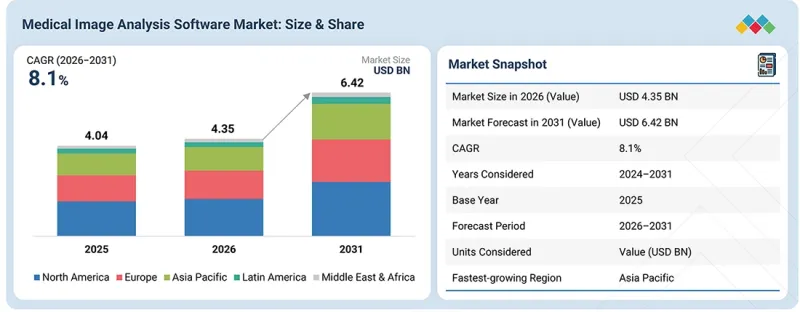
세계의 의료 영상 분석 소프트웨어 시장 규모는 2026년 43억 5,000만 달러에서 2031년에는 64억 2,000만 달러에 달할 것으로 예측되고 있으며, CAGR은 8.1%에 달할 전망입니다.
이러한 시장 성장은 주로 검출, 분할, 재구성, 보고서 작성 등 각 워크플로우에서 방사선과 의사의 업무 부담을 경감해야 할 필요성이 높아지고 있기 때문입니다. 병원에서는 AI 기반 소프트웨어를 활용하여 응급 소견의 우선순위 지정, 판독 시간 단축, 증가하는 CT, MRI, 초음파, 유방촬영술 검사 건수 관리를 수행하고 있습니다. 또한 진단 영상 센터에서는 보고서 작성 속도를 높이고 여러 거점에 걸친 원격 판독을 지원하기 위해 클라우드 기반 플랫폼을 도입하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2020-2032년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2032년 |
| 단위 | 금액(달러) |
| 부문 | 제공, 네트워크 유형, 최종사용자, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카 |
이미지 데이터세트이 점점 더 대규모화되고 복잡해지는 가운데, 학술·연구 기관에서는 다기관 공동 임상시험이나 질환 특이적 연구에서 AI 소프트웨어에 대한 의존도가 높아지고 있습니다. 또한 비용 절감과 진단까지 소요되는 시간 단축에 기여하는 AI 지원 통합형 하드웨어, 딥러닝 알고리즘, 클라우드 네이티브 플랫폼, 기업용 영상 획득 시스템이 시장을 더욱 견인하고 있습니다.
"AI 대응 기술별로는 딥러닝이 2025년에 가장 큰 점유율을 차지했습니다."
방사선 AI 벤더들은 원시 픽셀 데이터에서 직접 골절, 종양, 뇌졸중 및 기타 이상을 탐지하기 위한 컨볼루션 신경망(CNN) 기반 모델을 지속적으로 개발하고 있으며, 이것이 해당 부문에서 높은 점유율을 차지하는 요인입니다. 이 부문에는 병변의 자동 탐지, 영상 분할, 정량적 측정, 이상 징후 분류 등이 포함됩니다. 특히 딥러닝 모델은 대규모 다기관 횡단적 영상 데이터세트을 활용하여 학습시킬 수 있고, 기존의 규칙 기반 접근 방식보다 신속하게 FDA 승인을 위한 검증을 수행할 수 있으므로 그 도입이 특히 빠르게 진행되고 있습니다.
"최종사용자별로는 영상 진단 센터가 예측 기간 중 가장 빠른 성장세를 보일 것으로 예상됩니다."
이러한 성장은 주로 외래 환자의 영상 검사 건수 증가, 신속한 보고서의 작성에 대한 수요, 원격 및 텔레라디올로지 판독 모델을 지원하기 위한 AI 활용 확대에 의해 주도되고 있습니다. 진단 영상 센터에서는 현장의 방사선과 전문의 인력이 제한적인 상황에서 표준화된 스캔 영상을 대량으로 처리해야 하므로, AI를 활용한 분류 및 보고서 작성 소프트웨어의 활용이 확대되고 있습니다. 외래 영상 진단 수요가 증가하고 각 센터가 보고서 작성 소요 시간을 놓고 경쟁을 벌이는 가운데, 이익률을 유지하고 환자 처리 능력을 향상시키기 위해 AI를 활용한 검출 및 워크플로우 소프트웨어가 우선적인 투자 분야로 부상하고 있습니다.
"아시아태평양이 예측 기간 중 가장 높은 성장률을 기록할 것으로 전망됩니다."
이러한 성장은 주로 의료 디지털화의 진전, 민간 병원 네트워크의 확대, 보험 적용 범위 확대, 영상 진단 수요에 대한 방사선과 전문의의 심각한 부족에 의해 지원되고 있습니다. 인도, 중국, 일본, 한국, 호주, 필리핀 등의 국가들은 의료 기관이 증가하는 환자 수에 대응하고, 진단 지연을 줄이며, 지방 및 2·3선 도시에서 전문의의 영상 진단 접근성을 개선하려는 노력 속에서 중요한 시장으로 부상하고 있습니다. 인도는 심각한 방사선과 의사 부족 문제에 직면해 있으며, 추정에 따르면 지방 지역에서는 인구 10만 명당 1명 미만의 방사선과 의사만 있는 것으로 알려져 있습니다. 또한 인도의 ‘아유슈만 바라트 디지털 미션(Ayushman Bharat Digital Mission)’은 연계형 의료 기록에 필요한 디지털 인프라 구축을 추진하고 있으며, 2025년 8월 기준으로 7억 9,900만 건의 디지털 헬스 ID를 발급하고 41만 곳의 의료 시설을 연계하고 있습니다. 이에 따라 향후 클라우드 기반의 AI 탑재 영상 진단 소프트웨어에 대한 수요가 증가할 가능성이 있습니다.
또한 아시아태평양은 숙련된 기술 인력이 풍부하고 소프트웨어 개발 비용 효율이 높으며, 현지에서 탄생한 AI 방사선 진단 벤더가 확대되고 있으며, 의료 영상 AI의 강력한 공급 거점으로 자리 잡고 있습니다. 인도의 AI 방사선 진단 기업인 Qure.ai는 2025년 타임지(Time)로부터 ‘세계에서 가장 영향력 있는 AI 헬스케어 기업’ 중 하나로 선정되었으며, 100개국 이상에서 솔루션을 전개하고 있으며, 다수의 FDA 승인을 획득했습니다.
이 보고서에서는 전 세계 의료 영상 분석 소프트웨어 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 규제 상황
제8장 고객 상황과 구매 행동
제9장 의료 영상 분석 소프트웨어 시장 : 최종사용자별
제10장 의료 영상 분석 소프트웨어 시장 : 기능별
제11장 의료 영상 분석 소프트웨어 시장 : 영상 유형별
제12장 의료 영상 분석 소프트웨어 시장 : 모달리티별
제13장 의료 영상 분석 소프트웨어 시장 : 기술별
제14장 의료 영상 분석 소프트웨어 시장 : 치료 영역별
제15장 의료 영상 분석 소프트웨어 시장 : 유형별
제16장 의료 영상 분석 소프트웨어 시장 : 지역별
제17장 경쟁 구도
제18장 기업 개요
제19장 조사 방법
제20장 부록
KSA 26.10.01The global medical image analysis software market is projected to reach USD 6.42 billion by 2031 from USD 4.35 billion in 2026, at a CAGR of 8.1%. Market growth is mainly driven by the rising need to reduce radiologist workload across detection, segmentation, reconstruction, and reporting workflows. Hospitals are using AI-based software to triage urgent findings, reduce interpretation time, and manage rising CT, MRI, ultrasound, and mammography volumes. Diagnostic imaging centers are adopting cloud-based platforms to improve report turnaround and support remote reading across multiple sites.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2020-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Million/Billion) |
| Segments | By Offering, Network Type, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
Academic and research institutions are increasingly relying on AI software for multi-center clinical studies and disease-specific research as imaging datasets grow larger and more complex. The market is further supported by integrated AI-enabled hardware, deep learning algorithms, cloud-native platforms, and enterprise imaging acquisitions that help reduce cost and improve diagnostic turnaround time.
"Deep learning accounted for the largest share of the AI-enabled technology market in 2025."
By AI-enabled technology, the medical image analysis software market is segmented into machine learning, deep learning, computer vision, and natural language processing. The deep learning segment accounted for the largest market share in 2025, as radiology AI vendors continue to build convolutional neural network-based models for detecting fractures, tumors, strokes, and other abnormalities directly from raw pixel data. This segment includes automated lesion detection, image segmentation, quantitative measurement, and abnormality classification. Adoption is especially strong because deep learning models can be trained on large, multi-institutional imaging datasets and validated for FDA clearance faster than older rule-based approaches.
"Diagnostic imaging centers are expected to register the fastest growth among end users during the forecast period."
Based on end user, the medical image analysis software market is segmented into hospitals, diagnostic imaging centers, academic and research institutions, and other end users. Among these, diagnostic imaging centers are expected to record the fastest growth during the forecast period. The growth is mainly driven by rising outpatient imaging volumes, the need for faster report turnaround, and increasing use of AI to support remote and teleradiology reading models. Diagnostic imaging centers are increasingly using AI-based triage and reporting software because they process high volumes of standardized scans with limited on-site radiologist staff. As outpatient imaging demand rises and centers compete on turnaround time, AI-based detection and workflow software is becoming a priority investment area to protect margins and improve patient throughput.
"Asia Pacific to witness the highest growth rate in the medical image analysis software market during the forecast period."
Asia Pacific is expected to witness the highest growth rate in the medical image analysis software market during the forecast period. The growth is mainly supported by rising healthcare digitization, expanding private hospital networks, growing insurance coverage, and a severe shortage of radiologists relative to imaging demand. Countries such as India, China, Japan, South Korea, Australia, and the Philippines are becoming important markets as healthcare organizations try to manage higher patient volumes, reduce diagnostic delays, and improve access to specialist imaging review in rural and tier-2/tier-3 areas. India faces a critical radiologist shortage, with estimates suggesting fewer than one radiologist per 100,000 people in rural areas. India's Ayushman Bharat Digital Mission is also building the digital infrastructure needed for connected health records, having created 799 million digital health IDs and linked 410,000 healthcare facilities as of August 2025, which can increase demand for cloud-based, AI-enabled imaging software over time. Asia Pacific is also a strong delivery hub for medical imaging AI because of its large skilled technical workforce, cost-efficient software development, and growing base of homegrown AI radiology vendors. Qure.ai, an Indian AI radiology company, was recognized in 2025 by Time Magazine as one of the world's most influential AI healthcare companies, deploying its solutions in over 100 countries with multiple FDA clearances.
The breakdown of primary participants is as given below:
- By Company Type - Tier 1: 60%, Tier 2: 30%, and Tier 3: 10%
- By Designation - C-level: 30%, Director-level: 50%, and Others: 20%
- By Region - North America: 45%, Europe: 20%, Asia Pacific: 25%, Rest of the world: 10%.
Siemens Healthineers AG (Germany), GE HealthCare (US), Koninklijke Philips N.V. (Netherlands), Canon Medical Systems Corporation (Japan), FUJIFILM Holdings Corporation (Japan), and Aidoc Medical Ltd. (Israel) are key players in the medical image analysis software market.
The study includes an in-depth competitive analysis of these key players in the medical image analysis software market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the medical image analysis software market by Type [Integrated Software, Standalone Software], Technology [AI-Enabled Technology {Machine Learning, Deep Learning, Computer Vision, Natural Language Processing}, Conventional Technology], Function [Reconstruction & Visualization, Detection & Localization, Segmentation & Analysis, Registration & Comparison, Reporting & Communication, Clinical Decision Support], Image Type [2D Imaging, 3D Imaging, 4D Imaging], Modality [Radiography (X-Ray), Computed Tomography (CT) {High-end Slice CT, Mid-end Slice CT, Low-end Slice CT}, Magnetic Resonance Imaging (MRI) {Closed MRI Systems, Open MRI Systems}, Ultrasound Imaging {2D Ultrasound Systems, 3D and 4D Ultrasound Systems, Doppler Imaging}, Nuclear Imaging {Positron Emission Tomography (PET), Single-Photon Emission Computed Tomography (SPECT)}, Mammography, Combined/Hybrid Modalities {PET/CT, SPECT/CT, PET/MR}, Others], Therapeutic Area [Cardiology, Oncology, Neurology, Orthopedics, Dental, Obstetrics & Gynecology, Mammography/Breast Imaging, Others], End User [Hospitals, Diagnostic Imaging Centers, Academic & Research Institutions, Other End Users], and Region [North America, Europe, Asia Pacific, Latin America, and Middle East & Africa]. The report covers detailed information on major factors such as drivers, restraints, challenges, and opportunities influencing the growth of the medical image analysis software market. This report provides a detailed analysis of key industry players, including their business overview, product portfolios, technology capabilities, key strategies, contracts, partnerships, agreements, product launches, mergers & acquisitions, and recent developments in the medical image analysis software market. This report covers a competitive analysis of established and emerging players in the medical image analysis software ecosystem.
Reasons to buy this report
The report will help market leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the medical image analysis software market and the subsegments. This report will help stakeholders understand the competitive landscape and gain insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- The report provides insights on the following pointers: Analysis of key drivers (rising imaging volumes amid growing radiologist workforce shortages, increasing FDA and regulatory clearances for AI-enabled imaging software, growing integration of AI capabilities into imaging hardware systems, rising prevalence of chronic diseases requiring imaging-based diagnosis, increasing venture capital and strategic investment in AI radiology platforms), restraints (high cost of software validation, integration, and deployment, data privacy and cross-border health data regulations), opportunities (expansion of cloud-native and AI-as-a-service imaging platforms, untapped growth potential in emerging markets across Asia Pacific, Latin America, and Middle East & Africa, emerging applications of foundation models and multimodal AI in diagnostic imaging), and challenges (limited interoperability with legacy PACS/RIS and vendor-specific systems, algorithm generalizability and bias across diverse patient populations) influencing the growth of the medical image analysis software market.
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the medical image analysis software market.
- Market Development: Comprehensive information about lucrative markets; the report analyses the medical image analysis software market across varied regions.
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the medical image analysis software market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players like Siemens Healthineers AG (Germany), GE HealthCare (US), Koninklijke Philips N.V. (Netherlands), Canon Medical Systems Corporation (Japan), FUJIFILM Holdings Corporation (Japan), and Aidoc Medical Ltd. (Israel), among others, in the medical image analysis software market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET OVERVIEW
- 3.2 NORTH AMERICA: MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY TYPE & COUNTRY
- 3.3 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET: GEOGRAPHIC SNAPSHOT
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising imaging volumes amid growing radiologist workforce shortages
- 4.2.1.2 Increasing FDA and regulatory clearances for AI-enabled imaging software
- 4.2.1.3 Growing demand for early and accurate disease detection
- 4.2.1.4 Increasing adoption of quantitative and workflow-automation solutions
- 4.2.2 RESTRAINTS
- 4.2.2.1 High cost of software validation, integration, and deployment
- 4.2.2.2 Data privacy and cross-border health data regulations
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of cloud-native and AI-as-a-service imaging platforms
- 4.2.3.2 Emerging applications of foundation models and multimodal AI in diagnostic imaging
- 4.2.3.3 Expansion into new imaging modalities and clinical specialties
- 4.2.3.4 Integration of image analysis with clinical decision-support and longitudinal care platforms
- 4.2.4 CHALLENGES
- 4.2.4.1 Limited interoperability with legacy PACS/RIS and vendor-specific systems
- 4.2.4.2 Algorithm generalizability and bias across diverse patient populations
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF SUBSTITUTES
- 5.1.4 THREAT OF NEW ENTRANTS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL HEALTHCARE INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 RESEARCH, IMAGING DATA GENERATION, AND CLINICAL INPUTS
- 5.3.2 DATA ENGINEERING & AI INFRASTRUCTURE
- 5.3.3 AI MODEL & PLATFORM DEVELOPMENT
- 5.3.4 WORKFLOW INTEGRATION & INTEROPERABILITY
- 5.3.5 SOFTWARE DEPLOYMENT & CLINICAL SERVICES
- 5.3.6 CLINICAL VALIDATION, MONITORING, AND CONTINUOUS OPTIMIZATION
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 MEDICAL IMAGE ANALYSIS SOFTWARE PLATFORMS, BY KEY PLAYERS (2025)
- 5.5.2 INDICATIVE PRICE FOR MEDICAL IMAGE ANALYSIS SOFTWARE, BY REGION (2025)
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.10 IMPACT OF 2025 US TARIFF - MEDICAL IMAGE ANALYSIS SOFTWARE MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRY/REGION
- 5.10.4.1 US
- 5.10.4.2 Europe
- 5.10.4.3 Asia Pacific
- 5.10.5 IMPACT ON END USERS
- 5.10.5.1 Hospitals and health systems
- 5.10.5.2 Diagnostic imaging centers
- 5.10.5.3 Specialty clinics and ambulatory care providers
- 5.10.5.4 Pharmaceutical and biotechnology companies
- 5.10.5.5 Academic and research institutions
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 AI-POWERED DEEP LEARNING AND FOUNDATION MODELS
- 6.1.2 CLOUD-NATIVE MEDICAL IMAGING AND AI-AS-A-SERVICE
- 6.1.3 ADVANCED 3D VISUALIZATION, SEGMENTATION, AND QUANTITATIVE IMAGING
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 CLOUD COMPUTING AND EDGE COMPUTING
- 6.2.2 INTEROPERABILITY, PACS/VNA, AND CLINICAL DATA INTEGRATION
- 6.3 TECHNOLOGY/PRODUCT ROADMAP
- 6.4 PATENT ANALYSIS
- 6.4.1 PATENT PUBLICATION TRENDS FOR MEDICAL IMAGE ANALYSIS SOFTWARE MARKET
- 6.4.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.5 FUTURE APPLICATIONS
- 6.5.1 EARLY DISEASE DETECTION AND SCREENING
- 6.5.2 PERSONALIZED TREATMENT PLANNING AND THERAPY GUIDANCE
- 6.5.3 LONGITUDINAL DISEASE MONITORING AND TREATMENT RESPONSE
- 6.6 IMPACT OF AI/GEN AI ON MEDICAL IMAGE ANALYSIS SOFTWARE SOLUTIONS
- 6.6.1 INTRODUCTION
- 6.6.2 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION
- 6.6.2.1 AI-powered chest X-ray analysis for tuberculosis screening
- 6.6.3 IMPACT OF AI/GEN AI ON INTERCONNECTED & ADJACENT ECOSYSTEMS
- 6.6.3.1 PACS/VNA & enterprise imaging market
- 6.6.3.2 AI in medical imaging market
- 6.6.3.3 EHR/Clinical decision support market
- 6.6.4 USER READINESS & IMPACT ASSESSMENT
- 6.6.4.1 User readiness
- 6.6.4.1.1 User A: Healthcare providers
- 6.6.4.1.2 User B: Diagnostic imaging centers
- 6.6.4.2 Impact assessment
- 6.6.4.2.1 User A: Healthcare providers
- 6.6.4.2.2 User B: Diagnostic imaging centers
- 6.6.4.1 User readiness
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATORY FRAMEWORK
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 ASIA PACIFIC
- 7.1.2.4 LATIN AMERICA
- 7.1.2.5 MIDDLE EAST & AFRICA
- 7.1.3 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.5 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5.1 UNMET NEEDS
- 8.5.2 END USER EXPECTATIONS
- 8.6 MARKET PROFITABILITY
9 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY END USER
- 9.1 INTRODUCTION
- 9.2 HOSPITALS
- 9.2.1 INCREASING ADOPTION OF ADVANCED MEDICAL IMAGING AND AI IN HOSPITALS
- 9.3 DIAGNOSTIC IMAGING CENTERS
- 9.3.1 RISING DEMAND FOR EFFICIENT AND HIGH-VOLUME DIAGNOSTIC IMAGING TO BOOST MARKET
- 9.4 ACADEMIC & RESEARCH INSTITUTIONS
- 9.4.1 INCREASING USE OF MEDICAL IMAGE ANALYSIS SOFTWARE IN RESEARCH TO BOOST SEGMENT
- 9.5 OTHER END USERS
- 9.5.1 EXPANDING USE OF MEDICAL IMAGE ANALYSIS BEYOND CONVENTIONAL HEALTHCARE SETTING TO BOOST SEGMENT
10 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY FUNCTION
- 10.1 INTRODUCTION
- 10.2 RECONSTRUCTION & VISUALIZATION
- 10.2.1 INCREASING DEMAND FOR HIGH-QUALITY IMAGE RECONSTRUCTION AND 3D VISUALIZATION TO BOOST SEGMENT
- 10.3 DETECTION & LOCALIZATION
- 10.3.1 RISING DEMAND FOR AUTOMATED DETECTION AND LOCALIZATION OF ABNORMALITIES
- 10.4 SEGMENTATION & ANALYSIS
- 10.4.1 INCREASING ADOPTION OF AUTOMATED SEGMENTATION AND QUANTITATIVE IMAGE ANALYSIS
- 10.5 REGISTRATION & COMPARISON
- 10.5.1 GROWING NEED FOR ACCURATE ALIGNMENT AND COMPARISON OF MULTIMODAL MEDICAL IMAGES TO BOOST GROWTH
- 10.6 REPORTING & COMMUNICATION
- 10.6.1 GROWING ADOPTION OF AI-POWERED RADIOLOGY REPORTING AND WORKFLOW AUTOMATION TO DRIVE SEGMENT
- 10.7 CLINICAL DECISION SUPPORT
- 10.7.1 INCREASING ADOPTION OF AI-ASSISTED CLINICAL DECISION SUPPORT
11 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY IMAGE TYPE
- 11.1 INTRODUCTION
- 11.2 3D IMAGING
- 11.2.1 GROWING ADOPTION OF 3D IMAGING FOR DETAILED ANATOMICAL VISUALIZATION TO BOOST SEGMENT
- 11.3 4D IMAGING
- 11.3.1 GROWING DEMAND FOR DYNAMIC AND FUNCTIONAL MEDICAL IMAGING TO DRIVE SEGMENT
- 11.4 2D IMAGING
- 11.4.1 CONTINUED DEMAND FOR 2D IMAGING IN ROUTINE DIAGNOSTIC APPLICATIONS - KEY DRIVER
12 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY MODALITY
- 12.1 INTRODUCTION
- 12.2 RADIOGRAPHY (X-RAY)
- 12.2.1 INCREASING ADOPTION OF AI-ENABLED X-RAY ANALYSIS AND WORKFLOW AUTOMATION TO DRIVE SEGMENT
- 12.3 COMPUTED TOMOGRAPHY (CT)
- 12.3.1 SEGMENT DRIVEN BY AI-ENABLED CT IMAGE ANALYSIS FOR RECONSTRUCTION AND DETECTION
- 12.3.2 HIGH-END SLICE CT
- 12.3.2.1 Growing demand for high-resolution and advanced CT imaging - key driver
- 12.3.3 MID-END SLICE CT
- 12.3.3.1 Demand for versatile CT systems with automated analysis to boost growth
- 12.3.4 LOW-END SLICE CT
- 12.3.4.1 Expanding access to cost-efficient CT imaging to propel growth
- 12.4 MAGNETIC RESONANCE IMAGING (MRI)
- 12.4.1 INCREASING ADOPTION OF AI-POWERED MRI RECONSTRUCTION AND WORKFLOW AUTOMATION TO DRIVE MARKET
- 12.4.2 CLOSED MRI SYSTEMS
- 12.4.2.1 Increasing demand for high-resolution and AI-optimized MRI to drive segment
- 12.4.3 OPEN MRI SYSTEMS
- 12.4.3.1 Expanding access to patient-friendly and specialized MRI to drive segment
- 12.5 ULTRASOUND IMAGING
- 12.5.1 INCREASING ADOPTION OF AI-POWERED ULTRASOUND IMAGING AND WORKFLOW AUTOMATION TO DRIVE MARKET
- 12.5.2 2D ULTRASOUND SYSTEMS
- 12.5.2.1 Expanding use of AI-assisted analysis in routine 2D ultrasound to drive segment
- 12.5.3 3D & 4D ULTRASOUND SYSTEMS
- 12.5.3.1 Increasing demand for volumetric and dynamic ultrasound analysis to boost segment
- 12.5.4 DOPPLER IMAGING
- 12.5.4.1 Growing demand for automated blood-flow assessment
- 12.6 NUCLEAR IMAGING
- 12.6.1 GROWING ADOPTION OF QUANTITATIVE ANALYSIS IN NUCLEAR IMAGING TO BOOST SEGMENT
- 12.6.2 POSITRON EMISSION TOMOGRAPHY (PET)
- 12.6.2.1 Increasing use of quantitative PET for molecular and functional imaging to drive segment
- 12.6.3 SINGLE-PHOTON EMISSION COMPUTED TOMOGRAPHY (SPECT)
- 12.6.3.1 Growing demand for quantitative SPECT in theranostics and cardiovascular imaging
- 12.7 MAMMOGRAPHY
- 12.7.1 INCREASING ADOPTION OF AI-POWERED MAMMOGRAPHY FOR BREAST CANCER DETECTION TO BOOS SEGMENT
- 12.8 COMBINED/HYBRID MODALITIES
- 12.8.1 GROWING ADOPTION OF HYBRID IMAGING FOR INTEGRATED ANATOMICAL AND FUNCTIONAL ANALYSIS TO BOOST SEGMENT
- 12.8.2 PET/CT
- 12.8.2.1 Increasing demand for quantitative PET/CT in oncology
- 12.8.3 SPECT/CT
- 12.8.3.1 Increasing use of SPECT/CT for quantitative assessment and dosimetry
- 12.8.4 PET/MR
- 12.8.4.1 Growing demand for high-resolution multimodal brain and oncology imaging to propel demand
- 12.9 OTHERS
13 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY TECHNOLOGY
- 13.1 INTRODUCTION
- 13.2 AI-ENABLED TECHNOLOGY
- 13.2.1 INCREASING ADOPTION OF AI FOR AUTOMATED AND QUANTITATIVE IMAGE ANALYSIS
- 13.2.2 MACHINE LEARNING
- 13.2.2.1 Increasing use of machine learning for automated medical image analysis to drive segment
- 13.2.3 DEEP LEARNING
- 13.2.3.1 Growing use of deep learning for high-precision medical image reconstruction and analysis to boost segment
- 13.2.4 COMPUTER VISION
- 13.2.4.1 Increasing adoption of computer vision for automated detection and interpretation of medical images to boost segment
- 13.2.5 NATURAL LANGUAGE PROCESSING (NLP)
- 13.2.5.1 Increasing use of NLP for automated radiology reporting and clinical information extraction
- 13.3 CONVENTIONAL TECHNOLOGY
- 13.3.1 CONTINUED DEMAND FOR RELIABLE AND ESTABLISHED IMAGE PROCESSING
14 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY THERAPEUTIC AREA
- 14.1 INTRODUCTION
- 14.2 CARDIOLOGY
- 14.2.1 INCREASING ADOPTION OF AI-POWERED CARDIOVASCULAR IMAGE ANALYSIS TO DRIVE MARKET
- 14.3 ONCOLOGY
- 14.3.1 INCREASING USE OF MEDICAL IMAGING AND AI FOR CANCER DETECTION AND TREATMENT MONITORING TO BOOST SEGMENT
- 14.4 NEUROLOGY
- 14.4.1 RISING DEMAND FOR AI-ASSISTED NEUROLOGICAL IMAGING AND EARLY DISEASE DETECTION
- 14.5 ORTHOPEDICS
- 14.5.1 GROWING ADOPTION OF AI-ENABLED IMAGING FOR ORTHOPEDIC DIAGNOSIS AND SURGICAL PLANNING
- 14.6 DENTAL
- 14.6.1 INCREASING ADOPTION OF AI-ENABLED DENTAL IMAGING AND DIAGNOSTIC ANALYSIS TO BOOST SEGMENT
- 14.7 OBSTETRICS & GYNECOLOGY
- 14.7.1 INCREASING ADOPTION OF AI-ENABLED OBSTETRIC AND GYNECOLOGICAL IMAGING
- 14.8 MAMMOGRAPHY/BREAST IMAGING
- 14.8.1 GROWING ADOPTION OF AI FOR BREAST CANCER DETECTION AND MAMMOGRAPHY WORKFLOW OPTIMIZATION
- 14.9 OTHER THERAPEUTIC AREAS
- 14.9.1 EXPANDING APPLICATIONS OF MEDICAL IMAGE ANALYSIS ACROSS EMERGING THERAPEUTIC AREAS
15 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY TYPE
- 15.1 INTRODUCTION
- 15.2 INTEGRATED SOFTWARE
- 15.2.1 GROWING INTEGRATION OF AI-POWERED IMAGE ANALYSIS INTO CLINICAL WORKFLOWS TO BOOST SEGMENT
- 15.3 STANDALONE SOFTWARE
- 15.3.1 INCREASING ADOPTION OF AI-ENABLED STANDALONE IMAGE ANALYSIS SOLUTIONS TO DRIVE SEGMENT
16 MEDICAL IMAGE ANALYSIS SOFTWARE MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 16.2.2 US
- 16.2.2.1 Growing demand for faster diagnostics to boost demand
- 16.2.3 CANADA
- 16.2.3.1 Increasing investments in healthcare data infrastructure and medical imaging AI to drive market
- 16.3 EUROPE
- 16.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 16.3.2 GERMANY
- 16.3.2.1 Growing adoption of AI-powered medical imaging and radiology solutions to drive market
- 16.3.3 FRANCE
- 16.3.3.1 Increasing adoption of AI-based medical imaging solutions to drive market
- 16.3.4 UK
- 16.3.4.1 Increasing government support for AI-enabled medical imaging to boost market
- 16.3.5 ITALY
- 16.3.5.1 Growing adoption of AI in medical imaging and diagnostic workflows to boost market
- 16.3.6 SPAIN
- 16.3.6.1 Expanding adoption of AI-powered medical imaging solutions to boost market
- 16.3.7 REST OF EUROPE
- 16.4 ASIA PACIFIC
- 16.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 16.4.2 CHINA
- 16.4.2.1 Expanding deployment of AI-powered medical imaging solutions to boost market
- 16.4.3 JAPAN
- 16.4.3.1 Growing adoption of AI in medical imaging and radiology to boost market
- 16.4.4 INDIA
- 16.4.4.1 Increasing investment in AI-powered medical imaging and diagnostic infrastructure to drive market
- 16.4.5 AUSTRALIA
- 16.4.5.1 Increasing investment in AI-enabled medical imaging and diagnostic infrastructure
- 16.4.6 SOUTH KOREA
- 16.4.6.1 Strong government and industry investment in AI-enabled medical imaging
- 16.4.7 REST OF ASIA PACIFIC
- 16.5 LATIN AMERICA
- 16.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 16.5.2 BRAZIL
- 16.5.2.1 Increasing investment in AI infrastructure and medical imaging to drive market
- 16.5.3 MEXICO
- 16.5.3.1 Increasing deployment of AI-enabled medical imaging infrastructure
- 16.5.4 REST OF LATIN AMERICA
- 16.5.4.1 Growing adoption of AI in medical imaging to boost market
- 16.6 MIDDLE EAST & AFRICA
- 16.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 16.6.2 GCC
- 16.6.2.1 Expanding healthcare digitalization and AI adoption to drive market
- 16.6.2.2 Saudi Arabia
- 16.6.2.2.1 Accelerating adoption of AI in medical imaging - key driver
- 16.6.2.3 UAE
- 16.6.2.3.1 Government-led AI initiatives for smart healthcare to boost market
- 16.6.2.4 Rest of GCC
- 16.6.2.4.1 Increasing healthcare digitization to drive market
- 16.6.3 SOUTH AFRICA
- 16.6.3.1 Growing adoption and readiness for AI-enabled medical imaging to boost market
- 16.6.4 REST OF MIDDLE EAST & AFRICA
17 COMPETITIVE LANDSCAPE
- 17.1 INTRODUCTION
- 17.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 17.2.1 OVERVIEW OF STRATEGIES ADOPTED BY PLAYERS IN MEDICAL IMAGE ANALYSIS SOFTWARE MARKET
- 17.3 REVENUE ANALYSIS, 2021-2025
- 17.4 MARKET SHARE ANALYSIS, 2025
- 17.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 17.5.1 STARS
- 17.5.2 EMERGING LEADERS
- 17.5.3 PERVASIVE PLAYERS
- 17.5.4 PARTICIPANTS
- 17.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 17.5.5.1 Company footprint
- 17.5.5.2 Region footprint
- 17.5.5.3 Type footprint
- 17.5.5.4 Technology footprint
- 17.5.5.5 Image Type footprint
- 17.6 COMPANY EVALUATION MATRIX: STARTUPS /SMES, 2025
- 17.6.1 PROGRESSIVE COMPANIES
- 17.6.2 RESPONSIVE COMPANIES
- 17.6.3 DYNAMIC COMPANIES
- 17.6.4 STARTING BLOCKS
- 17.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 17.6.5.1 Detailed list of key startups/SMEs
- 17.6.5.2 Competitive benchmarking of key startups/SMEs
- 17.7 COMPANY VALUATION AND FINANCIAL METRICS
- 17.8 BRAND/SOFTWARE COMPARISON
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 PRODUCT/SERVICE LAUNCHES & UPGRADES
- 17.9.2 DEALS
- 17.9.3 EXPANSIONS
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 SIEMENS HEALTHINEERS AG
- 18.1.1.1 Products/solutions/services offered
- 18.1.1.2 Recent developments
- 18.1.1.2.1 Product launches & upgrades
- 18.1.1.2.2 Deals
- 18.1.1.2.3 Expansions
- 18.1.1.3 MnM view
- 18.1.1.3.1 Key strengths
- 18.1.1.3.2 Strategic choices
- 18.1.1.3.3 Weaknesses and competitive threats
- 18.1.2 GE HEALTHCARE
- 18.1.2.1 Business overview
- 18.1.2.2 Products/solutions/services offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Product launches & upgrades
- 18.1.2.3.2 Deals
- 18.1.2.4 MnM view
- 18.1.2.4.1 Key strengths
- 18.1.2.4.2 Strategic choices
- 18.1.2.4.3 Weaknesses and competitive threats
- 18.1.3 KONINKLIJKE PHILIPS N.V.
- 18.1.3.1 Business overview
- 18.1.3.2 Products/solutions/services offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product launches & upgrades
- 18.1.3.3.2 Deals
- 18.1.3.3.3 Expansions
- 18.1.3.4 MnM view
- 18.1.3.4.1 Key strengths
- 18.1.3.4.2 Strategic choices
- 18.1.3.4.3 Weaknesses and competitive threats
- 18.1.4 CANON MEDICAL SYSTEMS CORPORATION
- 18.1.4.1 Business overview
- 18.1.4.2 Products/solutions/services offered
- 18.1.4.3 Recent developments
- 18.1.4.3.1 Product launches & upgrades
- 18.1.4.3.2 Deals
- 18.1.5 FUJIFILM HOLDINGS CORPORATION
- 18.1.5.1 Business overview
- 18.1.5.2 Products/solutions/services offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Product launches & upgrades
- 18.1.5.3.2 Deals
- 18.1.6 AGFA-GEVAERT N.V.
- 18.1.6.1 Business overview
- 18.1.6.2 Products/solutions/services offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Product launches & upgrades
- 18.1.6.3.2 Deals
- 18.1.7 CARESTREAM HEALTH
- 18.1.7.1 Business overview
- 18.1.7.2 Products/solutions/services offered
- 18.1.7.3 Recent developments
- 18.1.7.3.1 Product launches & upgrades
- 18.1.7.3.2 Deals
- 18.1.8 HOLOGIC, INC.
- 18.1.8.1 Business overview
- 18.1.8.2 Products/solutions/services offered
- 18.1.8.3 Recent developments
- 18.1.8.3.1 Product launches & upgrades
- 18.1.8.3.2 Deals
- 18.1.9 MERATIVE
- 18.1.9.1 Business overview
- 18.1.9.2 Products/solutions/services offered
- 18.1.9.3 Recent developments
- 18.1.9.3.1 Product launches & upgrades
- 18.1.9.3.2 Deals
- 18.1.9.3.3 Expansions
- 18.1.10 SECTRA AB
- 18.1.10.1 Business overview
- 18.1.10.2 Products/solutions/services offered
- 18.1.10.3 Recent developments
- 18.1.10.3.1 Product launches & upgrades
- 18.1.10.3.2 Deals
- 18.1.11 BRUKER CORPORATION
- 18.1.11.1 Business overview
- 18.1.11.2 Products/solutions/services offered
- 18.1.12 QUIBIM
- 18.1.12.1 Business overview
- 18.1.12.2 Products/solutions/services offered
- 18.1.12.3 Recent developments
- 18.1.12.3.1 Deals
- 18.1.13 MIRADA MEDICAL LTD.
- 18.1.13.1 Business overview
- 18.1.13.2 Products/solutions/services offered
- 18.1.13.3 Recent developments
- 18.1.13.3.1 Products launches & upgrades
- 18.1.13.3.2 Deals
- 18.1.13.4 Other developments
- 18.1.14 MEDIAN TECHNOLOGIES
- 18.1.14.1 Business overview
- 18.1.14.2 Products/solutions/services offered
- 18.1.14.3 Recent developments
- 18.1.14.3.1 Products launches & upgrades
- 18.1.14.3.2 Deals
- 18.1.15 ELUCID
- 18.1.15.1 Business overview
- 18.1.15.2 Products/solutions/services offered
- 18.1.15.3 Recent developments
- 18.1.15.3.1 Products launches & upgrades
- 18.1.15.3.2 Other developments
- 18.1.16 RAPIDAI, INC.
- 18.1.16.1 Business overview
- 18.1.16.2 Products/solutions/services offered
- 18.1.16.3 Recent developments
- 18.1.16.3.1 Product launches & upgrades
- 18.1.16.3.2 Deals
- 18.1.17 MICROSOFT CORPORATION
- 18.1.17.1 Business overview
- 18.1.17.2 Products/solutions/services offered
- 18.1.17.3 Recent developments
- 18.1.17.3.1 Product launches & upgrades
- 18.1.17.3.2 Deals
- 18.1.18 TEMPUS AI, INC.
- 18.1.18.1 Business overview
- 18.1.18.2 Products/solutions/services offered
- 18.1.18.3 Recent developments
- 18.1.18.3.1 Product launches & upgrades
- 18.1.18.3.2 Deals
- 18.1.19 NANO-X IMAGING LTD
- 18.1.19.1 Business overview
- 18.1.19.2 Products/solutions/services offered
- 18.1.19.3 Recent developments
- 18.1.19.3.1 Product launches & upgrades
- 18.1.19.3.2 Deals
- 18.1.20 CONTEXTVISION AB
- 18.1.20.1 Business overview
- 18.1.20.2 Products/solutions/services offered
- 18.1.20.3 Recent developments
- 18.1.20.3.1 Product launches & upgrades
- 18.1.20.3.2 Deals
- 18.1.1 SIEMENS HEALTHINEERS AG
- 18.2 OTHER PLAYERS
- 18.2.1 VIZ.AI, INC.
- 18.2.2 AIDOC MEDICAL LTD.
- 18.2.3 AVICENNA.AI
- 18.2.4 CLEERLY, INC.
- 18.2.5 OVERJET, INC.
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH APPROACH
- 19.1.1 SECONDARY RESEARCH
- 19.1.1.1 Key data from secondary sources
- 19.1.2 PRIMARY RESEARCH
- 19.1.2.1 Key data from primary sources
- 19.1.2.2 Insights from primary experts
- 19.1.1 SECONDARY RESEARCH
- 19.2 RESEARCH METHODOLOGY DESIGN
- 19.3 MARKET SIZE ESTIMATION
- 19.4 MARKET BREAKDOWN DATA TRIANGULATION
- 19.5 MARKET SHARE ESTIMATION
- 19.6 STUDY ASSUMPTIONS
- 19.7 LIMITATIONS
- 19.7.1 SCOPE-RELATED LIMITATIONS
- 19.7.2 METHODOLOGY-RELATED LIMITATIONS
- 19.8 RISK ASSESSMENT
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS


