
|
시장보고서
상품코드
2136426
문서 AI 시장 : 제공별, 문서 유형별, 사용 사례별, 업계별, 지역별 - 세계 예측(-2031년)Document AI Market by Offering (IDP, Document Workflow Automation, Generative AI Document Generation, ECM, and Governance Tools), Use Case (Compliance Reports, Customer Feedback, KYC Document, RFP Responses, Purchase Orders) - Global Forecast to 2031 |
||||||

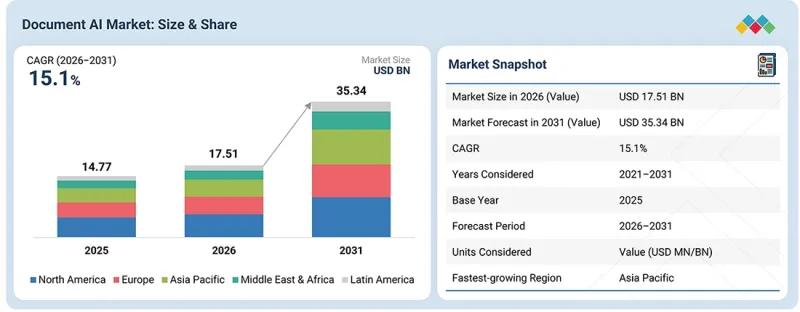
세계의 문서 AI 시장 규모는 2026년 175억 1,000만 달러에서 2031년까지 353억 4,000만 달러로, CAGR 15.1%로 확대될 것으로 예측됩니다.
적응형 문서 학습 모델을 통해 시스템이 실시간 사용자 피드백을 바탕으로 스스로 개선할 수 있게 되어, 수동 재훈련의 필요성이 줄어들고 다양한 문서 형식 전반에 걸쳐 정확도가 향상됨에 따라 시장이 성장하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 제공별, 문서 유형별, 사용 사례별, 업계별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카 |
그래프 기반 문서 인텔리전스는 여러 페이지로 구성된 문서 내의 엔티티와 관계를 연결함으로써 문맥에 대한 이해도도 높입니다. 이는 법무, 보험, 규정 준수 워크플로우에서 특히 가치가 있습니다. 그러나 업계 전반에 걸쳐 문서 데이터 형식의 표준화가 진행되지 않아 상호 운용성이 제한되고, 대규모의 원활한 모델 배포가 저해되고 있습니다.
“기업들이 엔드투엔드 자동화와 규정 준수를 위한 데이터 처리를 우선시하는 가운데, IDP 솔루션이 문서 AI 시장을 주도하고 있습니다.”
지능형 문서 처리(IDP) 솔루션은 비정형 및 반정형 문서의 전체 워크플로우에 걸쳐 완전한 자동화를 실현하는 능력을 바탕으로, 문서 AI 시장에서 가장 큰 시장 점유율을 차지할 것으로 예상됩니다. IDP 플랫폼은 OCR, NLP, 머신러닝을 통합하여 청구서, 양식, 계약서, 규정 준수 관련 문서에서 데이터를 높은 정확도로 추출, 분류, 검증합니다. 은행, 보험, 의료 등 업계의 기업들은 문서 처리 시간을 단축하고, 수작업 데이터 입력을 줄이며, 감사 대응이 가능한 디지털 기록을 유지하기 위해 IDP를 도입하고 있습니다. 원격 근무 및 종이 없는 업무 환경 구축 노력이 급속히 확대되고 있는 점도 클라우드 기반 IDP 플랫폼에 대한 수요를 더욱 높이고 있습니다. UiPath, ABBYY, Kofax 등의 벤더는 생성형 AI, RPA와의 통합, 그리고 사전 학습된 도메인 특정 모델을 활용하여 IDP 솔루션을 강화하고 있으며, 이를 통해 도입을 가속화하고 ROI를 향상시키고 있습니다. 또한, 설명 가능한 AI 및 데이터 계보 기능에 대한 수요 증가는 규제 준수 요건과도 부합하며, 기업 차원의 문서 자동화를 위한 기반으로 IDP가 선택되는 입지를 확고히 하고 있습니다.
“기업들이 복잡하고 방대한 콘텐츠 처리를 자동화하는 가운데, 비정형 문서가 문서 AI 시장을 주도하고 있습니다.”
비정형 문서의 종류는 문서 AI 시장에서 가장 큰 시장 점유율을 차지할 것으로 예상됩니다. 이는 고정된 템플릿이 없는 이메일, 계약서, 보고서, 손글씨 메모, 멀티미디어를 다용한 기록 등을 처리해야 할 필요성이 높아지고 있음을 반영합니다. 은행, 의료, 정부 기관 등 업종을 불문하고 기업의 데이터 대부분은 여전히 비정형이며, 다양한 문서 형식을 이해할 수 있는 고도화된 AI 모델에 대한 큰 수요가 발생하고 있습니다. 레이아웃 인식형 트랜스포머, 멀티모달 AI, 자연어 이해 분야의 최근 발전 덕분에 문서 AI 시스템은 텍스트, 표, 이미지에서 문맥 정보를 동시에 정확하게 추출할 수 있게 되었습니다. 구글, 마이크로소프트, AWS 등의 벤더들은 특정 업계를 위해 미세 조정된 사전 학습 모델을 사용하여 다양한 형식의 문서를 처리할 수 있도록 솔루션을 확대하고 있습니다. 비정형 문서 처리의 도입은 특히 감사 추적 및 고객과의 커뮤니케이션 분야에서 규정 준수를 주도하는 자동화 및 데이터 거버넌스 요구 사항에 의해 가속화되고 있습니다. 기업들이 레거시 아카이브의 디지털화와 검색 가능한 문서 저장소 구축에 주력하는 가운데, 비정형 문서 인텔리전스는 대규모 디지털 생태계 전반에 걸쳐 효율성 향상, 의사결정 개선, 규제상 투명성 확보를 추진하는 데 핵심적인 역할을 수행하고 있습니다.
“아시아태평양은 혁신과 전략의 진화에 힘입어 급속한 성장이 예상되는 반면, 2026년에는 북미가 시장 규모 면에서 선두를 차지할 전망입니다.”
문서 AI 시장은 지역별로 현저한 차이를 보이며, 인도, 인도네시아, 베트남 등 국가들의 급속한 디지털 전환을 배경으로 아시아태평양이 가장 빠른 성장을 이룰 것으로 예측됩니다. 이는 ‘디지털 인디아’나 일본의 ‘사회 5.0’과 같은 이니셔티브에 의해 뒷받침되고 있습니다. 다국어 OCR 및 자연어 처리 기능에 대한 수요가 증가함에 따라, 기업들은 BFSI(은행·금융·보험), 의료, 물류, 정부 기관의 워크플로우를 자동화하기 위해 클라우드 기반 문서 AI 및 IDP 솔루션에 대한 투자를 확대하고 있습니다. 핀테크, 디지털 결제, 전자 거버넌스의 부상 또한 규정 준수, 온보딩, 신원 확인 분야에서 문서 자동화에 대한 수요를 촉진하고 있습니다. 한편, 북미는 선진적인 인프라, 조기 도입, 그리고 Google, Microsoft, AWS, IBM, Adobe와 같은 벤더들의 존재로 인해 2026년에는 시장을 주도할 것으로 예상됩니다. HIPAA, SOX, GDPR과 같은 엄격한 규제로 인해 AI를 활용한 규정 준수 및 감사 솔루션의 도입이 진행되고 있습니다. 특히 금융, 보험, 의료 분야에서는 분류, 계약 분석, 보험금 청구 처리에 AI가 활용되고 있습니다. 생성형 AI, RAG, 설명 가능성 모델의 통합을 통해 문서의 정확도와 이해도가 향상됩니다. 이처럼 북미의 혁신과 아시아태평양의 디지털 성장이 맞물려 전 세계 문서 AI 시장을 형성하고, 시장 확대를 주도하고 있습니다.
문서 AI 시장의 주요 기업으로는 Google(미국), Microsoft(미국), SAP(독일), IBM(미국), AWS(미국), Oracle(미국), Adobe(미국),ABBYY(미국), Automation Anywhere(미국), UiPath(미국), Appian(미국), H2O.ai(미국), EdgeVerve(인도), Super.ai(미국), Rossum(체코), Tungsten Automation(미국), OpenText(캐나다),Hyland(미국), Hyperscience(미국), EXL(미국), Snowflake(미국), Salesforce(미국), Grooper(미국), DocDigitizer(미국), Cinnamon(일본),Docugami(미국), Mistral AI(프랑스), Upstage(한국), DocByte(벨기에), Infrrd(미국), Docketry(미국), OpenAI(미국), Gamma(미국), AidocMaker(미국), Anthropic(미국), Checkbox(미국),Docubee(미국), DocuPilot(미국), Docsumo(미국), Formstack(미국), HyperWrite(미국), Lindy(미국), QuillBot(미국), 및 Scribe(미국) 등이 있습니다.
조사 범위
본 조사 보고서에서는 문서 AI 시장을 제공 유형별(솔루션 및 서비스), 문서 유형별(구조화, 비구조화, 반구조화 및 멀티모달/혼합 콘텐츠), 사용 사례(재무·회계, 법무·컴플라이언스, 고객 서비스, 마케팅·영업, 인사, 공급망·물류),산업별(BFSI, 헬스케어·생명과학, 정부·공공 부문, 소매·E-Commerce, 제조, 에너지·공공사업, 통신, 운송·물류, 교육, 기타 산업), 및 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카)로 분류하고 있습니다. 본 보고서의 조사 범위에는 문서 AI 시장의 성장에 영향을 미치는 주요 요인(촉진요인, 제약요인, 과제 및 기회 등)에 대한 상세한 정보가 포함되어 있습니다. 본 보고서에서는 주요 업계 플레이어에 대해 사업 개요, 솔루션 및 서비스, 주요 전략, 계약, 파트너십, 합의 사항, 제품·서비스 출시, 합병·인수, 그리고 문서 AI 시장의 최근 동향을 포함한 상세한 분석을 제공합니다. 또한, 문서 AI 시장 생태계에서 두각을 나타내고 있는 스타트업 기업의 경쟁 분석도 포괄하고 있습니다.
본 보고서를 구매해야 하는 이유
본 보고서는 시장을 선도하는 기업과 신규 진입 기업에게 문서 AI 시장 전체 및 그 하위 부문의 매출에 대한 가장 정확한 추정치를 제공합니다. 이를 통해 이해관계자는 경쟁 구도를 이해하고, 자사의 비즈니스를 더 유리한 위치에 놓으며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻을 수 있습니다. 또한 이해관계자가 시장 동향을 파악하고, 주요 시장 촉진요인 및 과제에 대한 정보를 얻는 데에도 도움이 됩니다.
본 보고서에서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인 분석(정확도 향상을 실현하는 OCR+NER 융합 파이프라인의 발전, 문서와 거래를 연결하는 전자서명 및 전자 워크플로우 생태계의 성장, 캡처 도구와 분석·BI 도구를 결합한 마켓플레이스의 전개), 제약요인(모델 훈련 및 텔레메트리 분야의 국경을 초월한 데이터 거주 요건, 희귀하고 롱테일인 템플릿에 대한 높은 주석 비용),기회(틈새 훈련 데이터셋을 위한 합성 문서 마켓플레이스, 조항 라이브러리와 통합된 생성형 AI를 활용한 계약서 작성, 피드백 루프를 통해 추출 오류를 자가 복구하는 자동 수정 엔진),및 과제(템플릿 및 양식의 진화에 따른 추출 안정성 유지, 악의적인 라벨이나 저품질 라벨로부터 어노테이션 공급망을 보호하는 것)
- 제품 개발/혁신 : 문서 AI 시장의 향후 기술, 연구 개발 활동 및 제품·서비스 출시에 관한 상세한 인사이트
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보 및 각 지역별 문서 AI 시장 분석
- 시장 다각화 : 문서 AI 시장의 새로운 솔루션 및 서비스, 미개척 지역, 최근 동향 및 투자에 대한 종합적인 정보
- 경쟁 분석 : Google(미국), Microsoft(미국),SAP(독일), IBM(미국), AWS(미국), Oracle(미국), Adobe(미국), ABBYY(미국), Automation Anywhere(미국), UiPath(미국), Appian(미국), H2O.ai(미국), EdgeVerve(인도),Super.ai(미국), Rossum(체코), Tungsten Automation(미국), OpenText(캐나다), Hyland(미국), Hyperscience(미국), EXL(미국), Snowflake(미국), Salesforce(미국), Grooper(미국),DocDigitizer(미국), Cinnamon(일본), Docugami(미국), Mistral AI(프랑스), Upstage(한국), DocByte(벨기에), Infrrd(미국), Docketry(미국), OpenAI(미국), Gamma(미국), AidocMaker(미국),Anthropic(미국), Checkbox(미국), Docubee(미국), DocuPilot(미국), Docsumo(미국), Formstack(미국), HyperWrite(미국), Lindy(미국), QuillBot(미국), 및 Scribe(미국).
또한, 본 보고서는 주요 시장 촉진요인, 시장 억제요인, 과제 및 기회에 대한 정보를 제공함으로써 이해관계자들이 문서 AI 시장의 동향을 파악하는 데 도움이 될 것입니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 규제 상황
제8장 고객 상황과 구매 행동
제9장 문서 AI 시장(제공별)
제10장 문서 AI 시장(문서 유형별)
제11장 문서 AI 시장(사용 사례별)
제12장 문서 AI 시장(업계별)
제13장 문서 AI 시장(지역별)
제14장 경쟁 구도
제15장 기업 개요
제16장 조사 방법
제17장 인접 시장 및 관련 시장
제18장 부록
KSM 26.10.07The global Document AI market is projected to grow from USD 17.51 billion in 2026 to USD 35.34 billion by 2031, at a CAGR of 15.1%. The market is growing as adaptive document learning models enable systems to self-improve through real-time user feedback, reducing the need for manual retraining and improving accuracy across diverse document formats.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Billion) |
| Segments | By Offering, Solution, Service, Document Type, Use Case, & Vertical |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
Graph-based document intelligence also enhances contextual understanding by linking entities and relationships within multi-page documents, which is particularly valuable for legal, insurance, and compliance workflows. However, limited standardization of document data formats across industries continues to restrain interoperability and hinders seamless model deployment at scale.
"IDP solutions dominate the Document AI market as enterprises prioritize end-to-end automation and compliance-ready data processing."
Intelligent document processing (IDP) solutions are projected to hold the largest market share in the Document AI market, driven by their ability to deliver complete automation across unstructured and semi-structured document workflows. IDP platforms integrate OCR, NLP, and machine learning to extract, classify, and validate data from invoices, forms, contracts, and compliance documents with high accuracy. Enterprises in sectors such as banking, insurance, and healthcare are adopting IDP to accelerate document turnaround times, reduce manual data entry, and maintain audit-ready digital records. The rapid expansion of remote operations and paperless initiatives has further increased demand for cloud-based IDP platforms. Vendors like UiPath, ABBYY, and Kofax are enhancing IDP solutions with generative AI, RPA integration, and pre-trained domain-specific models, enabling faster deployments and higher ROI. Additionally, the growing need for explainable AI and data lineage capabilities aligns with regulatory compliance requirements, reinforcing IDP's position as the preferred foundation for enterprise-scale document automation.
"Unstructured documents lead the Document AI market as enterprises automate complex, high-volume content processing."
Unstructured document types are expected to hold the largest market share in the Document AI market, reflecting the growing need to process emails, contracts, reports, handwritten notes, and multimedia-rich records that lack fixed templates. Across industries such as banking, healthcare, and government, most enterprise data remains unstructured, creating a significant demand for advanced AI models capable of understanding variable document formats. Recent advancements in layout-aware transformers, multimodal AI, and natural language understanding are allowing Document AI systems to accurately extract contextual information from text, tables, and images simultaneously. Vendors like Google, Microsoft, and AWS have expanded their solutions to handle multi-format documents using pre-trained models fine-tuned for specific industries. The adoption of unstructured document processing is also being accelerated by compliance-driven automation and data governance requirements, particularly for audit trails and customer communications. As enterprises focus on digitizing legacy archives and enabling searchable document repositories, unstructured document intelligence has become central to driving efficiency, improving decision-making, and ensuring regulatory transparency across large-scale digital ecosystems.
"Asia Pacific to witness rapid growth fueled by innovation and evolving strategies, while North America leads in terms of market size in 2026."
The Document AI market exhibits strong regional differences, with the Asia Pacific region predicted to grow the fastest due to the rapid digital transformation in countries such as India, Indonesia, and Vietnam, supported by initiatives like Digital India and Japan's Society 5.0. Businesses are increasingly investing in cloud-based Document AI and IDP solutions to automate workflows in BFSI, healthcare, logistics, and government, driven by the need for multilingual OCR and natural language processing capabilities. The rise of fintech, digital payments, and e-governance is also driving the need for document automation in compliance, onboarding, and identity verification. Meanwhile, North America is expected to lead in 2026, thanks to its advanced infrastructure, early adoption, and vendors such as Google, Microsoft, AWS, IBM, and Adobe. Strict regulations, such as HIPAA, SOX, and GDPR, are driving the adoption of AI-driven compliance and audit solutions, particularly in the finance, insurance, and healthcare sectors, which utilize AI for classification, contract analysis, and claims processing. The integration of generative AI, RAG, and explainability models enhances document accuracy and understanding. Thus, North America's innovation and Asia Pacific's digital growth are jointly shaping the global Document AI landscape, driving market expansion.
Breakdown of Primaries
In-depth interviews were conducted with chief executive officers (CEOs), innovation and technology directors, system integrators, and executives from various key organizations operating in the Document AI market.
- By Company: Tier 1 - 38%, Tier 2 - 47%, and Tier 3 - 15%
- By Designation: C-level Executives - 31%, Directors - 46%, and Others - 23%
- By Region: North America - 39%, Europe - 22%, Asia Pacific - 28%, Middle East & Africa - 4%, and Latin America - 7%
Note: Others include sales, marketing, and product managers.
Tier 1 companies' revenues are more than USD 500 million, Tier 2 companies' revenues range between USD 100 and 500 million, and Tier 3 companies' revenues are equal to or less than USD 100 million.
The major players in the Document AI market include Google (US), Microsoft (US), SAP (Germany), IBM (US), AWS (US), Oracle (US), Adobe (US), ABBYY (US), Automation Anywhere (US), UiPath (US), Appian (US), H2O.ai (US), EdgeVerve (India), Super.ai (US), Rossum (Czech Republic), Tungsten Automation (US), OpenText (Canada), Hyland (US), Hyperscience (US), EXL (US), Snowflake (US), Salesforce (US), Grooper (US), DocDigitizer (US), Cinnamon (Japan), Docugami (US), Mistral AI (France), Upstage (South Korea), DocByte (Belgium), Infrrd (US), Docketry (US), OpenAI (US), Gamma (US), AidocMaker (US), Anthropic (US), Checkbox (US), Docubee (US), DocuPilot (US), Docsumo (US), Formstack (US), HyperWrite (US), Lindy (US), QuillBot (US), and Scribe (US).
Research Coverage
This research report categorizes the Document AI market by offering (solutions and services), document type (structured, unstructured, semi-structured, and multimodal/mixed content), use case (finance & accounting, legal & compliance, customer service, marketing & sales, HR, and supply chain & logistics), vertical (BFSI, healthcare & life sciences, government & public sector, retail & e-commerce, manufacturing, energy & utilities, telecommunications, transportation & logistics, education, and other verticals), and region (North America, Europe, Asia Pacific, Middle East & Africa, and Latin America). The scope of the report covers detailed information regarding the major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the Document AI market. This report provides a detailed analysis of key industry players, including their business overview, solutions and services, key strategies, contracts, partnerships, agreements, product and service launches, mergers and acquisitions and recent developments in the Document AI market. This report covers a competitive analysis of upcoming startups in the Document AI market ecosystem.
Reasons to Buy This Report
The report will provide market leaders and new entrants with information on the closest approximations of the revenue numbers for the overall Document AI market and its subsegments. It will help stakeholders understand the competitive landscape and gain more insights to position their business better and plan suitable go-to-market strategies. It also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (advancements in OCR+NER fusion pipelines delivering higher precision, growth of e-signature and e-workflow ecosystems tying documents to transactions, marketplace bundling of capture tools with analytics and BI tools), restraints (cross-border data residency limits for model training and telemetry, high annotation cost for rare and long-tail templates), opportunities (synthetic-document marketplaces for niche training datasets, generative-assisted contract drafting integrated with clause libraries, auto-remediation engines that self-heal extraction errors through feedback loops), and challenges (maintaining extraction stability as templates and forms evolve, securing annotation supply chains against malicious or low-quality labels)
- Product development/innovation: Detailed insights into upcoming technologies, research & development activities, and product and service launches in the Document AI market
- Market development: Comprehensive information about lucrative markets, analysis of the Document AI market across varied regions
- Market Diversification: Exhaustive information about new solutions and services, untapped geographies, recent developments, and investments in the Document AI market
- Competitive Assessment: In-depth assessment of market shares, growth strategies and offerings of the major players in the Document AI market, like Google (US), Microsoft (US), SAP (Germany), IBM (US), AWS (US), Oracle (US), Adobe (US), ABBYY (US), Automation Anywhere (US), UiPath (US), Appian (US), H2O.ai (US), EdgeVerve (India), Super.ai (US), Rossum (Czech Republic), Tungsten Automation (US), OpenText (Canada), Hyland (US), Hyperscience (US), EXL (US), Snowflake (US), Salesforce (US), Grooper (US), DocDigitizer (US), Cinnamon (Japan), Docugami (US), Mistral AI (France), Upstage (South Korea), DocByte (Belgium), Infrrd (US), Docketry (US), OpenAI (US), Gamma (US), AidocMaker (US), Anthropic (US), Checkbox (US), Docubee (US), DocuPilot (US), Docsumo (US), Formstack (US), HyperWrite (US), Lindy (US), QuillBot (US), and Scribe (US).
The report also helps stakeholders understand the pulse of the Document AI market, providing them with information on key market drivers, restraints, challenges, and opportunities.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.2.1 INCLUSIONS AND EXCLUSIONS
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.2 DISRUPTIVE TRENDS IN DOCUMENT AI MARKET
- 2.3 HIGH GROWTH SEGMENTS
- 2.4 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES IN THE DOCUMENT AI MARKET
- 3.2 DOCUMENT AI MARKET, BY REGION
- 3.3 DOCUMENT AI MARKET, BY OFFERING
- 3.4 NORTH AMERICA: DOCUMENT AI MARKET, BY TOP SOLUTIONS AND DOCUMENT TYPES
- 3.5 DOCUMENT AI MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Advancements in OCR+NER fusion pipelines delivering higher precision
- 4.2.1.2 Growth of e-signature and e-workflow ecosystems tying documents to transactions
- 4.2.1.3 Marketplace bundling of capture tools with analytics and BI tools
- 4.2.2 RESTRAINTS
- 4.2.2.1 Cross-border data residency limits for model training and telemetry
- 4.2.2.2 High annotation cost for rare and long-tail templates
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Synthetic-document marketplaces for niche training datasets
- 4.2.3.2 Generative-assisted contract drafting integrated with clause libraries
- 4.2.3.3 Auto-remediation engines that self-heal extraction errors through feedback loops
- 4.2.4 CHALLENGES
- 4.2.4.1 Maintaining extraction stability as templates and forms evolve
- 4.2.4.2 Securing annotation supply chains against malicious or low-quality labels
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN DOCUMENT AI MARKET
- 4.3.2 WHITE-SPACE OPPORTUNITIES IN DOCUMENT AI MARKET
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 EVOLUTION OF DOCUMENT AI
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 THREAT OF NEW ENTRANTS
- 5.2.2 THREAT OF SUBSTITUTES
- 5.2.3 BARGAINING POWER OF SUPPLIERS
- 5.2.4 BARGAINING POWER OF BUYERS
- 5.2.5 INTENSITY OF COMPETITION RIVALRY
- 5.3 MACROECONOMIC INDICATORS
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.4 SUPPLY CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 INTELLIGENT DOCUMENT PROCESSING PROVIDERS
- 5.5.2 GEN AI DOCUMENT GENERATION PROVIDERS
- 5.5.3 DOCUMENT WORKFLOW AUTOMATION PROVIDERS
- 5.5.4 ECM & GOVERNANCE PROVIDERS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE OF OFFERINGS, BY KEY PLAYER, 2025
- 5.6.2 AVERAGE SELLING PRICE, BY USE CASE, 2025
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 VERYFI ENABLES KOLLWITZOWEN TO PROVIDE FAIR PROMOTIONS WITH INSTANT RECEIPT VALIDATIONS
- 5.10.2 INFRRD AI TRANSFORMS MEDTECH LEADER'S PURCHASE ORDER PROCESSING BY AUTOMATING MULTI-LANGUAGE DOCUMENTS
- 5.10.3 DOCSUMO HELPS N.S. TRUCKING PROCESS 45K+ DISPATCH TICKETS 4X FASTER
- 5.10.4 INDICO DATA CUTS GLOBAL SPECIALTY INSURER'S SUBMISSION PROCESSING TIME TO UNDER 30 SECONDS WITH AI AUTOMATION
- 5.10.5 ROSSUM BOOSTS VEOLIA'S INVOICE PROCESSING SPEED BY 8X WITH AI-DRIVEN WORKFLOW AUTOMATION
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 OCR
- 6.1.2 NLP
- 6.1.3 COMPUTER VISION
- 6.1.4 NEURAL NETWORKS
- 6.1.5 LLM
- 6.1.6 KNOWLEDGE GRAPHS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 RPA
- 6.2.2 CLOUD COMPUTING
- 6.2.3 DATA ANNOTATION AND LABELING
- 6.2.4 CYBERSECURITY
- 6.2.5 DATABASE & DATA LAKE TECHNOLOGIES
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 SPEECH-TO-TEXT AND VOICE RECOGNITION
- 6.3.2 DIGITAL IDENTITY VERIFICATION
- 6.3.3 BLOCKCHAIN
- 6.3.4 INTERNET OF THINGS (IOT)
- 6.3.5 AUGMENTED AND VIRTUAL REALITY (AR/VR)
- 6.4 TECHNOLOGY ROADMAP
- 6.4.1 SHORT-TERM (2026-2027) | GENERATIVE DOCUMENT EXTRACTION, MULTIMODAL UNDERSTANDING & WORKFLOW INTEGRATION
- 6.4.2 MID-TERM (2027-2030) | AGENTIC DOCUMENT WORKFLOWS, CROSS-DOCUMENT REASONING & ENTERPRISE CONTENT INTELLIGENCE
- 6.4.3 LONG-TERM (2030-2035+) | AUTONOMOUS, TRUSTED & UBIQUITOUS DOCUMENT INTELLIGENCE
- 6.5 PATENT ANALYSIS
- 6.5.1 METHODOLOGY
- 6.5.2 PATENTS FILED, BY DOCUMENT TYPE, 2016-2026**
- 6.5.3 INNOVATION AND PATENT APPLICATIONS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AUTONOMOUS DOCUMENT-TO-ACTION SYSTEMS
- 6.6.2 DYNAMIC POLICY ADAPTATION ENGINES
- 6.6.3 DOCUMENT INTELLIGENCE FOR EDGE DEVICES
- 6.6.4 MULTI-AGENT DOCUMENT COLLABORATION HUBS
- 6.6.5 CONTEXT-AWARE KNOWLEDGE RECONSTRUCTION
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATIONS
- 7.1.2.1 North America
- 7.1.2.1.1 Executive Order 14110 on Safe, Secure, and Trustworthy AI (US)
- 7.1.2.1.2 Artificial Intelligence and Data Act-AIDA (Canada)
- 7.1.2.2 Europe
- 7.1.2.2.1 Europe Artificial Intelligence Act (European Union)
- 7.1.2.2.2 General Data Protection Regulation (European Union)
- 7.1.2.2.3 Data Protection Act 2018 (UK)
- 7.1.2.2.4 Federal Data Protection Act (Germany)
- 7.1.2.2.5 French Data Protection Act (France)
- 7.1.2.2.6 Personal Data Protection Code-Legislative Decree 196/2003 (Italy)
- 7.1.2.2.7 Organic Law 3/2018 (Spain)
- 7.1.2.2.8 UAVG and Public-Sector Algorithm Transparency (Netherlands)
- 7.1.2.3 Asia Pacific
- 7.1.2.3.1 Interim Measures for the Management of Generative AI Services (China)
- 7.1.2.3.2 Digital Personal Data Protection Act, 2023 (India)
- 7.1.2.3.3 Act on the Protection of Personal Information (Japan)
- 7.1.2.3.4 Basic Act on Artificial Intelligence (South Korea)
- 7.1.2.3.5 Personal Data Protection Act (Singapore)
- 7.1.2.4 Middle East & Africa
- 7.1.2.4.1 Federal Decree-Law No. 45 of 2021 on the Protection of Personal Data (UAE)
- 7.1.2.4.2 Personal Data Protection Law (KSA)
- 7.1.2.4.3 Protection of Personal Information Act (South Africa)
- 7.1.2.4.4 Personal Data Privacy Protection Law (Qatar)
- 7.1.2.4.5 Law on the Protection of Personal Data No. 6698 (Turkey)
- 7.1.2.5 Latin America
- 7.1.2.5.1 General Data Protection Law - LGPD (Brazil)
- 7.1.2.5.2 Federal Law on Protection of Personal Data Held by Private Parties (Mexico)
- 7.1.2.5.3 Personal Data Protection Law No. 25,326 (Argentina)
- 7.1.2.1 North America
- 7.1.3 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.1.1 STRATEGIC EVALUATION AND BUSINESS CASE ALIGNMENT
- 8.1.2 TECHNICAL VALIDATION AND VENDOR DIFFERENTIATION
- 8.1.3 PROCUREMENT, CHANGE MANAGEMENT, AND LONG-TERM VALUE REALIZATION
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USER VERTICALS
- 8.5 MARKET PROFITABILITY
9 DOCUMENT AI MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 DRIVERS: DOCUMENT AI MARKET, BY OFFERING
- 9.2 SOLUTIONS
- 9.2.1 IDP
- 9.2.1.1 Enabling high-accuracy extraction and automation of unstructured data
- 9.2.2 DOCUMENT WORKFLOW AUTOMATION
- 9.2.2.1 Bridging IDP and business operations for seamless processing
- 9.2.3 GEN AI DOCUMENT GENERATION
- 9.2.3.1 Redefining content creation and document authoring workflows
- 9.2.4 ECM & GOVERNANCE TOOLS
- 9.2.4.1 Ensuring security, compliance, and structured document management
- 9.2.1 IDP
- 9.3 SERVICES
- 9.3.1 PROFESSIONAL SERVICES
- 9.3.1.1 Enabling seamless implementation and strategic alignment of Document AI
- 9.3.1.2 Consulting & advisory
- 9.3.1.3 Deployment & integration
- 9.3.1.4 Support & training
- 9.3.2 MANAGED SERVICES
- 9.3.2.1 Enabling scalable and cost-effective Document AI operations
- 9.3.1 PROFESSIONAL SERVICES
- 9.4 DEPLOYMENT MODE
- 9.4.1 CLOUD
- 9.4.1.1 Accelerating time-to-value and global scalability of Document AI
- 9.4.2 ON-PREMISES
- 9.4.2.1 Essential for data-sensitive and regulated industries
- 9.4.1 CLOUD
10 DOCUMENT AI MARKET, BY DOCUMENT TYPE
- 10.1 INTRODUCTION
- 10.1.1 DRIVERS: DOCUMENT AI MARKET, BY DOCUMENT TYPE
- 10.2 STRUCTURED
- 10.2.1 DRIVING HIGH-VOLUME, HIGH-ACCURACY AUTOMATION AT SCALE
- 10.3 UNSTRUCTURED
- 10.3.1 POWERING NEXT WAVE OF INTELLIGENT DOCUMENT UNDERSTANDING
- 10.4 SEMI-STRUCTURED
- 10.4.1 BRIDGING RULE-BASED AUTOMATION AND ADAPTIVE AI MODELS
- 10.5 MULTIMODAL/MIXED CONTENT
- 10.5.1 UNLOCKING NEW FRONTIERS IN COMPLEX DATA UNDERSTANDING
11 DOCUMENT AI MARKET, BY USE CASE
- 11.1 INTRODUCTION
- 11.1.1 DRIVERS: DOCUMENT AI MARKET, BY USE CASE
- 11.2 FINANCE & ACCOUNTING
- 11.2.1 INVOICES & TAX FORMS
- 11.2.1.1 Streamlining payables with intelligent data extraction and validation
- 11.2.2 RECEIPTS & REIMBURSEMENT CLAIMS
- 11.2.2.1 Accelerating employee expense management through automated capture
- 11.2.3 BANK STATEMENTS
- 11.2.3.1 Enabling transparent financial reconciliation and anomaly detection
- 11.2.4 FINANCIAL REPORTS & REGULATORY FILINGS
- 11.2.4.1 Ensuring compliance and accuracy in complex disclosures
- 11.2.5 EXPENSE FORMS
- 11.2.5.1 Reducing manual entry and policy violations through context-aware automation
- 11.2.6 OTHER FINANCE & ACCOUNTING USE CASES
- 11.2.1 INVOICES & TAX FORMS
- 11.3 HR
- 11.3.1 RESUMES/CVS
- 11.3.1.1 Accelerating talent acquisition with AI-driven resume intelligence
- 11.3.2 ONBOARDING DOCUMENTS
- 11.3.2.1 Streamlining employee onboarding with intelligent document automation
- 11.3.3 PAYROLL
- 11.3.3.1 Automating payroll documentation for compliance and accuracy
- 11.3.4 POLICY DOCUMENT
- 11.3.4.1 Enforcing policy compliance through AI-driven document governance
- 11.3.5 OTHER HR USE CASES
- 11.3.1 RESUMES/CVS
- 11.4 LEGAL & COMPLIANCE
- 11.4.1 CONTRACTS
- 11.4.1.1 Automating contract lifecycle management for speed and risk reduction
- 11.4.2 AGREEMENTS
- 11.4.2.1 Streamlining agreement validation and compliance auditing through AI
- 11.4.3 NDAS
- 11.4.3.1 Enhancing confidentiality governance with automated NDA monitoring
- 11.4.4 REGULATORY FILINGS
- 11.4.4.1 Accelerating regulatory compliance through AI-enabled document intelligence
- 11.4.5 COMPLIANCE REPORTS
- 11.4.5.1 Ensuring continuous audit readiness with automated compliance documentation
- 11.4.6 OTHER LEGAL & COMPLIANCE USE CASES
- 11.4.1 CONTRACTS
- 11.5 CUSTOMER SERVICE
- 11.5.1 KYC DOCUMENTS
- 11.5.1.1 Accelerating customer verification and compliance through AI-powered KYC automation
- 11.5.2 CLAIM FORMS
- 11.5.2.1 Streamlining claim processing through context-aware document understanding
- 11.5.3 CUSTOMER FEEDBACK
- 11.5.3.1 Turning unstructured customer feedback into actionable insights with AI
- 11.5.4 SERVICE REQUEST
- 11.5.4.1 Automating service request handling for faster and more personalized support
- 11.5.5 OTHER CUSTOMER SERVICE USE CASES
- 11.5.1 KYC DOCUMENTS
- 11.6 MARKETING & SALES
- 11.6.1 PROPOSALS
- 11.6.1.1 Streamlining proposal creation and review with AI-powered document intelligence
- 11.6.2 RFP RESPONSES
- 11.6.2.1 Accelerating RFP lifecycle management with intelligent document automation
- 11.6.3 SURVEY RESULTS
- 11.6.3.1 Transforming customer insights from survey documents into strategic intelligence
- 11.6.4 CAMPAIGN COLLATERAL
- 11.6.4.1 Optimizing marketing content management with AI-driven document structuring
- 11.6.5 OTHER MARKETING & SALES USE CASES
- 11.6.1 PROPOSALS
- 11.7 SUPPLY CHAIN & LOGISTICS
- 11.7.1 PURCHASE ORDERS
- 11.7.1.1 Automating procurement approvals and supplier coordination with intelligent PO processing
- 11.7.2 DELIVERY NOTES
- 11.7.2.1 Streamlining goods receipt and verification through automated delivery note processing
- 11.7.3 BILLS OF LADING
- 11.7.3.1 Ensuring shipping accuracy and regulatory compliance with intelligent bill of lading processing
- 11.7.4 SHIPMENT MANIFESTS
- 11.7.4.1 Enabling real-time cargo visibility and tracking with AI-enabled manifest digitization
- 11.7.5 OTHER SUPPLY CHAIN & LOGISTICS USE CASES
- 11.7.1 PURCHASE ORDERS
12 DOCUMENT AI MARKET, BY VERTICAL
- 12.1 INTRODUCTION
- 12.1.1 DRIVERS: DOCUMENT AI MARKET, BY VERTICAL
- 12.2 BFSI
- 12.2.1 MODERNIZING HIGH-VOLUME FINANCIAL DOCUMENTATION WITH AI-DRIVEN PRECISION
- 12.3 TRANSPORTATION & LOGISTICS
- 12.3.1 AUTOMATING SHIPMENT AND COMPLIANCE DOCUMENTATION FOR FASTER SUPPLY CHAIN FLOWS
- 12.4 HEALTHCARE & LIFE SCIENCES
- 12.4.1 IMPROVING CLINICAL ACCURACY AND ADMINISTRATIVE EFFICIENCY WITH DOCUMENT AI
- 12.5 GOVERNMENT & PUBLIC SECTOR
- 12.5.1 ACCELERATING ADMINISTRATIVE EFFICIENCY AND CITIZEN SERVICES THROUGH DOCUMENT INTELLIGENCE
- 12.6 RETAIL & E-COMMERCE
- 12.6.1 ENHANCING TRANSACTION SPEED AND CUSTOMER EXPERIENCE WITH AUTOMATED DOCUMENT FLOWS
- 12.7 MANUFACTURING
- 12.7.1 DRIVING PRODUCTION EFFICIENCY AND COMPLIANCE WITH AUTOMATED DOCUMENT INTELLIGENCE
- 12.8 ENERGY & UTILITIES
- 12.8.1 STRENGTHENING REGULATORY COMPLIANCE AND ASSET MANAGEMENT WITH AI-DRIVEN DOCUMENT PROCESSING
- 12.9 TELECOMMUNICATIONS
- 12.9.1 STREAMLINING SERVICE DOCUMENTATION AND REGULATORY PROCESSES THROUGH AUTOMATION
- 12.10 EDUCATION
- 12.10.1 EMPOWERING EDUCATIONAL EFFICIENCY THROUGH AI-DRIVEN DOCUMENT INTELLIGENCE
- 12.11 OTHER VERTICALS
13 DOCUMENT AI MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 NORTH AMERICA: DOCUMENT AI MARKET DRIVERS
- 13.2.2 NORTH AMERICA: MACROECONOMIC OUTLOOK
- 13.2.3 US
- 13.2.3.1 Innovation leadership and regulatory maturity to drive market
- 13.2.4 CANADA
- 13.2.4.1 Public sector digitization and cloud adoption to drive market
- 13.3 EUROPE
- 13.3.1 EUROPE: DOCUMENT AI MARKET DRIVERS
- 13.3.2 EUROPE: MACROECONOMIC OUTLOOK
- 13.3.3 UK
- 13.3.3.1 Early enterprise digitalization and regulatory clarity to strengthen market
- 13.3.4 GERMANY
- 13.3.4.1 Manufacturing leadership and data sovereignty to drive Document AI adoption
- 13.3.5 FRANCE
- 13.3.5.1 Public sector digitization and language localization to boost market
- 13.3.6 ITALY
- 13.3.6.1 Modernization of public administration and BFSI to drive market
- 13.3.7 SPAIN
- 13.3.7.1 Digital public administration and e-invoicing modernization to drive market
- 13.3.8 REST OF EUROPE
- 13.4 ASIA PACIFIC
- 13.4.1 ASIA PACIFIC: DOCUMENT AI MARKET DRIVERS
- 13.4.2 ASIA PACIFIC: MACROECONOMIC OUTLOOK
- 13.4.3 CHINA
- 13.4.3.1 National digital ecosystem and e-government push to fuel demand for Document AI
- 13.4.4 INDIA
- 13.4.4.1 Digital governance and rapid cloud adoption to power Document AI uptake
- 13.4.5 JAPAN
- 13.4.5.1 Workforce automation and paperless initiatives to drive Document AI adoption
- 13.4.6 SOUTH KOREA
- 13.4.6.1 High digital readiness and AI integration to fuel market
- 13.4.7 ASEAN
- 13.4.7.1 Digital trade integration and paperless workflows to strengthen market
- 13.4.8 REST OF ASIA PACIFIC
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 MIDDLE EAST & AFRICA: DOCUMENT AI MARKET DRIVERS
- 13.5.2 MIDDLE EAST & AFRICA: MACROECONOMIC OUTLOOK
- 13.5.3 SAUDI ARABIA
- 13.5.3.1 National digitalization and Vision 2030 to catalyze Document AI ecosystem
- 13.5.4 UAE
- 13.5.4.1 Early government adoption and smart infrastructure programs to drive Document AI leadership
- 13.5.5 SOUTH AFRICA
- 13.5.5.1 Urban enterprise digitalization and BFSI modernization to fuel the market
- 13.5.6 TURKEY
- 13.5.6.1 National AI strategy and digital infrastructure investments to strengthen market
- 13.5.7 REST OF MIDDLE EAST & AFRICA
- 13.6 LATIN AMERICA
- 13.6.1 LATIN AMERICA: DOCUMENT AI MARKET DRIVERS
- 13.6.2 LATIN AMERICA: MACROECONOMIC OUTLOOK
- 13.6.3 BRAZIL
- 13.6.3.1 Strict e-invoicing regulations and tax modernization programs to drive market
- 13.6.4 MEXICO
- 13.6.4.1 Tax digitalization and e-signature expansion to accelerate Document AI adoption
- 13.6.5 REST OF LATIN AMERICA
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2022-2026
- 14.3 REVENUE ANALYSIS, 2021-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.4.1 MARKET RANKING ANALYSIS, 2025
- 14.5 PRODUCT COMPARISON
- 14.5.1 PRODUCT COMPARATIVE ANALYSIS, BY DOCUMENT AI SOLUTION TYPE (IDP)
- 14.5.2 PRODUCT COMPARATIVE ANALYSIS, BY DOCUMENT AI SOLUTION TYPE (DOCUMENT WORKFLOW AUTOMATION)
- 14.5.3 PRODUCT COMPARATIVE ANALYSIS, BY DOCUMENT AI SOLUTION TYPE (GEN AI DOCUMENT GENERATION)
- 14.5.4 PRODUCT COMPARATIVE ANALYSIS, BY DOCUMENT AI SOLUTION TYPE (ECM & GOVERNANCE TOOLS)
- 14.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.6.1 IDP, DOCUMENT WORKFLOW AUTOMATION, AND ECM & GOVERNANCE TOOLS
- 14.6.1.1 Stars
- 14.6.1.2 Emerging leaders
- 14.6.1.3 Pervasive players
- 14.6.1.4 Participants
- 14.6.2 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.6.2.1 Company footprint
- 14.6.2.2 Regional footprint
- 14.6.2.3 Offering footprint
- 14.6.2.4 Use case footprint
- 14.6.2.5 Vertical footprint
- 14.6.3 GENERATIVE AI DOCUMENT GENERATION
- 14.6.3.1 Stars
- 14.6.3.2 Emerging leaders
- 14.6.3.3 Pervasive players
- 14.6.3.4 Participants
- 14.6.4 COMPANY FOOTPRINT: KEY PLAYERS (GENERATIVE AI DOCUMENT GENERATION), 2025
- 14.6.4.1 Company footprint
- 14.6.4.2 Regional footprint
- 14.6.4.3 Offering footprint
- 14.6.4.4 Use case footprint
- 14.6.4.5 Vertical footprint
- 14.6.1 IDP, DOCUMENT WORKFLOW AUTOMATION, AND ECM & GOVERNANCE TOOLS
- 14.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.7.1 PROGRESSIVE COMPANIES
- 14.7.2 RESPONSIVE COMPANIES
- 14.7.3 DYNAMIC COMPANIES
- 14.7.4 STARTING BLOCKS
- 14.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.7.5.1 Detailed list of key startups/SMEs
- 14.7.5.2 Competitive benchmarking of key startups/SMEs
- 14.8 COMPANY VALUATION AND FINANCIAL METRICS
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES AND ENHANCEMENTS
- 14.9.2 DEALS
15 COMPANY PROFILES
- 15.1 INTRODUCTION
- 15.2 INTELLIGENT DOCUMENT PROCESSING
- 15.2.1 KEY PLAYERS
- 15.2.1.1 Google
- 15.2.1.1.1 Business overview
- 15.2.1.1.2 Products/Solutions/Services offered
- 15.2.1.1.3 Recent developments
- 15.2.1.1.3.1 Product launches and enhancements
- 15.2.1.1.3.2 Deals
- 15.2.1.1.4 MnM view
- 15.2.1.1.4.1 Key strengths
- 15.2.1.1.4.2 Strategic choices
- 15.2.1.1.4.3 Weaknesses and competitive threats
- 15.2.1.2 Microsoft
- 15.2.1.2.1 Business overview
- 15.2.1.2.2 Products/Solutions/Services offered
- 15.2.1.2.3 Recent developments
- 15.2.1.2.3.1 Product launches and enhancements
- 15.2.1.2.3.2 Deals
- 15.2.1.2.4 MnM view
- 15.2.1.2.4.1 Key strengths
- 15.2.1.2.4.2 Strategic choices
- 15.2.1.2.4.3 Weaknesses and competitive threats
- 15.2.1.3 IBM
- 15.2.1.3.1 Business overview
- 15.2.1.3.2 Products/Solutions/Services offered
- 15.2.1.3.3 Recent developments
- 15.2.1.3.3.1 Product launches and enhancements
- 15.2.1.3.3.2 Deals
- 15.2.1.3.4 MnM view
- 15.2.1.3.4.1 Key strengths
- 15.2.1.3.4.2 Strategic choices
- 15.2.1.3.4.3 Weaknesses and competitive threats
- 15.2.1.4 AMAZON.COM, INC.
- 15.2.1.4.1 Business overview
- 15.2.1.4.2 Products/Solutions/Services offered
- 15.2.1.4.3 Recent developments
- 15.2.1.4.3.1 Product launches and enhancements
- 15.2.1.4.3.2 Deals
- 15.2.1.4.4 MnM view
- 15.2.1.4.4.1 Key strengths
- 15.2.1.4.4.2 Strategic choices
- 15.2.1.4.4.3 Weaknesses and competitive threats
- 15.2.1.5 Oracle
- 15.2.1.5.1 Business overview
- 15.2.1.5.2 Products/Solutions/Services offered
- 15.2.1.5.3 Recent developments
- 15.2.1.5.3.1 Product launches and enhancements
- 15.2.1.5.3.2 Deals
- 15.2.1.5.4 MnM view
- 15.2.1.5.4.1 Key strengths
- 15.2.1.5.4.2 Strategic choices
- 15.2.1.5.4.3 Weaknesses and competitive threats
- 15.2.1.6 Adobe
- 15.2.1.6.1 Business overview
- 15.2.1.6.2 Products/Solutions/Services offered
- 15.2.1.6.3 Recent developments
- 15.2.1.6.3.1 Product launches and enhancements
- 15.2.1.6.3.2 Deals
- 15.2.1.7 UiPath
- 15.2.1.7.1 Business overview
- 15.2.1.7.2 Products/Solutions/Services offered
- 15.2.1.7.3 Recent developments
- 15.2.1.7.3.1 Product launches and enhancements
- 15.2.1.7.3.2 Deals
- 15.2.1.8 Appian
- 15.2.1.8.1 Business overview
- 15.2.1.8.2 Products/Solutions/Services offered
- 15.2.1.8.3 Recent developments
- 15.2.1.8.3.1 Product launches and enhancements
- 15.2.1.8.3.2 Deals
- 15.2.1.9 Salesforce, Inc.
- 15.2.1.9.1 Business overview
- 15.2.1.9.2 Products/Solutions/Services offered
- 15.2.1.9.3 Recent developments
- 15.2.1.9.3.1 Product launches & enhancements
- 15.2.1.9.3.2 Deals
- 15.2.1.10 ABBYY
- 15.2.1.10.1 Business overview
- 15.2.1.10.2 Products/Solutions/Services offered
- 15.2.1.10.3 Recent developments
- 15.2.1.10.3.1 Product launches and enhancements
- 15.2.1.10.3.2 Deals
- 15.2.1.11 Automation Anywhere
- 15.2.1.11.1 Business overview
- 15.2.1.11.2 Products/Solutions/Services offered
- 15.2.1.11.3 Recent developments
- 15.2.1.11.3.1 Product launches and enhancements
- 15.2.1.11.3.2 Deals
- 15.2.1.12 Hyland
- 15.2.1.12.1 Business overview
- 15.2.1.12.2 Products/Solutions/Services offered
- 15.2.1.12.3 Recent developments
- 15.2.1.12.3.1 Product launches and enhancements
- 15.2.1.12.3.2 Deals
- 15.2.1.13 Snowflake
- 15.2.1.14 EdgeVerve (Infosys)
- 15.2.1.15 Tungsten Automation
- 15.2.1.16 OpenText
- 15.2.1.17 SAP
- 15.2.1.18 EXL
- 15.2.1.19 Scribe
- 15.2.1.20 Docketry
- 15.2.1.21 Cohere
- 15.2.1.22 Hyperscience
- 15.2.1.23 SER Group
- 15.2.1.1 Google
- 15.2.2 OTHER PLAYERS
- 15.2.2.1 Grooper
- 15.2.2.2 DocDigitizer
- 15.2.2.3 Super.ai
- 15.2.2.4 Cinnamon AI
- 15.2.2.5 Docugami
- 15.2.2.6 DocByte
- 15.2.2.7 Infrrd
- 15.2.2.8 Rossum
- 15.2.2.9 Docubee
- 15.2.2.10 Docsumo
- 15.2.2.11 Checkbox
- 15.2.2.12 Mindee
- 15.2.1 KEY PLAYERS
- 15.3 GENERATIVE AI DOCUMENT GENERATION
- 15.3.1 KEY PLAYERS
- 15.3.1.1 OpenAI
- 15.3.1.1.1 Business overview
- 15.3.1.1.2 Products/Solutions/Services offered
- 15.3.1.1.3 Recent developments
- 15.3.1.1.3.1 Product launches and enhancements
- 15.3.1.1.3.2 Deals
- 15.3.1.2 Gamma
- 15.3.1.3 Upstage
- 15.3.1.4 Aidocmaker
- 15.3.1.5 Anthropic
- 15.3.1.6 Mistral AI
- 15.3.1.7 DocuPilot
- 15.3.1.8 Intellistack
- 15.3.1.9 HyperWrite (OthersideAI)
- 15.3.1.10 Lindy
- 15.3.1.11 Quillbot
- 15.3.1.1 OpenAI
- 15.3.1 KEY PLAYERS
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Breakup of primary profiles
- 16.1.2.2 Key industry insights
- 16.2 MARKET BREAKUP AND DATA TRIANGULATION
- 16.3 MARKET SIZE ESTIMATION
- 16.3.1 TOP-DOWN APPROACH
- 16.3.2 BOTTOM-UP APPROACH
- 16.4 MARKET FORECAST
- 16.5 RESEARCH ASSUMPTIONS
- 16.6 RESEARCH LIMITATIONS
17 ADJACENT AND RELATED MARKETS
- 17.1 INTRODUCTION
- 17.2 ARTIFICIAL INTELLIGENCE MARKET - GLOBAL FORECAST TO 2032
- 17.2.1 MARKET DEFINITION
- 17.2.2 MARKET OVERVIEW
- 17.2.2.1 Artificial intelligence (AI) market, by offering
- 17.2.2.2 Artificial intelligence (AI) market, by technology
- 17.2.2.3 Artificial intelligence (AI) market, by business function
- 17.2.2.4 Artificial intelligence (AI) market, by enterprise application
- 17.2.2.5 Artificial intelligence (AI) market, by end user
- 17.2.2.6 Artificial intelligence (AI) market, by region
- 17.3 AI DETECTOR MARKET - GLOBAL FORECAST TO 2030
- 17.3.1 MARKET DEFINITION
- 17.3.2 MARKET OVERVIEW
- 17.3.2.1 AI detector market, by offering
- 17.3.2.2 AI detector market, by detection modality
- 17.3.2.3 AI detector market, by application
- 17.3.2.4 AI detector market, by end user
- 17.3.2.5 AI detector market, by region
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS


