

|
시장보고서
상품코드
2138096
고무 가공유 시장 : 점도별, 용도별, 유형별, 지역별 - 세계 예측(-2031년)Rubber Process Oil Market by Type (Naphthenic, Paraffinic, TDAE, DAE, MES, RAE, and TRAE), Application (Tires, Industrial Rubber Products, Oil-extended Polymers, and Thermoplastic Elastomers), Viscosity, and Region - Global Forecast to 2031 |
||||||

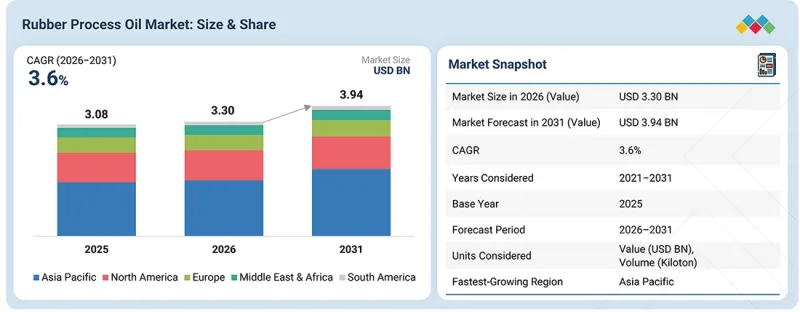
세계의 고무 가공유 시장 규모는 2026년 33억 달러에서 2031년까지 39억 4,000만 달러로 확대될 것으로 예상되며, 예측 기간 동안 연평균 성장률(CAGR)은 3.6%에 달할 것으로 전망됩니다.
고무 가공유는 천연 고무 및 합성 고무 컴파운드의 가공성과 성능 특성을 향상시키는 데 있어 매우 중요한 역할을 하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(100만 달러) 및 킬로톤 |
| 부문 | 점도별, 용도별, 유형별, 지역별 |
| 대상 지역 | 북미, 아시아태평양, 유럽, 중동 및 아프리카, 남미 |
이러한 오일은 충전제의 분산성을 높이고, 점도를 낮추며, 보다 원활한 혼합 작업을 가능하게함으로써 타이어, 산업용 고무 제품, 열가소성 엘라스토머 및 오일 연신 폴리머의 안정적인 생산을 뒷받침하고 있습니다. 시장은 배합 요건의 변화에 따라 점점 더 형성되고 있으며, 각 제조사는 진화하는 규제 기준과 성능에 대한 기대에 부응하기 위해 더 깨끗하고 PAH 함량이 낮으며 용도에 특화된 오일에 주력하고 있습니다. 고무 배합이 더욱 전문화되고 생산 라인에 높은 효율성이 요구됨에 따라, 점도 범위나 추출 유형에 관계없이 용도에 맞는 RPO 등급의 중요성은 꾸준히 높아지고 있습니다.
“유형별로는 처리된 증류분 방향족 추출물(TDAE) 부문이 예측 기간 동안 두 번째로 큰 점유율을 차지할 것으로 전망됩니다.”
처리된 증류분 방향족 추출물(TDAE) 부문은 고무 가공유 시장에서 두 번째로 큰 점유율을 차지할 것으로 추정됩니다. TDAE는 성능, 안전성, 비용의 균형이 뛰어나 다양한 고무 용도에서 선호되는 선택지가 되고 있습니다. 규제 기준에 따라 고농도 PAH를 함유한 방향족 오일의 사용이 단계적으로 축소되는 가운데, 많은 타이어 및 산업용 고무 제조업체들은 더 안전하고 규제를 준수하는 대체재로 TDAE를 채택하고 있습니다. TDAE는 기존 배합에 요구되는 가공 용이성, 탄성 향상 및 상용성을 여전히 제공합니다. 컴파운드의 부드러움을 유지하고, 분산성을 높이며, 뛰어난 구름 특성과 내열성을 지원하는 능력 덕분에 TDAE는 표준 및 중성능 타이어 두 부문 모두에서 신뢰할 수 있는 선택지가 되고 있습니다. 동시에, 구하기 쉽고 가격이 합리적이어서 대량 생산을 하는 제조사에게도 활용하기 쉬운 제품입니다. 규제 준수, 성능의 신뢰성, 비용 효율성을 모두 갖추고 있어 TDAE는 RPO 시장에서 2위의 시장 점유율을 차지하고 있으며, 타이어 및 비타이어용 고무 제품 모두에서 안정적인 수요가 예상됩니다.
“용도별로는 예측 기간 동안 산업용 고무 제품 부문이 두 번째로 큰 시장 점유율을 차지할 것으로 전망됩니다.”
산업용 고무 제품 부문은 벨트, 호스, 개스킷, 씰, 성형 부품 등의 제품에 널리 사용되고 있어, 예측 기간 동안 고무 가공유의 용도 중 2위 규모를 차지할 것으로 전망됩니다. 고무 가공유는 유연성을 높이고, 충전제의 분산성을 향상시키며, 일관된 가공 성능을 확보하기 위해 산업용 고무 제조에 필수적인 요소입니다. 이 부문은 산업화, 인프라 개발 및 다양한 산업 분야에서 내구성과 고성능을 갖춘 고무 부품에 대한 수요에 힘입어 안정적인 수요의 혜택을 누리고 있습니다. 또한, 각 제조사는 제품 성능을 유지하면서 환경 기준 및 규제 기준을 충족하기 위해 고품질이면서 PAH 함량이 낮은 오일의 채택을 확대하고 있습니다. 타이어 제조는 총 생산량이 많기 때문에 여전히 최대의 용도 부문이지만, 산업용 고무는 반복적으로 사용된다는 점, 폭넓은 적용성, 그리고 성능이 최적화되고 규제를 준수하는 오일에 대한 수요 증가로 인해 확고한 입지를 유지하고 있습니다.
“예측 기간 동안 북미는 두 번째로 큰 시장 점유율을 차지할 것으로 전망됩니다.”
북미는 강력한 자동차 제조 기반, 대규모 교체용 타이어 시장, 그리고 확립된 산업용 고무 부문을 배경으로 고무 가공유 시장에서 2위 규모를 차지할 것으로 예측됩니다. 이 지역은 타이어, 벨트,호스, 개스킷, 성형 고무 부품 등의 생산이 성숙 단계에 이르렀으며, 이들 모두는 안정적이고 고품질의 고무 가공유에 크게 의존하고 있습니다. 고성능 및 특수 고무 소재 분야의 선진적인 제품 개발 또한 TDAE 및 저 PAH 배합을 포함한, 더 깨끗하고 정제도가 높은 RPO 등급에 대한 꾸준한 수요를 견인하고 있습니다. 또한, 이 지역의 엄격한 규제 환경은 더 안전하고 환경 친화적인 오일 사용을 촉진하여, 고부가가치형 RPO로의 전환을 뒷받침하고 있습니다. 안정적인 정제 기반, 고품질 소재에 대한 고객의 강한 선호, 그리고 고무 가공 기술의 지속적인 향상으로 인해 북미는 지속적인 산업 활동과 견고한 자동차 생태계에 힘입어 지역별 시장 중 2위의 규모를 확립하고 있습니다.
Sinopec(중국), Exxon Mobil Corporation(미국), PetroChina Company Limited(중국), Chevron Corporation(미국), 그리고 Shell plc(영국)는 고무 가공유 시장의 주요 참여 기업입니다.
조사 범위:
본 보고서에서는 고무 가공유 시장을 종류, 점도, 용도, 지역별로 세분화하고 있습니다. 또한, 시장 성장에 영향을 미치는 주요 요인(촉진요인, 억제요인, 기회, 과제 등)에 대한 상세한 정보를 제공합니다. 더불어, 고무 가공유 제조업체를 전략적으로 분석하여 시장 점유율과 핵심 경쟁력을 포괄적으로 평가하고 있습니다.
본 보고서를 구매해야 하는 이유:
본 보고서는 고무 가공유 시장 및 각 부문의 매출에 대해 가장 정확한 추정치를 제공함으로써, 시장을 선도하는 기업과 신규 진입 기업을 지원하는 데 기여할 것으로 기대됩니다. 또한, 본 보고서는 이해관계자가 시장의 경쟁 구도를 더 깊이 이해하고, 자사의 사업 위치를 향상시키기 위한 인사이트를 얻어 적절한 시장 진입 전략을 수립하는 데 도움이 될 것으로 기대됩니다. 아울러, 이해관계자가 시장 동향을 파악할 수 있도록 지원하는 동시에 주요 시장 촉진요인, 억제요인, 과제 및 기회에 관한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인 분석(승용차, 중·대형 상용차(MHCV), 오프로드 차량을 포함한 전 세계 자동차 생산 증가에 더해, 애프터마켓에서의 타이어 교체 증가가 타이어 생산을 끌어올리고, 고무 가공유 수요를 견인하고 있습니다. 또한, 합성 고무 생산 확대, 저PAH, 저점도 및 특수 오일에 대한 수요 증가), 제약요인(방향족 RPO에 대한 전 세계적인 엄격한 규제(EU, 미국, 중국),바이오 기반/지속가능한 가소제로의 대체, 적절한 그룹 I/II 기유 확보의 어려움), 기회(친환경/생분해성 고무용 오일에 대한 수요 증가; 아시아, 중동 및 아프리카(MEA), 동유럽의 신규 타이어 공장 투자; 고급차 및 전기자동차 수요 증가에 따른 고성능 타이어 수요 확대), 그리고 과제(원유 유래 증류분 및 방향족 추출물 등 주요 RPO 원료 가격 변동)
- 제품 개발 및 혁신 : 고무 공정 오일 시장의 향후 기술 동향 및 연구 개발 활동에 대한 상세한 분석
- 시장 동향 : 수익성이 높은 시장에 대한 종합적인 정보 - 본 보고서는 다양한 지역의 고무 가공유 시장을 분석합니다.
- 경쟁 분석 : 고무 가공유 시장에서 Sinopec(중국), Exxon Mobil Corporation(미국), PetroChina Company Limited(중국), Chevron Corporation(미국), Shell plc(영국) 등 주요 기업의 시장 점유율, 성장 전략, 제품 라인업에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 고무 가공유 시장(점도별)
제10장 고무 가공유 시장(용도별)
제11장 고무 가공유 시장(유형별)
제12장 고무 가공유 시장(지역별)
제13장 경쟁 구도
제14장 기업 개요
제15장 조사 방법
제16장 부록
KSM 26.10.08The global rubber process oil market is projected to grow from USD 3.30 billion in 2026 to USD 3.94 billion by 2031, at a CAGR of 3.6% during the forecast period. Rubber process oils play a critical role in improving the processing behavior and performance characteristics of both natural and synthetic rubber compounds.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million) and Volume (Kiloton) |
| Segments | Type, Viscosity, and Application |
| Regions covered | North America, Asia Pacific, Europe, Middle East & Africa, and South America |
By enhancing filler dispersion, reducing viscosity, and enabling smoother mixing operations, these oils support consistent production of tires, industrial rubber goods, thermoplastic elastomers, and oil-extended polymers. The market is increasingly shaped by shifting formulation requirements, where manufacturers are focusing on cleaner, low-PAH, and more application-specific oils to meet evolving regulatory norms and performance expectations. As rubber formulations become more specialized and production lines demand higher efficiency, the relevance of tailored RPO grades-across viscosity ranges and extract types-continues to grow steadily.
"By type, treated distillate aromatic extract (TDAE) segment to account for the second-largest share during the forecast period."
The treated distillate aromatic extract (TDAE) segment is estimated to account for the second-largest share of the rubber process oil market. TDAE strikes a strong balance between performance, safety, and cost, making it a preferred choice for a wide range of rubber applications. As regulatory norms continue to phase down high-PAH aromatic oils, many tire and industrial rubber manufacturers are adopting TDAE as a safer and more compliant alternative, yet one that still offers the processing ease, elasticity improvement, and compatibility required in traditional formulations. Its ability to maintain compound softness, enhance dispersion, and support better rolling and heat-resistance characteristics has made it a dependable option for both standard and mid-performance tire categories. At the same time, its availability and affordability keep it accessible for large-volume producers. This combination of regulatory alignment, performance reliability, and cost suitability has positioned TDAE as the second-largest segment in the RPO market, with steady demand across both tire and non-tire rubber products.
"By application, industrial rubber products segment to account for the second-largest market share during the forecast period."
The industrial rubber products segment is projected to be the second-largest application of rubber process oil during the forecast period due to its wide use in products such as belts, hoses, gaskets, seals, and molded components. Rubber process oils enhance flexibility, improve filler dispersion, and ensure consistent processing performance, making them essential for industrial rubber manufacturing. The segment benefits from steady demand driven by industrialization, infrastructure development, and the need for durable and high-performance rubber components across multiple sectors. Additionally, manufacturers increasingly adopt high-quality, low-PAH oils to meet environmental and regulatory standards while maintaining product performance. Although tire manufacturing remains the largest application segment due to higher overall volume, industrial rubber maintains a strong position because of recurring usage, broad applicability, and rising demand for performance-optimized, regulation-compliant oils.
"North America to account for the second-largest market share during the forecast period."
North America is projected to be the second-largest market for rubber process oil because of its strong automotive manufacturing base, large replacement tire market and well-established industrial rubber sector. The region benefits from mature production of tires, belts, hoses, gaskets, and molded rubber components, all of which rely heavily on consistent, high-quality rubber process oils. Advanced product development in high-performance and specialty rubber materials also drives steady demand for cleaner and more refined RPO grades, including TDAE and low-PAH formulations. In addition, the region's robust regulatory environment encourages safer, environmentally aligned oils, reinforcing the shift toward higher-value RPO types. A stable refining base, strong customer preference for premium-quality materials, and continuous upgrades in rubber processing technologies collectively position North America as the second-largest regional market, supported by sustained industrial activity and a strong automotive ecosystem.
Profile breakdown of primary participants for the report:
- By Company Type: Tier 1 - 65%, Tier 2 - 20%, and Tier 3 - 15%
- By Designation: Directors - 25%, Managers - 30%, and Others - 45%
- By Region: North America - 30%, Asia Pacific - 40%, Europe - 20%, Middle East & Africa - 7%, and South America - 3%
Sinopec (China), Exxon Mobil Corporation (US), PetroChina Company Limited (China), Chevron Corporation (US), and Shell plc (UK) are among the major players in the rubber process oil market.
Research Coverage:
The report segments the rubber process oil market based on type, viscosity, application, and region. It provides detailed information regarding the major factors influencing the market's growth, such as drivers, restraints, opportunities, and challenges. It strategically profiles rubber process oil manufacturers, comprehensively analyzing their market shares and core competencies.
Reasons to Buy the Report:
The report is expected to help market leaders/new entrants by providing them with the closest approximations of revenue numbers for the rubber process oil market and its segments. This report is also expected to help stakeholders obtain an improved understanding of the market's competitive landscape, gain insights to improve the position of their businesses, and make suitable go-to-market strategies. It also enables stakeholders to understand the market's pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of critical drivers (rising global vehicle production-including passenger cars, MHCVs, and off-highway vehicles-along with increasing aftermarket tire replacements, is boosting tire output and driving demand for rubber process oils; growth in synthetic rubber production; rising demand for low-PAH, low-viscosity, and specialty oils), restraints (stringent global regulations on aromatic RPO (EU, US, China), substitution by bio-based/sustainable plasticizers, declining availability of suitable Group I/II base oils), opportunities (rising demand for green/biodegradable rubber oils; new tire plant investments across Asia, MEA, and Eastern Europe; rising demand for luxury vehicles and electric cars boosting need for high-performance tires), and challenges (fluctuating prices of key RPO feedstocks such as crude-derived distillates and aromatic extracts)
- Product Development/Innovation: Detailed insights on upcoming technologies and research & development activities in the rubber process oil market
- Market Development: Comprehensive information about lucrative markets - the report analyses the rubber process oil market across varied regions.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and product offerings of leading players such as Sinopec (China), Exxon Mobil Corporation (US), PetroChina Company Limited (China), Chevron Corporation (US), and Shell plc (UK) in the rubber process oil market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.3.5 UNITS CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN RUBBER PROCESS OIL MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN RUBBER PROCESS OIL MARKET
- 3.2 RUBBER PROCESS OIL MARKET, BY REGION
- 3.3 RUBBER PROCESS OIL MARKET, BY TYPE
- 3.4 RUBBER PROCESS OIL MARKET, BY KEY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising global vehicle production, along with increasing aftermarket tire replacements, boosting tire output
- 4.2.1.2 Growth in synthetic rubber production
- 4.2.1.3 Rising demand for low-PAH, low-viscosity, and specialty oils
- 4.2.2 RESTRAINTS
- 4.2.2.1 Stringent global regulations on aromatic RPO (EU, US, China)
- 4.2.2.2 Substitution by bio-based/sustainable plasticizers
- 4.2.2.3 Declining availability of suitable Group I/II base oils
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Rising demand for green/biodegradable rubber oils
- 4.2.3.2 New tire plant investments across Asia, MEA, and Eastern Europe
- 4.2.3.3 Rising demand for luxury vehicles and electric cars boosting need for high-performance tires
- 4.2.4 CHALLENGES
- 4.2.4.1 Fluctuating prices of key RPO feedstocks, such as crude-derived distillates and aromatic extracts
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN RUBBER PROCESS OIL MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF NEW ENTRANTS
- 5.1.4 THREAT OF SUBSTITUTES
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 GDP TRENDS AND FORECAST
- 5.2.2 TRENDS IN GLOBAL RUBBER PROCESS OIL INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.3.1 RAW MATERIAL SUPPLY
- 5.3.2 RUBBER PROCESS OIL PRODUCTION
- 5.3.3 RUBBER PROCESS OIL TYPES
- 5.3.4 DISTRIBUTORS
- 5.3.5 END-USE INDUSTRIES
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND OF RUBBER PROCESS OIL, BY REGION, 2022-2025
- 5.5.2 AVERAGE SELLING PRICE OF RUBBER PROCESS OIL TYPE, BY KEY PLAYER, 2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 2709)
- 5.6.2 EXPORT SCENARIO (HS CODE 2709)
- 5.7 KEY CONFERENCES AND EVENTS, 2025-2026
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 RRII (RUBBER RESEARCH INSTITUTE) - INDIAN OIL COLLABORATION ON ADVANCED RUBBER PROCESS OIL APPLICATIONS
- 5.10.2 REPSOL'S BIOEXTENSOIL - A CIRCULAR AND HIGH-PERFORMANCE ALTERNATIVE TO MINERAL RUBBER PROCESS OILS
- 5.10.3 SHELL FLAVEX 595 - ENABLING COMPLIANCE AND HIGH-PERFORMANCE TIRE MANUFACTURING
- 5.11 TRUMP TARIFF IMPACT ON RUBBER PROCESS OIL MARKET
- 5.11.1 KEY TARIFF RATES IMPACTING MARKET
- 5.11.2 PRICE IMPACT ANALYSIS
- 5.11.3 KEY IMPACT ON VARIOUS REGIONS
- 5.11.3.1 US
- 5.11.3.2 Europe
- 5.11.3.3 Asia Pacific
- 5.11.4 IMPACT ON END-USE INDUSTRIES OF RUBBER PROCESS OIL MARKET
- 5.11.4.1 Tires
- 5.11.4.2 Oil-extended polymers
- 5.11.4.3 Industrial rubber products
- 5.11.4.4 Thermoplastic elastomers (TPEs)
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 BIO-BASED RUBBER PROCESS OILS
- 6.1.1.1 Introduction: A shift toward sustainable processing oils
- 6.1.1.2 Renewable feedstocks driving material transformation
- 6.1.1.3 Regulatory alignment and industry-wide adoption momentum
- 6.1.1.4 Market impact and long-term strategic relevance
- 6.1.1 BIO-BASED RUBBER PROCESS OILS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 ADVANCED ADDITIVES FOR ENHANCED PERFORMANCE IN RUBBER PROCESS OILS
- 6.2.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.2.1 Short-term (2025-2027) | process efficiency & low-PCA compliance
- 6.2.2.2 Mid-term (2027-2030) | sustainability transition & value-added formulations
- 6.2.2.3 Long-term (2030-2035+) | circularity, high-performance synthesis & next-gen RPO
- 6.3 PATENT ANALYSIS
- 6.3.1 METHODOLOGY
- 6.4 FUTURE APPLICATIONS
- 6.4.1 TIRES: ENHANCED FLEXIBILITY AND PROCESSING EFFICIENCY
- 6.4.2 OIL-EXTENDED POLYMERS: IMPROVED POLYMER FLOW AND REDUCED VISCOSITY
- 6.4.3 INDUSTRIAL RUBBER PRODUCTS: SUPPORTED ELASTICITY AND UNIFORM COMPOUNDING
- 6.4.4 THERMOPLASTIC ELASTOMERS (TPE): FACILITATED SOFTENING AND MELT-FLOW BEHAVIOR
- 6.5 IMPACT OF GENERATIVE AI ON RUBBER PROCESS OIL MARKET
- 6.5.1 INTRODUCTION
- 6.5.2 AI-DRIVEN FORMULATION INNOVATION
- 6.5.3 SMART MANUFACTURING AND PROCESS OPTIMIZATION
- 6.5.4 MARKET INSIGHT AND PRODUCT POSITIONING
- 6.5.5 CUSTOMER COLLABORATION AND VALUE-ADDED SERVICES
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT AND ECO-APPLICATIONS OF RUBBER PROCESS OIL
- 7.2.1.1 Carbon Impact Reduction
- 7.2.1.2 Eco-applications
- 7.2.1 CARBON IMPACT AND ECO-APPLICATIONS OF RUBBER PROCESS OIL
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN THE BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS APPLICATIONS
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 RUBBER PROCESS OIL MARKET, BY VISCOSITY
- 9.1 INTRODUCTION
- 9.2 LOW VISCOSITY
- 9.2.1 GROWING FOCUS ON EFFICIENT, EASY-PROCESSING RUBBER FORMULATIONS
- 9.3 MEDIUM VISCOSITY
- 9.3.1 BROAD ADAPTABILITY AND CONSISTENT PERFORMANCE
- 9.4 HIGH VISCOSITY
- 9.4.1 RISE IN DEMAND FOR DURABLE, HIGH-PERFORMANCE RUBBER PRODUCTS
10 RUBBER PROCESS OIL MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.2 TIRES
- 10.2.1 RISING DEMAND FOR HIGH-PERFORMANCE, DURABLE, AND ENVIRONMENTALLY COMPLIANT TIRES
- 10.3 OIL-EXTENDED POLYMERS
- 10.3.1 GROWING USE OF OIL-EXTENDED POLYMERS IN HIGH-PERFORMANCE RUBBER PRODUCTS
- 10.4 INDUSTRIAL RUBBER PRODUCTS
- 10.4.1 INCREASING NEED FOR DURABLE, HIGH-PERFORMANCE, AND COMPLIANT INDUSTRIAL RUBBER PRODUCTS
- 10.5 THERMOPLASTIC ELASTOMERS (TPE)
- 10.5.1 RISING ADOPTION OF THERMOPLASTIC ELASTOMERS IN VERSATILE AND HIGH-PERFORMANCE APPLICATIONS
- 10.6 OTHER APPLICATIONS
11 RUBBER PROCESS OIL MARKET, BY TYPE
- 11.1 INTRODUCTION
- 11.2 TREATED DISTILLATE AROMATIC EXTRACT (TDAE)
- 11.2.1 RISING PREFERENCE FOR CLEANER, REGULATION-COMPLIANT, AND HIGH-PERFORMANCE RUBBER PROCESS OILS
- 11.3 DISTILLATE AROMATIC EXTRACT (DAE)
- 11.3.1 CONTINUED USE OF COST-EFFECTIVE, HIGH-SOLVENCY AROMATIC OILS LIKE DAE IN KEY RUBBER PROCESSING APPLICATIONS
- 11.4 MILD EXTRACTED SOLVATE (MES)
- 11.4.1 INCREASING INDUSTRY SHIFT TOWARD LOW-PAH, ENVIRONMENTALLY COMPLIANT, AND PERFORMANCE-STABLE RUBBER PROCESS OILS
- 11.5 RESIDUAL AROMATIC EXTRACT (RAE) AND TREATED RESIDUAL AROMATIC EXTRACT (TRAE)
- 11.5.1 STEADY USE OF RAE AND GROWING ADOPTION OF CLEANER TRAE GRADES
- 11.6 PARAFFINIC
- 11.6.1 RISING NEED FOR CLEAN, THERMALLY STABLE, AND HIGH-PERFORMANCE RUBBER FORMULATIONS
12 RUBBER PROCESS OIL MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 ASIA PACIFIC
- 12.2.1 CHINA
- 12.2.1.1 Increasing vehicle and tire production to drive market
- 12.2.2 JAPAN
- 12.2.2.1 Advanced tire manufacturing and precision-focused industrial rubber production
- 12.2.3 INDIA
- 12.2.3.1 Strong replacement-driven tire growth and expanding industrial rubber production
- 12.2.4 SOUTH KOREA
- 12.2.4.1 Growing vehicle production and strong industrial rubber manufacturing base
- 12.2.5 INDONESIA
- 12.2.5.1 Expansion of industrial rubber manufacturing base and rise in domestic tire demand
- 12.2.6 THAILAND
- 12.2.6.1 Abundant natural rubber resources and growing domestic tire and industrial rubber production
- 12.2.7 REST OF ASIA PACIFIC
- 12.2.1 CHINA
- 12.3 NORTH AMERICA
- 12.3.1 US
- 12.3.1.1 Shift toward electric mobility strengthening demand dynamics for rubber process oils
- 12.3.2 CANADA
- 12.3.2.1 Growth in industrial production base and increasing need for durable, climate-resilient rubber components
- 12.3.3 MEXICO
- 12.3.3.1 Expansion of automotive manufacturing base and rising demand for cost-efficient, high-performance rubber goods
- 12.3.1 US
- 12.4 EUROPE
- 12.4.1 RUSSIA
- 12.4.1.1 Growing tire replacement needs and expanding industrial rubber production
- 12.4.2 GERMANY
- 12.4.2.1 Shift toward electric mobility and strong manufacturing demand for rubber-intensive components
- 12.4.3 UK
- 12.4.3.1 Expanding demand for high-quality rubber components and growing EV-related material production
- 12.4.4 FRANCE
- 12.4.4.1 Rising vehicle registrations and strong demand for tire and industrial rubber components
- 12.4.5 SPAIN
- 12.4.5.1 Rising tire demand and expanding industrial rubber manufacturing
- 12.4.6 ITALY
- 12.4.6.1 Strong tire manufacturing activity and rising demand for industrial rubber components
- 12.4.7 REST OF EUROPE
- 12.4.1 RUSSIA
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.5.1.1 Iran
- 12.5.1.1.1 Expanding domestic tire production, increasing self-sufficiency, and rising output across multiple vehicle segments
- 12.5.1.2 Turkey
- 12.5.1.2.1 Growing tire manufacturing and export activity to drive market
- 12.5.1.1 Iran
- 12.5.2 REST OF MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 Expanding automotive activity, strong tire demand, and broad-based industrial rubber production
- 12.6.2 ARGENTINA
- 12.6.2.1 Sustained tire demand and expanding use of industrial rubber products
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 INTRODUCTION
- 13.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 13.3 REVENUE ANALYSIS
- 13.3.1 TOP 5 PLAYERS' REVENUE ANALYSIS
- 13.4 MARKET SHARE ANALYSIS
- 13.4.1 MARKET SHARE OF KEY PLAYERS
- 13.5 BRAND/PRODUCT COMPARISON
- 13.5.1 POWEROIL FLEXOIL N
- 13.5.2 PANOL C 160-P
- 13.5.3 ENI CELTIS
- 13.5.4 DIVYOL PARAFFINIC OIL
- 13.5.5 CALSOL
- 13.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.6.1 STARS
- 13.6.2 EMERGING LEADERS
- 13.6.3 PERVASIVE PLAYERS
- 13.6.4 PARTICIPANTS
- 13.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.6.5.1 Company footprint
- 13.6.5.2 Region footprint
- 13.6.5.3 Viscosity footprint
- 13.6.5.4 Type footprint
- 13.6.5.5 Application footprint
- 13.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.7.1 PROGRESSIVE COMPANIES
- 13.7.2 RESPONSIVE COMPANIES
- 13.7.3 DYNAMIC COMPANIES
- 13.7.4 STARTING BLOCKS
- 13.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 13.7.5.1 Detailed list of key startups/SMES
- 13.7.5.2 Competitive benchmarking of key startups/SMES
- 13.8 COMPETITIVE SCENARIO
- 13.8.1 PRODUCT LAUNCHES
- 13.9 VALUATION AND FINANCIAL METRICS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 SINOPEC
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 MnM view
- 14.1.1.3.1 Right to win
- 14.1.1.3.2 Strategic choices
- 14.1.1.3.3 Weaknesses and competitive threats
- 14.1.2 PETROCHINA COMPANY LIMITED
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 MnM view
- 14.1.2.3.1 Right to win
- 14.1.2.3.2 Strategic choices
- 14.1.2.3.3 Weaknesses and competitive threats
- 14.1.3 CHEVRON CORPORATION
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 MnM view
- 14.1.3.3.1 Right to win
- 14.1.3.3.2 Strategic choices
- 14.1.3.3.3 Weaknesses and competitive threats
- 14.1.4 EXXON MOBIL CORPORATION
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 MnM view
- 14.1.4.3.1 Right to win
- 14.1.4.3.2 Strategic choices
- 14.1.4.3.3 Weaknesses and competitive threats
- 14.1.5 TOTALENERGIES
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 MnM view
- 14.1.5.3.1 Right to win
- 14.1.5.3.2 Strategic choices
- 14.1.5.3.3 Weaknesses and competitive threats
- 14.1.6 SHELL PLC
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 MnM view
- 14.1.6.3.1 Right to win
- 14.1.6.3.2 Strategic choices
- 14.1.6.3.3 Weaknesses and competitive threats
- 14.1.7 APAR INDUSTRIES LTD.
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.8 PANAMA PETROCHEM LTD.
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.9 BEHRAN OIL CO.
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.10 ENILIVE S.P.A.
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.11 GANDHAR OIL REFINERY (INDIA) LIMITED
- 14.1.11.1 Business overview
- 14.1.11.2 Products/Solutions/Services offered
- 14.1.12 HINDUSTAN PETROLEUM CORPORATION LIMITED
- 14.1.12.1 Business overview
- 14.1.12.2 Products/Solutions/Services offered
- 14.1.13 INDIAN OIL CORPORATION LTD
- 14.1.13.1 Business overview
- 14.1.13.2 Products/Solutions/Services offered
- 14.1.14 ORLEN UNIPETROL GROUP
- 14.1.14.1 Business overview
- 14.1.14.2 Products/Solutions/Services offered
- 14.1.15 IDEMITSU KOSAN CO., LTD.
- 14.1.15.1 Business overview
- 14.1.15.2 Products/Solutions/Services offered
- 14.1.16 REPSOL
- 14.1.16.1 Business overview
- 14.1.16.2 Products/Solutions/Services offered
- 14.1.17 ORGKHIM BIOCHEMICAL HOLDING
- 14.1.17.1 Business overview
- 14.1.17.2 Products/Solutions/Services offered
- 14.1.18 PPL
- 14.1.18.1 Business overview
- 14.1.18.2 Products/Solutions/Services offered
- 14.1.19 IRANOL (LLP)
- 14.1.19.1 Business overview
- 14.1.19.2 Products/Solutions/Services offered
- 14.1.20 PETRO GULF INTERNATIONAL FZE
- 14.1.20.1 Business overview
- 14.1.20.2 Products/Solutions/Services offered
- 14.1.21 CALUMET, INC.
- 14.1.21.1 Business overview
- 14.1.21.2 Products/Solutions/Services offered
- 14.1.22 H&R GROUP
- 14.1.22.1 Business overview
- 14.1.22.2 Products/Solutions/Services offered
- 14.1.23 NYNAS AB
- 14.1.23.1 Business overview
- 14.1.23.2 Products/Solutions/Services offered
- 14.1.23.3 Recent developments
- 14.1.23.3.1 Product Launches
- 14.1.24 IRPC PUBLIC COMPANY LIMITED
- 14.1.24.1 Business overview
- 14.1.24.2 Products/Solutions/Services offered
- 14.1.25 PT. ENERCO RPO INTERNASIONAL
- 14.1.25.1 Business overview
- 14.1.25.2 Products/Solutions/Services offered
- 14.1.26 WITMANS INDUSTRIES PVT. LTD.
- 14.1.26.1 Business overview
- 14.1.26.2 Products/Solutions/Services offered
- 14.1.27 THAIOIL GROUP
- 14.1.27.1 Business overview
- 14.1.27.2 Products/Solutions/Services offered
- 14.1.28 SHANGDONG TIANYUAN CHEMICAL CO., LTD
- 14.1.28.1 Business overview
- 14.1.28.2 Products/Solutions/Services offered
- 14.1.29 P.S.P. SPECIALTIES PUBLIC COMPANY LIMITED
- 14.1.29.1 Business overview
- 14.1.29.2 Products/Solutions/Services offered
- 14.1.1 SINOPEC
- 14.2 OTHER PLAYERS
- 14.2.1 PETRO NAFT
- 14.2.2 PANOL INDUSTRIES RMC FZE
- 14.2.3 EAGLE PETROCHEM
- 14.2.4 LODHA PETRO
- 14.2.5 RLS PETROCHEM LUBRICANTS LLC
- 14.2.6 GAZPROMNEFT - LUBRICANTS LTD.
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 List of primary interview participants (demand and supply sides)
- 15.1.2.3 Key industry insights
- 15.1.2.4 Breakdown of interviews with experts
- 15.1.1 SECONDARY DATA
- 15.2 MATRIX CONSIDERED FOR DEMAND-SIDE ANALYSIS
- 15.3 MARKET SIZE ESTIMATION
- 15.3.1 BOTTOM-UP APPROACH
- 15.3.2 TOP-DOWN APPROACH
- 15.3.2.1 Calculations for supply-side analysis
- 15.4 GROWTH FORECAST
- 15.5 DATA TRIANGULATION
- 15.6 RESEARCH ASSUMPTIONS
- 15.7 RESEARCH LIMITATIONS
- 15.8 RISK ASSESSMENT
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


