

|
시장보고서
상품코드
2146278
환자 체험 테크놀러지 시장 예측(-2031년) : 제품, 기능, 최종사용자, 지역별Patient Experience Technology Market by Offerings, Functions (Appointment {Online Booking}, Registration {Intake}, Virtual Care {Telehealth, RPM}, Communication, Feedback), End User (Providers, Payers, Pharma & Biotech), Region - Global Forecast to 2031 |
||||||

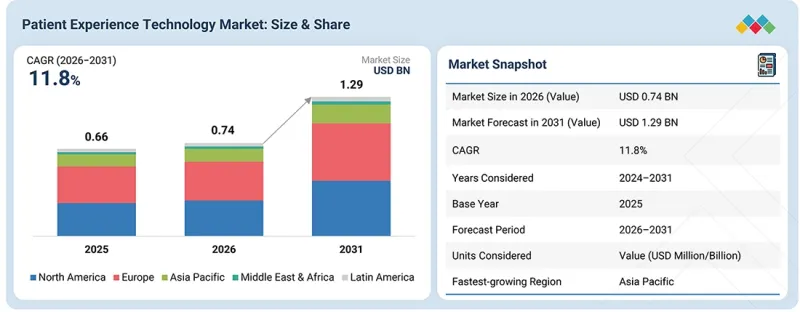
환자 체험 테크놀러지 시장은 2026년 7억 4,000만 달러에서 2031년까지 12억 9,000만 달러로 성장하며, 예측 기간 중 CAGR은 11.8%에 달할 것으로 전망되고 있습니다.
의료 서비스 제공자들이 단일 참여 툴에 의존하기보다는 환자 여정 전반에 걸쳐 기술을 점점 더 도입함에 따라 이 시장은 디지털 전환의 새로운 단계로 접어들고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 제품·기능·최종사용자 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카. |
AI를 활용한 커뮤니케이션, 디지털 환자 포털, 가상 진료, 온라인 예약, 자동 접수, 피드백 관리의 도입이 확대됨에 따라 의료 기관은 접근성 향상, 맞춤형 서비스, 환자 참여도 증대를 실현하고 있습니다. 환자 경험 플랫폼과 EHR(전자 건강 기록), CRM 시스템, 원격의료 플랫폼, 분석 솔루션 간의 통합이 진행됨에 따라 기술 제공업체에게는 더 많은 비즈니스 기회가 창출되고 있습니다. 의료 기관이 환자 중심의 진료, 편의성, 그리고 경험 주도형 성과를 더욱 중시함에 따라 확장 가능하고 지능적인 환자 경험 솔루션에 대한 수요는 예측 기간 중 크게 증가할 것으로 전망됩니다.
"예측 기간 중 소프트웨어/플랫폼 부문 중에서도 클라우드 기반 부문이 특히 높은 성장률을 보일 것으로 전망됩니다."
제공에 따라 환자 경험 기술 시장은 소프트웨어/플랫폼과 서비스로 구분됩니다. 소프트웨어/플랫폼은 온프레미스, 클라우드 기반, 하이브리드로 분류됩니다. 클라우드 기반 플랫폼은 확장성, 낮은 초기 비용, 그리고 업데이트를 신속하게 배포할 수 있는 능력 덕분에 예측 기간 중 상당한 시장 성장이 예상됩니다. 의료 서비스 제공자들은 디지털 체크인, 원격의료를 통한 트리아지, 환자 포털, AI를 활용한 개인 맞춤화 분야에서 클라우드 솔루션을 점점 더 선호하고 있습니다. Press Ganey, Qualtrics, Epic 등의 벤더들은 유연성과 의료 접근성을 향상시키는 클라우드 네이티브 분석 기능, 대화형 AI, 앰비언트 리스닝 툴을 통합하고 있습니다. 예를 들어 2025년 2월 Press Ganey는 Microsoft와 제휴하여 Press Ganey가 보유한 76억 건 이상의 환자 접객 데이터세트와 Microsoft의 AI, 클라우드, 앰비언트 리스닝 툴을 결합한 생성형 AI 기반 솔루션 개발에 착수했습니다. 이번 제휴를 통해 환자 안전을 보장하기 위한 예측 분석, 의료 제공자를 위한 실시간 실용적 인사이트, 그리고 Azure를 통한 안전한 데이터 공유가 가능해졌으며, 클라우드 기반 PX 플랫폼이 개인화, 효율성, 그리고 환자 경험 향상을 주도하고 있음을 입증하고 있습니다.
따라서 이러한 전략적 제휴는 의료 현장 전반에 걸쳐 개인화되고 효율적이며 데이터베이스의 치료를 제공하는 데 있으며, 클라우드 기반 AI 지원 환자 경험 플랫폼이 수행하는 역할이 점점 더 중요해지고 있음을 여실히 보여주고 있습니다.
"최종사용자별로는 예측 기간 중 의료 보험사 부문이 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다."
최종사용자별로는 의료 보험사 부문이 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 의료 보험사들은 가입자의 참여도 향상, 보험금 청구 및 관리 프로세스의 효율화, 그리고 의료 보험 서비스에 대한 전반적인 만족도 향상을 도모하기 위해 환자 경험(PX) 플랫폼에 대한 투자를 점점 더 늘리고 있습니다. 가치 기반 의료 및 성과 주도형 보상 모델에 대한 관심이 높아지는 가운데, 보험사들은 AI, 분석, 환자 피드백 툴을 활용하여 서비스 품질을 모니터링하고, 가입자의 요구를 예측하며, 예방 가능한 의료 서비스 격차를 줄여가고 있습니다.
가입자 포털, 원격 분류(teletriage), 자동 커뮤니케이션 툴 등의 디지털 채널이 도입되어, 개인화된 실시간 지원 제공, 예방 의료 준수율 향상, 그리고 환자 충성도 강화가 도모되고 있습니다. 또한 미국의 ‘Cures Act’나 유럽의 ‘EHDS’ 등 상호 운용성 및 환자 접근성과 관련된 규제 요건으로 인해 보험사들이 환자 경험을 개선하기 위한 기술 도입을 가속화하고 있습니다. 그 결과, 보험사들은 가입자의 경험과 치료 결과에 대한 전략적 중점을 반영하며 시장의 주요 성장 동력으로 부상하고 있습니다.
"북미가 가장 큰 시장 점유율을 차지할 것으로 예상됩니다."
북미는 확립된 의료 IT 인프라, 디지털 헬스 기술의 높은 보급률, 그리고 주요 환자 경험 기술 제공업체들의 강력한 입지에 힘입어 지역 시장을 주도하고 있습니다. 이 지역의 의료 기관들은 환자 만족도와 업무 효율성을 높이기 위해 디지털 환자 참여, 환자 포털, 가상 진료, 자동화된 커뮤니케이션, 피드백 관리, AI를 활용한 경험 분석에 대한 투자를 점점 더 늘리고 있습니다. 환자 중심 치료, 가치 기반 의료, 상호 운용성, 그리고 소비자 지향적 의료 제공에 대한 관심이 높아지고 있는 것이 도입을 더욱 촉진하고 있습니다. 또한 의료 제공자와 기술 기업의 AI 기반 개인화 및 디지털 프론트도어 기능에 대한 지속적인 투자가 이 지역의 생태계를 강화하고 있습니다. 이러한 요인들로 인해 예측 기간 중 북미는 환자 경험 기술 시장에서 주도적인 위치를 유지할 것으로 예상됩니다.
주요 참여 기업의 내역은 다음과 같습니다. :
- 기업 유형별 - Tier 1: 32%, Tier 2: 44%, Tier 3: 24%
- 직책별 - 이사: 30%, 관리자: 34%, 기타: 36%
- 지역별 - 북미: 40%, 유럽: 28%, 아시아태평양: 20%, 라틴아메리카: 7%, 중동 및 아프리카: 5%
주요 기업
환자 경험 기술 시장에서 사업을 운영하는 주요 기업으로는 Press Ganey(미국), National Research Corporation(NRC Health)(미국), Medallia Inc.(미국), Phreesia(미국), NiCE(이스라엘), R1 RCM Inc.(미국),Epic Systems Corporation(미국), IQVIA(미국), Qualtrics(미국), Relias LLC(미국), GetWellNetwork(미국), CipherHealth Inc.(미국), Kyruus, Inc.(미국),Twilio Inc.(미국), Relatient(미국), Alida(캐나다), Certify Health(미국), Avaamo(미국), Luma Health Inc.(미국), Solutionreach(미국), 그리고 Salesforce, Inc.(미국) 등이 있습니다. 이 기업은 환자 경험 기술 시장에서의 입지를 강화하기 위해 전략적 제휴, 협업, 제품 출시, 플랫폼 기능 강화, 기반 모델 및 생성형 AI에 대한 투자, 합병·인수, 그리고 사업 지역 확대와 같은 전략을 채택하고 있습니다.
조사 범위
이 보고서는 환자 경험 기술 시장을 분석합니다. 제공 서비스, 기능, 최종사용자, 지역을 기반으로 다양한 시장 부문 시장 규모와 향후 성장 가능성을 추정하고 있습니다. 또한 시장 성장에 영향을 미치는 촉진요인, 제약 요인, 기회, 과제 등의 요인에 대해서도 분석하고 있습니다. 더불어 환자 경험 기술 생태계 전반에 걸친 기회를 평가하고, 주요 이해관계자들의 경쟁 구도를 평가하고 있습니다. 아울러 이 보고서는 성장 동향, 전망 및 환자 경험 기술 시장 전체에 대한 기여도라는 관점에서 마이크로 마켓을 분석하고 있습니다. 주요 지역별 시장 매출을 예측함과 동시에, 주요 시장 참여 기업에 대해 기업 개요, 제품 포트폴리오, 최근 동향, 주요 성장 전략을 포함한 포괄적인 경쟁 분석을 제공합니다.
이 보고서를 구매해야 하는 이유
이 보고서는 기존 기업, 신규 진입 기업 및 중소기업이 시장 동향을 파악하고 시장 점유율 확대에 활용하는 데 도움이 됩니다. 이 보고서를 구매한 기업은 다음 전략 중 하나 또는 여러 가지를 활용하여 시장내 입지를 강화할 수 있습니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인 분석(디지털 참여 플랫폼 및 맞춤형 환자 치료에 대한 수요 증가, 원격의료,모바일 헬스 앱, AI 기반 분석의 보급, 의료 디지털 전환을 가속화하기 위한 정부 주도의 노력 및 자금 지원, 실시간 피드백 툴을 통한 환자 만족도 및 장기적 참여도 향상에 대한 관심 증가, 그리고 클라우드 기반 참여 플랫폼의 확대),제약 요인(도입을 제한하는 데이터 개인정보 보호 및 사이버 보안에 대한 우려, 의료 제공자에게 발생하는 높은 도입·통합 비용, 환자 참여 시스템과 기존 전자건강기록(EHR) 간의 상호 운용성 제한),기회(의료 인프라가 점차 정비되고 있는 신흥 시장에서의 확대, 환자 치료에 있으며, AI 기반 개인화 및 예측 분석의 도입, 디지털 헬스 보급을 가속화하기 위한 제약 기업 및 보험사와의 제휴 증가, 그리고 환자 교육 및 복약 순응도 강화를 위한 VR/AR 플랫폼의 확대),그리고 과제(환자 피드백 데이터의 정확성과 신뢰성 확보, 지속적인 업데이트와 교육이 필요한 급속한 기술 진화)가 환자 경험 기술 시장의 성장에 영향을 미치고 있습니다
- 제품 개발/혁신: 환자 경험 기술 시장의 향후 기술 동향, 연구개발 활동 및 신제품 출시에 대한 상세 인사이트
- 시장 개발: 수익성이 높은 신흥 시장에 대한 포괄적인 정보(제공 서비스, 기능, 최종사용자, 지역별)
- 시장 다각화: 환자 경험 기술 시장의 제품 포트폴리오, 급성장 중인 지역, 최근 동향 및 투자에 대한 포괄적인 정보
- 경쟁 분석: Press Ganey(미국), National Research Corporation(NRC Health)(미국), Medallia Inc.(미국),Phreesia(미국), NiCE(이스라엘), R1 RCM Inc.(미국), Epic Systems Corporation(미국), IQVIA(미국), Qualtrics(미국), Relias LLC(미국), GetWellNetwork(미국),CipherHealth Inc.(미국), Kyruus, Inc.(미국), Twilio Inc.(미국), Relatient(미국), Alida(캐나다), Certify Health(미국), Avaamo(미국), Luma Health Inc.(미국), Solutionreach(미국),Salesforce, Inc.(미국), Vital(미국), NexHealth(미국), Collectly, Inc.(미국), Business Integrity Services(미국) 및 Bamboo Health(미국)
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 환자 경험 기술 시장의 개요
- 북미: 환자 경험 기술 시장(제공 서비스별·지역별)
- 환자 경험 기술 시장: 지역별 성장 기회
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- 미충족 수요와 미개발 분야
- 상호 연관된 시장 및 부문 간 기회
- Tier 1/2/3 주요 기업의 전략적 움직임
제5장 업계 동향
- Porter's Five Forces 분석
- 공급업체의 협상력
- 구매자의 협상력
- 신규 진입자의 위협
- 대체품의 위협
- 경쟁 기업간 경쟁 관계의 격렬함
- 거시경제 지표
- GDP 동향 및 전망
- 의료의 디지털화와 환자 참여 유도 도입 동향
- 밸류체인 분석
- 제품 설계 및 개발
- 시스템 통합 및 워크플로우 맞춤화
- 도입 및 변경 관리
- 경험 분석 및 보고서를 통한 인사이트
- 사후 서비스 및 지속적인 개선
- 생태계 분석
- 가격 분석
- 주요 기업별 평균 판매 가격 동향
- 지역별 평균 판매 가격 동향
- 2026-2027년 주요 회의 및 행사
- 고객의 비즈니스에 영향을 미치는 동향/파괴적 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- 2025년 미국 관세가 환자 경험 기술 시장에 미치는 영향
- 주요 관세율
- 국가 및 지역에 미치는 영향
- 최종사용자에 미치는 영향
제6장 기술, 특허, 디지털화 및 AI 도입에 따른 전략적 변혁
- 주요 신규 기술
- 환자 목소리(VOP) 플랫폼
- 원격의료 및 가상 진료 플랫폼
- 환자 포털 및 개인 건강 기록
- 원격 환자 모니터링(RPM)
- 보완 기술
- 상호 운용성/API 및 FHIR 인프라
- 환자 ID 관리 및 인증 시스템
- 관련 기술
- 임상의사결정지원시스템(CDSS)
- 집단건강관리(PHM) 플랫폼
- 환자 참여 솔루션
- 기술·제품 로드맵
- 특허 분석
- 특허 공개 동향
- 관할 구역 분석
- 환자 경험 기술 시장의 주요 특허
- 미래 응용 분야
- AI를 활용한 디지털 프론트 도어 및 지능형 환자 내비게이션
- 예측적이고 선견지명 있는 환자 경험 관리
- 개인화되고, 옴니채널이며, 연결된 환자 참여
제7장 규제 현황
- 지역별 규제 및 규정 준수
- 규제 분석
- 업계 기준
제8장 고객 현황과 구매 행동
- 의사결정 과정
- 주요 이해관계자와 구매 기준
- 구매 과정의 주요 이해관계자
- 주요 구매 기준
- 다양한 최종 용도 산업 분야의 미충족 수요
- 미충족 수요
- 최종사용자의 기대
- 시장의 수익성
제9장 환자 경험 기술 시장: 기능별
- 예약 관리
- 환자 등록
- 가상 진료
- 환자와의 소통
- 청구
- 피드백 관리
- 기타 기능
제10장 환자 경험 기술 시장: 제공 유형별
- 소프트웨어
- 서비스
제11장 환자 경험 기술 시장: 최종사용자별
- 의료보험사
- 제약·바이오기술 기업
- 기타 최종사용자
제12장 환자 경험 기술 시장: 지역별
- 북미
- 북미의 거시경제 전망
- 미국
- 캐나다
- 유럽
- 유럽의 거시경제 전망
- 영국
- 독일
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 아시아태평양의 거시경제 전망
- 일본
- 중국
- 인도
- 한국
- 호주
- 기타 아시아태평양
- 라틴아메리카
- 라틴아메리카의 거시경제 전망
- 브라질
- 멕시코
- 기타 라틴아메리카
- 중동 및 아프리카
- 중동 및 아프리카의 거시경제 전망
- GCC 국가들
- 남아프리카
- 기타 중동 및 아프리카
제13장 경쟁 현황
- 개요
- 주요 진입 기업의 전략/강점
- 환자 경험 기술 시장의 주요 업체들이 채택하고 있는 전략 개요
- 수익 분석(2021-2025년)
- 시장 점유율 분석(2025년)
- 기업 평가 및 재무 지표
- 브랜드/소프트웨어 비교
- 기업 평가 매트릭스: 주요 기업, 2025년
- 스타 기업
- 신흥 리더
- 광범위한 영향력을 가진 기업
- 진출 기업
- 기업의 사업 전개: 주요 기업, 2025년
- 기업 평가 매트릭스: 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 스타트업/중소기업의 경쟁사 벤치마킹, 2025년
- 경쟁 시나리오
- 솔루션/서비스 출시
- 거래
- 사업 확장
제14장 기업 개요
- 주요 기업
- PRESS GANEY
- NATIONAL RESEARCH CORPORATION
- MEDALLIA INC.
- PHREESIA
- NICE
- R1
- EPIC SYSTEMS CORPORATION
- IQVIA
- QUALTRICS
- RELIAS LLC
- GETWELLNETWORK, INC.
- CIPHERHEALTH INC.
- KYRUUS, INC.
- RELATIENT
- ALIDA
- TWILIO INC.
- AVAAMO
- CERTIFY HEALTH
- LUMA HEALTH INC.
- SOLUTIONREACH
- SALESFORCE, INC.
- 기타 주요 기업
- VITAL
- NEXHEALTH
- COLLECTLY, INC.
- BUSINESS INTEGRITY SERVICES
- BAMBOO HEALTH
제15장 조사 방법론
제16장 부록
KSA 26.10.19The patient experience technology market is projected to grow from USD 0.74 billion in 2026 to USD 1.29 billion by 2031, at a CAGR of 11.8% during the forecast period. The market is entering a new phase of digital transformation as healthcare providers increasingly adopt technology across the patient journey rather than relying on standalone engagement tools.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Offerings, Functions, End Users |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. |
Growing adoption of AI-powered communication, digital patient portals, virtual care, online appointment scheduling, automated registration, and feedback management is enabling healthcare organizations to improve accessibility, personalization, and patient engagement. Increasing integration of patient experience platforms with EHRs, CRM systems, telehealth platforms, and analytics solutions is further creating opportunities for technology providers. As healthcare organizations place greater emphasis on patient-centric care, convenience, and experience-driven outcomes, demand for scalable and intelligent patient experience solutions is expected to increase substantially over the forecast period.
"The cloud-based segment is projected to register high growth among software/platform segments during the forecast period."
Based on the offerings, the patient experience technology market is segmented into software/platform and services. The software/platform is divided into on-premise, cloud-based, and hybrid. The cloud-based platform is expected to see significant market growth during the forecast period due to its scalability, lower upfront costs, and ability to rapidly deploy updates. Healthcare providers increasingly favor cloud solutions for digital check-ins, telehealth triage, patient portals, and AI-driven personalization. Vendors such as Press Ganey, Qualtrics, and Epic are embedding cloud-native analytics, conversational AI, and ambient listening tools that improve flexibility and care access. For instance, in February 2025, Press Ganey partnered with Microsoft to develop generative AI-powered solutions that combine Press Ganey's dataset of over 7.6 billion patient encounters with Microsoft's AI, cloud, and ambient listening tools. This collaboration enables predictive analytics for patient safety, real-time actionable insights for providers, and secure data sharing via Azure, demonstrating that cloud-based PX platforms are driving personalization, efficiency, and improved patient experience.
Hence, such strategic collaborations underscore the growing role of cloud-based, AI-enabled patient experience platforms in delivering personalized, efficient, and data-driven care across healthcare settings.
"By end user, the healthcare payers segment is expected to grow at the highest CAGR during the forecast period."
By end user, the healthcare payers segment is expected to register the highest CAGR during the forecast period. Payers are increasingly investing in patient experience (PX) platforms to improve member engagement, streamline claims and administrative processes, and enhance overall satisfaction with health plan services. The growing emphasis on value-based care and outcomes-driven reimbursement models is prompting payers to leverage AI, analytics, and patient feedback tools to monitor service quality, predict member needs, and reduce preventable gaps in care.
Digital channels, such as member portals, teletriage, and automated communication tools, are being adopted to provide personalized, real-time support, improve adherence to preventive care, and strengthen patient loyalty. Additionally, regulatory mandates for interoperability and patient access, such as the US Cures Act and Europe's EHDS, are accelerating payer adoption of patient experience technologies. As a result, payers are emerging as a key growth driver in the market, reflecting their strategic focus on member experience and outcomes.
"North America is expected to hold the largest market share."
North America represents the leading regional market, supported by a well-established healthcare IT infrastructure, high adoption of digital health technologies, and a strong presence of leading patient experience technology providers. Healthcare organizations across the region are increasingly investing in digital patient engagement, patient portals, virtual care, automated communication, feedback management, and AI-enabled experience analytics to improve patient satisfaction and operational efficiency. The growing emphasis on patient-centric care, value-based healthcare, interoperability, and consumer-oriented healthcare delivery is further supporting adoption. In addition, continued investments by healthcare providers and technology companies in AI-powered personalization and digital front-door capabilities are strengthening the regional ecosystem. These factors are expected to maintain North America's leading position in the patient experience technology market over the forecast period.
The breakdown of primary participants is as mentioned below:
- By Company Type - Tier 1: 32%, Tier 2: 44%, and Tier 3: 24%
- By Designation - Directors: 30%, Managers: 34%, and Others: 36%
- By Region - North America: 40%, Europe: 28%, Asia Pacific: 20%, Latin America: 7%, and Middle East & Africa: 5%
Key Players
The key players operating in the patient experience technology market include Press Ganey (US), National Research Corporation (NRC Health) (US), Medallia Inc. (US), Phreesia (US), NiCE (Israel), R1 RCM Inc. (US), Epic Systems Corporation (US), IQVIA (US), Qualtrics (US), Relias LLC (US), GetWellNetwork (US), CipherHealth Inc. (US), Kyruus, Inc. (US), Twilio Inc. (US), Relatient (US), Alida (Canada), Certify Health (US), Avaamo (US), Luma Health Inc. (US), Solutionreach (US), and Salesforce, Inc. (US). These companies have adopted strategies such as strategic partnerships, collaborations, product launches, platform enhancements, investments in foundation models and generative AI, mergers and acquisitions, and geographic expansion to strengthen their market presence in the patient experience technology market.
Research Coverage
The report analyzes the patient experience technology market. It estimates the market size and future growth potential of various market segments based on offerings, function, end user, and region. The report also analyzes factors such as drivers, restraints, opportunities, and challenges influencing market growth. It evaluates opportunities across the patient experience technology ecosystem and assesses the competitive landscape for key stakeholders. The report also analyzes micro markets by growth trends, prospects, and contributions to the overall patient experience technology market. It forecasts market revenue across major regions and provides a comprehensive competitive analysis of leading market participants, including their company profiles, product portfolios, recent developments, and key growth strategies.
Reasons to Buy the Report
This report will help established firms and new entrants/smaller firms gauge the pulse of the market, which can help them gain a greater market share. Firms purchasing the report could use one or more of the following strategies to strengthen their market position.
This report provides insights on:
- Analysis of key drivers (rising demand for digital engagement platforms and personalized patient care, increasing adoption of telehealth, mobile health apps, and AI-powered analytics, government initiatives and funding to accelerate healthcare digital transformation, growing focus on improving patient satisfaction and long-term engagement through real-time feedback tools, and expansion of cloud-based engagement platforms), restraints (data privacy and cybersecurity concerns restricting adoption, high implementation and integration costs for healthcare providers, limited interoperability between patient engagement systems and existing EHRs), opportunities (expansion in emerging markets with growing healthcare infrastructure, adoption of AI-driven personalization and predictive analytics for patient care, rising partnerships with pharma and payers to accelerate digital health adoption, and growing VR/AR platforms for enhanced patient education and adherence), and challenges (ensuring accuracy and reliability of patient feedback data and rapid technological evolution requiring continuous updates and training) influencing the growth of the patient experience technology market
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product launches in the patient experience technology market
- Market Development: Comprehensive information on the lucrative emerging markets, by offerings, functions, end user, and region
- Market Diversification: Exhaustive information about the product portfolios, growing geographies, recent developments, and investments in the patient experience technology market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, and capabilities of the leading players in the patient experience technology market such as Press Ganey (US), National Research Corporation (NRC Health) (US), Medallia Inc. (US), Phreesia (US), NiCE (Israel), R1 RCM Inc. (US), Epic Systems Corporation (US), IQVIA (US), Qualtrics (US), Relias LLC (US), GetWellNetwork (US), CipherHealth Inc. (US), Kyruus, Inc. (US), Twilio Inc. (US), Relatient (US), Alida (Canada), Certify Health (US), Avaamo (US), Luma Health Inc. (US), Solutionreach (US), Salesforce, Inc. (US), Vital (US), NexHealth (US), Collectly, Inc. (US), Business Integrity Services (US), and Bamboo Health (US)
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION & REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 LIMITATIONS
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 PATIENT EXPERIENCE TECHNOLOGY MARKET OVERVIEW
- 3.2 NORTH AMERICA: PATIENT EXPERIENCE TECHNOLOGY MARKET, BY OFFERING & REGION
- 3.3 PATIENT EXPERIENCE TECHNOLOGY MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising demand for digital engagement platforms and personalized patient care
- 4.2.1.2 Increasing adoption of telehealth, mobile health apps, and AI-powered analytics
- 4.2.1.3 Government initiatives and funding for healthcare digital transformation
- 4.2.1.4 Growing focus on improving patient satisfaction and long-term engagement
- 4.2.1.5 Expansion of cloud-based engagement platforms
- 4.2.2 RESTRAINTS
- 4.2.2.1 Data privacy and cybersecurity concerns
- 4.2.2.2 High implementation and integration costs for healthcare providers
- 4.2.2.3 Limited interoperability between patient engagement systems and existing electronic health record systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growth opportunities in emerging market
- 4.2.3.2 Adoption of AI-driven personalization and predictive analytics for patient care
- 4.2.3.3 Strategic partnerships among technology providers, pharma companies, and payers
- 4.2.3.4 Rising adoption of virtual reality and augmented reality
- 4.2.4 CHALLENGES
- 4.2.4.1 Need to ensure accuracy and reliability of feedback data
- 4.2.4.2 Rapid technological evolution
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.2 BARGAINING POWER OF SUPPLIERS
- 5.3 BARGAINING POWER OF BUYERS
- 5.4 THREAT OF NEW ENTRANTS
- 5.5 THREAT OF SUBSTITUTES
- 5.6 INTENSITY OF COMPETITIVE RIVALRY
- 5.7 MACROECONOMIC INDICATORS
- 5.7.1 INTRODUCTION
- 5.7.2 GDP TRENDS AND FORECAST
- 5.7.3 HEALTHCARE DIGITALIZATION AND PATIENT ENGAGEMENT ADOPTION TRENDS
- 5.8 VALUE CHAIN ANALYSIS
- 5.8.1 PRODUCT DESIGN & DEVELOPMENT
- 5.8.2 SYSTEM INTEGRATION & WORKFLOW CUSTOMIZATION
- 5.8.3 IMPLEMENTATION & CHANGE MANAGEMENT
- 5.8.4 EXPERIENCE ANALYTICS & REPORTING INSIGHTS
- 5.8.5 POST-SALES SUPPORT & CONTINUOUS IMPROVEMENT
- 5.9 ECOSYSTEM ANALYSIS
- 5.10 PRICING ANALYSIS
- 5.10.1 AVERAGE SELLING PRICE TREND, BY KEY PLAYER
- 5.10.2 AVERAGE SELLING PRICE TREND, BY REGION
- 5.11 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.12 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.13 INVESTMENT AND FUNDING SCENARIO
- 5.14 CASE STUDY ANALYSIS
- 5.15 IMPACT OF 2025 US TARIFFS ON PATIENT EXPERIENCE TECHNOLOGY MARKET
- 5.15.1 INTRODUCTION
- 5.15.2 KEY TARIFF RATES
- 5.15.3 IMPACT ON COUNTRY/REGION
- 5.15.3.1 US
- 5.15.3.2 Europe
- 5.15.3.3 Asia Pacific
- 5.15.4 IMPACT ON END USERS
- 5.15.4.1 Healthcare providers
- 5.15.4.2 Healthcare payers
- 5.15.4.3 Pharma & biotech companies
- 5.15.4.4 Others
6 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTION
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 VOICE-OF-THE-PATIENT (VOP) PLATFORMS
- 6.1.2 TELEHEALTH AND VIRTUAL CARE PLATFORMS
- 6.1.3 PATIENT PORTALS AND PERSONAL HEALTH RECORDS
- 6.1.4 REMOTE PATIENT MONITORING (RPM)
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 INTEROPERABILITY/API AND FHIR INFRASTRUCTURE
- 6.2.2 PATIENT IDENTITY MANAGEMENT AND AUTHENTICATION SYSTEMS
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 CLINICAL DECISION SUPPORT SYSTEMS (CDSS)
- 6.3.2 POPULATION HEALTH MANAGEMENT (PHM) PLATFORMS
- 6.3.3 PATIENT ENGAGEMENT SOLUTIONS
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.5 PATENT ANALYSIS
- 6.5.1 PATENT PUBLICATION TRENDS
- 6.5.2 JURISDICTION ANALYSIS
- 6.5.3 MAJOR PATENTS IN PATIENT EXPERIENCE TECHNOLOGY MARKET
- 6.6 FUTURE APPLICATIONS
- 6.6.1 AI-POWERED DIGITAL FRONT DOOR AND INTELLIGENT PATIENT NAVIGATION
- 6.6.2 PREDICTIVE AND PROACTIVE PATIENT EXPERIENCE MANAGEMENT
- 6.6.3 PERSONALIZED, OMNICHANNEL, AND CONNECTED PATIENT ENGAGEMENT
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY ANALYSIS
- 7.1.1.1 Regulatory bodies, government agencies, and other organizations
- 7.1.2 INDUSTRY STANDARDS
- 7.1.1 REGULATORY ANALYSIS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 KEY BUYING CRITERIA
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.4.1 UNMET NEEDS
- 8.4.2 END-USER EXPECTATIONS
- 8.5 MARKET PROFITABILITY
9 PATIENT EXPERIENCE TECHNOLOGY MARKET, BY FUNCTION
- 9.1 INTRODUCTION
- 9.2 APPOINTMENT SCHEDULING
- 9.2.1 ENABLING OPERATIONAL EFFICIENCY AND PATIENT ACCESS
- 9.3 PATIENT REGISTRATION
- 9.3.1 OPTIMIZING FRONT-END WORKFLOWS AND DATA ACCURACY
- 9.4 VIRTUAL CARE
- 9.4.1 EXPANDING REMOTE ACCESS AND CONTINUITY OF CARE
- 9.5 PATIENT COMMUNICATION
- 9.5.1 DRIVING PATIENT ACTIVATION AND CARE ADHERENCE
- 9.6 BILLING
- 9.6.1 PUSH FOR TRANSPARENT & AUTOMATED FINANCIAL WORKFLOWS
- 9.7 FEEDBACK MANAGEMENT
- 9.7.1 FACILITATING CONTINUOUS IMPROVEMENT IN PATIENT EXPERIENCE
- 9.8 OTHER FUNCTIONS
- 9.8.1 GROWING FOCUS ON HOLISTIC, PATIENT-CENTRIC CARE
10 PATIENT EXPERIENCE TECHNOLOGY MARKET, BY OFFERING
- 10.1 INTRODUCTION
- 10.2 SOFTWARE
- 10.2.1 ON-PREMISE SOFTWARE
- 10.2.1.1 Ensuring data control, compliance, and system integration
- 10.2.2 CLOUD-BASED
- 10.2.2.1 Lower upfront costs and seamless interoperability to aid growth
- 10.2.3 HYBRID SOFTWARE
- 10.2.3.1 Ability to ensure maximum compliance and control to boost market
- 10.2.1 ON-PREMISE SOFTWARE
- 10.3 SERVICES
- 10.3.1 MANAGED SERVICES
- 10.3.1.1 Rising demand for operational efficiency and risk mitigation to encourage growth
- 10.3.2 PROFESSIONAL SERVICES
- 10.3.2.1 Need for continuous patient engagement to contribute to growth
- 10.3.1 MANAGED SERVICES
11 PATIENT EXPERIENCE TECHNOLOGY MARKET, BY END USER
- 11.1 INTRODUCTION
- 11.1.1 HEALTHCARE PROVIDERS
- 11.1.1.1 Growing patient expectations and digital-first strategies
- 11.1.2 HOSPITALS & HEALTH SYSTEMS
- 11.1.2.1 Enterprise-wide digital platforms to unify patient journeys and optimize value-based care
- 11.1.3 OUTPATIENT & AMBULATORY CARE CENTERS
- 11.1.3.1 Digital transformation elevates patient experience in ambulatory settings
- 11.1.4 PHYSICIAN & GROUP PRACTICES
- 11.1.4.1 AI, EHRs, and mobile apps transform care delivery in group practices
- 11.1.5 LONG-TERM CARE & POST-ACUTE FACILITIES
- 11.1.5.1 Enhancing care quality and patient experience in LTC and PAC Facilities
- 11.1.6 OTHER HEALTHCARE PROVIDERS
- 11.1.6.1 Improving patient engagement and care efficiency across specialty and ambulatory settings to drive segment
- 11.1.1 HEALTHCARE PROVIDERS
- 11.2 HEALTHCARE PAYERS
- 11.2.1 ADVANCING MEMBER-CENTRIC CARE TO BOOST GROWTH
- 11.3 PHARMA & BIOTECH COMPANIES
- 11.3.1 PHARMA & BIOTECH ADVANCING PATIENT EXPERIENCE THROUGH DIGITAL SOLUTIONS
- 11.4 OTHER END USERS
- 11.4.1 ENABLERS OF STANDARDS, COMPLIANCE, AND INNOVATION DRIVING PATIENT EXPERIENCE TECHNOLOGY ADOPTION
12 PATIENT EXPERIENCE TECHNOLOGY MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 12.2.2 US
- 12.2.2.1 US to dominate global market for patient experience technology
- 12.2.3 CANADA
- 12.2.3.1 Advancing patient-centric digital health solutions
- 12.3 EUROPE
- 12.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 12.3.2 UK
- 12.3.2.1 NHS-driven patient-centric innovation
- 12.3.3 GERMANY
- 12.3.3.1 Digital health leadership and patient engagement
- 12.3.4 FRANCE
- 12.3.4.1 Advancing patient-centric digital health
- 12.3.5 ITALY
- 12.3.5.1 Regional growth and telemedicine expansion
- 12.3.6 SPAIN
- 12.3.6.1 Patient-centric digital health and regional innovation
- 12.3.7 REST OF EUROPE
- 12.4 ASIA PACIFIC
- 12.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 12.4.2 JAPAN
- 12.4.2.1 Rapidly growing elderly population to propel market expansion
- 12.4.3 CHINA
- 12.4.3.1 Widespread super-app integration to accelerate adoption
- 12.4.4 INDIA
- 12.4.4.1 National digital health programs accelerating market growth in India
- 12.4.5 SOUTH KOREA
- 12.4.5.1 Regulatory liberalization and ICT integration fueling market growth
- 12.4.6 AUSTRALIA
- 12.4.6.1 Mature healthcare system and digital infrastructure driving adoption
- 12.4.7 REST OF ASIA PACIFIC
- 12.5 LATIN AMERICA
- 12.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 12.5.2 BRAZIL
- 12.5.2.1 Brazil to dominate patient experience technology market in Latin America
- 12.5.3 MEXICO
- 12.5.3.1 Mexico emerges as a hub for retail-integrated and multilingual patient experience platforms
- 12.5.4 REST OF LATIN AMERICA
- 12.6 MIDDLE EAST & AFRICA
- 12.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 12.6.2 GCC COUNTRIES
- 12.6.2.1 Rising healthcare investments to fuel uptake
- 12.6.2.2 Saudi Arabia
- 12.6.2.2.1 Vision 2030 and MoH digital-first strategy
- 12.6.2.3 UAE
- 12.6.2.3.1 Government-led digital transformation and private-sector innovation
- 12.6.2.4 Rest of GCC
- 12.6.2.4.1 Rising demand for telehealth & virtual care
- 12.6.3 SOUTH AFRICA
- 12.6.4 REST OF MIDDLE EAST & AFRICA
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 13.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN PATIENT EXPERIENCE TECHNOLOGY MARKET
- 13.3 REVENUE ANALYSIS, 2021-2025
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.5 COMPANY VALUATION AND FINANCIAL METRICS
- 13.6 BRAND/SOFTWARE COMPARISON
- 13.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.7.5.1 Company footprint
- 13.7.5.2 Region footprint
- 13.7.5.3 Offering footprint
- 13.7.5.4 Function footprint
- 13.7.5.5 End user footprint
- 13.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.8.1 PROGRESSIVE COMPANIES
- 13.8.2 RESPONSIVE COMPANIES
- 13.8.3 DYNAMIC COMPANIES
- 13.8.4 STARTING BLOCKS
- 13.8.5 COMPETITIVE BENCHMARKING OF STARTUPS/SMES, 2025
- 13.8.5.1 Detailed list of key startups/SMEs
- 13.8.5.2 Competitive benchmarking of key startups/SMEs
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 SOLUTION/SERVICE LAUNCHES
- 13.9.2 DEALS
- 13.9.3 EXPANSIONS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 PRESS GANEY
- 14.1.1.1 Business overview
- 14.1.1.2 Solutions offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Solution launches and enhancements
- 14.1.1.3.2 Deals
- 14.1.1.4 MnM view
- 14.1.1.4.1 Right to win
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 NATIONAL RESEARCH CORPORATION
- 14.1.2.1 Business overview
- 14.1.2.2 Solutions offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Solution launches and enhancements
- 14.1.2.4 MnM view
- 14.1.2.4.1 Right to win
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 MEDALLIA INC.
- 14.1.3.1 Business overview
- 14.1.3.2 Solutions offered
- 14.1.3.3 Recent developments
- 14.1.3.3.1 Solution launches and enhancements
- 14.1.3.3.2 Deals
- 14.1.3.4 MnM view
- 14.1.3.4.1 Right to win
- 14.1.3.4.2 Strategic choices
- 14.1.3.4.3 Weaknesses and competitive threats
- 14.1.4 PHREESIA
- 14.1.4.1 Business overview
- 14.1.4.2 Products offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Solution launches and enhancements
- 14.1.4.3.2 Deals
- 14.1.4.4 MnM view
- 14.1.4.4.1 Right to win
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 NICE
- 14.1.5.1 Business overview
- 14.1.5.2 Solutions offered
- 14.1.5.3 MnM view
- 14.1.5.3.1 Right to win
- 14.1.5.3.2 Strategic choices
- 14.1.5.3.3 Weaknesses and competitive threats
- 14.1.6 R1
- 14.1.6.1 Business overview
- 14.1.6.2 Solutions offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Solution launches and enhancements
- 14.1.6.3.2 Deals
- 14.1.7 EPIC SYSTEMS CORPORATION
- 14.1.7.1 Business overview
- 14.1.7.2 Solutions offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Solution launches and enhancements
- 14.1.7.3.2 Deals
- 14.1.8 IQVIA
- 14.1.8.1 Business overview
- 14.1.8.2 Solutions offered
- 14.1.8.3 Recent developments
- 14.1.8.3.1 Solution launches and enhancements
- 14.1.9 QUALTRICS
- 14.1.9.1 Business overview
- 14.1.9.2 Solutions offered
- 14.1.9.3 Recent developments
- 14.1.9.3.1 Deals
- 14.1.9.3.2 Expansions
- 14.1.9.3.3 Other developments
- 14.1.10 RELIAS LLC
- 14.1.10.1 Business overview
- 14.1.10.2 Solutions offered
- 14.1.10.3 Recent developments
- 14.1.10.3.1 Deals
- 14.1.11 GETWELLNETWORK, INC.
- 14.1.11.1 Business overview
- 14.1.11.2 Solutions offered
- 14.1.11.3 Recent developments
- 14.1.11.3.1 Solution launches and enhancements
- 14.1.11.3.2 Deals
- 14.1.12 CIPHERHEALTH INC.
- 14.1.12.1 Business overview
- 14.1.12.2 Solutions offered
- 14.1.12.3 Recent developments
- 14.1.12.3.1 Solution launches and enhancements
- 14.1.12.3.2 Deals
- 14.1.13 KYRUUS, INC.
- 14.1.13.1 Business overview
- 14.1.13.2 Solutions offered
- 14.1.13.3 Recent developments
- 14.1.13.3.1 Solution launches and enhancements
- 14.1.13.3.2 Deals
- 14.1.14 RELATIENT
- 14.1.14.1 Business overview
- 14.1.14.2 Solutions offered
- 14.1.14.3 Recent developments
- 14.1.14.3.1 Solution launches and enhancements
- 14.1.15 ALIDA
- 14.1.15.1 Business overview
- 14.1.15.2 Solutions offered
- 14.1.16 TWILIO INC.
- 14.1.16.1 Business overview
- 14.1.16.2 Solutions offered
- 14.1.16.3 Recent developments
- 14.1.16.3.1 Solution launches and enhancements
- 14.1.16.3.2 Deals
- 14.1.17 AVAAMO
- 14.1.17.1 Business overview
- 14.1.17.2 Products offered
- 14.1.17.3 Recent developments
- 14.1.17.3.1 Solution launches and enhancements
- 14.1.18 CERTIFY HEALTH
- 14.1.18.1 Business overview
- 14.1.18.2 Solutions offered
- 14.1.18.3 Recent developments
- 14.1.18.3.1 Other developments
- 14.1.19 LUMA HEALTH INC.
- 14.1.19.1 Business overview
- 14.1.19.2 Solutions offered
- 14.1.19.3 Recent developments
- 14.1.19.3.1 Solution launches and enhancements
- 14.1.19.3.2 Deals
- 14.1.20 SOLUTIONREACH
- 14.1.20.1 Business overview
- 14.1.20.2 Solutions offered
- 14.1.20.3 Recent developments
- 14.1.20.3.1 Solution launches and enhancements
- 14.1.21 SALESFORCE, INC.
- 14.1.21.1 Business overview
- 14.1.21.2 Solutions offered
- 14.1.21.3 Recent developments
- 14.1.21.3.1 Solution launches and enhancements
- 14.1.1 PRESS GANEY
- 14.2 OTHER PLAYERS
- 14.2.1 VITAL
- 14.2.2 NEXHEALTH
- 14.2.3 COLLECTLY, INC.
- 14.2.4 BUSINESS INTEGRITY SERVICES
- 14.2.5 BAMBOO HEALTH
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Breakdown of primary sources
- 15.1.1 SECONDARY DATA
- 15.2 RESEARCH METHODOLOGY DESIGN
- 15.3 MARKET SIZE ESTIMATION
- 15.4 MARKET BREAKDOWN & DATA TRIANGULATION
- 15.5 RESEARCH ASSUMPTIONS
- 15.5.1 MARKET SIZING ASSUMPTIONS
- 15.5.2 OVERALL STUDY ASSUMPTIONS
- 15.6 RISK ASSESSMENT
- 15.7 RESEARCH LIMITATIONS
- 15.7.1 METHODOLOGY-RELATED LIMITATIONS
- 15.7.2 SCOPE-RELATED LIMITATIONS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


