

|
시장보고서
상품코드
2146284
RWE(Real-world Evidence) 솔루션 시장 예측(-2031년) : 컴포넌트별(데이터세트), 용도별, 최종사용자별, 지역별Real-world Evidence Solutions Market by Component [Datasets (Claims, Clinical, Pharmacy, Genomics)], Application (Drug/Device Development, Reimbursement), End User (Pharma, Medtech, Payers, Provider), Region- Global Forecast to 2031 |
||||||

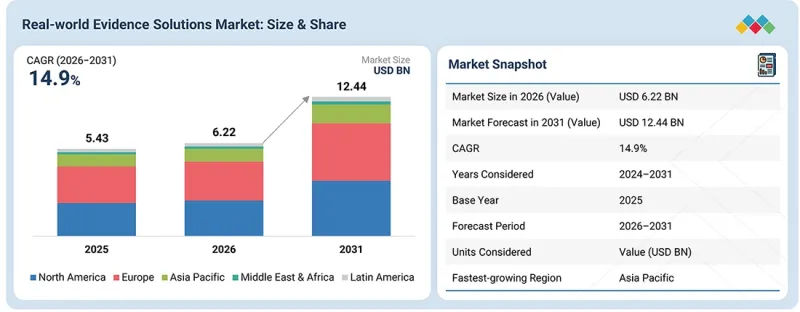
RWE(Real-world Evidence) 솔루션 시장은 2026년 62억 2,000만 달러에서 2031년까지 124억 4,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년까지 연평균 성장률(CAGR)은 14.9%에 달할 전망입니다.
제약 및 생명과학 기업은 임상 개발, 규제 당국에 대한 신청, 의료 기술 평가(HTA), 시장 진입 및 시판 후 의사결정을 지원하기 위한 지속적인 근거를 필요로 하고 있으므로 RWE 솔루션 시장은 이러한 기업에게 점점 더 전략적인 역량이 되어가고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 구성 요소, 용도, 배포 방식, 수익 모델, 최종사용자 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
최근 동향으로는 BC Platforms가 전 세계 바이오의약품 기업과 공동으로 영국, 독일, 스페인 전역에서 바이오마커 기반의 비소세포폐암(NSCLC) 치료법에 대한 종단적 증거를 생성하기 위한 2026년 RWE 프로그램을 발표한 것을 들 수 있습니다. 이 프로그램은 바이오마커 검사, 치료 경로 및 치료 결과를 평가하여 제품 출시 및 HTA(의료기술평가) 계획 수립을 지원하는 것을 목적으로 합니다. 이와 병행하여, RTI International은 2026년 5월 Navidence사에 전략적 투자를 단행하여, AI 및 표준화된 질환·치료·예후 정의를 활용하여 RWE 생성 효율과 품질을 향상시키는 것을 목표로 하고 있습니다. 이러한 동향은 헬스케어 제품의 전체 수명 주기 전반에 걸쳐 종단적 데이터세트, AI를 활용한 분석, 데이터 조화, 그리고 전문적인 증거 생성 능력에 대한 수요가 증가하고 있음을 여실히 보여주고 있습니다.
"구성 요소별로는 데이터세트 부문이 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다."
구성 요소에 따라 RWE 솔루션 시장은 서비스와 데이터세트로 구분됩니다. 데이터세트 부문은 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다. 의료의 디지털화가 진행되고 FDA나 EMA 등 규제 당국의 RWD(Real World Data) 수용이 높아짐에 따라 EHR, 청구 데이터, 레지스트리 데이터 등 고품질의 엄선된 데이터세트에 대한 수요가 급증하고 있습니다. 이러한 데이터세트은 분석, AI 모델, 의료경제학 연구를 지원하며, 제약, 바이오기술, 헬스케어 기업에게 필수적인 자산이 되고 있습니다. 또한 라이선싱을 통한 지속적인 수익 창출 가능성은 RWE 분야에서 이러한 데이터세트의 우위를 더욱 강화하고 있습니다.
"용도별로는 시장 접근 및 보험 급여·적용 범위 결정 부문이 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다."
용도별로 보면 RWE 솔루션 시장은 의약품 개발·승인, 의료기기 개발·승인, 시판 후 조사, 시장 접근·급여/적용 범위 의사결정, 임상·규제상 의사결정 및 기타 용도로 분류됩니다. RWE 솔루션 시장에서 시장 접근 및 환급·적용 범위 의사결정 부문이 가장 빠른 성장세를 보일 것으로 예상됩니다. 지불자 및 의료제도에 대해 가치, 비용 대비 효과, 비교 유효성, 그리고 실세계에서의 치료 성과를 입증해야 한다는 압박이 커지고 있는 것이 RWE 수요를 견인하고 있습니다. 제약 기업은 가격 책정, 보험 급여 협상, 처방약 리스트 등재, 의료기술평가(HTA), 그리고 가치 기반 계약을 지원하기 위해 RWE를 점점 더 많이 활용하고 있습니다.
"최종사용자별로는 제약·바이오기술 기업 부문이 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다."
최종사용자별로 보면 RWE 솔루션 시장은 제약·바이오기술 기업, 의료기기 기업, 의료보험사, 의료 제공자 및 기타 최종사용자로 구분됩니다. 제약·바이오기술 기업 부문은 의약품 개발 및 상업화의 전체 수명주기에 걸친 RWE 활용 확대에 힘입어, 예측 기간 중 RWE 솔루션 시장에서 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다. 이러한 기업은 환자 집단 식별, 임상시험 계획 수립, 규제 당국에 대한 신청, 안전성 및 유효성 평가, 적응증 확대, 시장 진입, 시판 후 조사를 위해 RWE를 활용하고 있습니다.
"아시아태평양은 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다."
지역별로는 시장 세분화에서 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카로 분류됩니다. 아시아태평양의 RWE 솔루션 시장은 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다. 이 지역의 높은 성장률은 제약 회사 및 의료기기 기업의 RWE 도입 노력이 증가하고 있기 때문입니다. 이러한 급속한 성장은 중국, 인도, 일본, 한국 등의 경제권에서 수행되는 임상시험 건수가 많은 데다, 의약품 승인 및 시판 후 감시에 있으며, RWE를 수용하기 시작한 규제 프레임워크의 진화에 의해 주도되고 있습니다. 규제 당국 및 HTA(의료기술평가)에서의 RWE 채택은 더욱 강화되고 있으며, 중국의 국가위생건강위원회(NHSA)는 2026년까지 RWE에 특화된 6개의 지침을 발간할 예정입니다. 한편, 일본, 한국, 대만 및 기타 시장에서는 보험 급여, 안전성 모니터링, 그리고 임상적 의사결정에서 RWE의 활용이 지속적으로 확대되고 있습니다.
공급 측면의 1차 인터뷰 내역(기업 유형, 지정 구분, 지역별):
- 기업 유형별: Tier 1(40%), Tier 2(35%), Tier 3(25%)
- 직책별: C레벨(35%), 이사급(45%), 기타(20%)
- 지역별: 북미(55%), 유럽(20%), 아시아태평양(15%), 라틴아메리카(5%), 중동 및 아프리카(5%)
이 보고서에서 다룬 기업 개요 리스트
- IQVIA(미국)
- Merative(미국)
- Optum Inc.(미국)
- Syneos Health(미국)
- ICON plc(아일랜드)
- Parexel International Corporation(미국)
- Flatiron Health(미국)
- Oracle(미국)
- Fortrea(미국)
- Elevance Health(미국)
- SAS Institute Inc.(미국)
- Tata Consultancy Services Limited(인도)
- Trinity Partners, LLC(미국)
- Medidata(미국)
- Cognizant(미국)
- Cegedim Health Data(프랑스)
- Verantos(미국)
- Medpace(미국)
- TriNetX, LLC(미국)
- Datavant(미국)
조사 범위
이 보고서에서는 RWE 솔루션 시장을 구성 요소, 용도, 수익 모델, 도입 형태, 최종사용자 및 지역별로 분석하고 있습니다. 또한 시장 성장에 영향을 미치는 요인(촉진요인, 제약 요인, 기회, 과제 등)에 대해서도 분석하고 있습니다. 이해관계자에게 있으며, 시장내 기회와 과제를 평가함과 동시에, 시장을 선도하는 기업에 대한 경쟁 구도의 세부 정보를 제공합니다. 또한 이 보고서에서는 성장 동향, 전망 및 RWE 솔루션 시장 전체에 대한 기여도라는 관점에서 마이크로 마켓에 대해서도 조사하고 있습니다. 더불어 5개 지역별로 각 시장 부문의 매출 예측을 제시하고 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서에는 다음과 같은 내용도 포함되어 있습니다. :
- 주요 촉진요인(고령 인구 증가 및 만성질환 발병률 상승, 양 중심 의료에서 가치 중심 의료로의 전환, 의약품 개발 비용 절감 및 개발 과정 신속화에 있으며, RWE의 잠재력, 신약 및 의료기기 개발을 위한 연구개발비 증가, 그리고 RWE 솔루션 활용에 대한 규제 당국의 지원)에 대한 분석,제약 요인(의료 종사자 및 연구자들이 실세계 연구에 의존하는 데 소극적인 점),기회(엔드투엔드 RWE 서비스에 대한 관심 증가 및 신흥 시장의 성장 기회), 그리고 과제(숙련된 인력 부족 및 보편적으로 수용된 조사 방법론 원칙과 데이터 처리 인프라의 부재)에 대해서도 분석하고 있습니다.
- 제품 개발/혁신: RWE 솔루션 시장의 향후 동향, 연구개발 활동 및 신규 소프트웨어 출시에 대한 상세 인사이트.
- 시장 개발: 수익성이 높은 신흥 시장에 대한 포괄적인 정보(구성 요소, 용도, 수익 모델, 도입 형태, 최종사용자, 지역별).
- 시장 다각화: RWE 솔루션 시장의 소프트웨어 포트폴리오, 급성장하는 지역, 최근 동향 및 투자에 관한 포괄적인 정보.
- 경쟁 분석: 글로벌 RWE 솔루션 시장 주요 기업의 시장 점유율, 성장 전략, 제품 라인업, 기업 평가 매트릭스 및 역량에 대한 상세한 평가.
자주 묻는 질문
목차
제1장. 서론
제2장 요약
제3장 주요 인사이트
- RWE(Real-world Evidence) 솔루션 시장 개요
- RWE(Real-world Evidence)(RE) 솔루션 시장: 구성 요소별·지역별
- RWE(Real-world Evidence)(Real-World Evidence) 솔루션 시장: 지역별 현황
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- 미충족 수요와 미개발 분야
- 상호 연관된 시장 및 부문 간 기회
- Tier 1/2/3 주요 기업의 전략적 움직임
제5장 업계 동향
- Porter's Five Forces 분석
- 신규 진입자의 위협
- 공급업체의 협상력
- 구매자의 협상력
- 대체재로부터의 위협
- 경쟁 기업 간의 적대적 관계
- GDP 동향 및 전망
- 세계 헬스케어 IT 산업의 동향
- 밸류체인 분석
- 생태계 분석
- 가격 책정 분석
- 구성 요소별, 리얼 월드 에비던스(REW) 솔루션의 참고 가격
- 지역별 리얼 월드 에비던스(REW) 솔루션 참고 가격
- 2026-2027년 주요 컨퍼런스 및 행사
- 고객의 비즈니스에 영향을 미치는 동향/파괴적 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- RWE 대시보드 설계 및 구축, 그리고 EHR 및 청구 데이터 활용
- 전문 약국 및 환자 허브 데이터를 RWD 데이터와 통합하여 복약 순응도 저하의 요인을 조사
- RWE 플랫폼을 통한 데이터 분석 간소화
제6장 2025년 미국 요금 체계의 영향 - 개요
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가·지역에 미치는 영향
- 최종 용도 산업에 미치는 영향
제7장 기술, 특허, 디지털화 및 AI 도입에 따른 전략적 변혁
- 주요 신규 기술
- AI 및 기계학습(ML)의 활용
- 블록체인 기술
- 관련 기술
- 보완 기술
- 특허 분석
- 실증적 증거 솔루션 관련 특허 공개 동향
- 인사이트: 관할 구역 및 주요 출원인 분석
- 향후 응용
- AI를 활용한 RWE 자동 생성
- 임상시험 데이터와 RWD(Real World Data)(RWD)의 통합 및 하이브리드 증거 생성
- 의약품 및 의료기기의 의사결정을 위한 규제 기준을 충족하는 RWE
- 시판 후 안전성 및 유효성에 대한 지속적인 모니터링
- 시장 진입, HEOR(의료경제·결과 연구) 및 의료기술 평가를 위한 실시간 증거
- AI/생성형 AI가 실제 세계 증거(RWE) 솔루션 시장에 미치는 영향
- 주요 활용 사례 및 시장 잠재력
- AI/생성형 AI 도입: 사례 연구
- 생성형 AI가 상호 연결된 시장 및 인접 시장 생태계에 미치는 영향
- 사용자의 수용도 및 영향 평가
- 규제기관, 정부 기관 및 기타 조직
- 규제 분석
제8장 고객 동향 및 구매 행동
- 의사결정 과정
- 구매자의 이해관계자와 구매 평가 기준
- 구매 과정에서 주요 이해관계자
- 구매 기준
- 도입 장벽 및 사내 과제
- 최종사용자 분석
- 미충족 요구
- 최종사용자의 기대
- 시장의 수익성
제9장 리얼 월드 에비던스 솔루션 시장: 구성 요소별
- 서비스
- 데이터세트
제10장 리얼 월드 에비던스 솔루션 시장: 용도별
- 의약품 개발 및 승인
- 의료기기 개발 및 승인
- 시판 후 조사
- 시장 진입 및 보험 급여·적용 범위 결정
- 임상 및 규제 관련 의사결정
- 기타 용도
제11장 리얼 월드 에비던스 솔루션 시장: 수익 모델별
- 사용량 기반 과금(가치 기반 가격)
- 구독
- 라이선스
제12장 리얼 월드 에비던스 솔루션 시장: 배포 방식별
- 온프레미스
- 클라우드형
- 하이브리드
제13장 리얼 월드 에비던스 솔루션 시장: 최종사용자별
- 제약·바이오기술 기업
- 의료기기 기업
- 의료보험자
- 공적 보험자
- 민간 보험사
- 의료 제공자
- 기타 최종사용자
제14장 리얼 월드 에비던스 솔루션 시장: 지역별
- 북미
- 북미: 거시경제 전망
- 미국
- 캐나다
- 유럽
- 유럽: 거시경제 전망
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 아시아태평양: 거시경제 전망
- 일본
- 중국
- 인도
- 호주
- 한국
- 기타 아시아태평양
- 라틴아메리카
- 라틴아메리카: 거시경제 전망
- 브라질
- 멕시코
- 기타 라틴아메리카
- 중동 및 아프리카
- 중동 및 아프리카: 거시경제 전망
- GCC 국가들
- 남아프리카
- 기타 중동 및 아프리카
제15장 경쟁 현황
- 주요 진입 기업의 전략/강점
- 주요 업체들이 채택하고 있는 전략 개요
- 매출 점유율 분석
- 시장 점유율 분석
- 기업 평가 매트릭스: 주요 기업
- 스타 기업
- 신흥 리더
- 광범위한 참여 기업
- 진입 기업
- 기업의 사업 전개
- 기업 평가 매트릭스: 스타트업/중소기업
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹
- 브랜드·제품 비교
- 기업 가치 평가 및 재무 지표
- 경쟁 시나리오
- 제품 출시 및 기능 강화
- 거래
- 주요 기업
- IQVIA
- MERATIVE
- OPTUM, INC.
- ICON PLC
- SYNEOS HEALTH
- PAREXEL INTERNATIONAL(MA) CORPORATION
- FLATIRON HEALTH
- FORTREA
- ORACLE
- ELEVANCE HEALTH
- SAS INSTITUTE INC.
- DATAVANT
- TRINETX, LLC
- TRINITY
- MEDIDATA
- COGNIZANT
- CEGEDIM HEALTH DATA
- VERANTOS
- MEDPACE
- TATA CONSULTANCY SERVICES LIMITED
- 기타 기업
- HEALTHVERITY, INC.
- OM1
- OPEN HEALTH
- TEMPUS
- INFINITI RESEARCH(QUANTZIG)
제16장 조사 방법
제17장 부록
KSA 26.10.19The real-world evidence solutions market is projected to reach USD 12.44 billion by 2031 from USD 6.22 billion in 2026, at a CAGR of 14.9% from 2026 to 2031. The RWE solutions market is increasingly becoming a strategic capability for pharmaceutical and life sciences companies, as organizations seek continuous evidence to support clinical development, regulatory submissions, HTA, market access, and post-launch decisions.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Component, Application, Deployment Mode, Revenue Model, and End User |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
Recent developments include BC Platforms reporting a 2026 RWE program with a global biopharmaceutical company to generate longitudinal evidence for a biomarker-driven NSCLC therapy across the UK, Germany, and Spain, assessing biomarker testing, treatment pathways, and outcomes to support launch and HTA planning. In parallel, RTI International made a strategic investment in Navidence in May 2026 to use AI and standardized disease, treatment, and outcome definitions to improve the efficiency and quality of RWE generation. These developments highlight growing demand for longitudinal datasets, AI-enabled analytics, data harmonization, and specialized evidence-generation capabilities across the healthcare product lifecycle.
"By component, the data sets segment is expected to grow at the highest CAGR during the forecast period."
Based on component, the RWE solutions market is segmented into services and data sets. The data sets segment is projected to grow at the highest CAGR during the forecast period. With the growing digitization of healthcare and increasing acceptance of real-world data by regulators such as the FDA and EMA, the demand for high-quality, curated datasets, such as EHRs, claims, and registry data, has surged. These datasets power analytics, AI models, and health economics studies, making them critical assets for pharma, biotech, and healthcare companies. Additionally, their recurring revenue potential through licensing further drives their dominance in the RWE landscape.
"By application, the market access & reimbursement/coverage decision-making segment is expected to register the highest CAGR during the forecast period."
By application, the RWE solutions market is segmented into drug development & approvals, medical device development & approvals, post-market surveillance, market access & reimbursement/coverage decision-making, clinical & regulatory decision-making, and other applications. The market access & reimbursement/coverage decision-making segment is expected to register the fastest growth in the RWE solutions market. Increasing pressure on payers and healthcare systems to demonstrate value, cost-effectiveness, comparative effectiveness, and real-world treatment outcomes is driving demand for RWE. Pharmaceutical companies are increasingly using RWE to support pricing and reimbursement negotiations, formulary placement, health technology assessments (HTAs), and value-based agreements.
"By end user, the pharmaceutical & biotechnology companies segment is projected to grow at the highest CAGR during the forecast period."
By end user, the RWE solutions market is segmented into pharmaceutical & biotechnology companies, medtech companies, healthcare payers, healthcare providers, and other end users. The pharmaceutical & biotechnology companies segment is projected to register the highest CAGR in the RWE solutions market during the forecast period, driven by the increasing use of RWE across the drug development and commercialization lifecycle. These companies use RWE for patient population identification, clinical trial planning, regulatory submissions, safety and effectiveness assessment, label expansion, market access, and post-market surveillance.
"The Asia Pacific region is projected to register the highest CAGR during the forecast period."
By region, the market is segmented into North America, Europe, the Asia Pacific, Latin America, and the Middle East & Africa. The RWE solutions market in the Asia Pacific region is projected to register the highest CAGR during the forecast period. This region's high growth rate is attributed to rising initiatives to adopt RWE by pharmaceutical & medical device companies. This rapid expansion is driven by the high volume of clinical trials undertaken by economies such as China, India, Japan, and South Korea, along with evolving regulatory frameworks that are beginning to accept RWE for drug approvals and post-market surveillance. Regulatory and HTA adoption is strengthening further, with China's NHSA having issued six RWE-specific guidelines by 2026, while Japan, South Korea, Taiwan, and other markets continue to expand the use of RWE for reimbursement, safety monitoring, and clinical decision-making.
Breakdown of supply-side primary interviews, by company type, designation, and region:
- By Company Type: Tier 1 (40%), Tier 2 (35%), and Tier 3 (25%)
- By Designation: C-level (35%), Director-level (45%), and Others (20%)
- By Region: North America (55%), Europe (20%), Asia Pacific (15%), Latin America (5%), and Middle East & Africa (5%)
List of Companies Profiled in the Report
- IQVIA (US)
- Merative (US)
- Optum Inc. (US)
- Syneos Health (US)
- ICON plc (Ireland)
- Parexel International Corporation (US)
- Flatiron Health (US)
- Oracle (US)
- Fortrea (US)
- Elevance Health (US)
- SAS Institute Inc. (US)
- Tata Consultancy Services Limited (India)
- Trinity Partners, LLC (US)
- Medidata (US)
- Cognizant (US)
- Cegedim Health Data (France)
- Verantos (US)
- Medpace (US)
- TriNetX, LLC (US)
- Datavant (US)
Research Coverage
This report studies the RWE solutions market based on component, application, revenue model, deployment mode, end user, and region. The report also analyses factors (such as drivers, restraints, opportunities, and challenges) affecting market growth. It evaluates the opportunities and challenges in the market for stakeholders and provides details of the competitive landscape for market leaders. The report also studies micro markets with respect to their growth trends, prospects, and contributions to the total RWE solutions market. The report forecasts the revenue of the market segments with respect to five regions.
Reasons to Buy the Report
This report also includes:
- Analysis of key drivers (rising geriatric population and rise in incidences of chronic diseases, shift from volume-based care to value-based care, potential of RWE in reducing drug development costs and expediting drug development process, increased R&D spending for development of new pharmaceutical products and medical devices, and support from regulatory bodies for use of RWE solutions), restraints (reluctance of medical practitioners and researchers to rely on real-world studies), opportunities (increased focus on end-to-end RWE services, and growth opportunities in emerging markets), and challenges (scarcity of skilled personnel, and the lack of universally accepted methodology principles and data processing infrastructure).
- Product Development/Innovation: Detailed insights on upcoming trends, research & development activities, and new software launches in the RWE solutions market.
- Market Development: Comprehensive information on the lucrative emerging markets, by component, application, revenue model, deployment mode, end user, and region.
- Market Diversification: Exhaustive information about the software portfolios, growing geographies, recent developments, and investments in the RWE solutions market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, company evaluation matrix, and capabilities of leading players in the global RWE solutions market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.4 YEARS CONSIDERED
- 1.5 CURRENCY CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 REAL-WORLD EVIDENCE SOLUTIONS MARKET OVERVIEW
- 3.2 REAL-WORLD EVIDENCE SOLUTIONS MARKET, BY COMPONENT & REGION
- 3.3 REAL-WORLD EVIDENCE SOLUTIONS MARKET: GEOGRAPHIC SNAPSHOT
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising geriatric population and subsequent increase in prevalence of chronic diseases
- 4.2.1.2 Shift from volume-based care to value-based care
- 4.2.1.3 Potential of real-world evidence in reducing drug development costs and expediting drug development process
- 4.2.1.4 Increased R&D spending for development of new pharmaceutical products and medical devices
- 4.2.1.5 Support from regulatory bodies for use of real-world evidence solutions
- 4.2.2 RESTRAINTS
- 4.2.2.1 Reluctance of medical practitioners and researchers to rely on real-world studies
- 4.2.2.2 Data quality and standardization issues
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growth opportunities in emerging markets
- 4.2.3.2 Increased focus on end-to-end RWE services
- 4.2.3.3 Increased focus on personalized and precision medicine
- 4.2.3.4 Market access, health technology assessment (HTA), and reimbursement
- 4.2.4 CHALLENGES
- 4.2.4.1 Lack of universally accepted methodology standards and data processing infrastructure
- 4.2.4.2 Shortage of skilled professionals
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT FROM NEW ENTRANTS
- 5.1.2 BARGAINING POWER OF SUPPLIERS
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 THREAT FROM SUBSTITUTES
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.6 GDP TRENDS AND FORECAST
- 5.1.7 TRENDS IN GLOBAL HEALTHCARE IT INDUSTRY
- 5.2 VALUE CHAIN ANALYSIS
- 5.3 ECOSYSTEM ANALYSIS
- 5.4 PRICING ANALYSIS
- 5.4.1 INDICATIVE PRICING FOR REAL-WORLD EVIDENCE SOLUTIONS, BY COMPONENT
- 5.4.2 INDICATIVE PRICING OF REAL-WORLD EVIDENCE SOLUTIONS, BY REGION
- 5.5 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.6 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.7 INVESTMENT AND FUNDING SCENARIO
- 5.8 CASE STUDY ANALYSIS
- 5.8.1 DESIGNING AND BUILDING RWE DASHBOARDS AND LEVERAGING EHR AND CLAIMS DATA
- 5.8.2 INTEGRATING SPECIALTY PHARMACY AND PATIENT HUB DATA WITH RWD DATA TO INVESTIGATE INTO NON-ADHERENCE FACTORS
- 5.8.3 SIMPLIFYING DATA ANALYTICS WITH RWE PLATFORM
6 IMPACT OF 2025 US TARIFF - OVERVIEW
- 6.1 INTRODUCTION
- 6.2 KEY TARIFF RATES
- 6.2.1 PRICE IMPACT ANALYSIS
- 6.2.2 IMPACT ON COUNTRY/REGION
- 6.2.2.1 US
- 6.2.2.2 Europe
- 6.2.2.3 Asia Pacific
- 6.2.3 IMPACT ON END-USE INDUSTRIES
7 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTION
- 7.1 KEY EMERGING TECHNOLOGIES
- 7.1.1 USE OF AI AND ML
- 7.1.2 BLOCKCHAIN TECHNOLOGY
- 7.1.3 ADJACENT TECHNOLOGIES
- 7.1.3.1 Predictive analytics
- 7.1.3.2 Visualization dashboard software
- 7.1.4 COMPLEMENTARY TECHNOLOGIES
- 7.1.4.1 Electronic health records (EHRs)
- 7.1.4.2 Clinical trial management system
- 7.2 PATENT ANALYSIS
- 7.2.1 PATENT PUBLICATION TRENDS FOR REAL-WORLD EVIDENCE SOLUTIONS
- 7.2.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 7.3 FUTURE APPLICATIONS
- 7.3.1 AI-POWERED AUTOMATED RWE GENERATION
- 7.3.2 CLINICAL TRIAL-RWD INTEGRATION AND HYBRID EVIDENCE GENERATION
- 7.3.3 REGULATORY-GRADE RWE FOR DRUG AND MEDICAL DEVICE DECISIONS
- 7.3.4 CONTINUOUS POST-MARKET SAFETY AND EFFECTIVENESS MONITORING
- 7.3.5 REAL-TIME EVIDENCE FOR MARKET ACCESS, HEOR, AND HEALTH TECHNOLOGY ASSESSMENT
- 7.4 IMPACT OF AI/GENERATIVE AI ON REAL-WORLD EVIDENCE SOLUTIONS MARKET
- 7.4.1 TOP USE CASES & MARKET POTENTIAL
- 7.4.1.1 Key use cases
- 7.4.2 IMPLEMENTATION OF AI/GENERATIVE AI: CASE STUDIES
- 7.4.2.1 AI-powered RWE transformed patient targeting and treatment initiation
- 7.4.3 IMPACT OF GENERATIVE AI ON INTERCONNECTED AND ADJACENT MARKET ECOSYSTEM
- 7.4.3.1 Electronic health record (EHR) market
- 7.4.3.2 Real world data (RWD) market
- 7.4.4 USER READINESS AND IMPACT ASSESSMENT
- 7.4.5 REGULATORY BODIES, GOVERNMENT AGENCIES, & OTHER ORGANIZATIONS
- 7.4.6 REGULATORY ANALYSIS
- 7.4.6.1 North America
- 7.4.6.1.1 US
- 7.4.6.1.1.1 Use cases
- 7.4.6.1.2 Canada
- 7.4.6.1.1 US
- 7.4.6.2 Europe
- 7.4.6.3 Asia Pacific
- 7.4.6.3.1 China
- 7.4.6.3.2 Japan
- 7.4.6.3.3 India
- 7.4.6.4 Middle East & Africa
- 7.4.6.5 Latin America
- 7.4.6.1 North America
- 7.4.1 TOP USE CASES & MARKET POTENTIAL
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.5 END USER ANALYSIS
- 8.5.1 UNMET NEEDS
- 8.5.2 END USER EXPECTATIONS
- 8.6 MARKET PROFITABILITY
9 REAL-WORLD EVIDENCE SOLUTIONS MARKET, BY COMPONENT
- 9.1 INTRODUCTION
- 9.2 SERVICES
- 9.2.1 RISING NEED TO CONVERT DATA INTO ACTIONABLE EVIDENCE TO DRIVE DEMAND
- 9.3 DATA SETS
- 9.3.1 DISPARATE DATA SETS
- 9.3.1.1 Clinical settings data sets
- 9.3.1.1.1 Increasing utilization of EHR data for trial recruitment to fuel growth
- 9.3.1.2 Claims data sets
- 9.3.1.2.1 Growing need to understand economic benefits of drug reimbursement by payers to drive growth
- 9.3.1.3 Pharmacy data sets
- 9.3.1.3.1 Increasing adoption of e-prescribing systems to drive growth
- 9.3.1.4 Patient-powered data sets
- 9.3.1.4.1 Increasing need to access opinions on diseases and treatments across social media to drive growth
- 9.3.1.5 Registry-based data sets
- 9.3.1.5.1 Increasing number of disease registries to drive demand for registry-based data sets in evidence generation
- 9.3.1.6 Others
- 9.3.1.6.1 Increasing number of genomics registries to drive demand for RWE solutions
- 9.3.1.1 Clinical settings data sets
- 9.3.2 INTEGRATED DATA SETS
- 9.3.2.1 Increasing demand for integrated data from multiple sources to drive growth
- 9.3.1 DISPARATE DATA SETS
10 REAL-WORLD EVIDENCE SOLUTIONS MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.2 DRUG DEVELOPMENT & APPROVAL
- 10.2.1 ONCOLOGY
- 10.2.1.1 Growing number of clinical trials focused on cancer treatment to drive demand
- 10.2.2 CARDIOVASCULAR DISEASES
- 10.2.2.1 High prevalence of cardiovascular diseases to support market growth
- 10.2.3 NEUROLOGY
- 10.2.3.1 Rapidly aging global population and subsequent increase in prevalence of neurological disorders to drive growth
- 10.2.4 IMMUNOLOGY
- 10.2.4.1 Increasing focus on developing innovative products to drive growth
- 10.2.5 RARE DISEASES
- 10.2.5.1 Need for harnessing RWE to advance therapies for rare diseases to boost market
- 10.2.6 OTHER THERAPEUTIC AREAS
- 10.2.1 ONCOLOGY
- 10.3 MEDICAL DEVICE DEVELOPMENT & APPROVAL
- 10.3.1 INCREASING RESEARCH IN MEDICAL DEVICE DEVELOPMENT TO DRIVE DEMAND
- 10.4 POST-MARKET SURVEILLANCE
- 10.4.1 EXTENSIVE USE OF RWE SOLUTIONS IN POST-MARKET SURVEILLANCE TO BOOST MARKET
- 10.5 MARKET ACCESS & REIMBURSEMENT/COVERAGE DECISION-MAKING
- 10.5.1 GROWING USE OF RWE SOLUTIONS TO DEVELOP ECONOMIC AND BUDGET IMPACT MODELS TO FAVOR MARKET GROWTH
- 10.6 CLINICAL & REGULATORY DECISION-MAKING
- 10.6.1 LIMITED VALIDITY OF RANDOMIZED CONTROLLED TRIALS TO DRIVE USE OF RWE SOLUTIONS
- 10.7 OTHER APPLICATIONS
11 REAL-WORLD EVIDENCE SOLUTIONS MARKET, BY REVENUE MODEL
- 11.1 INTRODUCTION
- 11.2 PAY-PER-USAGE (VALUE-BASED PRICING)
- 11.2.1 RISING DEMAND FOR COST-EFFECTIVE AND FLEXIBLE SOLUTIONS TO BOOST MARKET
- 11.3 SUBSCRIPTION
- 11.3.1 RISING PREFERENCE FOR FLEXIBILITY AND SCALABILITY TO SUPPORT MARKET GROWTH
- 11.4 LICENSE
- 11.4.1 FOCUS ON ENABLING END-TO-END RWE DELIVERY THROUGH PLATFORM LICENSING TO DRIVE MARKET
12 REAL-WORLD EVIDENCE SOLUTIONS MARKET, BY DEPLOYMENT MODE
- 12.1 INTRODUCTION
- 12.2 ON-PREMISES
- 12.2.1 NEED FOR ENHANCED DATA CONTROL BENEFITS TO BOOST DEMAND
- 12.3 CLOUD-BASED
- 12.3.1 INCREASED SCALABILITY AND FLEXIBILITY IN DATA COLLECTION TO DRIVE GROWTH
- 12.4 HYBRID
- 12.4.1 EMPHASIS ON INCREASED SCALABILITY AND FLEXIBILITY IN DATA COLLECTION TO DRIVE GROWTH
13 REAL-WORLD EVIDENCE SOLUTIONS MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 13.2.1 INCREASED R&D EXPENDITURE IN INNOVATIVE MEDICINES TO DRIVE MARKET GROWTH
- 13.3 MEDTECH COMPANIES
- 13.3.1 NEED TO ACCELERATE MEDTECH MARKET ACCESS VIA REAL-WORLD EVIDENCE SOLUTIONS TO BOOST GROWTH
- 13.4 HEALTHCARE PAYERS
- 13.4.1 INCREASED FOCUS ON OUTCOME-BASED PAYMENT MODELS TO DRIVE DEMAND
- 13.5 PUBLIC PAYERS
- 13.5.1 FOCUS ON ENHANCING PUBLIC PAYER DECISION-MAKING WITH RWE SOLUTIONS TO BOOST MARKET
- 13.6 PRIVATE PAYERS
- 13.6.1 NEED TO LEVERAGE PRIVATE PAYERS FOR SUSTAINABLE RWE SOLUTIONS TO SPUR DEMAND
- 13.7 HEALTHCARE PROVIDERS
- 13.7.1 GROWING FOCUS ON IMPROVED PROFITABILITY TO SUPPORT MARKET GROWTH
- 13.7.2 HOSPITALS
- 13.7.3 CLINICS & OTHER OUTPATIENT SETTINGS
- 13.7.4 OTHER HEALTHCARE PROVIDERS
- 13.8 OTHER END USERS
14 REAL-WORLD EVIDENCE SOLUTIONS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 NORTH AMERICA: MACROECONOMIC OUTLOOK
- 14.2.2 US
- 14.2.2.1 US to account for significant share of North American market
- 14.2.3 CANADA
- 14.2.3.1 Increase in pharma hub growth in Canada to drive market
- 14.3 EUROPE
- 14.3.1 EUROPE: MACROECONOMIC OUTLOOK
- 14.3.2 GERMANY
- 14.3.2.1 High pharmaceutical R&D spending in Germany to boost market growth
- 14.3.3 UK
- 14.3.3.1 Growing adoption of HTA to support market growth
- 14.3.4 FRANCE
- 14.3.4.1 Need for extensive and diversified database to drive market growth
- 14.3.5 ITALY
- 14.3.5.1 High demand for RWE due to widespread use of pay-for-outcomes to drive market
- 14.3.6 SPAIN
- 14.3.6.1 Rising R&D expenditure to propel market growth
- 14.3.7 REST OF EUROPE
- 14.4 ASIA PACIFIC
- 14.4.1 ASIA PACIFIC: MACROECONOMIC OUTLOOK
- 14.4.2 JAPAN
- 14.4.2.1 Stringent regulatory scenario in Japan to restrain market growth
- 14.4.3 CHINA
- 14.4.3.1 Low cost of clinical trials and large pharmaceutical R&D base in China to drive market
- 14.4.4 INDIA
- 14.4.4.1 Growing adoption of outcome-based research to drive market
- 14.4.5 AUSTRALIA
- 14.4.5.1 Policy reforms and strong regulations to support market growth
- 14.4.6 SOUTH KOREA
- 14.4.6.1 Increased focus on pharma R&D to boost market growth
- 14.4.7 REST OF ASIA PACIFIC
- 14.5 LATIN AMERICA
- 14.5.1 LATIN AMERICA: MACROECONOMIC OUTLOOK
- 14.5.2 BRAZIL
- 14.5.2.1 Evolving regulatory frameworks that facilitate clinical research to drive market
- 14.5.3 MEXICO
- 14.5.3.1 Increased funding and investments in pharma R&D to favor growth
- 14.5.4 REST OF LATIN AMERICA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 MIDDLE EAST & AFRICA: MACROECONOMIC OUTLOOK
- 14.6.2 GCC COUNTRIES
- 14.6.2.1 Growing availability of healthcare funding to offer opportunities for market growth
- 14.6.2.2 Saudi Arabia
- 14.6.2.2.1 Digital health reform and regulatory innovation to offer opportunities for market growth
- 14.6.2.3 UAE
- 14.6.2.3.1 Need for driving data-driven healthcare transformation to boost market
- 14.6.2.4 Rest of GCC
- 14.6.3 SOUTH AFRICA
- 14.6.3.1 Emphasis on supporting healthcare infrastructure to drive market growth
- 14.6.4 REST OF MIDDLE EAST & AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 INTRODUCTION
- 15.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS
- 15.3 REVENUE SHARE ANALYSIS
- 15.4 MARKET SHARE ANALYSIS
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.5.5 COMPANY FOOTPRINT
- 15.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES
- 15.6.1 PROGRESSIVE COMPANIES
- 15.6.2 RESPONSIVE COMPANIES
- 15.6.3 DYNAMIC COMPANIES
- 15.6.4 STARTING BLOCKS
- 15.6.5 COMPETITIVE BENCHMARKING
- 15.7 BRAND/PRODUCT COMPARISON
- 15.8 VALUATION AND FINANCIAL METRICS
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT LAUNCHES/ENHANCEMENTS
- 15.9.2 DEALS
- 15.10 KEY PLAYERS
- 15.10.1 IQVIA
- 15.10.1.1 Business overview
- 15.10.1.2 Products offered
- 15.10.1.3 Recent developments
- 15.10.1.3.1 Deals
- 15.10.1.4 MnM view
- 15.10.1.4.1 Key strengths/Right to win
- 15.10.1.4.2 Strategic choices
- 15.10.1.4.3 Weaknesses and competitive threats
- 15.10.2 MERATIVE
- 15.10.2.1 Business overview
- 15.10.2.2 Products offered
- 15.10.2.2.1 Other developments
- 15.10.2.3 MnM view
- 15.10.2.3.1 Key strengths/Right to win
- 15.10.2.3.2 Strategic choices
- 15.10.2.3.3 Weaknesses and competitive threats
- 15.10.3 OPTUM, INC.
- 15.10.3.1 Business overview
- 15.10.3.2 Products offered
- 15.10.3.3 Recent developments
- 15.10.3.3.1 Product launches/developments
- 15.10.3.4 MnM view
- 15.10.3.4.1 Key strengths/Right to win
- 15.10.3.4.2 Strategic choices made
- 15.10.3.4.3 Weaknesses and competitive threats
- 15.10.4 ICON PLC
- 15.10.4.1 Business overview
- 15.10.4.2 Products offered
- 15.10.4.3 Recent developments
- 15.10.4.3.1 Product launches/developments
- 15.10.4.3.2 Deals
- 15.10.4.4 MnM view
- 15.10.4.4.1 Key strengths/Right to win
- 15.10.4.4.2 Strategic choices
- 15.10.4.4.3 Weaknesses and competitive threats
- 15.10.5 SYNEOS HEALTH
- 15.10.5.1 Business overview
- 15.10.5.2 Products offered
- 15.10.5.3 Recent developments
- 15.10.5.3.1 Deals
- 15.10.5.4 MnM view
- 15.10.5.4.1 Key strengths/Right to win
- 15.10.5.4.2 Strategic choices
- 15.10.5.4.3 Weaknesses and competitive threats
- 15.10.6 PAREXEL INTERNATIONAL (MA) CORPORATION
- 15.10.6.1 Business overview
- 15.10.6.2 Products offered
- 15.10.6.3 Recent developments
- 15.10.6.3.1 Product launches/developments
- 15.10.6.3.2 Deals
- 15.10.7 FLATIRON HEALTH
- 15.10.7.1 Business overview
- 15.10.7.2 Products offered
- 15.10.7.3 Recent developments
- 15.10.7.3.1 Product launches/developments
- 15.10.7.3.2 Deals
- 15.10.7.3.3 Expansions
- 15.10.8 FORTREA
- 15.10.8.1 Business overview
- 15.10.8.2 Products offered
- 15.10.8.3 Recent developments
- 15.10.8.3.1 Product launches/developments
- 15.10.8.3.2 Deals
- 15.10.9 ORACLE
- 15.10.9.1 Business overview
- 15.10.9.2 Products offered
- 15.10.9.3 Recent developments
- 15.10.9.3.1 Product launches/developments
- 15.10.9.3.2 Deals
- 15.10.10 ELEVANCE HEALTH
- 15.10.10.1 Business overview
- 15.10.10.2 Products offered
- 15.10.11 SAS INSTITUTE INC.
- 15.10.11.1 Business overview
- 15.10.11.2 Products offered
- 15.10.11.3 Recent developments
- 15.10.11.3.1 Product launches/developments
- 15.10.12 DATAVANT
- 15.10.12.1 Business overview
- 15.10.12.2 Products offered
- 15.10.12.3 Recent developments
- 15.10.12.3.1 Product launches/developments
- 15.10.12.3.2 Deals
- 15.10.13 TRINETX, LLC
- 15.10.13.1 Business overview
- 15.10.13.2 Products offered
- 15.10.13.3 Recent developments
- 15.10.13.3.1 Deals
- 15.10.13.3.2 Expansions
- 15.10.14 TRINITY
- 15.10.14.1 Business overview
- 15.10.14.2 Products offered
- 15.10.14.3 Recent developments
- 15.10.14.3.1 Deals
- 15.10.15 MEDIDATA
- 15.10.15.1 Business overview
- 15.10.15.2 Products offered
- 15.10.15.3 Recent developments
- 15.10.15.3.1 Product launches/developments
- 15.10.15.3.2 Deals
- 15.10.16 COGNIZANT
- 15.10.16.1 Business overview
- 15.10.16.2 Products offered
- 15.10.17 CEGEDIM HEALTH DATA
- 15.10.17.1 Business overview
- 15.10.17.2 Products offered
- 15.10.17.3 Recent developments
- 15.10.17.3.1 Product launches/developments
- 15.10.17.3.2 Deals
- 15.10.18 VERANTOS
- 15.10.18.1 Business overview
- 15.10.18.2 Products offered
- 15.10.18.3 Recent developments
- 15.10.18.3.1 Product launches/developments
- 15.10.18.3.2 Deals
- 15.10.19 MEDPACE
- 15.10.19.1 Business overview
- 15.10.19.2 Products offered
- 15.10.20 TATA CONSULTANCY SERVICES LIMITED
- 15.10.20.1 Business overview
- 15.10.20.2 Products offered
- 15.10.20.3 Recent developments
- 15.10.20.3.1 Deals
- 15.10.1 IQVIA
- 15.11 OTHER PLAYERS
- 15.11.1 HEALTHVERITY, INC.
- 15.11.2 OM1
- 15.11.3 OPEN HEALTH
- 15.11.4 TEMPUS
- 15.11.5 INFINITI RESEARCH (QUANTZIG)
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Key data from primary sources
- 16.1.2.2 Key industry insights
- 16.1.1 SECONDARY DATA
- 16.2 RESEARCH METHODOLOGY DESIGN
- 16.3 MARKET SIZE ESTIMATION
- 16.3.1 BOTTOM-UP APPROACH
- 16.3.2 TOP-DOWN APPROACH
- 16.4 MARKET BREAKDOWN AND DATA TRIANGULATION
- 16.5 RESEARCH ASSUMPTIONS
- 16.6 RISK ASSESSMENT
- 16.7 LIMITATIONS
- 16.7.1 SCOPE-RELATED LIMITATIONS
- 16.7.2 METHODOLOGY-RELATED LIMITATIONS
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS


