

|
시장보고서
상품코드
2149760
모듈형 데이터센터 시장 : 솔루션별, 폼팩터별, 건물 유형별 - 세계 예측(-2031년)Modular Data Center Market by Solution (All-in-one and Prefabricated Modules [IT, Power, Cooling]), Form Factor (ISO Containers [20 feet, 40 feet], Enclosures, Skid-mounted), Build Type (Semi-prefabricated, Fully-prefabricated) - Global Forecast to 2031 |
||||||

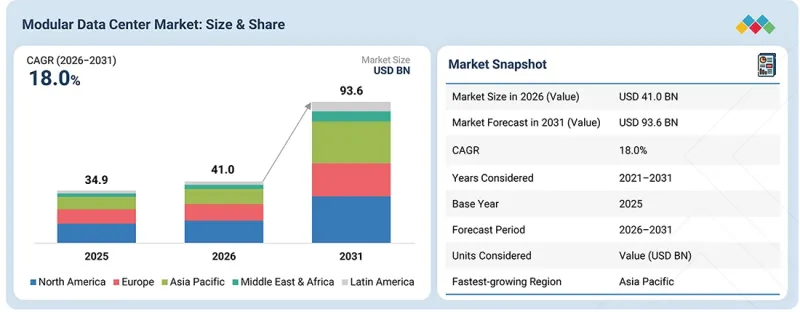
모듈형 데이터센터 시장은 2026년 410억 달러에서 2031년 936억 달러로 성장할 것으로 예상되며, 예측 기간 동안 연평균 성장률(CAGR)은 18.0%에 달할 것으로 전망됩니다.
이러한 시장의 성장은 확장성이 뛰어나고 유연하며 신속하게 구축 가능한 데이터센터 인프라에 대한 수요 증가에 힘입고 있습니다. 모듈형 시설은 기존 데이터센터 건설에 비해 건설 기간을 단축하고, 용량을 신속하게 확장할 수 있으며, 에너지 효율을 향상시킵니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(백만/십억 달러) |
| 부문 | 구성요소, 폼팩터, 구축 유형, 데이터센터 규모, 도입 유형, 최종사용자 및 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카 및 라틴아메리카 |
모듈형 전원 및 냉각 시스템, 조립식 IT 모듈, 그리고 자동화 기술의 발전으로 인해 이러한 시설의 설계, 도입 및 관리가 더욱 개선되고 있습니다. 사전에 설계 및 테스트를 거친 모듈을 통해 현장 시공 요건이 완화되고, 설치 기간이 단축되며, 향후 업그레이드도 용이해집니다. 이러한 이점 덕분에 조직은 도입 및 운영 비용을 절감하면서도 변화하는 IT 인프라 요구 사항에 보다 효율적으로 대응할 수 있게 됩니다. 기업들이 디지털 인프라를 지속적으로 확장해 나가는 가운데, 모듈형 데이터센터는 보다 신속한 도입, 운영 유연성 및 인프라 성능 최적화를 추구하는 조직에게 실용적인 솔루션으로서 그 중요성이 커지고 있습니다.
“구성요소별로 보면 서비스 부문이 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다.”
서비스는 모듈형 데이터센터 시장의 중요한 구성요소이며, 모듈형 시설의 도입, 운영 및 장기적인 성능을 뒷받침합니다. 이러한 서비스에는 주로 설계·컨설팅, 통합·도입, 지원·유지보수가 포함됩니다. 설계·컨설팅 서비스는 공간, 전력, 냉각, 용량에 관한 조직별 요구 사항을 바탕으로 모듈형 데이터센터의 구성을 수립하는 데 도움을 줍니다. 통합·구축 서비스는 모듈형 유닛의 조립, 설치, 시운전을 포괄하며, 진행 중인 업무에 미치는 영향을 최소화하면서 보다 신속한 구축을 가능하게 합니다. 지원 및 유지보수 서비스에는 시스템 가용성을 유지하고 가동 중지 시간을 줄이기 위한 모니터링, 문제 해결, 예방적 유지보수, 기술 지원이 포함됩니다. 모듈형 인프라의 복잡성이 증가하고 신뢰성 높은 운영이 요구됨에 따라, 조직은 시설의 전체 수명주기 동안 전문 서비스 제공업체에 의존하게 되었습니다. 이러한 서비스는 비즈니스 및 기술 요구 사항의 변화에 따른 용량 확장 및 인프라 업그레이드도 지원합니다. 그 결과, 모듈형 데이터센터의 채택이 확대됨에 따라 도입을 간소화하고, 운영 신뢰성을 향상시키며, 인프라 관리 부담을 줄일 수 있는 전문 서비스에 대한 수요가 높아질 것으로 예상됩니다.
“솔루션별로는 예측 기간 동안 조립식 모듈 부문이 가장 큰 점유율을 차지할 것으로 전망됩니다.”
소규모 데이터센터는 최종 사용자와 더 가까운 곳에 컴퓨팅 인프라를 구축하려는 기업 및 기관의 수요가 증가함에 따라 모듈형 데이터센터 시장에서 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 이러한 솔루션에는 조립식 IT 모듈, 조립식 전원 모듈, 조립식 냉각 모듈이 포함되며, 각각 특정 데이터센터 인프라 요구 사항을 충족하도록 설계되었습니다. 이러한 모듈식 아키텍처 덕분에 조직은 건설 공사를 최소화하면서 용량 확장 및 업그레이드가 가능해지며, 기존 데이터센터 건설에 비해 도입 기간과 관련 비용을 절감할 수 있습니다. 조립식 모듈은 금융, 의료, 클라우드 서비스 등 컴퓨팅 요구 사항이 변동하기 쉽거나 급속히 증가하고 있는 산업에 특히 적합합니다. 표준화된 설계를 통해 구축의 일관성이 향상되는 한편, 설치 장소별 요구 사항에 따라 인프라를 유연하게 구성할 수도 있습니다. 또한, 최적화된 전력 및 냉각 구성을 통해 에너지 효율이 향상되어 지속가능성 목표 달성을 지원합니다. 또한 표준화된 모듈을 서로 다른 장소에 배치할 수 있으므로, 이러한 솔루션은 분산형 및 원격지 데이터센터 환경에도 적합합니다. 조직이 인프라의 신속한 도입, 확장성 및 비용 관리를 우선시함에 따라, 조립식 모듈에 대한 수요는 예측 기간 동안 견조한 추세를 보일 것으로 예상됩니다.
“데이터센터 규모별로 보면 예측 기간 동안 소규모 데이터센터가 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다.”
소규모 데이터센터는 최종 사용자와 더 가까운 곳에 컴퓨팅 인프라를 구축하려는 기업 및 기관의 수요가 증가함에 따라 모듈형 데이터센터 시장에서 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 일반적으로 100-1,000제곱피트(약 9.3-92.9㎡) 규모인 소규모 데이터센터는 신속하게 구축할 수 있으며, 컴퓨팅 수요가 증가함에 따라 확장할 수도 있습니다. 최종사용자와 가까운 위치에 있다는 특성 덕분에, 낮은 지연 시간과 처리 성능 향상이 중요한 엣지 컴퓨팅 용도에 최적입니다. 소규모 모듈형 데이터센터에는 인로우 냉각(In-row Cooling), HAC 또는 CAC 등 첨단 냉각 기술을 적용하여 열 관리 성능과 에너지 효율을 개선할 수 있습니다. 또한, 에너지 효율이 높은 장비, 모듈형 UPS 시스템, 고밀도 서버를 통합함으로써 전력 소비와 물리적 공간을 최적화하면서 증가하는 워크로드를 처리할 수 있습니다. 사물인터넷(IoT), 모바일 애플리케이션 및 분산형 디지털 서비스의 확산으로 인해 통신, 의료, 소매업 등 다양한 산업에서 현지화된 컴퓨팅 처리 용량에 대한 수요가 증가하고 있습니다. 이처럼 소규모 모듈형 데이터센터는 작은 설치 공간, 신속한 구축, 뛰어난 확장성 및 분산형 워크로드 지원 능력을 바탕으로 디지털 인프라를 확충하고자 하는 기업과 기관에 점점 더 실용적인 솔루션으로 자리 잡고 있습니다.
주요 참가 기업 개요 내역은 다음과 같습니다:
- 기업 규모별 : 티어 I : 30%, 티어 II : 45%, 티어 III : 25%
- 직책별 : C레벨 임원 : 50%, 이사급 : 35%, 기타 : 15%
- 지역별 : 북미 : 50%, 유럽 : 30%, 아시아태평양 : 15%, 기타 지역 : 5%
참고 : ‘기타’에는 영업 매니저, 마케팅 매니저, 제품 매니저가 포함됩니다.
참고 : ‘기타 지역’에는 중동 및 아프리카 및 라틴아메리카가 포함됩니다.
참고 : Tier 1 기업의 매출은 1억 달러 이상, Tier 2 기업의 매출은 1,000만 달러에서 1억 달러, Tier 3 기업의 매출은 1,000만 달러 미만입니다.
출처 : 2차 자료, 전문가 인터뷰 및 MarketsandMarkets의 분석
조사 범위:
본 조사에서는 시장 동향, 2025년까지의 잠재적 성장, 그리고 2026년부터 2031년까지의 예측을 바탕으로 모듈형 데이터센터 시장에 대한 상세한 분석을 수행하고 있습니다. 또한 모듈형 데이터센터 시장에 대한 상세한 시장 동향, 경쟁 구도, 시장 규모, 전망 및 주요 기업 분석을 제공합니다. 본 시장 조사에서는 모든 주요 지역에서 모듈형 데이터센터의 성장률과 보급률을 분석하고 있습니다.
본 보고서를 구매해야 하는 이유:
본 보고서는 시장을 선도하는 기업 및 신규 진입 기업에게 다음과 같은 측면에서 도움이 됩니다. 모듈형 데이터센터 시장 및 그 하위 부문의 매출에 대한 가장 정확한 추정치에 관한 상세 정보입니다. 본 조사는 이해관계자가 경쟁 구도를 이해하고, 비즈니스 위치를 최적화하며, 적절한 시장 진입 전략을 수립하는 데 도움이 되는 추가적인 인사이트를 제공합니다. 또한, 이해관계자가 시장 동향을 파악하는 데 도움을 주며, 주요 시장 촉진요인, 제약, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 모듈형 데이터센터 시장의 성장에 영향을 미치는 주요 촉진요인(클라우드 컴퓨팅 및 서비스 채택 확대, 확장성, 재해 복구 이점, 엣지 컴퓨팅 도입 확대), 제약요인(높은 초기 설비 투자), 기회(신속한 확장성 및 재해 복구의 이점), 그리고 과제(대규모 데이터센터에서의 확장성, 특수한 요구 사항에 대한 맞춤화 제한, 유지보수의 복잡성)에 대한 분석.
- 제품 개발/혁신 : 모듈형 데이터센터 시장의 향후 기술, 연구 개발 활동 및 신제품·서비스 출시에 대한 상세한 인사이트.
- 시장 개발 : 모듈형 데이터센터 시장의 향후 기술, 연구 개발 활동 및 신제품·서비스 출시에 대한 상세한 분석.
- 시장 다각화 : 모듈형 데이터센터 시장의 최신 제품 및 서비스, 미개척 지역, 최근 동향 및 투자에 대한 종합적인 상세 정보.
- 경쟁 평가 : 시장 점유율, 성장 전략, 모듈형 데이터센터 시장의 주요 기업에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 모듈형 데이터센터 시장에서 사업자를 위한 매력적인 성장 기회
- 모듈형 데이터센터 시장 점유율(구성요소별)
- 모듈형 데이터센터 솔루션 시장 점유율(유형별)
- 모듈형 데이터센터 시장 점유율, 조립식 모듈(유형별)
- 모듈형 데이터센터 서비스 시장 점유율(유형별)
- 모듈형 데이터센터 시장 점유율(폼팩터별)
- 모듈형 데이터센터 시장 점유율, 인클로저(유형별)
- 모듈형 데이터센터 시장 점유율, ISO 컨테이너(유형별)
- 모듈형 데이터센터 시장 점유율, 스키드 마운트형 시스템(유형별)
- 모듈형 데이터센터 시장 점유율(배치 유형별)
- 모듈형 데이터센터 시장 점유율(건물 유형별)
- 모듈형 데이터센터 시장 점유율(데이터센터 규모별)
- 모듈형 데이터센터 시장 점유율(최종사용자별)
- 모듈형 데이터센터 시장(지역별)
제4장 시장 개요 및 업계 동향
- 시장 역학
- 성장 촉진요인
- 성장 억제요인
- 기회
- 과제
- 미충족 수요 및 미개척 분야
- 모듈형 데이터센터 시장의 미충족 수요
- 미개척 시장의 기회
- 상호 연관된 시장 및 부문 간 기회
- 부문 간 기회
- Tier 1/2/3 주요 기업들의 전략적 움직임
- Porter's Five Forces 분석
- 신규 진입자의 위협
- 대체품의 위협
- 구매자의 협상력
- 공급업체의 협상력
- 경쟁 기업 간의 적대적 관계
- 거시경제 지표
- GDP 동향 및 전망
- 세계 데이터센터 솔루션 업계 동향
- 모듈형 데이터센터용 UPS 시장의 동향
- 공급망 분석
- 생태계 분석
- 가격 분석
- 솔루션별, 주요 기업의 평균 판매 가격 동향
- 지역별 평균 판매 가격 동향
- 2026-2027년 주요 컨퍼런스 및 행사
- 고객의 비즈니스에 영향을 미치는 동향/파괴적 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- T-SYSTEMS와 VERTIV : 바르셀로나에서의 모듈형 데이터센터 신속 도입
- 루저우 시 정부, 스마트 시티 개발을 위한 고효율 모듈형 데이터센터 구축을 위해 화웨이와 제휴
- 사그라다 파밀리아 대성당, 슈나이더 일렉트릭과 제휴하여 최첨단 모바일 데이터센터 구축
- MEEZA, VERTIV와 제휴하여 모듈형 데이터센터를 신속하게 확장
- ANIMAL LOGIC은 슈나이더 일렉트릭과 제휴하여 확장성이 뛰어나고 고성능인 조립식 모듈형 데이터센터를 도입했습니다
- 주요 요금 체계
- 가격 영향 분석
- 국가·지역별 영향
- 산업별 영향
- 기술 분석
- 주요 기술
- 보완 기술
- 인접 기술
- 무역 분석
- 기술·제품 로드맵
- 단기(2026-2028년) | 조립식화, 신속한 구축 및 AI 대응 인프라
- 중기(2028-2031년) | 고밀도·에너지 통합형·지능형 모듈형 데이터센터
- 장기(2031-2036년 이후) | 자율형·지속가능·적응형 모듈형 데이터센터
- 특허 분석
- 미래 응용
- AI를 활용한 모듈형 데이터센터의 설계 및 용량 계획
- 자율적 배포 및 워크로드 최적화
- 지능형 전력·냉각 관리
- AI를 활용한 원격 모니터링 및 예측 유지보수
- 에너지 효율이 뛰어나고 지속가능한 모듈형 데이터센터 운영
- 모듈형 데이터센터 시장에 대한 AI/생성형 AI의 영향
- 주요 활용 사례 및 시장의 잠재력
- 모듈형 데이터센터 시장의 모범 사례
- 모듈형 데이터센터 시장에서 AI 도입에 대한 사례 연구
- AI/생성형 AI를 도입하고 있는 주요 벤더
- 모듈형 데이터센터의 적용 사례
- 용량 확장
- 데이터센터 확장
- 재해 복구
- 비상 상황 및 일시적 구축
- 엣지 컴퓨팅
- 상호연결된 인접 생태계 및 시장 참여자에 미치는 영향
- 모듈형 데이터센터 시장에서 생성형 AI 도입에 대한 고객의 준비 현황
- 규제 현황
- 규제 기관, 정부 기관 및 기타 조직
- 지역별 규제
- 의사결정 과정
- 주요 이해관계자 및 구매 기준
- 조달 프로세스 내 주요 이해관계자
- 구매 기준
- 도입 장벽 및 내부 과제
- 각 최종사용자 산업 분야의 미충족 수요
- 시장의 수익성
- 수익 창출 가능성
- 비용 동향
- 주요 용도에서의 이익률 향상 기회
- 비즈니스 모델 분석
- 제품 라인업
- 수익원
- 수익 모델 동향
- 판매 채널
- 고객 부문
- 모듈형 데이터센터 활용 사례
- 용량 확장
- 데이터센터 확장
- 재해 복구
- 긴급 상황 및 일시적 도입
- 엣지 컴퓨팅
제5장 모듈형 데이터센터 시장 : 구성요소별
- 솔루션
- 서비스
제6장 모듈형 데이터센터 시장 : 폼팩터별
- ISO 컨테이너
- 스키드 마운트형 시스템
- 인클로저
제7장 모듈형 데이터센터 시장 : 건물 유형별
- 반조립식 데이터센터
- 완전 프리팹형 데이터센터
- 올인원형 데이터센터
제8장 모듈형 데이터센터 시장 : 데이터센터 규모별
- 소규모 데이터센터
- 중규모 데이터센터
- 대규모 데이터센터
제9장 모듈형 데이터센터 시장 : 구축 유형별
- 실내
- 실외
제10장 모듈형 데이터센터 시장 : 최종사용자별
- 통신 서비스 제공업체
- 클라우드 서비스 제공업체
- 기업
제11장 모듈형 데이터센터 시장 : 지역별
- 북미
- 북미 : 모듈형 데이터센터 시장의 성장 촉진요인
- 북미 : 거시경제 전망
- 미국
- 캐나다
- 유럽
- 유럽 : 모듈형 데이터센터 시장의 성장 촉진요인
- 유럽 : 거시경제 전망
- 영국
- 독일
- 프랑스
- 이탈리아
- 기타 유럽
- 아시아태평양
- 아시아태평양 : 모듈형 데이터센터 시장의 성장 촉진요인
- 아시아태평양 : 거시경제 전망
- 중국
- 일본
- 호주 및 뉴질랜드
- 기타 아시아태평양
- 중동 및 아프리카
- 중동 및 아프리카 : 모듈형 데이터센터 시장의 촉진요인
- 중동 및 아프리카 : 거시경제 전망
- 걸프협력회의(GCC) 회원국
- 남아프리카
- 기타 중동 및 아프리카
- 라틴아메리카
- 라틴아메리카 : 모듈형 데이터센터 시장의 성장 촉진요인
- 라틴아메리카 : 거시경제 전망
- 브라질
- 멕시코
- 기타 라틴아메리카
제12장 경쟁 현황
- 주요 업체가 채택한 전략/유력 기업
- 시장 점유율 분석
- 벤더별 제품·브랜드 비교
- DELL TECHNOLOGIES - EMC MDC
- SCHNEIDER ELECTRIC - ECOSTRUXURE
- VERTIV - MEGAMOD
- HUAWEI - FUSIONMODULE2000
- EATON - SMARTRACK
- 수익 분석
- 기업 평가 매트릭스 : 주요 기업, 2025년
- 스타 기업
- 신흥 리더
- 광범위한 업체
- 진입 기업
- 기업의 사업 전개 : 주요 기업, 2025년
- 기업 평가 매트릭스 : 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹 : 스타트업/중소기업, 2025년
- 주요 벤더의 기업 가치 평가 및 재무 지표
- 기업 가치 평가
- 재무 지표
- 경쟁 시나리오
- 제품 출시
- 거래
제13장 기업 개요
- 주요 기업
- DELL
- VERTIV
- SCHNEIDER ELECTRIC
- HUAWEI
- EATON
- RITTAL
- JOHNSON CONTROLS
- ABB
- DELTA ELECTRONICS
- STULZ
- HUBBELL(PCX)
- 기타 주요 기업
- IE CORP.
- CANNON TECHNOLOGIES
- EDGE MCS
- ASPERITAS
- RETEX
- BOX MODUL
- BLADEROOM
- WESCO INTERNATIONAL, INC.
- FIBERHOME
- SCALEMATRIX
- EQUINIX
- 365 DATA CENTERS
- CUPERTINO ELECTRIC(QUANTA SERVICES)
- K-STAR
- IEM
- MODULAR POWER SOLUTIONS
- FAITH TECHNOLOGIES INCORPORATED(FTI)
- M.C. DEAN
- DATA SPECIALTIES INC.
- TOTAL SITE SOLUTIONS
- ENVIRONMENTAL AIR SYSTEMS
- TAS
- AWS
- META
- ORACLE
- MICROSOFT
- APPLE
- INTEL
- NVIDIA
- IBM
- SIEMENS
- HPE
제14장 조사 방법론
제15장 부록
KSM 26.10.23The modular data center market is expected to grow from USD 41.0 billion in 2026 to USD 93.6 billion by 2031 at a CAGR of 18.0% during the forecast period. Market growth is driven by the increasing demand for scalable, flexible, and rapidly deployable data center infrastructure. Modular facilities reduce construction time, enable faster capacity expansion, and improve energy efficiency compared with conventional data center development.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) |
| Segments | Component, Form Factor, Build Type, Data Center Size, Deployment Type, End User and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
Advancements in modular power and cooling systems, prefabricated IT modules, and automation are further improving the design, deployment, and management of these facilities. Pre-engineered and pre-tested modules reduce on-site construction requirements, shorten installation timelines, and simplify future upgrades. These advantages allow organizations to respond more efficiently to changing IT infrastructure requirements while controlling deployment and operational costs. As enterprises continue to expand their digital infrastructure, modular data centers are gaining importance as a practical solution for organizations seeking faster deployment, operational flexibility, and optimized infrastructure performance.
"By component, the services segment will grow at the highest CAGR during the forecast period."
Services are an important component of the modular data center market, supporting the deployment, operation, and long-term performance of modular facilities. These services primarily include design & consulting, integration & deployment, and support & maintenance. Design and consulting services help organizations develop modular data center configurations based on their specific requirements for space, power, cooling, and capacity. Integration and deployment services cover the assembly, installation, and commissioning of modular units, enabling faster deployment with limited disruption to ongoing operations. Support and maintenance services include monitoring, troubleshooting, preventive maintenance, and technical assistance to maintain system availability and reduce downtime. The increasing complexity of modular infrastructure and the need for reliable operation are driving organizations to rely on specialized service providers throughout the facility lifecycle. These services also support capacity expansion and infrastructure upgrades as business and technology requirements change. Consequently, the growing adoption of modular data centers is expected to increase demand for professional services that can simplify deployment, improve operational reliability, and reduce infrastructure management requirements.
"By solution, the prefabricated modules segment will hold the largest share during the forecast period."
Prefabricated modules are expected to account for the largest share of the modular data center market during the forecast period due to their ability to provide standardized, pre-engineered, and rapidly deployable infrastructure. These solutions include prefabricated IT modules, prefabricated power modules, and prefabricated cooling modules, each designed to address specific data center infrastructure requirements. Their modular architecture allows organizations to expand or upgrade capacity with less construction work, reducing deployment time and associated costs compared with traditional data center development. Prefabricated modules are particularly suitable for industries with variable or rapidly increasing computing requirements, including finance, healthcare, and cloud services. Standardized designs also improve deployment consistency while providing flexibility to configure infrastructure according to site-specific requirements. In addition, optimized power and cooling configurations can improve energy efficiency and support sustainability objectives. The ability to deploy standardized modules across different locations also makes these solutions suitable for distributed and remote data center environments. As organizations prioritize faster infrastructure deployment, scalability, and cost control, demand for prefabricated modules is expected to remain strong throughout the forecast period.
"As per data center size, the small data center will grow with the highest CAGR during the forecast period."
Small data centers are expected to register the highest CAGR in the modular data center market as organizations increasingly require compact and flexible computing infrastructure closer to end users. Typically ranging from 100 to 1,000 square feet, these facilities can be deployed rapidly and expanded as computing requirements increase. Their proximity to end users makes them well suited for edge computing applications, where reduced latency and improved processing performance are important. Small modular data centers can incorporate advanced cooling technologies, including in-row cooling and hot-aisle or cold-aisle containment, to improve thermal management and energy efficiency. They may also integrate energy-efficient equipment, modular UPS systems, and high-density servers to support growing workloads while optimizing power consumption and physical space. The expansion of IoT, mobile applications, and distributed digital services is increasing the need for localized computing capacity across industries such as telecommunications, healthcare, and retail. Their compact footprint, rapid deployment, scalability, and ability to support distributed workloads position small modular data centers as an increasingly practical solution for organizations expanding their digital infrastructure.
The breakdown of the profiles of the primary participants is below:
- By Company: Tier I: 30%, Tier II: 45%, and Tier III: 25%
- By Designation: C-Level Executives: 50%, Director Level: 35%, and Others: 15%
- By Region: North America: 50%, Europe: 30%, Asia Pacific: 15%, Rest of World: 5%
Note: Others include sales managers, marketing managers, and product managers
Note: The rest of the World consists of the Middle East & Africa and Latin America
Note: Tier 1 companies have revenues of more than USD 100 million; tier 2 companies' revenue ranges from USD 10 million to USD 100 million; and tier 3 companies' revenue is less than 10 million
Source: Secondary Literature, Expert Interviews, and MarketsandMarkets Analysis
Major companies offering modular data center solutions and services are Dell (US), Schneider Electric (France), Vertiv (US), Johnson Controls (US), Eaton (US), Delta Electronics (Taiwan), Huawei (China), ABB (Switzerland), Stulz (Germany), Rittal (Germany), Hubbell (PCX) (US).
Research coverage:
In this study, an in-depth analysis of the modular data center market is done based on market trends, potential growth during 2025, and a forecast up to 2026-2031. Further, it provides detailed market trends, a competitive landscape, market size, forecasts, and key players' analysis of the modular data center market. This market study analyzes the growth rate and penetration of modular data centers across all the major regions.
Reasons to buy this report:
The report will aid the market leaders/new entrants in the following: Details regarding the closest approximations of the revenue numbers for the modular data center market and its subsegments. This study will aid the stakeholders in understanding the competitive landscape; it gives more insights to position their businesses better and plan suitable go-to-market strategies. It also helps the stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of critical drivers (rising adoption of cloud computing and services, scalability, disaster recovery benefits, and the growth in edge computing deployments), restraints (high initial capital expenditure), opportunities (rapid scalability and disaster recovery benefits), and challenges (scalability in large data centers, limited customization for specialized needs, and increased maintenance complexity) influencing the growth of the modular data center market.
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the modular data center market.
- Market Development: In-depth understanding of upcoming technologies, research & development efforts, and new product & service releases in the modular data center market.
- Market Diversification: Comprehensive details on the latest products & services, unexplored regions, recent advancements, and investments in the modular data center market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and Dell (US), Schneider Electric (France), Vertiv (US), Johnson Controls (US), Eaton (US), Delta Electronics (Taiwan), Huawei (China), ABB (Switzerland), Stulz (Germany), Rittal (Germany), Hubbell (PCX) (US), among others in the modular data center market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION & REGIONS COVERED
- 1.3.2 INCLUSIONS AND EXCLUSIONS OF STUDY
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN MODULAR DATA CENTER MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE GROWTH OPPORTUNITIES FOR PLAYERS IN MODULAR DATA CENTER MARKET
- 3.2 MODULAR DATA CENTER MARKET SHARE, BY COMPONENT
- 3.3 MODULAR DATA CENTER SOLUTIONS MARKET SHARE, BY TYPE
- 3.4 MODULAR DATA CENTER MARKET SHARE FOR PREFABRICATED MODULES, BY TYPE
- 3.5 MODULAR DATA CENTER SERVICES MARKET SHARE, BY TYPE
- 3.6 MODULAR DATA CENTER MARKET SHARE, BY FORM FACTOR
- 3.7 MODULAR DATA CENTER MARKET SHARE FOR ENCLOSURES, BY TYPE
- 3.8 MODULAR DATA CENTER MARKET SHARE FOR ISO CONTAINERS, BY TYPE
- 3.9 MODULAR DATA CENTER MARKET SHARE FOR SKID-MOUNTED SYSTEMS, BY TYPE
- 3.10 MODULAR DATA CENTER MARKET SHARE, BY DEPLOYMENT TYPE
- 3.11 MODULAR DATA CENTER MARKET SHARE, BY BUILD TYPE
- 3.12 MODULAR DATA CENTER MARKET SHARE, BY DATA CENTER SIZE
- 3.13 MODULAR DATA CENTER MARKET SHARE, BY END USER
- 3.14 MODULAR DATA CENTER MARKET, BY REGION
4 MARKET OVERVIEW AND INDUSTRY TRENDS
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Accelerating adoption of cloud computing and mobility benefits enables organizations to achieve rapid deployment and scalable infrastructure
- 4.2.1.2 Expanding cloud and mobility requirements drive the rapid deployment of scalable and flexible data center solutions
- 4.2.1.3 Increasing reliance on cloud services and disaster recovery capabilities empowers businesses to deploy infrastructure with unprecedented speed
- 4.2.2 RESTRAINTS
- 4.2.2.1 Heavy initial capital expenditures on modular solutions restrict organizations from achieving rapid market adoption
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Surging market demand for IoT, AI, and 5G technologies necessitates advanced data infrastructure, opening growth avenues in edge computing
- 4.2.3.2 Expanding deployment of edge computing driven by IoT and AI trends creates lucrative opportunities for specialized modular infrastructure
- 4.2.4 CHALLENGES
- 4.2.4.1 Encountering complex maintenance requirements and rigid customization limits hampers the seamless scaling of large data center projects
- 4.2.4.2 Managing intricate maintenance procedures and restricted customization options obstructs the smooth expansion of major data center initiatives
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN MODULAR DATA CENTER MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.6 PORTER'S FIVE FORCES ANALYSIS
- 4.6.1 THREAT OF NEW ENTRANTS
- 4.6.2 THREAT OF SUBSTITUTES
- 4.6.3 BARGAINING POWER OF BUYERS
- 4.6.4 BARGAINING POWER OF SUPPLIERS
- 4.6.5 INTENSITY OF COMPETITIVE RIVALRY
- 4.7 MACROECONOMIC INDICATORS
- 4.7.1 INTRODUCTION
- 4.7.2 GDP TRENDS & FORECASTS
- 4.7.3 TRENDS IN GLOBAL DATA CENTER SOLUTIONS INDUSTRY
- 4.7.4 TRENDS IN MODULAR DATA CENTER UPS MARKET
- 4.8 SUPPLY CHAIN ANALYSIS
- 4.9 ECOSYSTEM ANALYSIS
- 4.10 PRICING ANALYSIS
- 4.10.1 AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY SOLUTION
- 4.10.2 AVERAGE SELLING PRICE TREND, BY REGION
- 4.11 KEY CONFERENCES AND EVENTS, 2026-2027
- 4.12 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 4.13 INVESTMENT AND FUNDING SCENARIO
- 4.14 CASE STUDY ANALYSIS
- 4.14.1 T-SYSTEMS AND VERTIV: RAPID DEPLOYMENT OF MODULAR DATA CENTER IN BARCELONA
- 4.14.2 LUZHOU GOVERNMENT PARTNERED WITH HUAWEI TO BUILD EFFICIENT MODULAR DATA CENTER FOR SMART CITY DEVELOPMENT
- 4.14.3 BASILICA DE LA SAGRADA FAMILIA PARTNERED WITH SCHNEIDER ELECTRIC FOR STATE-OF-THE-ART MOBILE DATA CENTER
- 4.14.4 MEEZA COLLABORATED WITH VERTIV TO RAPIDLY SCALE MODULAR DATA CENTERS
- 4.14.5 ANIMAL LOGIC PARTNERED WITH SCHNEIDER ELECTRIC TO DEPLOY SCALABLE, HIGH-PERFORMANCE PREFABRICATED MODULAR DATA CENTER
- 4.14.6 KEY TARIFF RATES
- 4.14.7 PRICE IMPACT ANALYSIS
- 4.14.8 IMPACT ON COUNTRIES/REGIONS
- 4.14.8.1 US
- 4.14.8.2 Europe
- 4.14.8.3 Asia Pacific
- 4.14.9 IMPACT ON VERTICALS
- 4.14.9.1 BFSI
- 4.14.9.2 Cloud services providers & hyperscalers
- 4.14.9.3 Manufacturing
- 4.14.9.4 Government & public sector
- 4.15 TECHNOLOGY ANALYSIS
- 4.15.1 KEY TECHNOLOGIES
- 4.15.1.1 Modular design
- 4.15.1.2 Power distribution units (PDUs)
- 4.15.1.3 Data center infrastructure management (DCIM) software
- 4.15.1.4 Cooling systems
- 4.15.2 COMPLEMENTARY TECHNOLOGIES
- 4.15.2.1 Virtualization
- 4.15.2.2 Software-defined networking
- 4.15.2.3 Storage area networks
- 4.15.2.4 Advanced battery storage
- 4.15.3 ADJACENT TECHNOLOGIES
- 4.15.3.1 Edge computing
- 4.15.3.2 Artificial intelligence & machine learning
- 4.15.3.3 Digital twins
- 4.15.3.4 Augmented reality
- 4.15.1 KEY TECHNOLOGIES
- 4.16 TRADE ANALYSIS
- 4.17 TECHNOLOGY/PRODUCT ROADMAP
- 4.17.1 SHORT-TERM (2026-2028) | PREFABRICATION, RAPID DEPLOYMENT & AI-READY INFRASTRUCTURE
- 4.17.2 MID-TERM (2028-2031) | HIGH-DENSITY, ENERGY-INTEGRATED & INTELLIGENT MODULAR DATA CENTERS
- 4.17.3 LONG-TERM (2031-2036+) | AUTONOMOUS, SUSTAINABLE & ADAPTIVE MODULAR DATA CENTERS
- 4.18 PATENT ANALYSIS
- 4.19 FUTURE APPLICATIONS
- 4.19.1 AI-DRIVEN MODULAR DATA CENTER DESIGN & CAPACITY PLANNING
- 4.19.2 AUTONOMOUS DEPLOYMENT & WORKLOAD OPTIMIZATION
- 4.19.3 INTELLIGENT POWER & COOLING MANAGEMENT
- 4.19.4 AI-ENABLED REMOTE MONITORING & PREDICTIVE MAINTENANCE
- 4.19.5 ENERGY-EFFICIENT & SUSTAINABLE MODULAR DATA CENTER OPERATIONS
- 4.20 IMPACT OF AI/GENERATIVE AI ON MODULAR DATA CENTER MARKET
- 4.20.1 TOP USE CASES AND MARKET POTENTIAL
- 4.20.2 BEST PRACTICES IN MODULAR DATA CENTER MARKET
- 4.20.3 CASE STUDY OF AI IMPLEMENTATION IN MODULAR DATA CENTER MARKET
- 4.20.3.1 Leading retailer enhanced distribution efficiency with AI-driven Vertiv's SmartRow solution
- 4.20.4 TOP VENDORS ADOPTING AI/GEN AI
- 4.20.4.1 Vertiv
- 4.20.4.2 Alibaba Cloud
- 4.21 APPLICATIONS OF MODULAR DATA CENTER
- 4.21.1 CAPACITY EXPANSION
- 4.21.2 DATA CENTER EXPANSION
- 4.21.3 DISASTER RECOVERY
- 4.21.4 EMERGENCY & TEMPORARY DEPLOYMENT
- 4.21.5 EDGE COMPUTING
- 4.21.6 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 4.21.7 CLIENT READINESS TO ADOPT GENERATIVE AI IN MODULAR DATA CENTER MARKET
- 4.22 REGULATORY LANDSCAPE
- 4.22.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 4.22.2 REGULATIONS, BY REGION
- 4.23 DECISION-MAKING PROCESS
- 4.24 KEY STAKEHOLDERS AND BUYING CRITERIA
- 4.24.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 4.24.2 BUYING CRITERIA
- 4.25 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 4.26 UNMET NEEDS IN VARIOUS END-USER INDUSTRIES
- 4.27 MARKET PROFITABILITY
- 4.27.1 REVENUE POTENTIAL
- 4.27.2 COST DYNAMICS
- 4.27.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
- 4.28 BUSINESS MODEL ANALYSIS
- 4.28.1 PRODUCT OFFERING
- 4.28.2 REVENUE STREAMS
- 4.28.3 REVENUE MODEL TRENDS
- 4.28.4 CHANNELS
- 4.28.5 CUSTOMER SEGMENTS
- 4.29 APPLICATIONS OF MODULAR DATA CENTER
- 4.29.1 CAPACITY EXPANSION
- 4.29.2 DATA CENTER EXPANSION
- 4.29.3 DISASTER RECOVERY
- 4.29.4 EMERGENCY & TEMPORARY DEPLOYMENT
- 4.29.5 EDGE COMPUTING
5 MODULAR DATA CENTER MARKET, BY COMPONENT
- 5.1 INTRODUCTION
- 5.1.1 COMPONENT: MODULAR DATA CENTER MARKET DRIVERS
- 5.2 SOLUTIONS
- 5.2.1 ALL-IN-ONE SOLUTIONS
- 5.2.1.1 Rising edge-computing demand to fuel adoption
- 5.2.2 PREFABRICATED MODULES
- 5.2.2.1 Rapid scalability to drive adoption of prefabricated modules
- 5.2.2.2 Prefabricated IT modules
- 5.2.2.2.1 Optimized IT infrastructure for rapid deployment to propel market
- 5.2.2.2.2 Servers
- 5.2.2.2.3 Networks
- 5.2.2.2.4 Storage
- 5.2.2.2.5 Others
- 5.2.2.3 Prefabricated power modules
- 5.2.2.3.1 Improved power distribution for critical loads to drive market
- 5.2.2.3.2 Power distribution units
- 5.2.2.3.3 Switchgear
- 5.2.2.3.4 Uninterruptible power supplies
- 5.2.2.3.5 Generators
- 5.2.2.3.6 Others
- 5.2.2.4 Prefabricated cooling modules
- 5.2.2.4.1 Enhanced energy efficiency to drive adoption in modular data centers
- 5.2.2.4.2 Chiller modules
- 5.2.2.4.3 Air handling units
- 5.2.2.4.4 Direct expansion cooling
- 5.2.2.4.5 Others
- 5.2.1 ALL-IN-ONE SOLUTIONS
- 5.3 SERVICES
- 5.3.1 DESIGN & CONSULTING
- 5.3.1.1 Growing demand for end-to-end solutions to drive market
- 5.3.2 INTEGRATION & DEPLOYMENT
- 5.3.2.1 Integration and deployment services to streamline setup and operation of prefabricated data centers
- 5.3.3 SUPPORT & MAINTENANCE
- 5.3.3.1 Support and maintenance services to ensure optimal performance, reliability, and longevity of infrastructure
- 5.3.1 DESIGN & CONSULTING
6 MODULAR DATA CENTER MARKET, BY FORM FACTOR
- 6.1 INTRODUCTION
- 6.1.1 FORM FACTOR: MODULAR DATA CENTER MARKET DRIVERS
- 6.2 ISO CONTAINERS
- 6.2.1 20-FEET CONTAINERS
- 6.2.1.1 20-feet containers to provide flexible, small-scale modular solutions for rapid IT capacity expansion
- 6.2.2 40-FEET CONTAINERS
- 6.2.2.1 40-feet containers to offer high-density computing and storage capacity for large-scale data centers
- 6.2.1 20-FEET CONTAINERS
- 6.3 SKID-MOUNTED SYSTEMS
- 6.3.1 FIXED SKID-MOUNTED SYSTEMS
- 6.3.1.1 Cost-effective modular deployment for long-term scalability to drive market
- 6.3.2 PORTABLE SKID-MOUNTED SYSTEMS
- 6.3.2.1 Portable skid-mounted systems to offer rapidly deployable solutions for temporary or remote data center applications
- 6.3.1 FIXED SKID-MOUNTED SYSTEMS
- 6.4 ENCLOSURES
- 6.4.1 LOW-DENSITY ENCLOSURES
- 6.4.1.1 Low-density enclosures to suit environments where equipment density stays low priority
- 6.4.2 MEDIUM-DENSITY ENCLOSURES
- 6.4.2.1 Medium-density enclosures to provide balanced performance for scalable growth in mid-range applications
- 6.4.3 HIGH-DENSITY ENCLOSURES
- 6.4.3.1 High-density enclosures to offer advanced infrastructure for high-density computing and storage demands
- 6.4.1 LOW-DENSITY ENCLOSURES
7 MODULAR DATA CENTER MARKET, BY BUILD TYPE
- 7.1 INTRODUCTION
- 7.1.1 BUILD TYPE: MODULAR DATA CENTER MARKET DRIVERS
- 7.2 SEMI PREFABRICATED DATA CENTERS
- 7.2.1 FLEXIBILITY AND ENERGY EFFICIENCY TO DRIVE DEMAND FOR SEMI-PREFABRICATED DATA CENTERS IN VARIOUS INDUSTRIES
- 7.3 FULLY PREFABRICATED DATA CENTERS
- 7.3.1 RAPID DEPLOYMENT AND SCALABILITY TO FUEL MARKET GROWTH
- 7.4 ALL-IN-ONE DATA CENTERS
- 7.4.1 ALL-IN-ONE DATA CENTERS TO MEET DIVERSE NEEDS OF BUSINESSES
8 MODULAR DATA CENTER MARKET, BY DATA CENTER SIZE
- 8.1 INTRODUCTION
- 8.1.1 DATA CENTER SIZE: MODULAR DATA CENTER MARKET DRIVERS
- 8.2 SMALL DATA CENTERS
- 8.2.1 LOCALIZED COMPUTING NEEDS TO DRIVE GROWTH
- 8.3 MID-SIZED DATA CENTERS
- 8.3.1 MID-SIZED DATA CENTERS TO ACCOMMODATE INCREASING DEMAND FOR PROCESSING POWER AND STORAGE
- 8.4 LARGE DATA CENTERS
- 8.4.1 LARGE DATA CENTERS TO HANDLE SIGNIFICANT WORKLOADS AND HIGH-DENSITY COMPUTING REQUIREMENTS
9 MODULAR DATA CENTER MARKET, BY DEPLOYMENT TYPE
- 9.1 INTRODUCTION
- 9.1.1 DATA CENTER SIZE: MODULAR DATA CENTER MARKET DRIVERS
- 9.2 INDOOR
- 9.2.1 INDOOR DEPLOYMENT TO HELP ORGANIZATIONS MAXIMIZE EXISTING SPACE
- 9.3 OUTDOOR
- 9.3.1 RAPID SCALABILITY AND LOCATION FLEXIBILITY TO DRIVE GROWTH
10 MODULAR DATA CENTER MARKET, BY END USER
- 10.1 INTRODUCTION
- 10.1.1 END USER: MODULAR DATA CENTER MARKET DRIVERS
- 10.2 TELCOM SERVICE PROVIDERS
- 10.2.1 RAPID SCALABILITY AND FLEXIBILITY TO PROPEL ADOPTION OF MODULAR DATA CENTERS
- 10.3 CLOUD SERVICE PROVIDERS
- 10.3.1 SCALABILITY AND FLEXIBILITY TO DRIVE ADOPTION OF MODULAR DATA CENTERS
- 10.4 ENTERPRISES
- 10.4.1 GROWING DATA DEMAND TO DRIVE MARKET
- 10.4.2 BFSI
- 10.4.2.1 Growing digital economy to drive adoption
- 10.4.2.2 BFSI: Use cases
- 10.4.2.2.1 Disaster recovery & business continuity
- 10.4.2.2.2 Scalable data processing
- 10.4.2.2.3 Compliance & security
- 10.4.2.2.4 Others
- 10.4.3 IT & TELECOM
- 10.4.3.1 Accelerating digital transformation to drive market
- 10.4.3.2 IT & telecom: Use cases
- 10.4.3.2.1 Edge computing
- 10.4.3.2.2 Disaster recovery
- 10.4.3.2.3 Data center expansion
- 10.4.3.2.4 Others
- 10.4.4 GOVERNMENT & DEFENSE
- 10.4.4.1 Rising national security demand to drive growth
- 10.4.4.2 Government & defense: Use cases
- 10.4.4.2.1 Tactical data centers
- 10.4.4.2.2 Disaster recovery & continuity of operations
- 10.4.4.2.3 Secure & classified information processing & storage
- 10.4.4.2.4 Others
- 10.4.5 HEALTHCARE & LIFE SCIENCES
- 10.4.5.1 Growing digital health demand to fuel adoption
- 10.4.5.2 Healthcare & life sciences: Use cases
- 10.4.5.2.1 Health information management
- 10.4.5.2.2 Telemedicine & remote health services
- 10.4.5.2.3 Others
- 10.4.6 RETAIL & E-COMMERCE
- 10.4.6.1 Surge in online shopping to drive retail adoption for efficiency
- 10.4.6.2 Retail & E-commerce: Use cases
- 10.4.6.2.1 E-commerce & online retail platforms
- 10.4.6.2.2 Point-of-sale systems
- 10.4.6.2.3 Inventory management
- 10.4.6.2.4 Others
- 10.4.7 MEDIA & ENTERTAINMENT
- 10.4.7.1 Enhanced content delivery and user experience to support market growth
- 10.4.7.2 Media & entertainment: Use cases
- 10.4.7.2.1 Content delivery networks
- 10.4.7.2.2 Post-production & video editing
- 10.4.7.2.3 Broadcasting & live streaming
- 10.4.7.2.4 Others
- 10.4.8 MANUFACTURING
- 10.4.8.1 Operational efficiency and digital transformation to drive adoption
- 10.4.8.2 Manufacturing: Use cases
- 10.4.8.2.1 Manufacturing process control
- 10.4.8.2.2 Supply chain management
- 10.4.8.2.3 Quality control & testing
- 10.4.8.2.4 Others
- 10.4.9 OTHER VERTICALS
11 MODULAR DATA CENTER MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 NORTH AMERICA
- 11.2.1 NORTH AMERICA: MODULAR DATA CENTER MARKET DRIVERS
- 11.2.2 NORTH AMERICA: MACROECONOMIC OUTLOOK
- 11.2.3 US
- 11.2.3.1 Technological advancements and large-scale investments to propel market growth
- 11.2.4 CANADA
- 11.2.4.1 Tax incentives and infrastructure investments to spur market growth
- 11.3 EUROPE
- 11.3.1 EUROPE: MODULAR DATA CENTER MARKET DRIVERS
- 11.3.2 EUROPE: MACROECONOMIC OUTLOOK
- 11.3.3 UK
- 11.3.3.1 Investments by cloud vendors and hyperscalers to boost market growth
- 11.3.4 GERMANY
- 11.3.4.1 Energy efficiency and heavy investment to power market growth
- 11.3.5 FRANCE
- 11.3.5.1 Government incentives and sustainability initiatives to support market growth
- 11.3.6 ITALY
- 11.3.6.1 Surge in investments and partnerships to galvanize growth
- 11.3.7 REST OF EUROPE
- 11.4 ASIA PACIFIC
- 11.4.1 ASIA PACIFIC: MODULAR DATA CENTER MARKET DRIVERS
- 11.4.2 ASIA PACIFIC: MACROECONOMIC OUTLOOK
- 11.4.3 CHINA
- 11.4.3.1 Surging AI demand and government investments to ignite market growth
- 11.4.4 JAPAN
- 11.4.4.1 Rising AI demand and major investments to drive market
- 11.4.5 AUSTRALIA & NEW ZEALAND
- 11.4.5.1 Growing data demand and innovation incentives to accelerate expansion and sustainability
- 11.4.6 REST OF ASIA PACIFIC
- 11.5 MIDDLE EAST & AFRICA
- 11.5.1 MIDDLE EAST & AFRICA: MODULAR DATA CENTER MARKET DRIVERS
- 11.5.2 MIDDLE EAST & AFRICA: MACROECONOMIC OUTLOOK
- 11.5.3 GULF COOPERATION COUNCIL (GCC) COUNTRIES
- 11.5.3.1 Kingdom of Saudi Arabia (KSA)
- 11.5.3.1.1 Digital transformation and investment incentives to propel market
- 11.5.3.2 UAE
- 11.5.3.2.1 Substantial investments in advanced technologies to drive market
- 11.5.3.3 Rest of GCC countries
- 11.5.3.1 Kingdom of Saudi Arabia (KSA)
- 11.5.4 SOUTH AFRICA
- 11.5.4.1 Rising cloud demand and energy resilience to strengthen growth and innovation
- 11.5.5 REST OF MIDDLE EAST & AFRICA
- 11.6 LATIN AMERICA
- 11.6.1 LATIN AMERICA: MODULAR DATA CENTER MARKET DRIVERS
- 11.6.2 LATIN AMERICA: MACROECONOMIC OUTLOOK
- 11.6.3 BRAZIL
- 11.6.3.1 Growing industry demand and investments to fuel market growth
- 11.6.4 MEXICO
- 11.6.4.1 Rising cloud demand and investments to catalyze growth and innovation
- 11.6.5 REST OF LATIN AMERICA
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 STRATEGIES ADOPTED BY KEY PLAYERS/RIGHT TO WIN
- 12.3 MARKET SHARE ANALYSIS
- 12.4 VENDOR PRODUCT/BRAND COMPARISON
- 12.4.1 DELL TECHNOLOGIES - EMC MDC
- 12.4.2 SCHNEIDER ELECTRIC - ECOSTRUXURE
- 12.4.3 VERTIV - MEGAMOD
- 12.4.4 HUAWEI - FUSIONMODULE2000
- 12.4.5 EATON - SMARTRACK
- 12.5 REVENUE ANALYSIS
- 12.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.6.1 STARS
- 12.6.2 EMERGING LEADERS
- 12.6.3 PERVASIVE PLAYERS
- 12.6.4 PARTICIPANTS
- 12.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.6.5.1 Company footprint
- 12.6.5.2 Region footprint
- 12.6.5.3 Component footprint
- 12.6.5.4 End-user footprint
- 12.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 12.7.1 PROGRESSIVE COMPANIES
- 12.7.2 RESPONSIVE COMPANIES
- 12.7.3 DYNAMIC COMPANIES
- 12.7.4 STARTING BLOCKS
- 12.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.7.5.1 Detailed list of key startups/SMEs
- 12.7.5.2 Competitive benchmarking of startups/SMEs
- 12.8 COMPANY VALUATION AND FINANCIAL METRICS OF KEY VENDORS
- 12.8.1 COMPANY VALUATION
- 12.8.2 FINANCIAL METRICS
- 12.9 COMPETITIVE SCENARIO
- 12.9.1 PRODUCT LAUNCHES
- 12.9.2 DEALS
13 COMPANY PROFILES
- 13.1 INTRODUCTION
- 13.2 KEY PLAYERS
- 13.2.1 DELL
- 13.2.1.1 Business overview
- 13.2.1.2 Products/Solutions/Services offered
- 13.2.1.3 Recent developments
- 13.2.1.3.1 Product launches
- 13.2.1.3.2 Deals
- 13.2.1.4 MnM view
- 13.2.1.4.1 Key strengths
- 13.2.1.4.2 Strategic choices
- 13.2.1.4.3 Weaknesses and competitive threats
- 13.2.2 VERTIV
- 13.2.2.1 Business overview
- 13.2.2.2 Products/Solutions/Services offered
- 13.2.2.3 Recent developments
- 13.2.2.3.1 Product launches
- 13.2.2.3.2 Deals
- 13.2.2.4 MnM view
- 13.2.2.4.1 Key strengths
- 13.2.2.4.2 Strategic choices
- 13.2.2.4.3 Weaknesses and competitive threats
- 13.2.3 SCHNEIDER ELECTRIC
- 13.2.3.1 Business overview
- 13.2.3.2 Products/Solutions/Services offered
- 13.2.3.3 Recent developments
- 13.2.3.3.1 Product launches
- 13.2.3.3.2 Deals
- 13.2.3.4 MnM view
- 13.2.3.4.1 Key strengths
- 13.2.3.4.2 Strategic choices
- 13.2.3.4.3 Weaknesses and competitive threats
- 13.2.4 HUAWEI
- 13.2.4.1 Business overview
- 13.2.4.2 Products/Solutions/Services offered
- 13.2.4.3 Recent developments
- 13.2.4.3.1 Product launches
- 13.2.4.3.2 Deals
- 13.2.4.4 MnM view
- 13.2.4.4.1 Key strengths
- 13.2.4.4.2 Strategic choices
- 13.2.4.4.3 Weaknesses and competitive threats
- 13.2.5 EATON
- 13.2.5.1 Business overview
- 13.2.5.2 Products/Solutions/Services offered
- 13.2.5.3 Recent developments
- 13.2.5.3.1 Product launches
- 13.2.5.3.2 Deals
- 13.2.5.3.3 Expansions
- 13.2.5.4 MnM view
- 13.2.5.4.1 Key strengths
- 13.2.5.4.2 Strategic choices
- 13.2.5.4.3 Weaknesses and competitive threats
- 13.2.6 RITTAL
- 13.2.6.1 Business overview
- 13.2.6.2 Products/Solutions/Services offered
- 13.2.6.3 Recent developments
- 13.2.6.3.1 Product launches
- 13.2.6.3.2 Deals
- 13.2.7 JOHNSON CONTROLS
- 13.2.7.1 Business overview
- 13.2.7.2 Products/Solutions/Services offered
- 13.2.7.3 Recent developments
- 13.2.7.3.1 Deals
- 13.2.8 ABB
- 13.2.8.1 Business overview
- 13.2.8.2 Products/Solutions/Services offered
- 13.2.8.3 Recent developments
- 13.2.8.3.1 Deals
- 13.2.9 DELTA ELECTRONICS
- 13.2.9.1 Business overview
- 13.2.9.2 Products/Solutions/Services offered
- 13.2.9.3 Recent developments
- 13.2.9.3.1 Deals
- 13.2.10 STULZ
- 13.2.10.1 Business overview
- 13.2.10.2 Products/Solutions/Services offered
- 13.2.10.3 Recent developments
- 13.2.10.3.1 Product launches
- 13.2.10.3.2 Deals
- 13.2.11 HUBBELL (PCX)
- 13.2.11.1 Business overview
- 13.2.11.2 Products/Solutions/Services offered
- 13.2.11.3 Recent developments
- 13.2.11.3.1 Deals
- 13.2.1 DELL
- 13.3 OTHER PLAYERS
- 13.3.1 IE CORP.
- 13.3.2 CANNON TECHNOLOGIES
- 13.3.3 EDGE MCS
- 13.3.4 ASPERITAS
- 13.3.5 RETEX
- 13.3.6 BOX MODUL
- 13.3.7 BLADEROOM
- 13.3.8 WESCO INTERNATIONAL, INC.
- 13.3.9 FIBERHOME
- 13.3.10 SCALEMATRIX
- 13.3.11 EQUINIX
- 13.3.12 365 DATA CENTERS
- 13.3.13 CUPERTINO ELECTRIC (QUANTA SERVICES)
- 13.3.14 K-STAR
- 13.3.15 IEM
- 13.3.16 MODULAR POWER SOLUTIONS
- 13.3.17 FAITH TECHNOLOGIES INCORPORATED (FTI)
- 13.3.18 M.C. DEAN
- 13.3.19 DATA SPECIALTIES INC.
- 13.3.20 TOTAL SITE SOLUTIONS
- 13.3.21 ENVIRONMENTAL AIR SYSTEMS
- 13.3.22 TAS
- 13.3.23 AWS
- 13.3.24 META
- 13.3.25 ORACLE
- 13.3.26 MICROSOFT
- 13.3.27 APPLE
- 13.3.28 INTEL
- 13.3.29 NVIDIA
- 13.3.30 IBM
- 13.3.31 SIEMENS
- 13.3.32 HPE
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH APPROACH
- 14.1.1 SECONDARY DATA
- 14.1.2 PRIMARY DATA
- 14.1.2.1 Breakup of primary profiles
- 14.1.2.2 Key industry insights
- 14.2 DATA TRIANGULATION
- 14.3 MARKET SIZE ESTIMATION
- 14.4 MARKET FORECAST
- 14.5 RESEARCH ASSUMPTIONS
- 14.6 RESEARCH LIMITATIONS
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS


