

|
시장보고서
상품코드
2149763
제지용 화학제품 시장 : 유형별, 형태별, 용도별, 지역별 - 세계 예측(-2031년)Paper Chemicals Market by Type (Process Chemicals, Pulp Chemicals, and Functional Chemicals), Form (Specialty and Commodity), Application (Papermaking, Pulp Manufacturing, and Water & Process Treatment), and by Region - Global Forecast to 2031 |
||||||

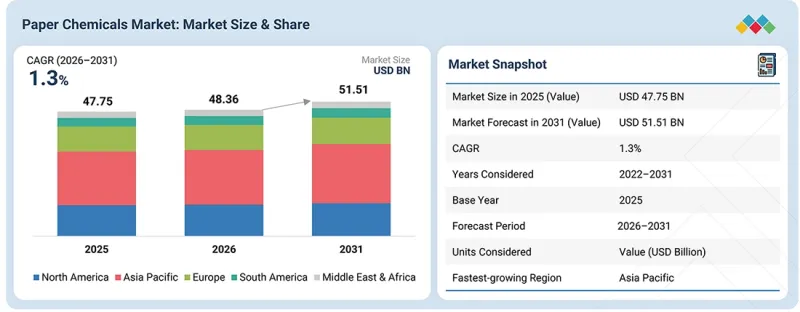
제지용 화학제품 시장은 2026년 483억 6,000만 달러에서 2031년까지 515억 1,000만 달러로 확대될 것으로 예상되며, 예측 기간 동안 연평균 성장률(CAGR)은 1.3%에 달할 것으로 전망됩니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(백만 달러) |
| 부문 | 유형, 형태, 용도 및 지역 |
| 대상 지역 | 북미, 아시아태평양, 유럽, 중동 및 아프리카, 남미 |
제지용 화학제품 시장은 제조업체들의 지속가능하고 재활용 가능한 종이 포장재 채택 확대에 따라 성장이 예상됩니다. 일회용 플라스틱에 대한 규제 강화로 인해 종이 및 판지 포장재의 사용이 촉진되고 있습니다. 이에 따라 종이의 특성을 향상시키기 위한 사이징제, 강도 향상제, 코팅제, 배리어제 및 기능성 화학제품에 대한 수요가 증가하고 있습니다.
“기능성 화학제품 부문은 2026년부터 2031년까지 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다.”
종이의 용도 향상에 대한 수요가 높아짐에 따라, 기능성 화학제품 부문은 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 고성능 포장재 및 특수 용지 시장이 확대됨에 따라 제조업체들은 점점 더 첨단 기능성 처리를 도입하고 있습니다. 또한, 친환경적이고 재활용 가능한 포장으로의 전환 역시 혁신적인 포장용 기능성 화학제품 솔루션에 새로운 기회를 창출하고 있습니다.
“2031년에는 특수 화학제품 부문이 가장 큰 시장 점유율을 차지할 것으로 예측됩니다.”
특수 부문은 펄프 생산, 제지 및 공정 처리 분야에서 폭넓게 사용되고 있기 때문에 2031년에는 최대 시장 점유율을 차지할 것으로 예상됩니다. 특수 화학제품은 강도, 리텐션, 배수성, 코팅, 사이징 및 불순물 제어 등 특정 성능 향상을 가져옵니다. 이러한 성능 향상은 고품질 포장지, 티슈, 위생용지 및 특수 용지 제품에 대한 수요 증가를 뒷받침하기 위해 활용되고 있습니다. 또한, 생산 효율 향상, 자원 보존, 지속가능한 제지 방식에 대한 요구 역시 특수 화학제품 수요를 촉진하고 있습니다.
“제지 부문은 2026년부터 2031년까지 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다.”
세계 제지 생산량 증가에 따라, 제지 부문은 2026년부터 2031년까지 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다. 포장지, 티슈, 위생용지, 인쇄용지, 특수지 시장이 확대되고 있으며, 이는 제지 공정에서 화학제품 사용 증가에 기여하고 있습니다. 제조 공정에서는 강도, 사이징, 리텐션, 드레나지, 코팅, 인쇄 적합성 및 표면 특성을 향상시키기 위해 화학제품 사용이 점점 더 증가하고 있습니다. 재생 섬유의 사용 증가와 물·에너지·생산 효율 향상에 대한 요구로 인해 화학제품 시장은 계속해서 견조한 추세를 보일 것으로 전망됩니다.
“아시아태평양의 제지용 화학제품 시장은 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다.”
아시아태평양의 제지용 화학제품 시장은 해당 지역의 펄프·제지 산업의 급속한 성장에 힘입어 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다. 아시아의 신흥 경제국인 중국, 인도, 일본, 인도네시아 등에서는 포장지, 티슈, 위생용지, 특수지 시장이 성장하고 있습니다. 또한, 급속한 산업화, 도시화, E-Commerce의 확대, 그리고 펄프·제지 생산에 대한 투자 증가로 인해 펄프·제지용 화학제품에 대한 새로운 수요도 창출되고 있습니다.
기업 유형별 : Tier 1 - 56%, Tier 2 - 30%, Tier 3 - 14%
직책별 : C레벨 - 43%, 이사급 - 34%, 기타 - 23%
지역별 : 북미 - 20%, 유럽 - 10%, 아시아태평양 - 40%, 남미 - 10%, 중동 및 아프리카 - 20%
대상 기업 : 본 보고서에서는 Solenis(미국), Kemira(핀란드), Ecolab Inc.(미국), Buckman(미국), Nouryon(네덜란드)을 비롯한 기업들이 다루어지고 있습니다.
본 조사에서는 제지용 화학제품 시장의 이러한 주요 기업들에 대해 기업 개요, 최근 동향 및 주요 시장 전략을 포함한 상세한 경쟁 분석을 수행하고 있습니다.
조사 범위
본 조사 보고서에서는 제지용 화학제품 시장을 종류(공정용 화학제품, 펄프용 화학제품, 기능성 화학제품), 형태(특수 제품 및 범용 제품), 용도(펄프 제조, 제지, 수처리 및 공정 처리), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)에 따라 분류하고 있습니다. 본 보고서의 범위에는 제지용 화학제품 시장의 성장에 영향을 미치는 촉진요인, 제약요인, 과제 및 기회에 관한 상세한 정보가 포함되어 있습니다. 주요 업계 플레이어에 대한 상세한 분석을 통해 사업 개요, 제공 제품, 그리고 제지용 화학제품 시장과 관련된 제휴, 인수, 사업 확장 등의 주요 전략에 대한 인사이트를 제공합니다. 또한, 본 보고서에서는 제지용 화학제품 시장의 생태계에서 두각을 나타내고 있는 스타트업 기업에 대한 경쟁 분석도 다루고 있습니다.
본 보고서를 구매해야 하는 이유
본 보고서는 시장 선도 기업 및 신규 진입 기업에게 제지용 화학제품 시장 전체 및 각 하위 부문의 매출에 대한 가장 정확한 추정치를 제공합니다. 본 보고서는 이해관계자가 경쟁 구도를 이해하고, 자사의 비즈니스를 보다 적절하게 포지셔닝하기 위한 인사이트를 심화하며, 적절한 시장 진입 전략을 수립하는 데 도움이 됩니다. 또한, 본 보고서는 이해관계자가 시장을 이해하는 데 도움을 주며, 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
주요 촉진요인(티슈 및 위생 용지의 용도 확대), 억제요인(원자재 가격 변동), 기회(신흥 시장의 성장), 과제(공급망 혼란 및 지정학적 리스크)에 대한 분석
- 제품 개발/혁신 : 제지용 화학제품 시장의 향후 기술, 연구개발 활동, 제품 및 서비스 출시에 대한 상세한 인사이트
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보--본 보고서는 다양한 지역에 걸친 제지용 화학제품 시장을 분석하고 있습니다
시장 다각화 : 제지용 화학제품 시장의 신제품·서비스, 미개척 지역, 최근 동향 및 투자에 관한 종합적인 정보
- 경쟁 분석 : 주요 기업의 시장 점유율, 성장 전략 및 서비스 제공 내용에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 제지용 화학제품 시장에서 사업자에게 매력적인 비즈니스 기회
- 형태별·지역별 : 제지용 화학제품 시장
- 유형별 : 제지용 화학제품 시장 점유율
- 용도별 : 제지용 화학제품 시장
- 국가별 : 제지용 화학제품 시장
제4장 시장 개요
- 시장 역학
- 성장 촉진요인
- 성장 억제요인
- 기회
- 과제
- 미충족 수요와 미개척 분야
- 제지용 화학제품 시장의 미충족 수요
- 미개척 시장의 기회
- 상호 연관된 시장과 부문 간 기회
- 상호 연관된 시장
- 부문 간 기회
- Tier 1/2/3 주요 기업들의 전략적 움직임
- Tier 1 기업 : 확장과 제지·화학 분야의 혁신을 주도하는 세계 리더
제5장 업계 동향
- Porter's Five Forces 분석
- 신규 진입자의 위협
- 대체품의 위협
- 공급업체의 협상력
- 구매자의 협상력
- 경쟁 기업 간의 적대 관계의 격렬함
- 거시경제 전망
- GDP 동향 및 전망
- 가치사슬 분석
- 생태계 분석
- 가격 책정 분석
- 지역별 가격 책정 분석
- 무역 분석
- 수출 시나리오(HS 코드 482370)
- 수입 시나리오(HS 코드 380992)
- 2026-2027년 주요 회의 및 행사
- 고객의 비즈니스에 영향을 미치는 동향 및 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- 솔레니스 : 사이징제 최적화를 통한 고급 종이 공장 생산성 향상
- 미국 관세의 영향 - 제지용 화학제품 시장
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가·지역별 영향
- 용도에 미치는 영향
제6장 기술 발전, AI의 영향, 특허, 혁신 및 향후 용도
- 주요 신흥 기술
- 효소를 이용한 제지 및 섬유 개질
- 재활용성을 높이는 화학 기술
- 녹색 화학
- 보완 기술
- 실시간 센서 및 온라인 공정 모니터링
- 화학제품의 자동 주입 및 폐쇄 루프 제어
- 고급 수처리 및 공정 처리
- 관련 기술
- 나노셀룰로오스 및 첨단 셀룰로오스 기반 소재
- 디지털 인쇄 및 기능성 종이 기술
- 기술·제품 로드맵
- 단기(2025-2027년) | 기반 구축 및 초기 상용화
- 중기(2027-2030년) | 확대·통합
- 장기(2030-2035년 이후) | 성숙, 순환형 사회 및 첨단 종이 화학 기술
- 특허 분석
- 조사 방법
- 특허 분석, 2016-2025년
- 미래 응용
- 첨단·고성능 용도에서의 제지용 화학제품 통합
- AI/생성형 AI가 제지용 화학제품 시장에 미치는 영향
- 주요 사용 사례 및 시장 잠재력
- 제지용 화학제품의 모범 사례
- 상호 연계된 생태계와 시장 관계자에 미치는 영향
- 제지용 화학제품 시장에서 생성형 AI 도입에 대한 고객의 준비 현황
- 솔레니스의 드라이 스트렝스 첨가제가 티슈의 강도와 기계의 생산성을 향상시킵니다
제7장 규제 현황 및 지속가능성 노력
- 지역별 규제 및 규정 준수
- 규제 기관, 정부 기관 및 기타 조직
- 업계 기준
- 지속가능성을 위한 노력
- 제지용 화학제품의 탄소 영향 및 친환경 용도
- 지속가능성에 미치는 영향 및 규제 정책 노력
- 인증, 표시 및 환경 기준
제8장 고객 동향 및 구매 행동
- 의사결정 과정
- 구매 과정에 관여하는 주요 이해관계자와 그 평가 기준
- 구매 과정의 주요 이해관계자
- 구매 기준
- 도입 장벽과 사내 과제
- 각종 용도에서의 미충족 수요
- 시장의 수익성
- 수익 창출 가능성
- 비용 동향
- 용도별 이익률 기회
제9장 제지용 화학제품 시장 : 유형별
- 펄프용 화학제품
- 가공용 화학제품
- 기능성 화학제품
제10장 제지용 화학제품 시장 : 형태별
- 특수 제품
- 범용 제품
제11장 제지용 화학제품 시장 : 용도별
- 제지
- 펄프 제조
- 수처리·공정 처리
제12장 제지용 화학제품 시장 : 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- 기타 아시아태평양
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 스웨덴
- 핀란드
- 러시아
- 프랑스
- 독일
- 기타 유럽
- 중동 및 아프리카
- GCC 국가들
- 남아프리카
- 기타 중동 및 아프리카
- 남미
- 브라질
- 아르헨티나
- 기타 남미
제13장 경쟁 현황
- 개요
- 주요 진입 기업의 전략/강점, 2021년 1월-2026년 8월
- 수익 분석, 2021-2025년
- 시장 순위(2025년)
- 기업 가치 평가 및 재무 지표
- 브랜드 및 제품 비교
- 기업 평가 매트릭스 : 주요 기업, 2025년
- 스타 기업
- 신흥 리더
- 광범위한 입지를 가진 기업
- 진출 기업
- 기업의 사업 전개 : 주요 기업, 2025년
- 기업 평가 매트릭스 : 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹 : 스타트업/중소기업, 2025년
- 주요 스타트업/중소기업의 경쟁사 벤치마킹
- 경쟁 시나리오
- 제품 출시
- 거래
- 사업 확장
- 기타 동향
제14장 기업 개요
- 주요 기업
- SOLENIS
- KEMIRA
- ECOLAB INC.
- BUCKMAN
- NOURYON
- HARIMA CHEMICALS GROUP, INC.
- SNF
- KURITA WATER INDUSTRIES LTD.
- ARCHROMA
- IVAX PAPER CHEMICALS LIMITED
- 기타 주요 기업
- PROTEX INTERNATIONAL
- WOLLNER GMBH
- ARAKAWA CHEMICAL INDUSTRIES, LTD.
- MARE S.P.A
- INDULOR CHEMIE GMBH
- SHANDONG BLUESUN CHEMICALS CO., LTD.
- ERCO WORLDWIDE
- SOLVAY
- EVONIK
- AAHAN CHEMIEX LLP
- NNOWETA PERFORMANCE CHEMICALS PVT LTD
- ACURO ORGANICS LIMITED
- FPCL
- PAPERTEX SPECIALITY CHEMICALS PVT. LTD.
- SHREE CHLORATES
제15장 조사 방법론
제16장 부록
KSM 26.10.28The paper chemicals market is projected to grow from USD 48.36 billion in 2026 to USD 51.51 billion by 2031, at a CAGR of 1.3% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million) |
| Segments | Type, Form, Application, and Region |
| Regions covered | North America, Asia Pacific, Europe, the Middle East & Africa, and South America |
The paper chemicals market will expand with the rise in the adoption of sustainable and recyclable paper-based packaging by manufacturers. The increased regulations on single-use plastics are driving the use of paper and paperboard packaging. This is driving a growing demand for sizing, strength, coating, barrier, and functional chemicals to enhance paper properties.
"The functional chemicals segment is projected to exhibit the highest CAGR from 2026 to 2031."
The functional chemicals segment is projected to exhibit the highest CAGR during the forecast period as the demand for improved paper applications is growing. Manufacturers are increasingly using advanced functional treatments due to the growing market for high-performance packaging and specialty papers. The shift towards environmentally friendly and recyclable packaging is also generating new opportunities for innovative package-oriented functional chemical solutions.
"The specialty segment is projected to capture the largest market share in 2031."
The specialty segment is expected to get the highest market share in 2031 because of its wide usage in pulp production, papermaking, and process treatment. Specialty chemicals offer specific performance enhancements, including strength, retention, drainage, coating, sizing, and control of contaminants. They are being adopted in support of rising demand for high-quality packaging, tissue, hygiene, and specialty paper products. The need for increased production efficiency, conservation of resources, and sustainable papermaking practices is also driving specialty chemicals.
"The papermaking segment is projected to exhibit the highest CAGR from 2026 to 2031."
The papermaking segment is projected to exhibit the highest CAGR from 2026 to 2031, due to the rising global production of paper. The market for packaging, tissue, hygiene, printing, and specialty papers is expanding, which contributes to a rise in the usage of chemicals in the papermaking process. Chemicals are increasingly being used in manufacturing to enhance strength, sizing, retention, drainage, coating, printability, and surface properties. Due to the increasing use of recycled fiber and the desire to enhance water, energy, and production efficiency, the chemical market should continue to be well supported.
"The paper chemicals market in Asia Pacific is projected to grow at the highest CAGR during the forecast period."
The paper chemicals market in Asia Pacific is expected to have the highest CAGR growth over the forecast period, owing to the rapid growth of the region's pulp & paper industry. Emerging Asian economies, China, India, Japan, Indonesia, and others are seeing growth in the packaging, tissue, hygiene, and specialty paper market. New demands for pulp and paper chemicals are also being generated by the rapid industrialization, urbanization, e-commerce growth, and rising investments in pulp and paper production.
By Company Type: Tier 1 - 56%, Tier 2 - 30%, and Tier 3- 14%
By Designation: C-level - 43%, Director Level - 34%, and Others - 23%
By Region: North America - 20%, Europe - 10%, Asia Pacific - 40%, South America - 10%, and Middle East & Africa - 20%
Companies Covered: Solenis (US), Kemira (Finland), Ecolab Inc. (US), Buckman (US), Nouryon (Netherlands), among other companies, are covered in the report.
The study includes an in-depth competitive analysis of these key players in the paper chemicals market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the paper chemicals market based on type (process chemicals, pulp chemicals, and functional chemicals), form (specialty and commodity), application (pulp manufacturing, paper making, and water & process treatment), and region (Asia Pacific, North America, Europe, South America, and the Middle East & Africa). The report's scope covers detailed information regarding the drivers, restraints, challenges, and opportunities influencing the growth of the paper chemicals market. A detailed analysis of the key industry players has been done to provide insights into their business overview, products offered, and key strategies, such as partnerships, acquisitions, and expansions, associated with the paper chemicals market. This report covers a competitive analysis of upcoming startups in the paper chemicals market ecosystem.
Reasons to Buy the Report
The report will offer market leaders/new entrants information on the closest approximations of the revenue numbers for the overall paper chemicals market and the subsegments. This report will help stakeholders understand the competitive landscape, gain more insights into positioning their businesses better, and plan suitable go-to-market strategies. The report will help stakeholders understand the market and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
Analysis of key drivers (Expansion of tissue and hygiene paper applications), restraints (Volatility in raw-material prices), opportunities (Growth in emerging markets), and challenges (Supply-chain disruptions and geopolitical risks)
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the paper chemicals market
- Market Development: Comprehensive information about profitable markets-the report analyzes the paper chemicals market across varied regions
Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the paper chemicals market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players, such as Solenis (US), Kemira (Finland), Ecolab Inc. (US), Buckman (US), Nouryon (Netherlands), and others.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET SCOPE
- 1.2.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.2.2 INCLUSIONS AND EXCLUSIONS
- 1.2.3 YEARS CONSIDERED
- 1.2.4 CURRENCY CONSIDERED
- 1.2.5 UNIT CONSIDERED
- 1.2.6 STAKEHOLDERS
- 1.3 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN PAPER CHEMICALS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN PAPER CHEMICALS MARKET
- 3.2 PAPER CHEMICALS MARKET, BY FORM AND REGION
- 3.3 PAPER CHEMICALS MARKET SHARE, BY TYPE
- 3.4 PAPER CHEMICALS MARKET, BY APPLICATION
- 3.5 PAPER CHEMICALS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Expansion of paper, pulp, and paperboard production
- 4.2.1.2 Expansion of tissue and hygiene paper applications
- 4.2.1.3 Global push against plastic pollution and regulatory requirements
- 4.2.1.4 Increasing use and high utilization of recycled paper
- 4.2.2 RESTRAINTS
- 4.2.2.1 Volatility in raw-material prices
- 4.2.2.2 Environmental and regulatory restrictions
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Development of sustainable paper chemicals
- 4.2.3.2 Growth in emerging economies
- 4.2.3.3 Expansion of e-commerce and food-service activities
- 4.2.4 CHALLENGES
- 4.2.4.1 Supply-chain disruptions and geopolitical risks
- 4.2.4.2 Strong competition among global and regional companies
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN PAPER CHEMICALS MARKET
- 4.3.1.1 Growing need for high-performance paper chemicals
- 4.3.1.2 Need for cost-effective and sustainable paper chemical solutions
- 4.3.1.3 Increasing need for specialized and application-specific paper chemicals
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.3.2.1 Expansion into high-growth emerging economies
- 4.3.2.2 Growth opportunities in sustainable and recycled-fiber paper production
- 4.3.2.3 Increasing demand for functional and barrier chemicals for paper packaging
- 4.3.1 UNMET NEEDS IN PAPER CHEMICALS MARKET
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 TIER 1 PLAYERS: GLOBAL LEADERS DRIVING EXPANSION AND PAPER CHEMICAL INNOVATION
- 4.5.1.1 BUCKMAN acquired by Pritzker private capital to support global expansion and product innovation
- 4.5.1.2 NOURYON enters long-term supply agreement with Arauco for sodium chlorate and chlorine dioxide
- 4.5.1.3 SOLENIS announces new production facility in China to expand paper chemicals capacity
- 4.5.1 TIER 1 PLAYERS: GLOBAL LEADERS DRIVING EXPANSION AND PAPER CHEMICAL INNOVATION
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECASTS
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 PRICING ANALYSIS BASED ON REGION
- 5.6 TRADE ANALYSIS
- 5.6.1 EXPORT SCENARIO (HS CODE 482370)
- 5.6.2 IMPORT SCENARIO (HS CODE 380992)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 SOLENIS: IMPROVING FINE PAPER MILL PERFORMANCE THROUGH SIZING AGENT OPTIMIZATION
- 5.11 IMPACT OF US TARIFFS - PAPER CHEMICALS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRY/REGION
- 5.11.4.1 US
- 5.11.4.2 Asia Pacific
- 5.11.4.3 Europe
- 5.11.5 IMPACT ON APPLICATIONS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 ENZYMATIC PAPERMAKING AND FIBER MODIFICATION
- 6.1.2 RECYCLABILITY-ENHANCING CHEMISTRY
- 6.1.3 GREEN CHEMISTRY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 REAL-TIME SENSORS AND ONLINE PROCESS MONITORING
- 6.2.2 AUTOMATED CHEMICAL DOSING AND CLOSED-LOOP CONTROL
- 6.2.3 ADVANCED WATER AND PROCESS TREATMENT
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 NANOCELLULOSE AND ADVANCED CELLULOSE-BASED MATERIALS
- 6.3.2 DIGITAL PRINTING AND FUNCTIONAL PAPER TECHNOLOGY
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID-TERM (2027-2030) | EXPANSION & INTEGRATION
- 6.4.3 LONG-TERM (2030-2035+) | MATURITY, CIRCULARITY & ADVANCED PAPER CHEMISTRY
- 6.5 PATENT ANALYSIS
- 6.5.1 INTRODUCTION
- 6.5.2 METHODOLOGY
- 6.5.3 PATENT ANALYSIS, 2016-2025
- 6.6 FUTURE APPLICATIONS
- 6.6.1 INTEGRATION OF PAPER CHEMICALS IN ADVANCED AND HIGH-PERFORMANCE APPLICATIONS
- 6.7 IMPACT OF AI/GEN AI ON PAPER CHEMICALS MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES IN PAPER CHEMICALS
- 6.7.3 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN PAPER CHEMICALS MARKET
- 6.7.5 SOLENIS DRY-STRENGTH ADDITIVE IMPROVES TISSUE STRENGTH AND MACHINE PRODUCTIVITY
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT AND ECO-APPLICATIONS OF PAPER CHEMICALS
- 7.2.1.1 Carbon impact reduction
- 7.2.1.2 Eco-applications
- 7.2.1 CARBON IMPACT AND ECO-APPLICATIONS OF PAPER CHEMICALS
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS APPLICATIONS
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.6 MARGIN OPPORTUNITIES, BY APPLICATION
9 PAPER CHEMICALS MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 PULP CHEMICALS
- 9.2.1 GROWING PAPER RECYCLING AND RECOVERED-FIBER PROCESSING TO DRIVE MARKET
- 9.3 PROCESS CHEMICALS
- 9.3.1 GROWING FOCUS ON PAPER MACHINE EFFICIENCY AND PROCESS-WATER MANAGEMENT TO PROPEL MARKET
- 9.4 FUNCTIONAL CHEMICALS
- 9.4.1 GROWING DEMAND FOR HIGH-PERFORMANCE PAPER TO FUEL GROWTH
10 PAPER CHEMICALS MARKET, BY FORM
- 10.1 INTRODUCTION
- 10.2 SPECIALTY
- 10.2.1 GROWING USE OF RECOVERED PAPER TO DRIVE MARKET
- 10.3 COMMODITY
- 10.3.1 HIGH-VOLUME PULP AND PAPERMAKING TO PROPEL MARKET
11 PAPER CHEMICALS MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 PAPERMAKING
- 11.2.1 GROWING GLOBAL PAPER PRODUCTION TO DRIVE MARKET
- 11.3 PULP PRODUCTION
- 11.3.1 GROWING PULP PRODUCTION TO PROPEL MARKET
- 11.4 WATER & PROCESS TREATMENT
- 11.4.1 INCREASING WATER SCARCITY AND STRINGENT ENVIRONMENTAL REGULATIONS TO PROPEL MARKET
12 PAPER CHEMICALS MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 ASIA PACIFIC
- 12.2.1 CHINA
- 12.2.1.1 Growing packaging industry to fuel demand
- 12.2.2 INDIA
- 12.2.2.1 Rapid consumption growth and packaging expansion are accelerating demand for paper-chemical solutions
- 12.2.3 JAPAN
- 12.2.3.1 Packaging premiumization and sustainability are driving demand for higher-performance paper chemicals
- 12.2.4 SOUTH KOREA
- 12.2.4.1 Convenience-led consumption and e-commerce accelerating demand for functional paper chemicals
- 12.2.5 REST OF ASIA PACIFIC
- 12.2.1 CHINA
- 12.3 NORTH AMERICA
- 12.3.1 US
- 12.3.1.1 Expansion of tissue and hygiene paper production to propel market
- 12.3.2 CANADA
- 12.3.2.1 Growing demand for sustainable paper-based packaging to drive market
- 12.3.3 MEXICO
- 12.3.3.1 Increasing domestic paper production to support market growth
- 12.3.1 US
- 12.4 EUROPE
- 12.4.1 SWEDEN
- 12.4.1.1 Expansion of tissue and hygiene paper production to propel market
- 12.4.2 FINLAND
- 12.4.2.1 Expansion of sustainable packaging to drive market
- 12.4.3 RUSSIA
- 12.4.3.1 Expansion of packaging and e-commerce applications to support market growth
- 12.4.4 FRANCE
- 12.4.4.1 Increasing adoption of sustainable and recyclable paper-based packaging to support market growth
- 12.4.5 GERMANY
- 12.4.5.1 Expansion of foodservice and paper-based food packaging to support market growth
- 12.4.6 REST OF EUROPE
- 12.4.1 SWEDEN
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.5.1.1 Saudi Arabia
- 12.5.1.1.1 Paper, tissue and packaging investments expand demand for high-performance chemical solutions
- 12.5.1.2 UAE
- 12.5.1.2.1 Regional trade, packaging expansion and circularity accelerate demand for high-performance paper chemicals
- 12.5.1.3 Rest of GCC countries
- 12.5.1.1 Saudi Arabia
- 12.5.2 SOUTH AFRICA
- 12.5.2.1 Packaging investments initiative strengthen demand for high-performance paper chemicals
- 12.5.3 REST OF MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 Accelerating paper chemicals demand through pulp & paper investments and sustainable packaging initiatives
- 12.6.2 ARGENTINA
- 12.6.2.1 Government investment plans to boost market
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.1.1 KEY PLAYERS' STRATEGIES/RIGHT TO WIN, JANUARY 2021-AUGUST 2026
- 13.2 REVENUE ANALYSIS, 2021-2025
- 13.3 MARKET RANKING, 2025
- 13.4 COMPANY VALUATION AND FINANCIAL METRICS
- 13.5 BRAND/PRODUCT COMPARISON
- 13.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.6.1 STARS
- 13.6.2 EMERGING LEADERS
- 13.6.3 PERVASIVE PLAYERS
- 13.6.4 PARTICIPANTS
- 13.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.6.5.1 Company footprint
- 13.6.5.2 Region footprint
- 13.6.5.3 Form footprint
- 13.6.5.4 Type footprint
- 13.6.5.5 Application footprint
- 13.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.7.1 PROGRESSIVE COMPANIES
- 13.7.2 RESPONSIVE COMPANIES
- 13.7.3 DYNAMIC COMPANIES
- 13.7.4 STARTING BLOCKS
- 13.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 13.7.5.1 Detailed list of key startups/SMEs
- 13.7.6 COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- 13.8 COMPETITIVE SCENARIO
- 13.8.1 PRODUCT LAUNCHES
- 13.8.2 DEALS
- 13.8.3 EXPANSIONS
- 13.8.4 OTHER DEVELOPMENTS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 SOLENIS
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Deals
- 14.1.1.3.2 Expansions
- 14.1.1.3.3 Other developments
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 KEMIRA
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Deals
- 14.1.2.3.2 Expansions
- 14.1.2.4 MnM view
- 14.1.2.4.1 Key strengths
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 ECOLAB INC.
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 MnM view
- 14.1.3.3.1 Key strengths
- 14.1.3.3.2 Strategic choices
- 14.1.3.3.3 Weaknesses and competitive threats
- 14.1.4 BUCKMAN
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Deals
- 14.1.4.3.2 Other developments
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 NOURYON
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Deals
- 14.1.5.3.2 Expansions
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 HARIMA CHEMICALS GROUP, INC.
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Product launches
- 14.1.6.3.2 Deals
- 14.1.6.3.3 Other developments
- 14.1.6.4 MnM view
- 14.1.6.4.1 Key strengths
- 14.1.7 SNF
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.7.3 MnM view
- 14.1.8 KURITA WATER INDUSTRIES LTD.
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.8.3 MnM view
- 14.1.8.3.1 Key strengths
- 14.1.9 ARCHROMA
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.9.3 MnM view
- 14.1.10 IVAX PAPER CHEMICALS LIMITED
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.10.3 MnM view
- 14.1.1 SOLENIS
- 14.2 OTHER PLAYERS
- 14.2.1 PROTEX INTERNATIONAL
- 14.2.2 WOLLNER GMBH
- 14.2.3 ARAKAWA CHEMICAL INDUSTRIES, LTD.
- 14.2.4 MARE S.P.A
- 14.2.5 INDULOR CHEMIE GMBH
- 14.2.6 SHANDONG BLUESUN CHEMICALS CO., LTD.
- 14.2.7 ERCO WORLDWIDE
- 14.2.8 SOLVAY
- 14.2.9 EVONIK
- 14.2.10 AAHAN CHEMIEX LLP
- 14.2.11 NNOWETA PERFORMANCE CHEMICALS PVT LTD
- 14.2.12 ACURO ORGANICS LIMITED
- 14.2.13 FPCL
- 14.2.14 PAPERTEX SPECIALITY CHEMICALS PVT. LTD.
- 14.2.15 SHREE CHLORATES
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Key industry insights
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.3 BASE NUMBER CALCULATION
- 15.3.1 SUPPLY-SIDE APPROACH
- 15.3.2 DEMAND-SIDE APPROACH
- 15.4 MARKET FORECAST APPROACH
- 15.4.1 SUPPLY SIDE
- 15.4.2 DEMAND SIDE
- 15.5 DATA TRIANGULATION
- 15.6 FACTOR ANALYSIS
- 15.7 RESEARCH ASSUMPTIONS
- 15.8 RESEARCH LIMITATIONS AND RISK ASSESSMENT
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


