

|
시장보고서
상품코드
2158065
측방유동 어세이 시장 예측(-2031년) : 제품별, 용도별, 검체별, 방법별, 최종사용자별, 지역별Lateral Flow Assays Market by Product, Application, Sample, Technique, End User, Region - Global Forecast to 2031 |
||||||

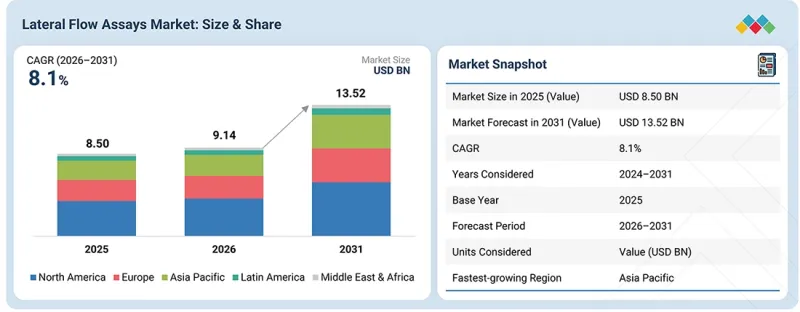
측류 분석 시장은 2026년 91억 4,000만 달러에서 2031년까지 135억 2,000만 달러로 성장할 것으로 예상되며, 연평균 성장률(CAGR)은 8.1%에 달할 것으로 전망됩니다.
| 조사 범위 | |
|---|---|
| 조사 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 제품, 용도, 방법, 검체 유형 및 최종사용자 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 및 GCC 국가 |
전 세계적 감염병 확산과 이에 따른 검사 수요 증가, 고령 인구의 급속한 증가, 가정용 래터럴 플로우 분석기 사용 확대, 그리고 POC(현장 진단) 검사 수요 증가가 시장 성장을 촉진하는 주요 요인으로 작용하고 있습니다. 그러나 다른 검사법과 비교했을 때 정확도의 편차가 존재하고, 의사와 환자가 기존 진단법에서 전환하는 데 소극적인 태도를 보이고 있는 점이 래터럴 플로우 분석 시장의 성장을 저해하고 있습니다.
"용도별로는 임상 검사 부문이 예측 기간 중 가장 큰 점유율을 차지할 것으로 예상됩니다."
임상 검사 부문은 래터럴 플로우 분석 시장에서 가장 큰 용도 부문입니다. 용도별로 보면 래터럴 플로우 분석 시장은 임상 검사, 수의학 진단, 식품 안전 및 환경 검사, 의약품 개발 및 품질 검사로 분류됩니다. 2025년, 임상 검사 부문은 래터럴 플로우 분석 시장에서 가장 큰 점유율을 차지했습니다. 이 부문의 높은 점유율은 전 세계 만성질환 및 감염병 유병률의 증가, 고령 인구 증가, 신속 검사 옵션에 대한 환자의 인식 제고, 의료비 절감에 대한 압박 증가, 그리고 환자 중심 치료에 대한 수요 증가에 기인합니다.
"병원·진료소 부문은 래터럴 플로우 분석 시장에서 가장 큰 시장 점유율을 차지하고 있습니다."
최종사용자별로 보면 LFA 시장은 병원·진료소, 진단 검사 기관, 재택 의료, 제약·생명공학 기업, 기타로 세분화됩니다. 2025년에는 병원·진료소가 가장 큰 시장 점유율을 차지했습니다. 기술 발전, 현장 진단(Point-of-Care) 검사의 보급 확대, 신속하고 조기 진단을 원하는 경향의 증가가 병원·진료소 부문의 성장을 촉진하고 있습니다.
"예측 기간 중 북미가 가장 큰 점유율을 차지할 것으로 예상됩니다."
전 세계 래터럴 플로우 분석(LFA) 시장은 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카, GCC 국가 등 6개 주요 지역으로 분류됩니다. 북미는 첨단인 의료 인프라, 막대한 의료비 지출, 주요 제조사의 강력한 입지에 힘입어 이 시장을 주도하고 있습니다. 고령화 진행, 감염병 및 만성질환 유병률 상승, 가정용 및 자가 검사 키트에 대한 강한 수요가 북미 시장의 성장을 더욱 지원하고 있습니다. 이 지역 부문은 예측 기간 중 지배적인 위치를 유지할 것으로 예상됩니다.
이 보고서에서 언급된 주요 기업의 내역은 다음과 같습니다. :
- 기업 유형별: Tier 1: 40%, Tier 2: 30%, Tier 3: 30%
- 직책별: C레벨: 27%, 이사급: 18%, 기타: 55%
- 지역별: 북미: 51%, 유럽: 21%, 아시아태평양: 18%, 라틴아메리카: 6%, 중동 및 아프리카: 4%
조사 범위
이 보고서에서는 제품(키트·시약 및 리더기), 용도(임상 검사, 수의학 진단, 식품 안전·환경 검사, 의약품 개발·품질 검사), 기법(샌드위치법, 경쟁법, 다중 검출법), 검체 유형(혈액 검체, 소변 검체, 타액 검체, 기타 검체), 최종사용자(병원·진료소, 진단 검사 기관, 재택 의료 현장, 제약·바이오기술 기업, 기타 최종사용자) 및 지역(북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카, GCC 국가)를 기준으로 래터럴 플로우 분석 시장을 분석하고 있습니다. 또한 이 보고서에서는 시장 성장에 영향을 미치는 요인(촉진요인, 제약 요인, 성장 기회, 과제 등)을 조사하고, 시장을 선도하는 기업의 경쟁 상황에 대한 상세한 정보를 제공하고 있습니다. 아울러 개별 성장 동향을 바탕으로 마이크로 마켓을 분석하고 있습니다. 6개 주요 지역(및 해당 지역내 각 국가)의 시장 부문별 매출 전망도 수록되어 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서는 기존 기업뿐만 아니라 신규 진입 기업 및 중소규모 기업에게도 시장 동향을 파악하는 데 도움이 되며, 궁극적으로 시장 점유율 확대로 이어집니다. 이 보고서를 구매한 기업은 다음 전략 중 하나 또는 이를 조합하여 활용함으로써 시장에서 입지를 강화할 수 있습니다.
이 리포트에서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인(감염병의 높은 유병률, 고령 인구 증가, 가정용 래터럴 플로우 분석기 사용 확대, POC 검사 수요 확대) 및 제약 요인(측류 분석 검사 결과의 편차)에 대한 분석, 기회(측류 분석의 용도 확대 및 식품 및 음료 업계에서의 수요 증가), 그리고 과제(측류 분석 제품에 대한 보험 급여 제한 및 검사 개발에 필요한 고품질 원자재 조달의 어려움)
- 시장 침투: 래터럴 플로우 분석 시장의 주요 기업이 제공하는 제품 포트폴리오에 대한 포괄적인 정보
- 제품 개발 및 혁신: 래터럴 플로우 분석 시장의 향후 동향, 연구개발 활동 및 신제품 출시에 대한 상세한 분석
- 시장 개발: 수익성이 높은 신흥 지역에 대한 포괄적인 정보
- 시장 다각화: 래터럴 플로우 분석 시장에서 신제품, 급성장 지역 및 최근 동향에 대한 포괄적인 정보
- 경쟁 평가: 시장 세분화, 성장 전략, 수익 분석 및 주요 시장 참여자의 제품에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 측류 분석(Lateral Flow Assay) 시장 개요
- 측류 분석(Lateral Flow Assay) 시장: 제품별, 2026년 대비 2031년
- 측류 분석(Lateral Flow Assay) 시장: 용도별, 2026년 대 2031년
- 측류 분석 키트 및 시약 시장: 분석 기법별, 2026년 대 2031년
- 측류 분석(Lateral Flow Assay) 시장: 검체 유형별, 2026년 대 2031년
- 측류 분석(Lateral Flow Assay) 시장: 최종사용자별, 2026년 대 2031년
- 측류 분석(Lateral Flow Assay) 시장: 지역별 성장 기회
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- 미충족 수요 및 미개발 분야
- 라테럴 플로우 분석 시장에서의 미충족 수요
- 미개발 시장의 기회
- 상호 연관된 시장 및 부문 간 기회
- 상호 연관된 시장
- 부문 간 기회
- Tier 1/2/3 주요 기업의 전략적 움직임
- 주요 동향 및 전략적 초점
제5장 업계 동향
- Porter's Five Forces 분석
- 공급업체의 협상력
- 구매자의 협상력
- 신규 진입자의 위협
- 대체품의 위협
- 경쟁 기업간 경쟁 관계의 격렬함
- 거시경제 지표
- GDP 동향 및 전망
- 공급망 분석
- 밸류체인 분석
- 생태계 분석
- 가격 분석
- 지역별 평균 판매 가격(2024-2026년)
- 주요 기업별 평균 판매 가격(2024-2026년)
- 무역 분석
- 수입 시나리오(HS 코드 382200)
- 수출 시나리오(HS 코드 382200)
- 주요 회의 및 행사(2026-2027년)
- 고객의 사업에 영향을 미치는 동향 및 변화
- 투자 및 자금 조달 시나리오
- 2025년 미국 관세가 라테럴 플로우 분석 시장에 미치는 영향
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가·지역별 영향
- 최종 용도 산업에 미치는 영향
제6장 기술 발전, AI의 영향, 특허, 혁신 및 향후 활용
- 주요 신규 기술
- 면역 크로마토그래피
- 보완 기술
- 동결건조 기술
- 관련 기술
- ELISA(효소면역측정법)
- 기술·제품 로드맵
- 특허 분석
- 주요 특허 리스트
- 향후 응용
- AI/생성형 AI가 래터럴 플로우 분석 시장에 미치는 영향
- 주요 활용 사례 및 시장 잠재력
- AI를 도입한 주요 기업
- AI의 미래
제7장 규제 현황 및 지속가능성 노력
- 지역별 규제 및 규정 준수
- 규제 분석
- 규제기관, 정부 기관 및 기타 조직
- 지속가능성 노력
- 측류 분석(Lateral Flow Assay) 시장의 환경적 영향 및 친환경 구상
- 지속가능성에 미치는 영향 및 규제 정책 구상
제8장 고객 동향 및 구매 행동
- 의사결정 과정
- 구매자의 이해관계자와 구매 평가 기준
- 구매 과정에서 주요 이해관계자
- 구매 기준
- 도입 장벽 및 사내 과제
- 각 최종 용도 산업별 미충족 수요
- 시장의 수익성
- 수익 창출 가능성
- 비용 동향
- 주요 용도에서의 이익률 향상 기회
제9장 래터럴 플로우 분석법 시장: 제품별
- 키트 및 시약
- 선도 기업
제10장 횡류 면역 분석법 키트 및 시약 시장: 기법별
- 샌드위치법
- 경쟁 분석법
- 멀티플렉스 검출 분석법
제11장 횡류 면역 분석법 시장: 용도별
- 임상 검사
- 수의학 진단
- 식품 안전 및 환경 검사
- 의약품 개발 및 품질 시험
제12장 래터럴 플로우 분석법 시장: 검체 유형별
- 혈액 검체
- 소변 검체
- 타액 검체
- 기타 검체
제13장 래터럴 플로우 분석법 시장: 최종사용자별
- 병원·진료소
- 재택 간호 시설
- 진단 실험실
- 제약·바이오기술 기업
- 기타 최종사용자
제14장 래터럴 플로우 분석법 시장: 지역별
- 북미
- 미국
- 캐나다
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 일본
- 중국
- 인도
- 호주
- 한국
- 기타 아시아태평양
- 라틴아메리카
- 브라질
- 멕시코
- 아르헨티나
- 기타 라틴아메리카
- 중동 및 아프리카
- 감염병 부담 증가와 정부 지원 확대가 시장을 촉진
- GCC 국가들
- 신속하고 비용 효율적인 진단법에 대한 수요 증가가 시장을 촉진
제15장 래터럴 플로우 분석법 시장: 판매량 분석
- 2024-2031년 전 세계 신규 결핵 진단 사례 수
제16장 경쟁 현황
- 주요 진입 기업의 전략/강점
- 측류 분석(Lateral Flow Assay) 시장의 주요 기업 전략 개요
- 수익 분석, 2023-2025년
- 시장 점유율 분석, 2025년
- 기업 평가 및 재무 지표
- 브랜드/제품 비교
- 기업 평가 매트릭스: 주요 기업, 2025년
- 스타 기업
- 신흥 리더
- 광범위한 입지를 가진 기업
- 진출 기업
- 기업의 사업 전개: 주요 기업, 2025년
- 기업 평가 매트릭스: 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹: 스타트업/중소기업, 2025년
- 경쟁 시나리오
- 제품 출시 및 승인
- 거래
제17장 기업 개요
- 주요 기업
- ABBOTT LABORATORIES
- F. HOFFMANN-LA ROCHE LTD.
- DANAHER CORPORATION
- QUIDELORTHO CORPORATION
- SIEMENS AG
- BECTON, DICKINSON AND COMPANY
- BIOMERIEUX SA
- THERMO FISHER SCIENTIFIC INC.
- REVVITY, INC.
- QIAGEN N.V.
- MERCK KGAA
- HOLOGIC, INC.
- SURMODICS, INC.
- ORASURE TECHNOLOGIES, INC.
- 기타 주요 기업
- CHEMBIO DIAGNOSTICS, INC.
- DCN DIAGNOSTICS
- POLYSCIENCES INC.
- ABINGDON HEALTH
- ORANOXIS INC.
- AESKU.GROUP GMBH
- BIO GROUP MEDICAL SYSTEM S.R.L.
- PHARMACT GMBH
- XIAMEN BIOTIME BIOTECHNOLOGY CO., LTD.
- BIOPANDA REAGENTS LTD
- ARTRON LABORATORIES INC.
제18장 조사 방법론
제19장 부록
KSA 26.11.03The lateral flow assays market is expected to grow from USD 9.14 billion in 2026 to USD 13.52 billion by 2031, with a CAGR of 8.1%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Product, Application, Technique, Sample Type, and End User |
| Regions covered | North America, Europe, Asia Pacific, Latin America, the Middle East & Africa, and GCC Countries |
The high prevalence of infectious diseases worldwide and the resulting need for testing, rapid growth in the geriatric population, the rising use of home-based lateral flow assay devices, and growing demand for POC testing are the major factors driving market growth. However, inconsistent accuracy compared to other methods and reluctance among doctors and patients to shift from traditional diagnostics are restraining growth in the lateral flow assays market.
"The clinical testing segment, by application, is expected to hold the largest share during the forecast period."
The clinical testing segment is the largest application segment in the lateral flow assays market. By application, the lateral flow assays market is segmented into clinical testing, veterinary diagnostics, food safety & environmental testing, and drug development & quality testing. The clinical testing segment accounted for the largest share of the lateral flow assays market in 2025. This segment's large share is attributed to the rising prevalence of chronic and infectious diseases worldwide, the growing geriatric population, increasing patient awareness of rapid test options, growing pressure to reduce healthcare costs, and increasing demand for patient-centric care.
"The hospitals & clinics segment accounts for the largest market share in the lateral flow assays market."
Based on end users, the LFA market is segmented into hospitals & clinics, diagnostic laboratories, home care settings, pharmaceutical & biotechnology companies, and others. Hospitals & clinics accounted for the largest market share in 2025. Technological advancements, increasing adoption of point-of-care testing, and the growing inclination toward fast, early diagnosis are driving growth in the hospitals & clinics segment.
"North America is expected to hold the largest share during the forecast period."
The global lateral flow assays market is segmented into six major regions: North America, Europe, Asia Pacific, Latin America, the Middle East & Africa, and GCC Countries. North America leads this market, driven by advanced healthcare infrastructure, significant healthcare expenditure, and the strong presence of key manufacturers. The increasing aging population, rising prevalence of infectious and chronic diseases, and strong demand for home-use and self-test kits further support market growth in North America. This regional segment is expected to maintain its dominant position throughout the forecast period.
A breakdown of the primary participants referred to in this report is provided below:
- By Company Type: Tier 1: 40%, Tier 2: 30%, and Tier 3: 30%
- By Designation: C-level: 27%, Director Level: 18%, and Others: 55%
- By Region: North America: 51%, Europe: 21%, Asia Pacific: 18%, Latin America: 6%, and Middle East & Africa: 4%
- The major players operating in the lateral flow assays market are Abbott Laboratories (US), F. Hoffmann-La Roche Ltd. (Switzerland), Danaher Corporation (US), Becton, Dickinson and Company (US), QuidelOrtho Corporation (US), Siemens AG (Germany), bioMerieux SA (France), Thermo Fisher Scientific, Inc. (US), Revvity, Inc. (US), Hologic, Inc. (US), QIAGEN N.V. (Netherlands), Merck KGaA (Germany), SurModics, Inc. (US), and OraSure Technologies, Inc. (US).
Research Coverage
This report studies the lateral flow assays market based on product (kits & reagents and readers), application (clinical testing, veterinary diagnostics, food safety & environmental testing, and drug development & quality testing), technique (sandwich assays, competitive assays, and multiplex detection assays), sample type (blood samples, urine samples, saliva samples, and other samples), end user (hospitals & clinics, diagnostic laboratories, home care settings, pharmaceutical & biotechnology companies, and other end users), and region (North America, Europe, Asia Pacific, Latin America, the Middle East & Africa, and GCC Countries). The report also studies factors (such as drivers, restraints, opportunities, and challenges) affecting market growth and provides details of the competitive landscape for market leaders. Furthermore, the report analyzes micromarkets by their individual growth trends. It forecasts revenue for the market segments across six major regions (and the respective countries in these regions).
Reasons to Buy the Report
The report will enable established firms as well as entrants/smaller firms to gauge the pulse of the market, which, in turn, would help them to gain a larger market share. Firms purchasing the report could use one or a combination of the strategies mentioned below to strengthen their market presence.
The report provides insights on the following points:
- Analysis of key drivers (high prevalence of infectious diseases, rising geriatric population, growing use of home-based lateral flow assay devices, and growing demand for POC testing), restraints (inconsistent results of lateral flow assay tests), opportunities (evolving applications of lateral flow assays and rising demand for lateral flow assays in the food & beverage industry), and challenges (limited reimbursements for lateral flow assay products and difficulties in procuring quality raw materials to develop tests)
- Market Penetration: Comprehensive information on the product portfolios offered by the top players in the lateral flow assays market
- Product Development/Innovation: Detailed insights into the upcoming trends, R&D activities, and product launches in the lateral flow assays market
- Market Development: Comprehensive information on lucrative emerging regions
- Market Diversification: Exhaustive information about new products, growing geographies, and recent developments in the lateral flow assays market
- Competitive Assessment: In-depth assessment of market segments, growth strategies, revenue analysis, and products of the leading market players
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKETS COVERED
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 LATERAL FLOW ASSAYS MARKET OVERVIEW
- 3.2 LATERAL FLOW ASSAYS MARKET, BY PRODUCT, 2026 VS. 2031
- 3.3 LATERAL FLOW ASSAYS MARKET, BY APPLICATION, 2026 VS. 2031
- 3.4 LATERAL FLOW ASSAY KITS & REAGENTS MARKET, BY TECHNIQUE, 2026 VS. 2031
- 3.5 LATERAL FLOW ASSAYS MARKET, BY SAMPLE TYPE, 2026 VS. 2031
- 3.6 LATERAL FLOW ASSAYS MARKET, BY END USER, 2026 VS. 2031
- 3.7 LATERAL FLOW ASSAYS MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 High prevalence of infectious diseases
- 4.2.1.2 Rising geriatric population
- 4.2.1.3 Growing use of home-based lateral flow assay devices
- 4.2.1.4 Growing demand for point-of-care (POC) testing
- 4.2.2 RESTRAINTS
- 4.2.2.1 Inconsistent results of lateral flow assay tests
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Evolving applications of lateral flow assays
- 4.2.3.2 Rising demand for lateral flow assays in food & beverage industry
- 4.2.4 CHALLENGES
- 4.2.4.1 Limited reimbursements for lateral flow assay products
- 4.2.4.2 Difficulties in procuring quality raw materials to develop tests
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN LATERAL FLOW ASSAYS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF NEW ENTRANTS
- 5.1.4 THREAT OF SUBSTITUTES
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE, BY REGION, 2024-2026
- 5.6.2 AVERAGE SELLING PRICE, BY KEY PLAYER, 2024-2026
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 382200)
- 5.7.2 EXPORT SCENARIO (HS CODE 382200)
- 5.8 KEY CONFERENCES & EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.10 INVESTMENT & FUNDING SCENARIO
- 5.11 IMPACT OF 2025 US TARIFFS-LATERAL FLOW ASSAYS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END-USE INDUSTRIES
- 5.11.5.1 Hospitals & clinics
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 IMMUNOCHROMATOGRAPHY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 LYOPHILIZATION (FREEZE-DRYING) TECHNOLOGIES
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 ELISA (ENZYME-LINKED IMMUNOSORBENT ASSAYS)
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.5 PATENT ANALYSIS
- 6.5.1 LIST OF MAJOR PATENTS
- 6.6 FUTURE APPLICATIONS
- 6.7 IMPACT OF AI/GENERATIVE AI ON LATERAL FLOW ASSAYS MARKET
- 6.7.1 INTRODUCTION
- 6.7.2 TOP USE CASES AND MARKET POTENTIAL
- 6.7.3 KEY COMPANIES IMPLEMENTING AI
- 6.7.4 FUTURE OF AI
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY ANALYSIS
- 7.1.1.1 North America
- 7.1.1.2 Europe
- 7.1.1.3 Asia Pacific
- 7.1.1.3.1 India
- 7.1.1.3.2 China
- 7.1.1.3.3 Japan
- 7.1.2 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.4 Latin America
- 7.1.2.5 Rest of the world
- 7.1.1 REGULATORY ANALYSIS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 ENVIRONMENTAL IMPACT AND ECO-FRIENDLY INITIATIVES IN LATERAL FLOW ASSAYS MARKET
- 7.2.1.1 Eco-friendly Initiatives
- 7.2.1 ENVIRONMENTAL IMPACT AND ECO-FRIENDLY INITIATIVES IN LATERAL FLOW ASSAYS MARKET
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 LATERAL FLOW ASSAYS MARKET, BY PRODUCT
- 9.1 INTRODUCTION
- 9.2 KITS & REAGENTS
- 9.2.1 RISE IN DEMAND FOR POC TESTING TO DRIVE MARKET
- 9.3 READERS
- 9.3.1 DIGITAL/HANDHELD READERS
- 9.3.1.1 Technological evolutions and demand for accuracy to drive adoption
- 9.3.2 BENCHTOP READERS
- 9.3.2.1 Lower diagnosis cost per patient to drive adoption
- 9.3.1 DIGITAL/HANDHELD READERS
10 LATERAL FLOW ASSAY KITS & REAGENTS MARKET, BY TECHNIQUE
- 10.1 INTRODUCTION
- 10.2 SANDWICH ASSAYS
- 10.2.1 WIDE RANGE OF APPLICATIONS IN CLINICAL TESTING TO SUPPORT MARKET GROWTH
- 10.3 COMPETITIVE ASSAYS
- 10.3.1 REDUCED SELECTIVITY AND SENSITIVITY COMPARED TO SANDWICH ASSAYS TO HAMPER GROWTH
- 10.4 MULTIPLEX DETECTION ASSAYS
- 10.4.1 HIGHER ADOPTION OF MULTI-ANALYTE ASSAYS AMONG CLINICIANS TO FUEL MARKET
11 LATERAL FLOW ASSAYS MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 CLINICAL TESTING
- 11.2.1 INFECTIOUS DISEASE TESTING
- 11.2.1.1 Mosquito-borne diseases
- 11.2.1.1.1 Increase in incidence of dengue and introduction of more reliable test kits to drive market
- 11.2.1.2 Influenza
- 11.2.1.2.1 Rise in prevalence of influenza globally to boost market growth, despite lower sensitivity of lateral flow assays
- 11.2.1.3 Sexually transmitted infections
- 11.2.1.3.1 HIV
- 11.2.1.3.1.1 Growing need for early detection and awareness of HIV POC testing to drive market
- 11.2.1.3.2 HPV
- 11.2.1.3.2.1 Rapid HPV diagnostics and real-time PCR, covering a broad range of genotypes, coupled with the higher incidence of cervical cancer to drive segment
- 11.2.1.3.3 Chlamydia
- 11.2.1.3.3.1 Greater viability of advanced techniques to drive market
- 11.2.1.3.4 Gonorrhea
- 11.2.1.3.4.1 Rising incidence of gonorrhea and antimicrobial resistance to augment growth
- 11.2.1.3.5 Syphilis
- 11.2.1.3.5.1 Need for early and accessible diagnosis to fuel growth
- 11.2.1.3.6 Other sexually transmitted infections
- 11.2.1.3.1 HIV
- 11.2.1.4 Hepatitis
- 11.2.1.4.1 Nucleic acid hybridization-based LFAs to show strong potential in hepatitis testing
- 11.2.1.5 Tuberculosis
- 11.2.1.5.1 Rise in prevalence and growing focus on early diagnosis and treatment to propel market
- 11.2.1.6 Other infectious diseases
- 11.2.1.1 Mosquito-borne diseases
- 11.2.2 CARDIAC MARKER TESTING
- 11.2.2.1 Troponin I & T
- 11.2.2.1.1 Introduction of high-sensitivity troponin assays to support market growth
- 11.2.2.2 CK-MB
- 11.2.2.2.1 Growing applications of lateral flow tests in acute myocardial injuries to drive market
- 11.2.2.3 BNP & NT-proBNP
- 11.2.2.3.1 Increase in demand for cardiac biomarker tests to detect heart stress and damage to support growth
- 11.2.2.4 Myoglobin
- 11.2.2.4.1 Availability of new high-sensitivity cardiac troponin assays to restrict market growth
- 11.2.2.5 D-Dimer
- 11.2.2.5.1 Rising incidence of CVDs to drive market for D-Dimer tests
- 11.2.2.6 Other cardiac markers
- 11.2.2.1 Troponin I & T
- 11.2.3 PREGNANCY & FERTILITY TESTING
- 11.2.3.1 Pregnancy testing
- 11.2.3.1.1 Pregnancy testing to hold larger market share but register slower growth
- 11.2.3.2 Fertility testing
- 11.2.3.2.1 Rise in infertility rates to drive demand for POC fertility testing kits
- 11.2.3.1 Pregnancy testing
- 11.2.4 CHOLESTEROL/LIPID TESTING
- 11.2.4.1 Lifestyle changes, cardiovascular disorder incidence to drive segment
- 11.2.5 DRUGS-OF-ABUSE TESTING
- 11.2.5.1 Technological advancements and rising focus on workplace drug testing to drive market
- 11.2.6 OTHER CLINICAL TESTS
- 11.2.1 INFECTIOUS DISEASE TESTING
- 11.3 VETERINARY DIAGNOSTICS
- 11.3.1 INFECTIOUS DISEASE OUTBREAKS AND TESTS AVAILABLE FOR DIFFERENT SPECIES TO DRIVE FRAGMENTED MARKET
- 11.4 FOOD SAFETY & ENVIRONMENT TESTING
- 11.4.1 HIGH SENSITIVITY AND EASE OF USE TO BOOST DEMAND FOR ASSAYS TO CLEAR FOODS FOR MARKET AVAILABILITY
- 11.5 DRUG DEVELOPMENT & QUALITY TESTING
- 11.5.1 GREATER FOCUS ON PRODUCT SAFETY AND QUALITY ASSURANCE TO SUPPORT MARKET GROWTH
12 LATERAL FLOW ASSAYS MARKET, BY SAMPLE TYPE
- 12.1 INTRODUCTION
- 12.2 BLOOD SAMPLES
- 12.2.1 SIGNIFICANT USE OF BLOOD SAMPLES FOR INFECTIOUS DISEASE TESTING TO DRIVE MARKET
- 12.3 URINE SAMPLES
- 12.3.1 GROWING USE OF URINE SAMPLES FOR PREGNANCY AND DRUGS- OF-ABUSE TESTING TO DRIVE MARKET
- 12.4 SALIVA SAMPLES
- 12.4.1 EASY AND LOW-COST COLLECTION, TRANSPORT, AND ANALYSIS OF SALIVA SAMPLES TO SUPPORT ADOPTION
- 12.5 OTHER SAMPLES
13 LATERAL FLOW ASSAYS MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 HOSPITALS & CLINICS
- 13.2.1 HIGH DEMAND FOR DIAGNOSTICS ACROSS LARGE POOLS OF PATIENTS IN HOSPITALS TO DRIVE MARKET
- 13.3 HOME CARE SETTINGS
- 13.3.1 GROWING ACCEPTANCE OF REMOTE MONITORING TO PROPEL MARKET
- 13.4 DIAGNOSTIC LABORATORIES
- 13.4.1 LABORATORY TESTING LARGELY PREFERRED OVER PROFESSIONAL SETTINGS FOR URINE AND BLOOD TESTING
- 13.5 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 13.5.1 RISING FOCUS ON PRODUCT SAFETY TO DRIVE ADOPTION OF LATERAL FLOW ASSAYS
- 13.6 OTHER END USERS
14 LATERAL FLOW ASSAYS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Large patient base to drive market growth
- 14.2.2 CANADA
- 14.2.2.1 Availability of research funding and implementation of favorable government initiatives to drive market
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 GERMANY
- 14.3.1.1 Well-developed healthcare system and rise in geriatric population to fuel growth
- 14.3.2 UK
- 14.3.2.1 Growth in incidence of chronic conditions to propel market growth
- 14.3.3 FRANCE
- 14.3.3.1 High prevalence of age-related chronic diseases and infectious diseases to drive market
- 14.3.4 ITALY
- 14.3.4.1 Growth in initiatives toward decentralization of medical services to support market growth
- 14.3.5 SPAIN
- 14.3.5.1 Aging population and strong healthcare infrastructure to drive market
- 14.3.6 REST OF EUROPE
- 14.3.1 GERMANY
- 14.4 ASIA PACIFIC
- 14.4.1 JAPAN
- 14.4.1.1 Growing elderly population and well-developed healthcare system to drive market
- 14.4.2 CHINA
- 14.4.2.1 Modernized healthcare system to drive market
- 14.4.3 INDIA
- 14.4.3.1 Growth in healthcare concerns and rise in income levels to propel market growth
- 14.4.4 AUSTRALIA
- 14.4.4.1 Rise in prevalence of infectious disease and healthcare expenditure to support growth
- 14.4.5 SOUTH KOREA
- 14.4.5.1 Growth in healthcare infrastructure to drive market
- 14.4.6 REST OF ASIA PACIFIC
- 14.4.1 JAPAN
- 14.5 LATIN AMERICA
- 14.5.1 BRAZIL
- 14.5.1.1 High private healthcare expenditure and rise in geriatric population to drive market
- 14.5.2 MEXICO
- 14.5.2.1 Efficient healthcare system and universal health coverage to support adoption
- 14.5.3 ARGENTINA
- 14.5.3.1 Availability of health insurance to favor market growth
- 14.5.4 REST OF LATIN AMERICA
- 14.5.1 BRAZIL
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 RISING BURDEN OF INFECTIOUS DISEASES AND GROWING GOVERNMENT SUPPORT TO DRIVE MARKET
- 14.7 GCC COUNTRIES
- 14.7.1 RISE IN DEMAND FOR RAPID AND COST-EFFECTIVE DIAGNOSTICS TO DRIVE MARKET
15 LATERAL FLOW ASSAYS MARKET: VOLUME ANALYSIS
- 15.1 INTRODUCTION
- 15.2 GLOBAL NUMBER OF NEWLY DIAGNOSED TB CASES, 2024-2031 (MILLION)
16 COMPETITIVE LANDSCAPE
- 16.1 INTRODUCTION
- 16.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 16.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN LATERAL FLOW ASSAYS MARKET
- 16.3 REVENUE ANALYSIS, 2023-2025
- 16.4 MARKET SHARE ANALYSIS, 2025
- 16.5 COMPANY VALUATION AND FINANCIAL METRICS
- 16.6 BRAND/PRODUCT COMPARISON
- 16.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 16.7.1 STARS
- 16.7.2 EMERGING LEADERS
- 16.7.3 PERVASIVE PLAYERS
- 16.7.4 PARTICIPANTS
- 16.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 16.7.5.1 Company footprint
- 16.7.5.2 Region footprint
- 16.7.5.3 Product footprint
- 16.7.5.4 Technique footprint
- 16.7.5.5 Application footprint
- 16.7.5.6 Sample type footprint
- 16.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 16.8.1 PROGRESSIVE COMPANIES
- 16.8.2 RESPONSIVE COMPANIES
- 16.8.3 DYNAMIC COMPANIES
- 16.8.4 STARTING BLOCKS
- 16.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 16.8.5.1 Detailed list of key startup/SME players
- 16.8.5.2 Competitive benchmarking of key startups/SMEs
- 16.9 COMPETITIVE SCENARIO
- 16.9.1 PRODUCT LAUNCHES & APPROVALS
- 16.9.2 DEALS
17 COMPANY PROFILES
- 17.1 KEY PLAYERS
- 17.1.1 ABBOTT LABORATORIES
- 17.1.1.1 Business overview
- 17.1.1.2 Products offered
- 17.1.1.3 Recent developments
- 17.1.1.3.1 Product launches & approvals
- 17.1.1.4 MnM view
- 17.1.1.4.1 Right to win
- 17.1.1.4.2 Strategic choices
- 17.1.1.4.3 Weaknesses and competitive threats
- 17.1.2 F. HOFFMANN-LA ROCHE LTD.
- 17.1.2.1 Business overview
- 17.1.2.2 Products offered
- 17.1.2.3 Recent developments
- 17.1.2.3.1 Deals
- 17.1.2.4 MnM view
- 17.1.2.4.1 Right to win
- 17.1.2.4.2 Strategic choices
- 17.1.2.4.3 Weaknesses and competitive threats
- 17.1.3 DANAHER CORPORATION
- 17.1.3.1 Business overview
- 17.1.3.2 Products offered
- 17.1.3.3 Recent developments
- 17.1.3.3.1 Deals
- 17.1.3.4 MnM view
- 17.1.3.4.1 Right to win
- 17.1.3.4.2 Strategic choices
- 17.1.3.4.3 Weaknesses and competitive threats
- 17.1.4 QUIDELORTHO CORPORATION
- 17.1.4.1 Business overview
- 17.1.4.2 Products offered
- 17.1.4.3 Recent developments
- 17.1.4.3.1 Product launches
- 17.1.5 SIEMENS AG
- 17.1.5.1 Business overview
- 17.1.5.2 Products offered
- 17.1.6 BECTON, DICKINSON AND COMPANY
- 17.1.6.1 Business overview
- 17.1.6.2 Products offered
- 17.1.6.3 Recent developments
- 17.1.6.3.1 Product approvals
- 17.1.7 BIOMERIEUX SA
- 17.1.7.1 Business overview
- 17.1.7.2 Products offered
- 17.1.7.3 Recent developments
- 17.1.7.3.1 Deals
- 17.1.8 THERMO FISHER SCIENTIFIC INC.
- 17.1.8.1 Business overview
- 17.1.8.2 Products offered
- 17.1.9 REVVITY, INC.
- 17.1.9.1 Business overview
- 17.1.9.2 Products offered
- 17.1.10 QIAGEN N.V.
- 17.1.10.1 Business overview
- 17.1.10.2 Products offered
- 17.1.11 MERCK KGAA
- 17.1.11.1 Business overview
- 17.1.11.2 Products offered
- 17.1.12 HOLOGIC, INC.
- 17.1.12.1 Business overview
- 17.1.12.2 Products offered
- 17.1.12.3 Recent developments
- 17.1.12.3.1 Deals
- 17.1.13 SURMODICS, INC.
- 17.1.13.1 Business overview
- 17.1.13.2 Products offered
- 17.1.13.3 Recent developments
- 17.1.13.3.1 Deals
- 17.1.14 ORASURE TECHNOLOGIES, INC.
- 17.1.14.1 Business overview
- 17.1.14.2 Products offered
- 17.1.14.3 Recent developments
- 17.1.14.3.1 Product launches & approvals
- 17.1.14.3.2 Deals
- 17.1.1 ABBOTT LABORATORIES
- 17.2 OTHER PLAYERS
- 17.2.1 CHEMBIO DIAGNOSTICS, INC.
- 17.2.2 DCN DIAGNOSTICS
- 17.2.3 POLYSCIENCES INC.
- 17.2.4 ABINGDON HEALTH
- 17.2.5 ORANOXIS INC.
- 17.2.6 AESKU.GROUP GMBH
- 17.2.7 BIO GROUP MEDICAL SYSTEM S.R.L.
- 17.2.8 PHARMACT GMBH
- 17.2.9 XIAMEN BIOTIME BIOTECHNOLOGY CO., LTD.
- 17.2.10 BIOPANDA REAGENTS LTD
- 17.2.11 ARTRON LABORATORIES INC.
18 RESEARCH METHODOLOGY
- 18.1 RESEARCH DATA
- 18.1.1 SECONDARY DATA
- 18.1.1.1 Key data from secondary sources
- 18.1.2 PRIMARY DATA
- 18.1.2.1 Primary sources
- 18.1.2.2 Key industry insights
- 18.1.2.3 Key data from primary sources
- 18.1.2.4 Breakdown of primary interviews
- 18.1.1 SECONDARY DATA
- 18.2 MARKET SIZE ESTIMATION
- 18.2.1 BOTTOM-UP APPROACH
- 18.2.1.1 Approach 1: Company revenue estimation approach
- 18.2.1.2 Approach 2: Presentations of companies and primary interviews
- 18.2.1.3 Approach 3: Primary interviews
- 18.2.1.4 Approach 4: Growth Forecast
- 18.2.1.5 CAGR projections
- 18.2.2 TOP-DOWN APPROACH
- 18.2.1 BOTTOM-UP APPROACH
- 18.3 MARKET BREAKDOWN & DATA TRIANGULATION
- 18.4 RESEARCH ASSUMPTIONS
- 18.4.1 STUDY-RELATED ASSUMPTIONS
- 18.4.2 GROWTH RATE ASSUMPTIONS
- 18.5 RISK ASSESSMENT
- 18.6 RESEARCH LIMITATIONS
19 APPENDIX
- 19.1 DISCUSSION GUIDE
- 19.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.3 CUSTOMIZATION OPTIONS
- 19.4 RELATED REPORTS
- 19.5 AUTHOR DETAILS


