|
시장보고서
상품코드
2044182
생산용 프린터 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Production Printer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
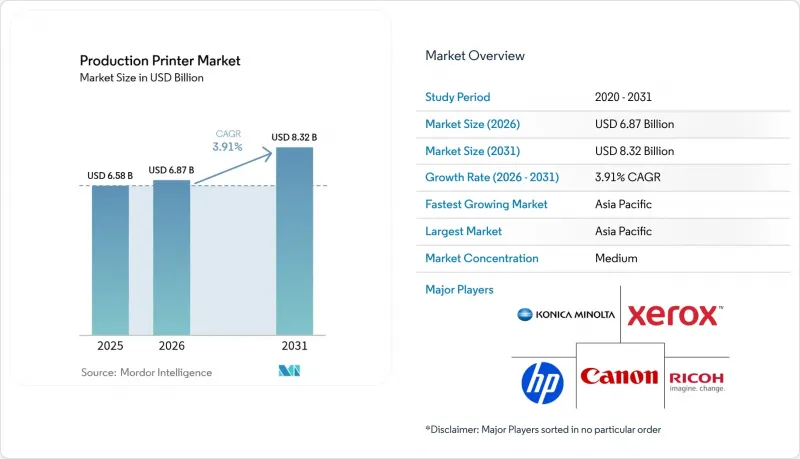
생산용 프린터 시장 규모는 2025년 65억 8,000만 달러, 2026년 68억 7,000만 달러에서 2031년까지 83억 2,000만 달러로 확대한다고 예측되고 있어 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 3.91%를 나타낼 전망입니다.
전통적인 출판 및 트랜잭션 메일에서 패키징, 라벨, 온디맨드 상업 인쇄로의 전환으로 수익 구조가 재편되고 있습니다. 디지털 워크플로우를 통한 대량 커스터마이징이 가능해져 기존 부문의 인쇄량 감소를 상쇄하고 있습니다. 브랜드 소유자는 한정판 SKU(재고 관리 단위) 출시, 복잡한 라벨 규정 준수, 빠른 배송 주문 관리를 위해 가변 데이터 워크플로우를 채택하고 있으며, 이 모든 것이 아날로그 장비보다 디지털 기반 인쇄기를 선호하고 있습니다. 반도체 공급망이 정상화되면서 설비투자가 점차 회복되고 있으며, 2024년 중반까지 고속 잉크젯 기계 도입에 제약이 되었던 납기가 단축되고 있습니다. 경쟁은 치열해지고 있지만, 서비스 계약의 경제성과 성과 기반 가격 모델 덕분에 저가의 아시아계 신규 진입 업체들의 장비 정가 압박에도 불구하고 벤더들은 수익률을 유지할 수 있었습니다.
세계 프로덕션 프린터 시장 동향 및 인사이트
패키징 분야에서의 인쇄 적용 확대
컨버터 업체들이 과거 대량 생산을 위한 아날로그 워크플로우에 유리했던 최소 주문 수량의 제약을 없애면서 디지털 인쇄기는 플렉서블 필름, 골판지, 접이식 카톤 생산 라인에 침투하고 있습니다. 2030년까지 재활용 가능한 단일 소재 구조를 의무화하는 유럽연합(EU)의 현행 규정은 특히 폴리에틸렌 및 폴리프로필렌 필름에서 수성 잉크젯으로의 전환을 가속화하고 있습니다. 식품 접촉용 잉크 인증을 획득하고 Delta E 2.0 이내의 색 재현성을 달성할 수 있는 인쇄기 제조업체는 특히 독일과 이탈리아에서 브랜드 소유자가 통일된 매장 내 소구력을 추구하는 인쇄기 제조업체의 우선 공급업체가 되고 있습니다. 초기 도입 기업들은 다층 라미네이트를 대체하는 단층 배리어 코팅 덕분에 최대 15%의 재료비 절감 효과를 보고하고 있습니다.
소량 및 주문형 인쇄 요구 사항
상업용 인쇄업체 수익의 절반 이상이 현재 5,000부 미만의 인쇄물에서 창출되고 있습니다. 소매업체가 프로모션을 지역화하고 제약회사가 일련번호 코드를 준수함에 따라 이 부문은 빠르게 성장하고 있습니다. 컷시트 잉크젯 플랫폼은 1,000부 미만의 인쇄로도 수익성을 확보할 수 있습니다. 이는 연속 급지 방식에 비해 훨씬 빠른 10분 이내로 전환이 가능하기 때문입니다. 납기 단축을 통해 소량 생산 시에도 수익률이 향상되고, 48시간 이내 납기를 계약으로 보장할 수 있다면 프리미엄 가격 설정도 가능합니다.
디지털 마케팅과 전자책으로의 전환
프로그래매틱 광고가 지속적으로 예산 점유율을 확대하고 있으며, 과거 연속 급지 웹 인쇄기를 가득 채우던 직접 메일의 인쇄량은 감소하고 있습니다. 미국 일반 도서 판매의 3분의 1 이상을 차지하는 전자책의 보급은 단납기 출판 수요를 더욱 압박하고 있습니다. 패키지 및 라벨 분야는 여전히 영향을 덜 받지만, 상업용 인쇄업체들은 나머지 업무에서 치열한 경쟁을 겪고 있으며, 2020년 이후 평균 영업 이익률은 몇 포인트 하락하고 있습니다.
부문 분석
컬러 장비는 2025년 매출의 69.42%를 차지하고, 2031년까지 연평균 4.28%의 연평균 복합 성장률(CAGR)로 생산용 프린터 시장 규모에서 차지하는 비중이 증가할 것으로 예측됩니다. 브랜드 소유주들은 전 세계 공급망에 걸쳐 선반에서 식별성을 보장하기 위해 메탈릭 마감과 정밀한 스팟 컬러 매칭을 위해 기꺼이 추가 비용을 지불하고 있습니다. 현재 표준 피에조 헤드로 인쇄할 수 있는 메탈릭 잉크와 기능성 잉크를 통해 고급 주류 라벨에서 RFID 안테나까지 적용 가능한 용도가 확대되고 있습니다.
매출의 30.58%를 차지하는 흑백 엔진은 페이지당 비용이 0.01달러 미만으로 컬러 요구 사항을 능가하는 트랜잭션 메일과 서적 본문 페이지에서 여전히 자리를 잡고 있습니다. 그러나 명세서의 온라인화가 진행되고 출판사가 텍스트 블록과 표지 아트를 이중 워크플로우 없이 처리할 수 있는 컬러 지원 플랫폼으로 전환함에 따라 이러한 틈새 시장조차도 축소되고 있습니다. 잉크젯용 소모품 비용이 지속적으로 하락하는 가운데, 많은 상업용 인쇄업체들이 흑백 전용기를 폐지하고, 자산 활용을 극대화하기 위해 비수기 단순 텍스트 인쇄 업무를 컬러 인쇄기로 전환하고 있습니다.
연속 급지 라인은 2025년 매출의 57.12%를 차지하고, 페이지당 운영비용이 낮고 마무리 공정이 통합되어 있어 5만부 이상의 작업에서 압도적인 점유율을 유지하고 있습니다. 그러나 전환의 복잡성, 몇 시간에 걸친 설정 시간, 전담 작업자의 필요성으로 인해 오늘날의 소량 주문에 대한 적합성은 제한적입니다. CAGR 4.31%로 시장 성장률을 상회할 것으로 예상되는 컷시트 라인은 5,000부 미만의 단납기 상업용 인쇄 및 패키징 작업에서 기본 선택이 되고 있습니다. 이 장비는 몇 분 안에 용지를 전환할 수 있고, 한 번의 교대 근무에서 서로 다른 재료를 혼합할 수 있으며, 인라인 다이 커팅 및 라미네이팅 장비와 결합하여 인쇄기 외부의 작업을 없앨 수 있습니다.
자산의 유연성은 매년 수십 가지의 지역별로 다양한 제품을 출시하는 소비재 브랜드에 서비스를 제공하는 컨버터에게 특히 매력적입니다. 이들 컨버터는 하루에 여러 고객을 대상으로 스케줄을 짜고 있는데, 이는 몇 시간에 걸친 단일 고객에 대한 블록을 전제로 하는 연속 급지 방식의 규모의 경제와는 상충되는 패턴입니다. 우편 규제 당국이 자동화 요금 바코드 규정을 강화하는 가운데, 가변 데이터베이스를 인라인으로 통합할 수 있는 컷시트 플랫폼이 미국 내 직접 메일 주문을 수주하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 35.32%를 차지할 것으로 예상되며, 2031년까지 연평균 4.93%의 연평균 복합 성장률(CAGR)로 2031년까지 생산용 프린터 시장 규모에 대한 기여도가 확대될 것으로 예측됩니다. 1,800억 달러 규모의 중국 포장 산업에서 규제 당국의 솔벤트 기반 플 렉소 인쇄 공장 폐쇄가 진행되면서 컨버터 업체들은 물 사용량을 70-80% 절감할 수 있는 잉크젯 설비 도입을 서두르고 있습니다. 두 자릿수 성장을 기록하고 있는 인도의 골판지 부문도 마찬가지로 지역별로 다른 그래픽을 필요로 하는 전자상거래 주문처리에 대응하기 위해 디지털 워크플로우를 도입하고 있습니다. 베트남의 라벨 산업 클러스터는 공급망 다변화를 배경으로 다국적 소비재 기업들이 최종 조립기지 근처에서 적시 생산을 위탁하고 있습니다.
북미는 시장 규모 2위를 차지하고 있지만, 디지털 광고와 전자책의 보급으로 직접 메일과 출판 분야는 구조적인 수요 감소에 직면해 있습니다. 식품, 음료, 퍼스널케어 분야의 패키징 성장이 이러한 감소를 일부 상쇄하고 있으며, 컨버터 업체들은 각 주에서 강화되는 재활용 규제에 대응하기 위해 고속 잉크젯에 대한 투자를 지속하고 있습니다. 미국 우정공사(USPS)의 바코드 도입 장려 정책은 타겟팅된 우편물을 위한 컷시트형 가변 데이터 인쇄기의 도입을 더욱 촉진하고 있습니다.
유럽은 프로덕션 프린터 시장에서 3번째로 높은 점유율을 차지하고 있습니다. PFAS 화학물질에 대한 규제가 도입의 원동력이 되고 있으며, 잉크 제조업체는 안료 분산액을 재조정해야 하고, 경우에 따라서는 인쇄기 출시가 최대 1년 정도 늦어질 수도 있습니다. 남미, 중동, 아프리카를 합친 시장 규모는 여전히 세계 전체 매출의 4분의 1 미만에 불과합니다. 환율 변동과 공급업체의 대출 제한으로 인해 투자 회수 기간이 길어지고 설비 교체 속도가 느려지고 있지만, 지역 내 패키징 분야의 기회는 단계적 업그레이드를 촉진하고 있습니다.
기타 특전:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.06.11The production printer market size is projected to expand from USD 6.58 billion in 2025 and USD 6.87 billion in 2026 to USD 8.32 billion by 2031, registering a 3.91% CAGR between 2026 and 2031.
A shift away from legacy publishing and transactional mail toward packaging, labels, and on-demand commercial work is reshaping profit pools, with digital workflows enabling mass customization that offsets falling volumes in traditional segments. Brand owners are adopting variable-data workflows to launch limited-edition stock-keeping units, comply with complex labeling regulations, and manage shorter order cycles, all of which favor digitally driven presses over analog equipment. Capital spending is gradually recovering as semiconductor supply chains normalize, reducing the delivery lead times that constrained high-speed inkjet installations through mid-2024. Competitive intensity is increasing, yet service-contract economics and outcome-based pricing models are helping vendors defend margins even as equipment list prices come under pressure from low-cost Asian entrants.
Global Production Printer Market Trends and Insights
Growth Of Printing Applications In Packaging
Digital presses are penetrating flexible film, corrugated, and folding-carton lines as converters eliminate minimum order constraints that once favored long-run analog workflows. Ongoing European Union rules mandating recyclable mono-material structures by 2030 accelerate the shift toward water-based inkjet, especially for polyethylene and polypropylene films. Press makers that can certify food-contact inks and achieve color-consistency within Delta E 2.0 have become preferred suppliers, particularly in Germany and Italy where brand owners demand uniform shelf impact. Early adopters report material cost savings of up to 15% thanks to single-layer barrier coatings that replace multi-layer laminates.
Short-Run, On-Demand Print Requirements
Commercial printers now generate more than half of revenue from jobs under 5,000 impressions, a segment that has grown rapidly as retailers localize promotions and pharmaceutical firms comply with serialization codes. Cut-sheet inkjet platforms deliver profitable runs below 1,000 impressions because changeovers can occur in under 10 minutes, far quicker than continuous-feed setups. Faster turnaround raises margins despite smaller volumes, and premium pricing is attainable when 48-hour delivery is contractually guaranteed.
Shift To Digital Marketing And E-Reading
Programmatic advertising continues to capture budget share, cutting direct-mail volumes that once filled continuous-feed webs. E-book penetration above one-third of U.S. trade-book sales further compresses short-run publishing demand. While packaging and labels remain insulated, commercial printers must compete aggressively on the remaining work, and average operating margins have slid several points since 2020.
Other drivers and restraints analyzed in the detailed report include:
- Advances In High-Speed Inkjet Technology
- AI-Driven Predictive Maintenance
- High Capital Expenditure Of Production Printers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Color devices generated 69.42% of 2025 revenue, and their share of the production printer market size is forecast to climb on a 4.28% CAGR through 2031. Brand owners willingly pay premiums for metallic finishes and precise spot-color matching that protect shelf identity across global supply chains. Metallic and functional inks, now printable on standard piezo heads, extend addressable applications from luxury spirits labels to RFID antennas.
Monochrome engines, with 30.58% revenue, persist in transactional mail and book interiors where cost-per-page below USD 0.01 outweighs color requirements. Even those niches are eroding as statements migrate online and publishers pivot to color-capable platforms that handle both text blocks and cover art without dual workflows. As inkjet consumable costs continue to fall, many commercial printers retire black-only fleets and route simple text work to color presses during off-peak shifts to maximize asset utilization.
Continuous-feed lines retained 57.12% of 2025 revenue, dominating jobs above 50,000 impressions thanks to low running costs per page and integrated finishing. Yet changeover complexity, multihour setup windows, and dedicated operators limit their suitability for today's shorter orders. Cut-sheet lines, projected to outpace market growth at a 4.31% CAGR, have become the default choice for fast-turn commercial and packaging work below 5,000 impressions. They switch substrates in minutes, accept mixed media within a shift, and pair with inline die-cutting or lamination units to eliminate off-press handling.
Asset flexibility is particularly attractive to converters serving consumer goods brands that launch dozens of regional variants each year. These converters build schedules around multiple customers per day, a pattern incompatible with the continuous-feed economies of scale that presuppose multi-hour single-customer blocks. As postal regulators tighten automation-rate barcode rules, cut-sheet platforms capable of merging variable databases in line are winning direct-mail placements in the United States.
The Production Printer Market Report is Segmented by Type (Monochrome and Color), Production Method (Cut Sheet, and Continuous Feed), Technology (Inkjet, Electrophotographic, and More), Application (Commercial Printing, Publishing, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Geography Analysis
Asia-Pacific anchored 35.32% of 2025 revenue, and its contribution to the production printer market size is set to widen by a 4.93% CAGR through 2031. China's USD 180 billion packaging sector is consolidating as regulators shutter solvent-based flexographic sites, prompting converters to fast-track inkjet installations that reduce water usage by 70-80%. India's corrugated segment, posting double-digit growth, is likewise embracing digital workflows to serve e-commerce fulfillment that demands variable regional graphics. Vietnam's label clusters ride supply-chain diversification, with multinational consumer-goods companies commissioning just-in-time runs near final assembly nodes.
North America ranks second in market size but faces structural volume erosion in direct mail and publishing as digital advertising and e-reading broaden reach. Packaging growth in food, beverage, and personal-care channels partially offsets those declines, and converters continue to invest in high-speed inkjet to comply with evolving state recycling mandates. The United States Postal Service's barcode incentives further spur adoption of cut-sheet variable-data presses for targeted mailings.
Europe holds the third-largest slice of the production printer market. Adoption is driven by regulations targeting PFAS chemicals, compelling ink formulators to retool pigment dispersions and delaying press launches by up to one year in some cases. South America, the Middle East, and Africa collectively remain below one-quarter of worldwide revenue. Currency volatility and limited vendor financing lengthen capital payback, slowing equipment turnover, although regional packaging opportunities encourage gradual upgrades.
- Xerox Holdings Corporation
- HP Inc.
- Canon Inc.
- Ricoh Company, Ltd.
- Konica Minolta, Inc.
- Eastman Kodak Company
- Fujifilm Holdings Corporation
- Screen Holdings Co., Ltd.
- Heidelberger Druckmaschinen AG
- Durst Group AG
- Xeikon NV (Flint Group)
- Inca Digital Printers Ltd
- Agfa-Gevaert N.V.
- Mark Andy Inc.
- Koenig and Bauer AG
- Riso Kagaku Corporation
- Seiko Epson Corporation
- Domino Printing Sciences plc
- Gallus Ferd. Ruesch AG
- Kyocera Document Solutions Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of Printing Applications in Packaging
- 4.2.2 Short-Run, On-Demand Print Requirements
- 4.2.3 Advances in High-Speed Inkjet Technology
- 4.2.4 Industrial-Grade Metallic and Functional Ink Demand
- 4.2.5 Digital Textile Microfactory Adoption
- 4.2.6 AI-Driven Predictive Maintenance Reducing Downtime
- 4.3 Market Restraints
- 4.3.1 Shift to Digital Marketing and E-Reading
- 4.3.2 High Capital Expenditure of Production Printers
- 4.3.3 Semiconductor Supply-Chain Volatility
- 4.3.4 Regulatory Push for PFAS-Free Ink Formulations Raising R and D Costs
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Monochrome
- 5.1.2 Color
- 5.2 By Production Method
- 5.2.1 Cut Sheet
- 5.2.2 Continuous Feed
- 5.3 By Technology
- 5.3.1 Inkjet
- 5.3.2 Electrophotographic (Toner)
- 5.3.3 Other Technologies
- 5.4 By Application
- 5.4.1 Commercial Printing
- 5.4.2 Publishing
- 5.4.3 Packaging
- 5.4.4 Transactional and Direct Mail
- 5.4.5 Other Applications
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Egypt
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Xerox Holdings Corporation
- 6.4.2 HP Inc.
- 6.4.3 Canon Inc.
- 6.4.4 Ricoh Company, Ltd.
- 6.4.5 Konica Minolta, Inc.
- 6.4.6 Eastman Kodak Company
- 6.4.7 Fujifilm Holdings Corporation
- 6.4.8 Screen Holdings Co., Ltd.
- 6.4.9 Heidelberger Druckmaschinen AG
- 6.4.10 Durst Group AG
- 6.4.11 Xeikon NV (Flint Group)
- 6.4.12 Inca Digital Printers Ltd
- 6.4.13 Agfa-Gevaert N.V.
- 6.4.14 Mark Andy Inc.
- 6.4.15 Koenig and Bauer AG
- 6.4.16 Riso Kagaku Corporation
- 6.4.17 Seiko Epson Corporation
- 6.4.18 Domino Printing Sciences plc
- 6.4.19 Gallus Ferd. Ruesch AG
- 6.4.20 Kyocera Document Solutions Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment