|
시장보고서
상품코드
2061968
예비 부품 물류 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Spare Parts Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 예비 부품 물류 시장 규모는 2025년 492억 2,000만 달러로 평가되었습니다. 2026년에는 515억 7,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR은 4.89%를 나타내, 2031년까지 654억 7,000만 달러에 이를 것으로 예측됩니다.
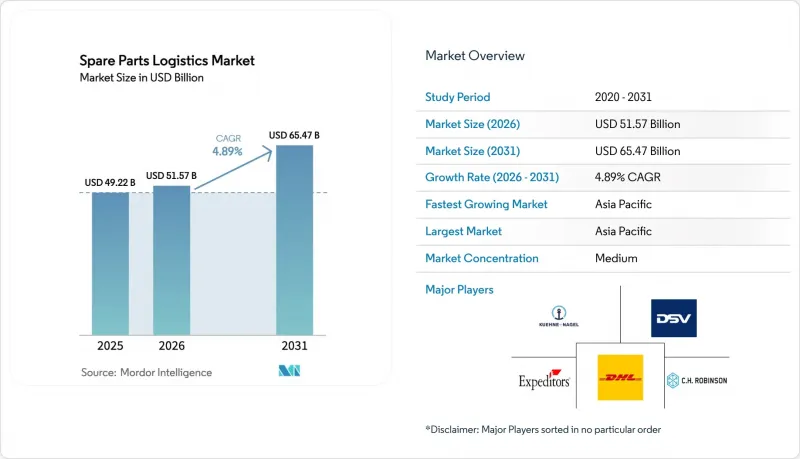
본 보고서는 서비스 유형(운송, 창고 및 물류, 부가가치 서비스), 조달 채널(OEM 채널, 독립형 애프터마켓), 최종 이용 산업(자동차, 항공우주 및 방위, 기타), 비즈니스 유형(B2B, B2C), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 전망은 금액 기준(10억 달러)으로 제시되어 있습니다.
세계의 예비 부품 물류 시장 동향과 인사이트
자주 교체해야 하는 노후화된 산업용 설비
설비 소유자는 자산의 사용 연한을 연장하고 있으며, 노후화에 따른 고장 위험이 높아짐에 따라 부품의 확보 가능성이 최우선 과제가 되고 있습니다. 이러한 운영 환경에서는 단 하나의 부품만 부족해도 생산이 중단되고, 이는 다운스트림 공정 일정이나 인력 계획에 파급 효과를 미칠 우려가 있기 때문에 구매자들은 예비 부품 물류 시장에서 높은 재고 충당률과 정확한 리드 타임을 중요하게 여기게 되었습니다. 또한, 산업 부문에서는 고장을 예측하고 수리 기간을 단축하기 위해 예측 유지보수를 도입하고 있으며, 이를 통해 중요한 SKU를 사전에 확보할 수 있는 공급업체가 유리한 입지를 점하고 있습니다. 설치된 구성을 반영하는 디지털 트윈은 고장 모드 예측 및 적시 보충과 서비스 수준 목표의 조화에 도움이 되며, 이를 통해 유지보수 포트폴리오의 운영 자금이 안정화됩니다. 성숙한 시장에서 설비 투자가 계속 미뤄지는 가운데, 예비 부품 물류 시장은 제조업체가 도입하는 가동률 보장 프로그램의 핵심적인 역할을 담당하게 되었습니다.
제품 판매에서 서비스 기반 수익 모델로의 전환
설치된 장비를 수익원으로 삼는 서비스 기반 계약은 조달 결정 및 예비 부품 물류 시장에서 물류 파트너에게 요구되는 역량을 변화시키고 있습니다. 연결된 기기와 서비스 라이프사이클 관리 플랫폼을 통해, 예측 가능한 부품 흐름에 기반한 가동 시간 보장, 정액 요금제, 그리고 원격 진단이 가능해졌습니다. 성과 기반 계약을 통해 약속된 서비스 성과에 대한 가격 책정 및 제공이 가능한 공급업체로 리스크가 이전됨에 따라, 규제 대상 분야에서 기술을 활용한 물류 및 규정 준수 시설에 대한 수요가 증가하고 있습니다. 엔지니어링 데이터, 재고 현황, 현장 업무를 통합할 수 있는 공급업체는 단순한 운송 업무를 넘어, 지속적인 서비스를 보장하는 통합적인 파트너십으로 발전하고 있습니다. 서비스화가 지역 및 산업 전반으로 확산되는 가운데, 예비 부품 물류 시장에서는 복잡한 부품 카탈로그를 실시간 가시성과 일관된 품질로 관리할 수 있는 공급업체가 높이 평가받고 있습니다.
SKU의 급증으로 인해 재고 관리가 복잡해집니다.
기기의 유형, 소재, 규제 요건에 따라 제품 라인이 세분화됨에 따라 SKU 수가 증가하고 있으며, 이는 예비 부품 물류 시장의 계획 시스템과 창고 공간에 부담을 주고 있습니다. 많은 MRO 부품은 장기간 가동되지 않은 채 방치되는 경우가 많으며, 이로 인해 자본이 묶일 뿐만 아니라 재고 부족으로 인한 벌금을 우려하여 합리화가 진전되지 않는 상황이 발생하고 있습니다. 반품은 상황을 더욱 복잡하게 만듭니다. 전자상거래 채널에서는 반품률이 높고, 예비 재고나 전문적인 처리가 필요하기 때문입니다. AI를 활용한 수요 예측 및 자율 보충 시스템을 도입한 공장에서는 SKU를 중요도나 고장 위험도에 따라 분류함으로써 긴급 구매와 재고 비용을 절감하고 있습니다. 또한, 시판 후 모니터링 및 의료기기 품질 요건의 강화로 인해 헬스케어 물류 분야에서 추적 의무가 발생하고 있으며, 이에 따라 서비스 제공업체의 운영 비용이 증가하고 있습니다.
부문별 분석
운송 서비스는 2025년 매출의 41.78%를 차지했지만, 부가가치 서비스는 연평균 6.32%의 속도로 성장하고 있어, 이로 인해 예비 부품 물류 시장의 고도화 장벽이 높아지고 있습니다. 도로망은 지역 내의 고밀도 보충을 지원하며, 항공 화물은 긴급하고 고가치의 화물을 취급하고, 해상 항로는 정기 유지보수용 재고의 배치를 담당하고 있습니다. 철도는 대륙 간 수송 능력을 보완하며, 예측 가능한 운행 스케줄을 통해 아시아의 허브와 유럽 수요 거점을 연결하고 있습니다. XPO가 북미에서 LTL(소량 혼재 운송)에 지속적으로 투자하고 서비스 센터를 확장하고 있는 것에서 알 수 있듯이, 고성능 네트워크는 자산 관리에 의존하고 있으며, 이를 통해 네트워크의 밀도와 서비스 품질이 향상되고 있습니다. 의료 및 항공우주 분야에서는 온도 관리, 시리얼화, 그리고 규정 준수 기반 보관이 필수 요건으로 자리 잡고 있으며, 2026년에 시행될 미국 FDA의 품질 관리 시스템 규정을 준수하는 인증 시설이 경쟁 우위를 점하게 될 것입니다.
VMI(공급업체 관리 재고), 키팅, 간이 조립 등의 부가가치 서비스는 예비 부품 물류 시장에서 복잡성 프리미엄을 확보하고 있습니다. 이러한 서비스는 기존에 분리되어 있던 공정을 통합된 워크플로로 묶어 처리 속도를 높이고, 고객 접점을 줄여줍니다. 통관 대행 서비스와 보세 시설을 갖춘 공급업체는 국경 간 리드타임을 단축하고, 규제 대상 품목의 통관 리스크를 줄여줍니다. 디지털 트윈 및 커넥티드 서비스 플랫폼의 활용 확대는 고객 현장의 부품 배치 정확도를 높여주며, 이를 통해 물류 성과가 유지보수 기간 및 가동률 보장으로 이어집니다. CEVA와 HAECO 간의 세계 항공 화물 제휴와 같은 파트너십은 지상에서 대기 중인 항공기 대응부터 온도 관리가 필요한 부품에 이르기까지, 항공우주용 예비 부품 분야에서 현재 요구되는 수직적 깊이를 보여주고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 38.21%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 5.21%를 나타낼 전망입니다. 이는 예비 부품 물류 시장에서 신속하고 규정 준수를 충족하는 예비 부품 유통이 필요한 자동차, 전자, 항공우주 분야의 밸류체인에 의해 뒷받침되고 있습니다. 2025년 중국 자동차 업계는 총 3,453만 1,000대의 차량을 생산했으며, 이 중 1,662만 6,000대가 신에너지차였습니다. 또한 709만 8,000대를 수출하고 있으며, 이를 통해 보증 및 서비스 네트워크가 수출 시장으로 확대되고 있습니다. 2026년 초에는 지역별 생산 여건이 악화되어 공급망 혼잡과 새로운 병목 현상의 발생이 예상되었습니다. 이를 통해 주요 SKU에 대한 확실한 대응과 스테이징의 가치가 높아지고 있습니다. 인증된 온도 관리, 위험물 규제 준수, 24시간 운영 체계를 갖춘 물류 업체들은 고부가가치 항공우주 및 헬스케어 분야의 계약을 수주하고 있습니다. 네트워크 확장에서는 통합 통관 대행 서비스와 보세 창고에도 중점을 두고 있으며, 이를 통해 통관 리스크가 감소하고 예비 부품 물류 시장 전체의 운송 시간이 안정화되고 있습니다.
북미와 유럽은 합쳐서 활동의 상당 부분을 차지하고 있으며, 예비 부품 물류 시장 수요는 노후화된 산업 자산, 전기화, 그리고 규제가 엄격한 의료 채널에 의해 뒷받침되고 있습니다. DSV가 2025년에 DB 쉔커를 인수함에 따라, 90개국 이상에서 사업을 전개하는 대규모 플랫폼이 구축되었습니다. 이는 시설 통합과 IT 통합을 통해 2028년까지 90억 덴마크 크로네(13억 달러)에 달하는 시너지 효과에 힘입은 것입니다. XPO는 북미 혼재 운송 네트워크에 대한 투자를 지속하며, 서비스 범위를 확대하고 서비스 수준을 향상시켰습니다. 이는 제조 거점 간 시간 지정 예비 부품 보충에 있어 중요한 요소입니다. 2026년, FDA는 ISO 13485 : 2016을 참조하는 품질 경영 시스템 규정을 최종 확정했습니다. 이로 인해 의료기기 물류 분야의 보관 및 서비스 제공 의무가 강화되었습니다. 이 지역의 구매 담당자들은 문서화된 품질 시스템, 감사 기록, 그리고 수리 가능한 부품 및 대여 장비를 위한 견고한 역물류 시스템을 중요하게 여깁니다. 예비 부품 및 물류 시장은 특수 품목에 대한 국경 간 대응 능력을 유지하면서, 재고를 소비지 가까이로 이동시킨 재구성된 네트워크의 혜택을 누리고 있습니다.
남미, 중동 및 아프리카가 나머지 시장 점유율을 차지하고 있으며, 예비 부품 물류 시장에서는 자동차, 에너지, 인프라 관련 프로그램과 연계된 선택적인 성장이 나타나고 있습니다. 아프리카의 광업 및 에너지 사업에서는 리드타임이 긴 특수 중장비 부품이 필요하며, 가동 시간을 확보하기 위해 사전에 배치된 위탁 재고나 예측 유지보수 프로그램이 중요시되고 있습니다. 만안 국가들은 첨단 제조 및 전력 프로젝트에 투자하고 있으며, 이는 엄격한 규정 준수 요건을 수반하는 안정적인 유지보수·수리·운영(MRO) 수요를 창출하고 있습니다. 남미에서는 사업자들이 지연 사태를 방지하고 관세 위험을 줄이기 위해 재고를 현지화하고 있으며, 이로 인해 해당 지역의 자동차 및 기계 차량에 대한 서비스 수준이 향상되고 있습니다. 프리존 라이선스를 취득하고 지역 허브를 구축한 공급업체는 리드 타임을 단축하고, 타사와의 차별화로 이어지는 신속한 대응을 약속함으로써 성공을 거둘 수 있습니다. 이러한 지역이 확대됨에 따라, 예비 부품 물류 시장에서는 세계 조달망과 규제 대상 품목에 대한 현지 주문 처리 및 규정 준수 능력을 겸비한 파트너가 주목받게 될 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.19According to Mordor Intelligence, the spare parts logistics market size is expected to grow from USD 49.22 billion in 2025 to USD 51.57 billion in 2026 and is forecast to reach USD 65.47 billion by 2031 at 4.89% CAGR over 2026-2031.
This report is Segmented by Service Type (Transportation, Warehousing & Distribution, and Value-Added Services), by Source Channel (OEM Channel, and Independent Aftermarket), by End-Use Industry (Automotive, Aerospace & Defense, and More), by Business Type (B2B, and B2C), and by Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD Billion).
Global Spare Parts Logistics Market Trends and Insights
Aging Industrial Equipment Base Requiring Frequent Replacements
Equipment owners are extending asset lifetimes, raising the priority on parts availability as breakdown risks increase with age. In this operating environment, a single missing component can stall production and ripple through downstream schedules and labor plans, which pushes buyers to value high fill rates and accurate lead times in the spare parts logistics market. Industrial teams are also deploying predictive maintenance to anticipate failures and shorten repair windows, which rewards providers able to pre-position critical SKUs. Digital twins that mirror installed configurations help forecast failure modes and align just-in-time replenishment with service-level targets, which stabilizes working capital for maintenance portfolios. As deferred capital expenditures persist in mature markets, the spare parts logistics market becomes central to uptime assurance programs adopted by manufacturers.
Shift from Product Sales to Service-Based Revenue Models
Service-based contracts that monetize the installed base are changing procurement decisions and the required capabilities of logistics partners in the spare parts logistics market. Connected equipment and service lifecycle management platforms now enable uptime guarantees, fixed-fee arrangements, and remote diagnostics that depend on predictable parts flows. Outcome-based agreements shift risk to providers that can price and deliver against promised service outcomes, which increases demand for tech-enabled logistics and compliant facilities in regulated categories. Vendors that can unify engineering data, inventory status, and field operations move beyond transactional shipping into integrated partnerships that lock in recurring services. As servitization spreads across regions and sectors, the spare parts logistics market rewards providers who can manage complex parts catalogs with real-time visibility and consistent quality.
Extreme SKU Proliferation Creating Inventory Management Complexity
SKU counts expand as equipment variants, materials, and regulatory requirements fragment product lines, which stresses planning systems and warehouse space in the spare parts logistics market. Many MRO parts remain unmoved for long periods, which ties up capital and discourages rationalization due to fear of stockout penalties. Returns add more complexity because e-commerce channels have higher return rates that require buffer stock and specialized processing. Plants that deploy AI-driven demand sensing and autonomous replenishment reduce emergency purchases and inventory costs by segmenting SKUs by criticality and failure risk. Tighter post-market surveillance and device-quality requirements also introduce tracking obligations in healthcare logistics that raise operational overhead for service providers.
Other drivers and restraints analyzed in the detailed report include:
- Equipment Downtime Cost Pressures Demanding Faster Delivery
- Complex Machinery Adoption in Emerging Manufacturing Hubs
- Long-Tail Inventory Holding Costs Eroding Profit Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transportation services secured 41.78% of 2025 revenue, while value-added services are advancing at a 6.32% annual rate that raises the sophistication threshold for the spare parts logistics market. Road networks support dense intra-regional replenishment, air freight handles urgent and high-value shipments, and ocean lanes position scheduled maintenance inventories. Rail adds intercontinental capacity, linking Asian hubs to European demand centers with predictable timetables. High-performance networks rely on asset control, as shown by XPO's continued North American LTL investments and service-center expansion that enhance network density and service quality. In healthcare and aerospace, temperature control, serialization, and compliant storage are table stakes that reward certified facilities aligned with the United States FDA's Quality Management System Regulation in 2026.
Value-added services, including vendor-managed inventory, kitting, and light assembly, are capturing a complexity premium in the spare parts logistics market. These services consolidate formerly separate steps into integrated workflows that improve speed and reduce touch points. Providers with customs brokerage and bonded facilities shorten cross-border lead times and reduce clearance risk on regulated items. The growing use of digital twins and connected service platforms supports accurate staging of parts at customer sites, which ties logistics outcomes to maintenance windows and uptime guarantees. Partnerships like CEVA and HAECO's global air-freight collaboration show the vertical depth now expected in aerospace spare parts, from aircraft-on-ground execution to temperature-managed components.
Geography Analysis
Asia-Pacific captured 38.21% of global revenue in 2025 and is set to grow at a 5.21% CAGR to 2031, supported by automotive, electronics, and aerospace value chains that require fast and compliant spare parts flows in the spare parts logistics market. China's automotive sector produced 34.531 million vehicles in 2025, including 16.626 million new-energy vehicles, with exports of 7.098 million units that extend warranty and service networks into destination markets. Regional manufacturing conditions tightened in early 2026, signaling busier supply chains and emerging bottlenecks that increase the value of guaranteed response and staging for critical SKUs. Logistics providers with certified temperature control, dangerous-goods compliance, and around-the-clock operations win higher-value aerospace and healthcare contracts. Network expansions also focus on integrated customs brokerage and bonded storage, which reduces clearance risk and stabilizes transit times across the spare parts logistics market.
North America and Europe jointly account for a significant share of activity, with demand anchored in aging industrial assets, electrification, and compliance-heavy medical channels in the spare parts logistics market. DSV's 2025 acquisition of DB Schenker created a larger platform with operations in more than 90 countries, supported by targeted synergies of DKK 9.0 billion (USD 1.3 billion) by 2028 from facility consolidation and IT integration. XPO continued to invest in its North American less-than-truckload network to expand coverage and improve service levels, which is relevant for time-definite spare parts replenishment across manufacturing corridors. In 2026, the FDA finalized its Quality Management System Regulation that references ISO 13485:2016, which heightens storage and servicing obligations in medical equipment logistics. Buyers in these regions value documented quality systems, audit trails, and robust reverse logistics for repairable components and loaner devices. The spare parts logistics market benefits from reconfigured networks that bring inventory closer to consumption while maintaining cross-border capabilities for specialized items.
South America, the Middle East, and Africa represent the remaining share and show selective growth tied to automotive, energy, and infrastructure programs in the spare parts logistics market. Mining and energy operations in Africa require specialized heavy components with long lead times, which favor pre-positioned consignment stock and predictive maintenance programs for uptime. Gulf economies invest in advanced manufacturing and power projects that generate steady maintenance, repair, and operations flows with tight compliance needs. In South America, operators localize inventories to avoid delays and reduce tariff exposure, which improves service levels for regional automotive and machinery fleets. Providers that secure free-zone licenses and establish regional hubs can shorten lead times and succeed on response commitments that differentiate offers. As these regions scale, the spare parts logistics market rewards partners that blend global procurement reach with local fulfillment and compliant handling for regulated categories.
- DHL Group
- Kuehne + Nagel International AG
- DSV A/S
- Expeditors International of Washington
- C.H. Robinson
- CEVA Logistics
- GEODIS
- XPO Logistics
- Ryder System Inc.
- Penske Logistics
- Hitachi Transport System
- Yusen Logistics (Part of NYK Line)
- Nippon Express
- Sinotrans
- TVS Supply Chain Solutions
- Choice Logistics
- AIT Worldwide Logistics
- Logwin AG
- Kerry Logistics Network Limited
- Hellmann Worldwide Logistics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Industrial Equipment Base Requiring Frequent Replacements
- 4.2.2 Shift from Product Sales to Service-Based Revenue Models
- 4.2.3 Equipment Downtime Cost Pressures Demanding Faster Delivery
- 4.2.4 Complex Machinery Adoption in Emerging Manufacturing Hubs
- 4.2.5 Growth of Multi-Brand Service Providers
- 4.2.6 Increasing Equipment Utilization Rates Accelerating Wear Cycles
- 4.3 Market Restraints
- 4.3.1 Extreme SKU Proliferation Creating Inventory Management Complexity
- 4.3.2 Long-Tail Inventory Holding Costs Eroding Profit Margins
- 4.3.3 Lack of Component Standardization Across Equipment Generations
- 4.3.4 High Return Rates and Complex Reverse Logistics
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Geo-Politics Events on the Market
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Service Type
- 5.1.1 Transportation
- 5.1.1.1 Road
- 5.1.1.2 Air
- 5.1.1.3 Sea
- 5.1.1.4 Rail
- 5.1.2 Warehousing & Distribution
- 5.1.3 Value-Added Services
- 5.1.1 Transportation
- 5.2 By Source Channel
- 5.2.1 OEM Channel
- 5.2.2 Independent Aftermarket (IAM)
- 5.3 By End-Use Industry
- 5.3.1 Automotive
- 5.3.2 Aerospace & Defense
- 5.3.3 Electronics & Semiconductors
- 5.3.4 Industrial Machinery & Heavy Equipment
- 5.3.5 Energy & Power
- 5.3.6 Healthcare Equipment
- 5.3.7 Maritime & Shipbuilding
- 5.3.8 Others
- 5.4 By Business Type
- 5.4.1 Business to Business (B2B)
- 5.4.2 Business to Consumer (B2C)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Asia-Pacific
- 5.5.3.1 India
- 5.5.3.2 China
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 Europe
- 5.5.4.1 United Kingdom
- 5.5.4.2 Germany
- 5.5.4.3 France
- 5.5.4.4 Spain
- 5.5.4.5 Italy
- 5.5.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.5.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.5.4.8 Rest of Europe
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab of Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East And Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 DHL Group
- 6.4.2 Kuehne + Nagel International AG
- 6.4.3 DSV A/S
- 6.4.4 Expeditors International of Washington
- 6.4.5 C.H. Robinson
- 6.4.6 CEVA Logistics
- 6.4.7 GEODIS
- 6.4.8 XPO Logistics
- 6.4.9 Ryder System Inc.
- 6.4.10 Penske Logistics
- 6.4.11 Hitachi Transport System
- 6.4.12 Yusen Logistics (Part of NYK Line)
- 6.4.13 Nippon Express
- 6.4.14 Sinotrans
- 6.4.15 TVS Supply Chain Solutions
- 6.4.16 Choice Logistics
- 6.4.17 AIT Worldwide Logistics
- 6.4.18 Logwin AG
- 6.4.19 Kerry Logistics Network Limited
- 6.4.20 Hellmann Worldwide Logistics