

|
시장보고서
상품코드
2062131
주조용 코크스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Foundry Coke - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
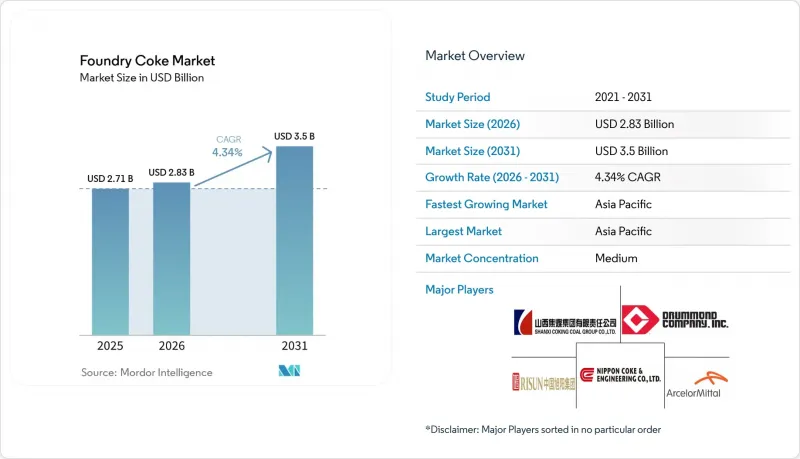
에 의하면, 주조용 코크스 시장 규모는 2025년에 27억 1,000만 달러로 평가되었고, 2026년 28억 3,000만 달러로 추정되고, 2031년까지 35억 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.34%를 나타낼 전망입니다.
본 보고서는 회분 함량별(8%-10%, 8% 미만, 10% 초과), 탄소 유형별(야금용 코크스, 석유 코크스 등), 최종 사용자 주조소 유형별(자동차용 주조소, 가공 주물, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제공됩니다.
세계의 주조용 코크스 시장 동향 및 분석
동남아시아 주조 클러스터의 확대
인도네시아, 베트남, 태국에서의 외국인 직접 투자 증가에 힘입어, 자체 코크스로를 가동하는 경제특구 내에서 니켈 제련, 스테인리스 스틸, 연성 주철용 큐폴라 공정이 통합되고 있습니다. 중부 술라웨시에 위치한 연간 320만 톤(Mtpa)의 생산 능력을 갖춘 모로와리 산업단지는 17개국에 걸친 51개 고객사에 제품을 공급하고 있으며, CBAM(탄소국경조정메커니즘) 방식의 탄소 추가 요금을 회피하고, 기존 무역사 계열 공급업체를 능가하는 물류 비용 절감을 실현하는 자급자족 모델을 구현하고 있습니다. 활발한 인프라 투자와 배터리 공급망의 현지화 덕분에 향후 수년간 수요 전망이 유지되고 있으며, 동남아시아는 주조용 코크스 시장 전체에서 가장 빠르게 성장하는 지역으로 자리매김하고 있습니다.
경량화를 위한 고강도 박판 주물에 대한 투자
연비 및 배기가스 관련 자동차 규제로 인해, 주조 업체들은 두께 3-5mm의 박판 연성 주철 및 치밀 흑연 주철로 전환해야 하는 상황에 직면해 있습니다. 이러한 주조품의 경우, 슬래그를 억제하고 엄격한 치수 공차를 유지하기 위해 높은 기계적 강도(M40 75% 이상)를 갖추고 회분 함량이 낮은(8% 미만) 프리미엄 코크스가 필요합니다. 스코프 3 보고에 이르기까지 포괄하는 OEM 감사를 통해, 현재는 일관된 저회분 성분과 배치별 완벽한 추적성을 보장하는 공급 계약이 권장되고 있습니다. 고품질 코크스를 확보하지 못하는 파운드리은 스크랩률 상승에 직면하거나, 고황 함량의 석유 코크스나 무연탄을 혼합할 수밖에 없게 되며, 이로 인해 용해 시 화학 성분 관리가 복잡해집니다.
변동이 심한 프리미엄 저황 코크스용 석탄 가격
호주의 사이클론으로 인한 혼란에 따라 피치는 2026년 프리미엄 석탄 가격 전망치를 톤당 190달러로 상향 조정했으나, 2025년 FOB(선적지 인도) 가격은 이미 전년 대비 21% 하락하여 생산자들의 이익률을 압박하고 있습니다. 자사 광산을 보유하지 않은 코크스 제조업체들은 마진 축소에 직면해 있으며, 주조 업체들은 6-12개월이라는 짧은 견적 기간에 얽매여 있어 장기적인 수주 계획 수립이 복잡해지고, 수요 안정을 뒷받침할 용광로 업그레이드 결정이 지연되고 있습니다.
부문별 분석
저회분(8% 미만) 등급은 슬래그 관련 결함을 줄이고, 라이닝의 수명을 연장하는 것으로, 2031년까지의 연평균 성장률(CAGR)은 4.77%로, 2025년 주조용 코크스 시장 점유율의 49.98%를 차지했으며, 8-10% 성장에 그치는 주류 부문을 상회하고 있습니다. 2025년 12월에 가동을 시작한 AM/NS India의 연간 생산량 150만 톤 규모의 하지라 배터리 공장은 자사 전용 고품질 원료 공급을 확보함으로써 현물 수입에 대한 의존도를 낮출 것입니다. 서유럽 및 북미의 자동차용 파운드리에서는 Scope 3 공개 규정을 충족하기 위해 저회분 계약이 의무화되어 있으며, 회분 7% 미만, 황분 0.8% 미만을 증명하는 인증서가 첨부된 배치에 대한 수요가 증가하고 있습니다.
중급 제품(회분 8-10%)인 코크스는 건설 기계 및 유틸리티용 주물 분야에서 여전히 주류를 이루는 대량 수요 품목입니다. 러시아의 GOST 3340-88 규격에서는 회분 함량을 11-12%로 제한하고 있지만, 이를 9%로 개선함으로써 중국과 인도네시아의 수출업체들은 프리미엄 등급의 전체 비용을 부담하지 않고도 EU 기준에 근접할 수 있게 됩니다. 프리미엄 코크스와 표준 코크스를 혼합하는 것은 용해 비용을 늘리지 않으면서 OEM의 감사 요건을 충족하기 위한 전략으로 점점 더 보편화되고 있으며, 이로 인해 중급 등급공급은 다음 투자 주기에서도 그 중요성을 유지하게 될 것입니다.
지역별 분석
아시아태평양은 2025년에 전 세계 소비량의 57.91%를 차지한 것으로 평가되었으며, 예측 기간(2026-2031년) 동안 연평균 성장률(CAGR) 5.08%로 성장할 것으로 전망됩니다. 이는 지역별로는 가장 빠른 성장세이며, 2024-2027년 계획된 7,000만 톤 이상의 고로 철강 생산 능력 확충에 힘입은 결과입니다. 인도네시아의 모로와리 클러스터는 인도 및 일본으로의 수출 거점 역할을 하고 있는 반면, 베트남 하이퐁 및 태국 촌부리 회랑에서는 상수도 인프라와 자동차 부품을 공급하는 국내 큐폴라 용광로를 위해 전용 코크스로가 추가되었습니다. 인도가 2024년 12월 저회분 코크스에 대한 수입 할당량을 강화함에 따라 공급이 부족해지자, 통합 제조업체들은 자급자족 프로젝트를 가속화했습니다. 이 정책은 역설적이긴 하지만, 국내 코크스용 석탄 세척에 대한 투자를 촉진하고 있습니다.
북미에서는 미국 에너지부(DOE)의 자금 지원을 받은 고로 전환이 본격화되기 시작하면서, 절대 톤수 기준으로 감소 추세를 보이고 있습니다. SunCoke의 국내 판매량은 2025년에 36만 톤 감소할 전망이며, 2026년에도 감소세가 이어질 것으로 예상되지만, 미국·멕시코·캐나다 협정(USMCA)에 기반한 국경 간 공급망은 여전히 자동차 및 농업용 주철(회주철)용 중급 코크스를 흡수하고 있습니다. 섹션 45X의 청정 제조 세액 공제 제도의 보급 정도가, 큐폴라 용광로의 폐지가 수자원 인프라라는 틈새 시장을 넘어 더 널리 확산될지 여부를 결정짓게 될 것입니다.
유럽에서는 총 수요량이 감소하고 있음에도 불구하고, CBAM(국경 탄소 조정 메커니즘)에 따른 비용 부담이 저회분 코크스 수요를 끌어올리고 있습니다. 생고뱅 PAM의 프랑스 공장에서는 유도 용해 방식으로의 전환을 통해 이산화탄소 배출량을 95% 감축하고, 연간 7,800톤의 석탄 사용량을 줄인 것이 입증되어, 다른 EU 주조소들에게 규정 준수 분야의 벤치마크가 되고 있습니다. 동유럽의 사업자들은 여전히 큐폴라로를 사용하고 있지만, 배출 계수를 문서화해야 하기 때문에 회분 함량이 10% 미만인 제품을 인증할 수 있는 중국이나 인도네시아공급업체로부터 완전한 추적성을 갖춘 건식 소성 코크스에 대한 수요가 증가하고 있습니다.
남미는 여전히 경기 순환의 영향을 받기 쉬운 상황입니다. 브라질은 광업 부문의 설비 투자와 현지 주조품 조달을 촉진하는 헤알화 약세의 혜택을 누리고 있지만, 높은 차입 비용이 생산 능력 확대를 제한하고 있습니다. 아르헨티나와 안데스 지역 국가들은 지자체 및 광업용 주물 제품을 위해 현물 거래로 코크스를 구매하고 있으며, 이 지역은 비용에 민감하여 저회분 프리미엄 계약 도입에 소극적인 태도를 보이고 있습니다.
중동 및 아프리카에서는 사우디아라비아의 금속 산업 다각화와 남아프리카공화국의 광산기계 수출에 수요가 집중되고 있습니다. 최종 사용자들은 주로 인도와 중국에서 코크스를 수입하고 있지만, 물류 병목 현상과 자금 조달 제약으로 인해 고품질의 저회분 코크스 도입은 제한적입니다. 명확한 탄소 가격 책정이나 스코프 3 규제가 없기 때문에 코크스 품질에 관한 결정은 지속가능성 목표가 아닌 고로 수율이라는 경제적 요인에 의해 계속해서 좌우되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.06.22According to Mordor Intelligence, the foundry coke market size was valued at USD 2.71 billion in 2025 and is estimated to grow from USD 2.83 billion in 2026 to reach USD 3.5 billion by 2031, at a CAGR of 4.34% during the forecast period (2026-2031).
This report is Segmented by Ash Content (8%-10% Ash Content, Less Than 8% Ash Content, and More Than 10% Ash Content), Carbon Type (Metallurgical Coke, Petroleum Coke, and More), End-User Foundry Type (Automotive Foundries, Fabricated Castings, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Foundry Coke Market Trends and Insights
Expansion of Southeast-Asian Foundry Clusters
Rising foreign direct investment in Indonesia, Vietnam, and Thailand is integrating nickel smelting, stainless steel, and ductile-iron cupolas inside special-economic zones that run their own coke ovens. The 3.2 million tonnes per annum (Mtpa) Morowali Industrial Park in Central Sulawesi supplies 51 customers across 17 countries, showcasing a self-sufficient model that bypasses CBAM-type carbon surcharges and achieves logistics savings that out-compete traditional merchant suppliers. Buoyant infrastructure expenditure and battery-supply-chain localization sustain multi-year demand visibility, establishing Southeast Asia as the fastest-growing pocket within the broader foundry coke market.
Investments in High-Strength Thin-Wall Castings for Lightweighting
Automotive regulations on fuel economy and emissions are pushing foundries toward 3-5 mm thin-wall ductile-iron and compacted-graphite-iron castings. These castings require premium low-ash coke (less than 8%) with high mechanical strength (M40 greater than or equal to 75%) to limit slag and maintain tight dimensional tolerances. OEM audits that extend to Scope 3 reporting now incentivize supply contracts that guarantee consistent low-ash chemistry and full batch traceability. Foundries unable to secure quality coke face higher scrap rates or must blend higher-sulfur petroleum coke and anthracite, which complicates melt chemistry control.
Volatile Premium Low-Sulfur Coking-Coal Pricing
Australian cyclone disruptions lifted Fitch's 2026 premium coal forecast to USD 190/ton, but 2025 Free On Board (FOB) prices had already fallen 21% year-on-year, undercutting producer margins. Coke makers lacking captive mines face squeezed spreads, and foundries endure quotation windows of only 6-12 months, complicating long-range order books and delaying furnace-upgrade decisions that underpin demand stability.
Other drivers and restraints analyzed in the detailed report include:
- Recovery of Construction-Equipment Output in India and Brazil
- Renewable-Energy Stimulus Driving Wind-Turbine Gearbox Castings
- Cupola-to-Electric-Melt Migration at Large U.S. Foundries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Low-ash (less than 8%) grades cut slag-related defects, extend lining life, and demonstrate a 4.77% CAGR through 2031, outstripping the 8-10% mainstream segment that nonetheless held 49.98% of the 2025 foundry coke market share. AM/NS India's 1.5 Mtpa Hazira battery, commissioned in December 2025, secures captive premium supply and reduces reliance on spot imports. Western European and North American automotive foundries now mandate low-ash contracts to meet Scope 3 disclosure rules, pushing demand for documented batches with ash below 7% and sulfur under 0.8 %.
Mid-grade 8-10% coke remains the volume workhorse for construction-equipment and municipal castings. Russian GOST 3340-88 limits ash at 11-12%; upgrading to 9% ash allows Chinese and Indonesian exporters to approach EU benchmarks without full premium-grade costs. Blending premium and standard coke is an increasingly common strategy to meet OEM audits without inflating melt costs, preserving the relevance of mid-grade supply for another investment cycle.
Geography Analysis
Asia-Pacific held 57.91% of global consumption in 2025 and is projected to advance at 5.08% CAGR during the forecast period (2026-2031), the fastest regional pace, underpinned by more than 70 million tons of new blast-furnace iron capacity scheduled between 2024 and 2027. Indonesia's Morowali cluster anchors exports to India and Japan, while Vietnam's Haiphong and Thailand's Chonburi corridors add captive coke ovens for domestic cupolas that supply water-infrastructure and automotive parts. India's December 2024 import quota on low-ash coke tightened supply and prompted integrated producers to accelerate self-sufficiency projects, a policy that paradoxically stimulates domestic coking-coal washing investments.
North America is contracting in absolute tonnage as the Department of Energy (DOE)-funded furnace switches begin to bite. SunCoke's domestic offtake fell 360,000 tons in 2025 and is guided lower for 2026, though cross-border supply chains under the United States-Mexico-Canada Agreement (USMCA) still absorb mid-grade coke for gray-iron auto and agricultural castings. Broader uptake of Section 45X clean-manufacturing tax credits will decide whether cupola retirements proceed beyond the water-infrastructure niche.
Europe faces CBAM costs that elevate low-ash coke demand even as total volume shrinks. Saint-Gobain PAM's French plant documented a 95% CO2 cut after switching to induction melting, eliminating 7,800 tons/year of coal and setting a compliance benchmark for other EU foundries. Eastern European operators remain on cupolas but must document emission factors, boosting demand for dry-quenched coke with full traceability from Chinese or Indonesian suppliers able to certify sub-10% ash lots.
South America remains cyclical. Brazil benefits from mining-sector capex and a weak real that encourages local casting procurement, yet high borrowing costs limit capacity build-outs. Argentina and the Andean nations purchase coke on a spot basis for municipal and mining castings, rendering the region cost-sensitive and slow to adopt premium low-ash contracts.
Middle East and Africa shows scattered demand concentrated in Saudi Arabia's metals diversification and South Africa's mining-machinery exports. End-users import coke primarily from India and China, with logistics bottlenecks and financing constraints capping uptake of premium low-ash material. Without explicit carbon-pricing or Scope 3 mandates, coke quality decisions remain dictated by furnace yield economics rather than sustainability targets.
- ArcelorMittal
- China Risun Group Limited
- Drummond Company, Inc.
- Hebei Xinzheng Coking
- Henan Shenhuo Coke
- Jindal Coke Limited
- METALIMEX a. s.
- NIPPON COKE & ENGINEERING CO., LTD.
- POSCO
- Sesa Goa Iron Ore
- Shanxi Blue Flame Holding Co Ltd
- Shanxi Coking Co. Ltd.
- Shanxi Jianlong Coking Group
- SunCoke Energy Inc.
- Tata Steel
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Southeast-Asian foundry clusters
- 4.2.2 Investments in high-strength thin-wall castings for lightweighting
- 4.2.3 Recovery of construction-equipment output in India and Brazil
- 4.2.4 Renewable-energy stimulus driving wind-turbine gearbox castings
- 4.2.5 OEM Scope-3 decarbonization accelerating low-ash (less than 8%) coke contracts
- 4.3 Market Restraints
- 4.3.1 Volatile premium low-sulfur coking-coal index pricing
- 4.3.2 Cupola-to-electric-melt migration at large U.S. foundries
- 4.3.3 EU CBAM carbon surcharges on coke-fired cupolas
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Ash Content
- 5.1.1 8%-10% Ash Content
- 5.1.2 Less than 8% Ash Content
- 5.1.3 More than 10% Ash Content
- 5.2 By Carbon Type
- 5.2.1 Metallurgical Coke
- 5.2.2 Petroleum Coke
- 5.2.3 Pitch Coke
- 5.2.4 Anthracite Coke
- 5.2.5 Others
- 5.3 By End-user Foundry Type
- 5.3.1 Automotive Foundries
- 5.3.2 Fabricated Castings (Pumps, Valves, and Motors)
- 5.3.3 Machine and Tool Manufacturing
- 5.3.4 Aerospace and Heavy Equipment
- 5.3.5 Other Industrial Foundries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ArcelorMittal
- 6.4.2 China Risun Group Limited
- 6.4.3 Drummond Company, Inc.
- 6.4.4 Hebei Xinzheng Coking
- 6.4.5 Henan Shenhuo Coke
- 6.4.6 Jindal Coke Limited
- 6.4.7 METALIMEX a. s.
- 6.4.8 NIPPON COKE & ENGINEERING CO., LTD.
- 6.4.9 POSCO
- 6.4.10 Sesa Goa Iron Ore
- 6.4.11 Shanxi Blue Flame Holding Co Ltd
- 6.4.12 Shanxi Coking Co. Ltd.
- 6.4.13 Shanxi Jianlong Coking Group
- 6.4.14 SunCoke Energy Inc.
- 6.4.15 Tata Steel
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


