

|
시장보고서
상품코드
2063365
자동차 스타트 스톱 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Start-Stop System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
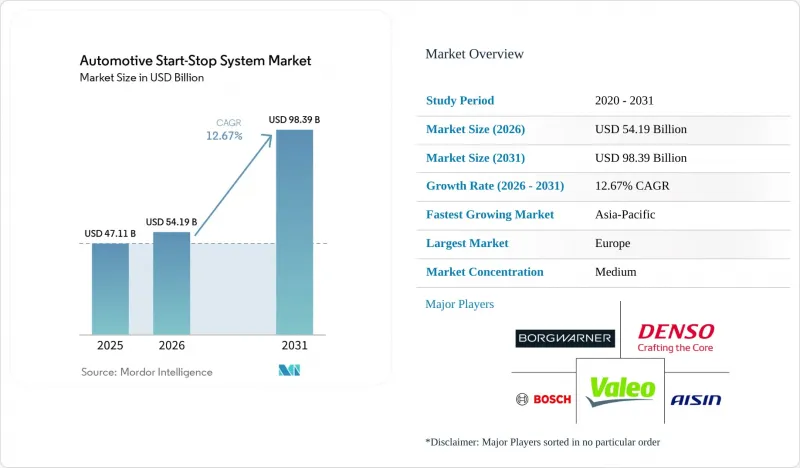
에 의하면, 자동차 스타트 스톱 시스템 시장 규모는 2025년 471억 1,000만 달러로 평가되었습니다. 2026년 541억 9,000만 달러에서 2031년까지 983억 9,000만 달러로 확대되어 2026-2031년까지 연평균 복합 성장률(CAGR)은 12.67%를 나타낼 것으로 예측됩니다.
본 보고서는 차종(승용차, 소형 상용차, 대형 상용차, 기타), 기술(벨트 구동식 알터네이터 스타터, 통합형 스타터 제너레이터, 직접 스타터), 구성품(배터리, 스타터 모터, 알터네이터, 기타), 연료 유형별(가솔린, 대체 연료, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 자동차 스타트 스톱 시스템 시장 동향 및 분석
기업 평균 연비(CAFE) 및 CO2 규제 강화
규제 강화는 자동차용 스타트 스톱 시스템 시장의 확대에 있어 여전히 가장 강력한 원동력으로 작용하고 있습니다. 미국에서는 2031년 모델 연도까지 갤런당 50.4마일에 달하는 기업 평균 연비 목표가 확정되었으며, 규제 위반에 대한 벌칙은 OEM의 제품 계획 예산을 비용 대비 효과가 높은 공회전 저감 기술로 전환시키기에 충분한 수준으로 설정되어 있습니다. 개정된 유럽 승용 밴용 CO₂ 배출 성능 기준에 따르면, 2030년부터 2034년까지 차량군 배출량을 55% 감축해야 하며, 배터리식 전기차공급량이 계획치를 밑돌 경우 규정을 준수하기 위한 대책으로서 마이크로 하이브리드에 대한 수요가 확고해지고 있습니다. 인도나 브라질에서도 이와 유사한 규제 강화 조치가 나타나고 있으며, 향후 5년간의 제품 수명 주기 동안 인증 획득 여부가 이 기술의 도입 여부를 좌우하게 될 것입니다. 이러한 중복된 규제는 종합적으로 볼 때, 장기적인 보급을 뒷받침하는 지속 가능한 규정 준수의 최소 기준을 제공합니다.
48V 마일드 하이브리드 아키텍처의 OEM 도입
자동차 제조업체들은 12V 벨트 스타터 방식에서 회생 제동 및 토크 어시스트를 가능하게 하는 48V 통합형 스타터 제너레이터(ISG) 토폴로지로 전환하고 있습니다. MAHLE의 48V 벨트 스타터 제너레이터는 최대 15kW의 회생 전력을 공급하여, 도심 주행 시 12-15%의 연료 절감 효과를 실현합니다. STMicroelectronics와 온세미의 실리콘 카바이드 파워 디바이스는 변환 손실을 30% 줄여, 각 OEM 업체들이 엔진룸 내의 패키지를 소형화할 수 있도록 하고 있습니다. 이러한 장점 외에도 리튬 이온 배터리 가격 하락이 더해지면서, 48V 시스템은 완전한 BEV(배터리 전기자동차)의 비용이나 충전 인프라의 위험을 감수하지 않고도, 향후 전기화를 위한 주요 가교 역할을 하고 있습니다.
전기차 보급 가속화가 장비 시장을 잠식하고 있습니다.
BEV의 보급률 상승은 스타트 스톱 시스템의 대상 시장을 직접적으로 축소시킵니다. 2025년, 중국의 신에너지차(NEV)는 신규 자동차 등록 대수의 44.97%를 차지했으며, 그중 BEV가 약 70%를 차지했습니다. 하버드 비즈니스 스쿨의 조사에 따르면, 연료 가격이 높고 충전 인프라가 잘 갖춰진 시장에서는 BEV의 총 소유 비용이 내연기관 차량과 대등해짐에 따라 스타트 스톱 시스템의 사업적 타당성이 약해집니다. 프리미엄 부문이 가장 먼저 전환됨에 따라, 12볼트 시스템의 판매 대수는 감소할 것입니다. 신흥국과 상용차 차량군이 그 영향을 완화하고 있는 반면, BEV의 성장은 여전히 가장 큰 구조적 역풍으로 작용하고 있습니다.
부문별 분석
2025년에는 전 세계 경차 플랫폼의 상당수가 차량 함대 목표를 달성하기 위해 공회전 감축을 표준화함에 따라, 승용차용 스타트 스톱 시스템 시장이 62.14%의 점유율을 차지하며 시장을 독점했습니다. 인도나 동남아시아의 도시 지역 운전자들은 정지-출발이 반복되는 교통 상황으로 인해 장시간 정차하는 경우가 많기 때문에 출발-정지 기능을 통해 연료를 절약하는 효과를 즉시 실감할 수 있습니다. 또한, 유럽과 북미의 차량 대여 업체들은 불필요한 공회전을 줄이기 위해 소형 밴에도 이 기술을 도입하고 있습니다. 대형 트럭은 토크나 부속 장비 부하 측면에서 뒤처지고 있지만, 쓰레기 수거차와 같은 틈새 시장에서는 점차 도입이 확대되고 있습니다.
이륜차는 가장 빠르게 성장하고 있는 부문으로, 2031년까지 연평균 성장률(CAGR) 14.61%를 나타낼 것으로 예측되며, 자동차용 스타트 스톱 시스템 시장을 재편하고 있습니다. 혼다의 ‘공회전 정지 시스템’은 스쿠터를 0.5초 만에 재시동시켜, 가격에 민감한 통근자들에게 두 자릿수의 연비 절감 효과를 제공하여 호평을 받고 있습니다. TVS 모터스는 자사의 ‘intelliGO’ 스타터를 통해 이러한 접근 방식을 재현하며, 프리미엄 오토바이에 그치지 않고 대중용 도시형 스쿠터로의 보급을 추진하고 있습니다. 헬멧 착용법 시행 강화와 마이크로모빌리티에 대한 수요 증가로 인해, 연비 효율과 저배기가스를 중시하는 도시 지역 라이더층이 더욱 확대되고 있습니다. 인도, 인도네시아, 베트남에서 이륜차 생산 대수가 증가함에 따라, 시스템 총 출하량에서 이륜차가 차지하는 비중은 꾸준히 상승할 것으로 보입니다.
벨트 구동식 알터네이터 스타터는 200-300달러라는 저렴한 부품 원가에 힘입어, 2025년 자동차용 스타트 스톱 시스템 시장에서 38.42%라는 견실한 점유율을 차지했습니다. 이는 특히 12볼트 전기 아키텍처가 유지되고 있는 부문에서 엔트리급 마이크로 하이브리드 차량의 주력 모델로 계속해서 자리매김할 것으로 보입니다. 그러나 각 OEM 업체들이 프리미엄 모델은 물론, 궁극적으로는 양산 모델에 이르기까지 48볼트 플랫폼을 확대해 나감에 따라, 통합형 스타터-제너레이터 유닛 시장은 두 자릿수 성장이 예상됩니다. 이러한 전환을 통해 회생 에너지, 전동 토크 보강, 더욱 부드러운 재시동이 가능해집니다.
통합형 스타터 제너레이터는 연평균 성장률(CAGR) 16.13%를 나타낼 것으로 예측되며, 우선 유럽과 중국에서 시장 점유율을 확보한 뒤 북미로 시장을 확대해 나갈 것으로 보입니다. 발레오(Valeo)사의 양산형 48V 시스템은 15kW의 회생 제동 능력을 갖추고 있으며, 이는 보조 컴프레서를 구동하기에 충분한 출력으로, 소형 3기통 엔진이 마치 더 큰 4기통 엔진과 같은 주행 성능을 발휘하는 것처럼 느껴지게 하는 데 도움이 됩니다. 반도체의 발전, 특히 인피니온(Infineon)사의 750V 실리콘 카바이드 MOSFET은 열 손실을 대폭 줄이고 컨버터의 소형화를 가능하게 함으로써, 소형 세단에 탑재할 수 있게 해주고 있습니다. 직접 스타터 솔루션은 가격이 저렴하지만, 이러한 기능적 장점이 부족하기 때문에 단종 직전의 플랫폼이나 규제가 완화된 시장에 한정되는 경향이 강해지고 있습니다.
지역별 분석
2025년, 유럽은 전 세계 자동차용 스타트 스톱 시스템 시장의 35.17%를 차지하며 지역 시장에서 주도적인 입지를 확고히 다졌습니다. 이러한 우위는 EU의 엄격한 CO2 배출 규제, 적극적인 차량 연비 효율화 의무화, 승용차에 대한 48V 마일드 하이브리드 아키텍처의 광범위한 도입에 기인합니다. 배터리식 전기자동차의 급속한 부상에도 불구하고, 스타트 스톱 시스템은 내연기관 차량 및 하이브리드 차량 플랫폼에서 여전히 널리 보급되어 있으며, 비용 대비 효과가 높은 규제 대응 솔루션으로 기능하고 있습니다. 또한, 독일과 프랑스, 그 밖의 자동차 산업 거점에 구축된 견고한 1차 공급업체 생태계가 시스템 통합 역량을 강화하고, 애프터마켓의 활발한 수요를 뒷받침하고 있습니다.
북미는 자동차용 스타트 스톱 시스템에 있어 매우 중요한 시장이며, 연비 기준의 강화와 소형 트럭, SUV, 상용차 차량군에 대한 도입 확대에 힘입어 성장하고 있습니다. 미국에서는 역사적으로 연료 가격이 낮았기 때문에 유럽에 비해 도입 속도가 더뎠으나, 규제 압력이 높아짐에 따라 현재는 OEM 플랫폼 전반에 걸쳐 도입이 가속화되고 있습니다. 또한, 해당 지역에서 마일드 하이브리드 파워트레인으로의 점진적인 전환이 수요를 확대시키고 있으며, 특히 차세대 픽업트럭 및 SUV 모델에서 이러한 현상이 두드러집니다.
급속한 도시화와 연료비 급등이 특징인 아시아태평양에서는 자동차용 스타트 스톱 시스템 수요가 급증하고 있습니다. 중국, 인도, 일본, 동남아시아 각국에서는 배기가스 규제가 강화되고 있어, 이러한 추세를 더욱 뒷받침하고 있습니다. 해당 지역에서 소형차 및 보급형 차량의 대량 생산에 따라, 연비 향상을 위한 비용 대비 효과가 높은 해결책으로서 스타트 스톱 시스템의 보급이 확대되고 있습니다. 또한, 배터리 및 시동 모터 제조의 현지화가 진행됨에 따라 가격이 저렴해지면서 대중차 부문으로의 보급이 더욱 확대되고 있습니다.
또한, 남미와 중동 및 아프리카는 규모는 작지만 자동차용 스타트 스톱 시스템의 신흥 시장을 형성하고 있습니다. 브라질, 사우디아라비아, 남아프리카공화국 등에서는 연비 효율을 중시하고, 규제를 강화하며, 차량의 현대화를 추진하고 있습니다. 그러나 경제 변동, 가혹한 운용 환경, 제한된 전동화 인프라 등의 요인으로 인해 도입은 여전히 제약을 받고 있으며, 꾸준한 수요 증가가 있음에도 불구하고 이러한 요인들이 복합적으로 작용하여 대규모 보급 속도는 둔화되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.24According to Mordor Intelligence, the automotive start-Stop system market size is projected to expand from USD 47.11 billion in 2025 and USD 54.19 billion in 2026 to USD 98.39 billion by 2031, registering a CAGR of 12.67% between 2026 to 2031.
This report is Segmented by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, and More), Technology (Belt-Driven Alternator Starter, Integrated Starter Generator, and Direct Starter), Component (Battery, Starter Motor, Alternator, and More), Fuel Type (Gasoline, Alternative Fuels, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Start-Stop System Market Trends and Insights
Heightened Corporate Average Fuel Economy and CO2 Regulations
Regulatory stringency remains the single most potent lever for expansion in the automotive start-stop system market. The United States finalized corporate average fuel-economy targets that climb toward 50.4 miles per gallon by model year 2031, and penalties for non-compliance are set high enough to shift OEM product-planning budgets toward cost-effective idle-reduction content. Europe's revised passenger-van CO2 performance standards require a 55% drop in fleet emissions by 2030 to 2034, cementing micro-hybrid demand as a compliance backstop when battery-electric deliveries miss plan. Similar tightening is visible in India and Brazil, binding the technology to certification success in the next five-year product cycle. Collectively, these overlapping mandates provide an enduring compliance floor that supports long-run adoption.
OEM Integration of 48-Volt Mild-Hybrid Architectures
Automakers are migrating from 12-volt belt-starter packages to 48-volt integrated starter-generator (ISG) topologies that unlock regenerative braking and torque assist. MAHLE's 48-volt belt-starter-generator delivers up to 15 kW of recuperation, saving 12-15% fuel in urban cycles.Silicon-carbide power devices from STMicroelectronics and onsemi are cutting conversion losses by 30%, letting OEMs shrink under-hood packaging. These gains, matched with falling lithium-ion prices, make 48-volt the dominant bridge toward deeper electrification without incurring full BEV cost or charging-infrastructure risk.
Accelerated Adoption of Battery-Electric Vehicles Cannibalizing Fitment
Rising BEV penetration directly shrinks the addressable pool for start-stop hardware. China's new-energy vehicles accounted for 44.97% of all new automobile registrations in 2025, with BEVs forming about 70% of that mix. Harvard Business School research shows that the start-stop business case weakens as BEV total cost of ownership approaches parity with internal-combustion vehicles in markets with high fuel prices and dense charging grids. Premium segments convert first, chopping volume for 12-volt systems. While emerging economies and commercial fleets temper the impact, BEV growth remains the single largest structural headwind.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Micro-Hybrid Passenger Cars in Emerging Economies
- Continuous Decline in Lithium-Ion Battery USD Per kWh Enhancing Durability
- Driver Discomfort from NVH During Heavy Stop-Start Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The automotive start-stop system market for passenger cars dominated in 2025, with a 62.14% share, as most global light-vehicle platforms standardized on idle-reduction to meet fleet targets. Urban motorists in India and Southeast Asia spend long stretches in stop-and-go traffic, making fuel savings from start-stop immediately tangible. Fleet operators in Europe and North America also add the technology to light vans to curb discretionary idling. Though heavy trucks lag in torque and accessory loads, niche applications such as refuse trucks are slowly adopting them.
Two-wheelers represent the fastest-growing segment, forecast to grow at a 14.61% CAGR through 2031, and are reshaping the automotive start-stop system market. Honda's Idling Stop System restarts a scooter in 0.5 seconds, delivering double-digit fuel savings that resonate with price-sensitive commuters. TVS Motor has replicated the approach with its intelliGO starter, pushing penetration beyond premium bikes into mass-market city runabouts. Rising helmet-law enforcement and growing micro-mobility appetites further enlarge the pool of urban riders that value efficiency and low tail-pipe emissions. As two-wheeler output expands in India, Indonesia, and Vietnam, their share of overall system shipments will rise steadily.
Belt-driven alternator starters enjoyed a robust 38.42% share of the automotive start-stop system market in 2025, driven by their favorable USD 200-300 bill-of-materials cost. It will continue to anchor entry-level micro-hybrids, particularly where 12-volt electrical architecture remains in place. Yet integrated starter-generator units are poised for double-digit growth as OEMs roll out 48-volt platforms across premium and, eventually, volume models. The switch unlocks energy recuperation, electric torque fill, and smoother restarts.
The integrated starter generator is set to post an 16.13% CAGR, capturing share in Europe and China first, then in North America. Valeo's high-volume 48-volt program offers 15 kW recuperation, enough to power auxiliary compressors and let a small three-cylinder engine feel like a larger four-cylinder. Semiconductor advances, especially 750 V silicon-carbide MOSFETs from Infineon, are slashing thermal losses and enabling smaller converters, enabling packaging in compact sedans. Direct-starter solutions, though cheaper, lack these functional wins and are increasingly relegated to late-life platforms or markets with lenient standards.
Geography Analysis
In 2025, Europe secured 35.17% of the global automotive start-stop system market, solidifying its position as the leading regional market. This dominance stems from stringent EU CO2 emission regulations, aggressive fleet efficiency mandates, and the widespread adoption of 48-volt mild-hybrid architectures in passenger vehicles. Even with the swift rise of battery-electric vehicles, start-stop systems remain prevalent on internal combustion and hybrid platforms, serving as a cost-effective compliance solution. Moreover, a robust Tier-1 supplier ecosystem in Germany, France, and other automotive hubs bolsters system integration capabilities and fuels strong aftermarket demand.
North America is a pivotal market for automotive start-stop systems, buoyed by tightening fuel-economy standards and their growing presence in light trucks, SUVs, and commercial fleets. Although historically lower fuel prices in the U.S. have tempered adoption rates compared to Europe, mounting regulatory pressures are now hastening their integration across OEM platforms. Additionally, the region's gradual pivot towards mild-hybrid powertrains is amplifying demand, especially in next-gen pickup and SUV models.
The Asia-Pacific region, marked by rapid urbanization and rising fuel costs, is witnessing a surge in demand for automotive start-stop systems. Countries like China, India, Japan, and those in Southeast Asia are tightening emissions regulations, further driving this trend. The region's large-scale production of compact and entry-level vehicles has led to widespread use of start-stop systems as a cost-effective solution for improving fuel efficiency. Furthermore, the increasing localization of battery and starter motor manufacturing is enhancing affordability, pushing deeper penetration into mass-market vehicle segments.
Furthermore, South America, the Middle East, and Africa form a smaller yet emerging market for automotive start-stop systems. Countries like Brazil, Saudi Arabia, and South Africa are emphasizing fuel efficiency, tightening regulations, and modernizing fleets. However, adoption remains constrained by economic volatility, harsh operating environments, and limited electrification infrastructure, which collectively slow large-scale penetration despite steady incremental demand.
- Aisin Corporation
- BorgWarner Inc.
- Continental AG
- DENSO Corporation
- Valeo SA
- Robert Bosch GmbH
- Hitachi Astemo Ltd.
- HELLA GmbH & Co. KGaA
- Johnson Controls International plc
- Mitsubishi Electric Corporation
- SEG Automotive Germany GmbH
- Marelli Holdings Co., Ltd.
- Schaeffler AG
- Panasonic Holdings Corporation (Automotive Systems)
- Calsonic Kansei Corporation
- Clarios, LLC
- Exide Technologies, LLC
- Furukawa Electric Co., Ltd.
- Prestolite Electric Incorporated
- Mando Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Heightened Corporate Average Fuel Economy (CAFE) and CO2 Regulations
- 4.2.2 Rising Demand for Micro-Hybrid Passenger Cars in Emerging Economies
- 4.2.3 OEM Integration of 48-V Mild-Hybrid Architectures
- 4.2.4 Continuous Decline in Lithium-Ion Battery USD/kWh Enhancing Durability
- 4.2.5 Adoption of Edge-AI Idle Prediction Algorithms to Minimize Restart Lag
- 4.2.6 Insurance Telematics Incentives Favoring Idle-Reduction Technologies
- 4.3 Market Restraints
- 4.3.1 Accelerated Adoption of Battery-Electric Vehicles Cannibalizing Fitment
- 4.3.2 Driver Discomfort From NVH During Heavy Stop-Start Cycles
- 4.3.3 Transition to Solid-State 12-V Batteries Necessitating Redesigns
- 4.3.4 Supply-Chain Fragility for Power MOSFETs and Relays
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors on the Market
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Light Commercial Vehicles
- 5.1.3 Heavy Commercial Vehicles
- 5.1.4 Two-Wheelers
- 5.2 By Technology
- 5.2.1 Belt-Driven Alternator Starter (BDAS)
- 5.2.2 Integrated Starter Generator (ISG)
- 5.2.3 Direct Starter
- 5.3 By Component
- 5.3.1 Battery
- 5.3.2 Starter Motor
- 5.3.3 Alternator
- 5.3.4 Control Unit and Sensors
- 5.3.5 Other Components
- 5.4 By Fuel Type
- 5.4.1 Gasoline
- 5.4.2 Diesel
- 5.4.3 Hybrid (Incl. 48-V)
- 5.4.4 Alternative Fuel Types
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Aisin Corporation
- 6.4.2 BorgWarner Inc.
- 6.4.3 Continental AG
- 6.4.4 DENSO Corporation
- 6.4.5 Valeo SA
- 6.4.6 Robert Bosch GmbH
- 6.4.7 Hitachi Astemo Ltd.
- 6.4.8 HELLA GmbH & Co. KGaA
- 6.4.9 Johnson Controls International plc
- 6.4.10 Mitsubishi Electric Corporation
- 6.4.11 SEG Automotive Germany GmbH
- 6.4.12 Marelli Holdings Co., Ltd.
- 6.4.13 Schaeffler AG
- 6.4.14 Panasonic Holdings Corporation (Automotive Systems)
- 6.4.15 Calsonic Kansei Corporation
- 6.4.16 Clarios, LLC
- 6.4.17 Exide Technologies, LLC
- 6.4.18 Furukawa Electric Co., Ltd.
- 6.4.19 Prestolite Electric Incorporated
- 6.4.20 Mando Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


