

|
시장보고서
상품코드
2063508
단구 활성화 검사 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Monocyte Activation Test - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
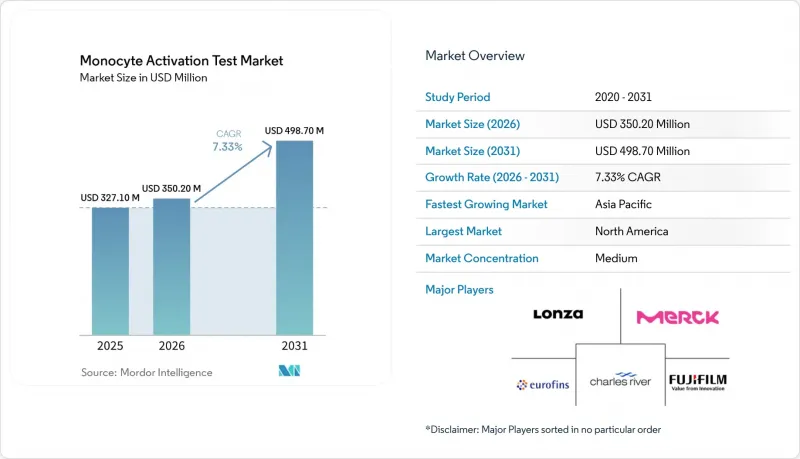
에 의하면, 단구 활성화 검사 시장 규모는 2025년 3억 2,710만 달러에서 2026년에는 3억 5,020만 달러로 확대되어 2026년부터 2031년까지 CAGR 7.33%로 성장을 지속하여, 2031년까지 4억 9,870만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 및 서비스(키트 및 시약 등), 검체 출처(PBMC 기반, 세포주 기반 등), 측정법(ELISA, 유세포분석법, QPCR/리포터 유전자), 용도(신약 개발, 백신 개발, 의료기기, 원자재), 최종 사용자(제약, 생명공학, 의료기기 제조업체, CRO/CMO, 학술 기관), 지역별로 분류되어 있습니다. 시장 전망치는 금액(달러)으로 표시되어 있습니다.
전 세계 단구 활성화 검사 시장 동향 및 인사이트
유럽에서 토끼 발열원 시험 규제의 단계적 폐지가 MAT 도입을 가속화하고 있습니다.
유럽 약전(Ph. Eur.)은 2026년 1월 1일부로 제2.6.8장에서 토끼를 이용한 발열원 시험을 삭제하였으며, 2025년 7월까지 57개 규격에서 이를 삭제했습니다. 이로써 MAT에 대한 투자를 지연시켜 왔던 마지막 규제상의 대안이 제거되었습니다. 제조업체는 현재 모든 공정 변경 시 비엔도톡신 발열원 위험 평가를 실시해야 하며, 사실상 복잡한 생물학적 제제에 대해서는 MAT 사용이 의무화되어 있습니다. 중동 및 아프리카의 규제 당국은 유럽 약전 기준을 따르며 각국의 지침을 개정하고 있어, 이에 따른 수요가 확대되고 있습니다. 이전에는 토끼를 이용해 시험되던 유럽의 주사제 대부분은 2026년 중반까지 MAT로 전환해야 하며, 이로 인해 단기적으로는 수요가 급증할 것으로 보이며, 중기적으로는 라틴아메리카 및 중동·북아프리카(MENA) 지역으로도 파급될 전망입니다.
확대되는 생물학적 제제 및 세포 및 유전자 치료 파이프라인이 피로겐 시험 수요를 증가시키고 있습니다.
2024년 유전자 치료에 대한 투자액은 152억 달러에 달했으며, 신규 임상시험의 절반 이상이 종양학 이외의 분야에서 진행되고 있으며, TLR 비의존적 경로를 통해 단구를 활성화시키는 지질 나노입자, 바이러스 캡시드 및 새로운 부형제가 도입되고 있습니다. 2025년에 발생한 AAV 관련 사망 사고를 계기로, FDA가 자연 면역 활성화를 엄격히 심사함에 따라, 전임상 및 제1상 임상시험 단계에서 MAT의 도입이 촉진되었습니다. mRNA 백신이 그 필요성을 보여주고 있습니다. 그 이온화 가능한 지질은 일반적인 엔도톡신 검사에서는 검출할 수 없는 TNF-α나 IL-6을 유도하기 때문입니다. 따라서 특히 북미와 유럽에서는 배치 릴리스에 그치지 않고 개발 및 검증 워크플로우에서도 검사량이 증가하고 있으며, 아시아태평양에서도 2030년까지 검사 역량이 확대되고 있습니다.
약전 간의 불일치와 제품별 검증 절차가 세계 시장 진출을 지연시키고 있습니다.
USP에는 MAT 전용 장이 없기 때문에 후원사는 <1225>에 근거한 완전한 대체법 검증 및 제품별 검증을 수행할 수밖에 없으며, 이로 인해 제품당 6-12개월의 기간과 최대 50만 달러의 추가 비용이 발생합니다. 일본 및 국제약전(Pharmacopoeia Internationalis)은 MAT를 완전히 제외하고 있으며, 해당 시장을 대상으로는 토끼를 이용한 이중 시험 또는 내독소 시험이 의무화되어 있습니다. ICH Q4B가 MAT로 확대될 때까지 다국적 기업들은 중복 비용과 과학적 이점을 저울질하며 검토하게 될 것입니다.
부문별 분석
2025년에는 키트 및 시약이 단구 활성화 검사 시장을 주도하며 56.18%의 점유율을 차지하고, 연평균 성장률(CAGR) 7.65%로 성장하고 있습니다. 신속 ELISA 및 리포터 유전자 형식이 수요의 기반을 이루고 있습니다. 이 장비 시장 점유율은 하나의 리더기로 여러 가지 분석에 대응할 수 있기 때문에 비교적 낮은 편이지만, 세포 기반 워크플로우에서는 여전히 필수적입니다. BMG LABTECH 등공급업체는 37℃에서의 배양 및 5% CO₂ 제어 기능을 갖춘 멀티모드 리더를 제공합니다. 생명공학 기업들이 검증 업무를 외부에 위탁함에 따라 서비스 사업도 확대되고 있습니다. Charles River는 턴키 방식의 시험, 간섭 시험, 규제 컨설팅 서비스를 제공하며, 이러한 복잡성을 수익으로 전환하고 있습니다.
대형 바이오의약품 기업들은 단위 비용 절감을 위해 MAT를 자체 생산하는 반면, 중소규모의 의뢰 기업들은 설비 투자를 피하기 위해 CRO를 활용하고 있습니다. 서비스 수익은 제품 출시나 검증 주기에 따라 일시적으로 발생하는 반면, 키트 판매는 배치별로 지속적으로 발생합니다. 세포, 시약, 기준 표준품, 프로토콜을 통합한 포트폴리오를 보유한 공급업체는 도입 장벽을 낮추고 이익률을 유지하고 있습니다. 법규 대응 및 신청 지원을 포함한 서비스 번들에 대한 수요가 증가함에 따라, 단구 활성화 검사 시장 내에서 양극화된 생태계가 형성되고 있습니다.
약전 선례에 따르면, 2025년에는 PBMC 기반 방법이 단구 활성화 검사 시장의 43.87%를 차지했습니다. 세포주 플랫폼은 재현성의 우위를 바탕으로 연평균 성장률(CAGR) 7.93%를 기록하며 성장하고 있습니다. NOMO-1 또는 THP-1을 이용한 NF-κB 루시페라제 분석법은 0.013 EU/mL 미만의 검출 한계를 달성하여 기증자 선별 비용을 절감합니다. 전혈 형식은 물류상의 제약으로 인해 규모 확대가 어려워, 파지 요법이나 복잡한 매트릭스 용도에서 틈새 시장으로만 자리 잡고 있습니다.
세포주는 대량 생산을 하는 백신 제조업체나 CDMO에게 매력적이지만, 규제 당국은 PBMC 분석법과의 동등성을 입증하기 위한 브릿징 시험을 요구하고 있습니다. MHRA의 2025년 파지 요법 지침은 세포 유래를 규정하지 않고 MAT를 승인함으로써, 검증된 대체 방법에 대한 수용성을 시사하고 있습니다. hiPSC 유래 대식세포는 GMP 생산을 위한 유망한 미래의 방향을 제시하지만, 아직 검증 단계에 있습니다. PBMC와 세포주의 병용 덕분에, 단구 활성화 검사 시장에서 예산 및 위험 프로파일에 따른 다양한 선택지가 확보되어 있습니다.
지역별 분석
2025년, 북미는 매출의 38.39%를 차지했습니다. FDA는 철저한 검증을 거친 경우 MAT를 대체법으로 인정하고 있지만, 약전에 등재되어 있지 않아 비용이 증가하고 있습니다. 론자가 메릴랜드주에서 진행한 18,000제곱피트 규모의 증설은 해당 지역의 지속적인 수요를 보여주고 있습니다. 유전자 치료 파이프라인의 집중과 2025년 이후 발생한 안전성 사건을 계기로 강화된 모니터링이 초기 단계에서의 도입을 뒷받침하고 있습니다. 캐나다와 멕시코의 기여도는 미미하지만, 멕시코의 바이오시밀러 제조업체들은 수출 기준을 충족하기 위해 MAT를 도입하고 있습니다.
유럽 시장 점유율은 법적 확실성의 혜택을 누리고 있습니다. 토끼 실험이 폐지되고, 비엔도톡신성 발열 물질의 위험성 평가가 의무화되었기 때문입니다. 독일, 영국, 프랑스는 바이오의약품 클러스터가 밀집해 있고, 3R(대체·감축·개선) 문화가 깊게 뿌리내리고 있어 이 분야를 선도하고 있습니다. EDQM의 2026년 심포지엄에서는 도입 지침이 제공되어 도입이 원활하게 진행되었습니다. 남유럽에서의 보급은 다소 더딘 편이지만, 조화로운 기준을 통해 중동·북아프리카(MENA) 및 라틴아메리카로 파급되는 효과 덕분에 성장이 유지되고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역이며, 2031년까지의 연평균 성장률(CAGR)은 7.59%입니다. 중국과 인도는 토끼를 이용한 시험 인프라가 없는 세포 치료제 및 바이오시밀러 제조 거점을 확대하고 있으며, 처음부터 MAT를 채택하고 있습니다. 일본 약전상의 규격 불일치로 인해 중복 시험을 실시할 수밖에 없게 되어, 성장이 둔화되고 있습니다. 한국은 세포 치료 분야에서의 선도적 위치를 바탕으로, 호주 규제 당국은 체외(in vitro) 방법을 우선적으로 채택하고 있습니다. 동남아시아와 대만은 수출 시장의 요건을 충족시키기 위해 신흥 도입국으로 부상하고 있습니다. 중동 및 아프리카 및 남미는 규모는 작지만 전략적으로 중요한 시장입니다. GCC(걸프협력회의) 회원국의 보건 당국과 브라질의 ANVISA(국가위생감독청)는 유럽 기준에 단계적으로 부합하도록 하고 있으며, 이를 통해 검사 키트 및 검증 서비스에 새로운 시장을 개척하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.06.23According to Mordor Intelligence, the monocyte activation test market size is expected to grow from USD 327.10 million in 2025 to USD 350.20 million in 2026 and is forecast to reach USD 498.70 million by 2031 at 7.33% CAGR over 2026-2031.
This report is Segmented by Product & Service (Kits and Reagents, and More), Source (PBMC-Based, Cell Line-Based, and More), Readout (ELISA, Flow Cytometry, QPCR/Reporter Gene), Application (Drug Development, Vaccine Development, Medical Devices, Raw Materials), End User (Pharma, Biotech, Device Manufacturers, CROs/CMOs, Academic Institutes), and Geography. Market Forecasts are in Value (USD).
Global Monocyte Activation Test Market Trends and Insights
Regulatory Phase-Out of Rabbit Pyrogen Test in Europe Accelerates MAT Adoption
European Pharmacopoeia suppressed the rabbit pyrogen test from chapter 2.6.8 on 1 January 2026 and deleted it from 57 monographs by July 2025, eliminating the last regulatory fallback that delayed MAT investment. Manufacturers must now conduct non-endotoxin pyrogen risk assessments for every process change, effectively mandating MAT for complex biologics. Middle Eastern and African regulators, mirroring Ph. Eur. standards, are updating national guidelines, expanding the addressable demand. The majority of European parenteral products that were formerly tested on rabbits must convert to MAT by mid-2026, triggering a short-term surge that spills into Latin America and MENA over the medium term.
Expanding Biologics, Cell/Gene-Therapy Pipelines Increase Pyrogen Testing Volumes
Gene-therapy investment reached USD 15.2 billion in 2024, with more than half of new trials outside oncology, bringing lipid nanoparticles, viral capsids, and novel excipients that activate monocytes via TLR-independent pathways . FDA scrutiny of innate immune activation following AAV-related fatalities in 2025 has driven MAT adoption at the preclinical and Phase I stages. mRNA vaccines illustrate the need: their ionizable lipids induce TNF-a and IL-6 that ordinary endotoxin assays miss. Volumes therefore rise beyond batch release into development and validation workflows, particularly in North America and Europe, with Asia-Pacific adding capacity through 2030.
Non-Harmonized Pharmacopeial Acceptance and Product-Specific Validations Slow Global Rollout
USP lacks a dedicated MAT chapter, forcing sponsors to deliver full alternative-method validation under <1225> and product-specific verification, adding 6-12 months and up to USD 0.5 million per product. Japan and Pharmacopoeia Internationalis omit MAT entirely, compelling dual rabbit or endotoxin testing for those markets. Until ICH Q4B expands to MAT, multinational firms weigh the costs of duplication against scientific gains.
Other drivers and restraints analyzed in the detailed report include:
- Ethical / 3Rs Mandates and Corporate Sustainability Policies Favor Animal-Free Testing
- Rapid MAT Formats Reduce Cycle Time and QC Bottlenecks
- Donor/Assay Variability and Inter-Lab Reproducibility Challenges Raise QA Burden
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Kits and reagents led the monocyte activation test market, with a 56.18% share in 2025, and are growing at a 7.65% CAGR. Rapid ELISA and reporter-gene formats underpin demand. Instruments represent a smaller slice because one reader supports multiple assays, yet remain critical for cell-based workflows; vendors such as BMG LABTECH offer multimode readers with 37 °C incubation and 5% CO2 control. Services expand as biotech firms outsource validation; Charles River provides turnkey testing, interference studies, and regulatory consulting, monetizing complexity.
Large biopharma internalizes MAT to cut unit costs, while small sponsors leverage CROs to avoid capital outlay. Service revenues are episodic, tied to product launches and validation cycles, whereas kit sales recur with every batch. Suppliers with integrated portfolios-cells, reagents, reference standards, and protocols-lower adoption barriers and defend margins. Demand for service bundles that include method development and submission support is increasing, creating a two-speed ecosystem within the monocyte activation test market.
PBMC-based methods controlled 43.87% of the monocyte activation test market share in 2025, thanks to pharmacopeial precedent. Cell-line platforms are advancing at a 7.93% CAGR driven by reproducibility advantages. NOMO-1 or THP-1 NF-κB luciferase assays deliver detection limits below 0.013 EU/mL and remove donor-screening costs . Whole-blood formats remain niche for phage therapy and complex matrices because logistics limit scale.
Cell lines appeal to vaccine manufacturers and CDMOs handling high volumes, yet regulators require bridging studies to show parity with PBMC assays. MHRA's 2025 phage-therapy guidance accepted MAT without prescribing cell source, indicating openness to validated alternatives. hiPSC-derived macrophages offer a promising future path for GMP production but await validation. The coexistence of PBMCs and cell lines ensures differentiated options across budgets and risk profiles in the monocyte activation test market.
Geography Analysis
North America commanded 38.39% of revenue in 2025. FDA accepts MAT as an alternative method upon full validation, yet the absence of a compendial chapter raises costs. Lonza's 18,000 sq ft Maryland expansion signals sustained regional demand. Concentrated gene-therapy pipelines and heightened scrutiny after 2025 safety events drive early-stage adoption. Canada and Mexico contribute modestly; Mexico's biosimilar producers implement MAT to meet export standards.
Europe's share benefits from legal certainty: the rabbit test was removed, and non-endotoxin pyrogen risk assessment is mandatory. Germany, the United Kingdom, and France are front-runners thanks to dense biopharma clusters and strong 3Rs culture. EDQM's 2026 symposium provided implementation guidance, smoothing adoption. Southern European uptake lags, but spillover into MENA and Latin America via harmonized standards sustains growth.
Asia-Pacific is the fastest-growing region, with a 7.59% CAGR through 2031. China and India scale cell-therapy and biosimilar plants devoid of rabbit infrastructure, embracing MAT from the outset. Japan's pharmacopoeia gap forces dual testing, muting growth. South Korea leverages its cell-therapy leadership, and Australia's regulators prioritize in vitro methods. Southeast Asia and Taiwan represent emerging adopters as they align with export-market requirements. The Middle East & Africa and South America remain smaller but strategic. GCC health authorities and Brazil's ANVISA align progressively with European standards, opening new markets for kits and validation services.
- Cellular Technology Limited (CTL)
- Charles River
- Eurofins
- FUJIFILM
- Haemochrom Diagnostica GmbH
- Labor LS SE & Co. KG
- Lonza Group Ltd.
- Mabtech
- MAT BioTech B.V.
- MAT Research B.V.
- Merck
- Microcoat Biotechnologie
- Minerva Biolabs GmbH
- Nelson Labs
- PromoCell
- Quality Assistance S.A.
- Sanquin Reagents B.V.
- SGS North America, Inc.
- WuXi App Tec
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory Phase-Out Of Rabbit Pyrogen Test (RPT) In Europe Accelerates MAT Adoption
- 4.2.2 Expanding Biologics, Cell/Gene Therapy, And Parenteral Pipelines Increase Pyrogen Testing Volumes
- 4.2.3 Ethical/3Rs Mandates and Corporate Sustainability Policies Favor Animal-Free Testing
- 4.2.4 Rapid MAT Formats (2-8 Hour ELISA/Reporters) Reduce Cycle Time and QC Bottlenecks
- 4.2.5 New EU Ph. Eur. 5.1.13 "Pyrogenicity" And NEP Risk-Assessment Drive MAT Where BET/Rfc Are Insufficient
- 4.2.6 PBMC Supply Scaling and Vendor Partnerships Improve Lot-To-Lot Reproducibility and Global Availability
- 4.3 Market Restraints
- 4.3.1 Non-Harmonized Pharmacopeial Acceptance and Product-Specific Validations Slow Global Rollout
- 4.3.2 Donor/Assay Variability and Inter-Lab Reproducibility Challenges Raise QA/Validation Burden
- 4.3.3 Limited NEP Reference Standards and Control Materials Constrain Robust PSV And Comparability
- 4.3.4 Specialized Equipment/Readouts (ELISA/Reporters) And Trained Staff Needs Elevate Entry Costs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product & Service
- 5.1.1 Kits and Reagents
- 5.1.2 Instruments
- 5.1.3 Services (CRO/CTO testing, validation, training)
- 5.2 By Source
- 5.2.1 PBMC-based
- 5.2.2 Cell line-based (e.g., MM6, THP-1, NOMO-1)
- 5.2.3 Whole blood-based
- 5.3 By Detection
- 5.3.1 ELISA-based
- 5.3.2 Flow-cytometry-based
- 5.3.3 qPCR/Reporter gene-based (e.g., NF-κB luciferase, dPCR)
- 5.4 By Application
- 5.4.1 Drug development / batch release
- 5.4.2 Vaccine development and inherently pyrogenic vaccines
- 5.4.3 Medical devices (material-mediated pyrogens)
- 5.4.4 Raw materials / excipients / APIs
- 5.5 By End User
- 5.5.1 Pharmaceutical companies
- 5.5.2 Biotechnology companies
- 5.5.3 Medical device manufacturers
- 5.5.4 CROs/CMOs/CTOs
- 5.5.5 Academic & research institutes
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 Cellular Technology Limited (CTL)
- 6.3.2 Charles River Laboratories International, Inc.
- 6.3.3 Eurofins Scientific SE
- 6.3.4 FUJIFILM Holdings Corporation
- 6.3.5 Haemochrom Diagnostica GmbH
- 6.3.6 Labor LS SE & Co. KG
- 6.3.7 Lonza Group Ltd.
- 6.3.8 Mabtech AB
- 6.3.9 MAT BioTech B.V.
- 6.3.10 MAT Research B.V.
- 6.3.11 Merck KGaA
- 6.3.12 Microcoat Biotechnologie GmbH
- 6.3.13 Minerva Biolabs GmbH
- 6.3.14 Nelson Labs
- 6.3.15 PromoCell GmbH
- 6.3.16 Quality Assistance S.A.
- 6.3.17 Sanquin Reagents B.V.
- 6.3.18 SGS North America, Inc.
- 6.3.19 WuXi AppTec
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


