

|
시장보고서
상품코드
2065573
소매용 ERP 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Retail Enterprise Resource Planning (ERP) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
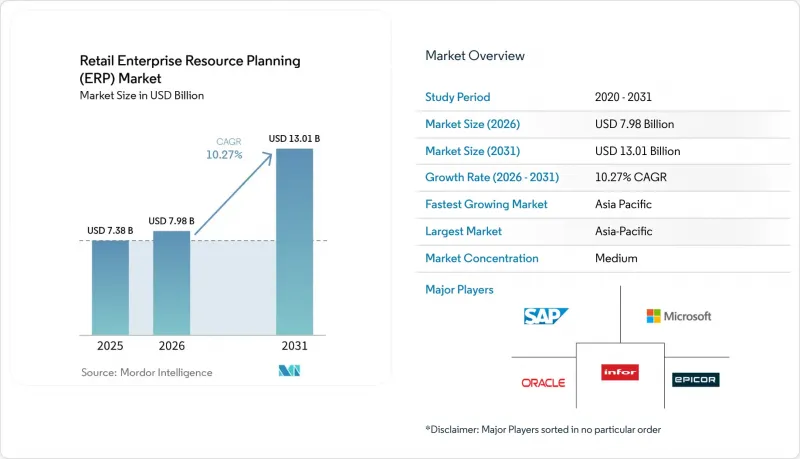
에 의하면, 소매용 ERP 시장 규모는 2025년 73억 8,000만 달러로 평가되었고, 2026년 79억 8,000만 달러로 추정되고, 2031년까지 130억 1,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 10.27%를 나타낼 전망입니다.
본 보고서는 배포 유형별(클라우드, 온프레미스, 하이브리드), 조직 규모별(중소기업, 대기업), 구성 요소별(재무 및 회계, 재고 및 창고 관리, 판매 및 CRM, 인사 관리 등), 소매 업태별(슈퍼마켓 및 하이퍼마켓, 전문점, 백화점 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 소매용 ERP 시장 동향 및 인사이트
클라우드 기반 소매용 ERP로의 전환이 가속화되고 있습니다.
2025년에는 소매업체들이 자동 업그레이드, 유연한 컴퓨팅, 인프라 비용 절감을 요구함에 따라, 신규 도입의 대부분을 클라우드 구독 서비스가 차지했습니다. 체인점이 데이터 거주법을 준수하기 위해 기밀성이 높은 고객 데이터를 로컬 서버에 보관하면서, 확장성을 확보하기 위해 스트림 분석 워크로드를 퍼블릭 클라우드에서 실행하는 하이브리드 전략이 점차 확산되고 있습니다. 중규모 전문 소매업체들이 가장 큰 혜택을 보고 있습니다. 이는 매장별 과금제가 6자리 숫자에 달하는 영구 라이선스를 대체함에 따라 초기 비용이 대폭 절감되었고, 도입 기간도 18개월 미만으로 단축되었기 때문입니다. 또한, 이러한 전환을 통해 기존 데이터센터에서는 이용할 수 없었던 확장 가능한 컴퓨팅에 기반한 동적 가격 책정 등의 내장형 AI 기능도 활용할 수 있게 됩니다.
옴니채널 소매의 복잡화
클릭 앤 콜렉트, 매장 발송, 엔드리스 아일(Endless Aisle)과 같은 서비스로 인해 실시간 주문 관리 엔진에 대한 수요가 증가하고 있습니다. 재고, 가격, 로열티 데이터가 매장, 웹사이트, 소셜 커머스 피드를 아우르는 단일 원장에 통합됨으로써, 분할 배송 비용이 절감되고 주문 처리 관련 의사결정이 최적화됩니다. 최신 ERP 제품군에서는 야간 일괄 전송이 필요 없기 때문에 가격 인하 결정이 해당 상품이 판매되는 모든 지점에 몇 분 만에 반영됩니다. 소셜 커머스와의 통합으로 인해 그 장벽은 더욱 높아졌으며, 소매업체들은 기존 시스템에서는 상상조차 하지 못했던 외부 플랫폼에서 상품 표시, 결제 처리, 서비스 티켓 처리를 수행할 수밖에 없게 되었습니다.
높은 도입 비용 및 예산 초과
최근 프로젝트의 4분의 3 가까이가 예산을 초과했는데, 그 원인은 범위 확대, 혼란스러운 데이터 마이그레이션, 그리고 과소평가된 변경 관리로 인한 서비스 시간 증가에 있습니다. 중견 소매업체들은 IT 인력이 부족하고, 기성 템플릿이라도 맞춤 설정이 필요하다는 사실을 너무 늦게 깨닫기 때문에 이러한 영향에 가장 크게 시달리고 있습니다. 타사 통합 라이선스, 구형 및 신형 시스템의 병행 운영, 성수기에 급증하는 사용자당 SaaS 이용료와 같은 숨겨진 비용으로 인해 총 소유 비용이 10년 치의 영구 라이선스 비용을 초과할 가능성도 있습니다.
부문별 분석
소매용 ERP 시장에서는 체인점들이 온프레미스 데이터 스토리지와 클라우드 분석을 결합하여, 현지 규제를 준수하면서도 유연한 컴퓨팅 환경을 활용하는 ‘하이브리드 구축’이 세를 넓혀가고 있습니다. 하이브리드 솔루션을 위한 소매용 ERP 시장 규모는 네트워크 장애 시에도 POS를 가동하고 나중에 중앙에서 보고서를 작성하기 위해 데이터를 동기화하는 엣지 서버의 보급에 따라 확대되고 있습니다. 중국과 유럽연합(EU)에서 사업을 전개하는 다국적 기업들은 고객 데이터가 국경을 넘지 않으면서도 집계된 분석 결과가 전 세계 대시보드에 반영되기 때문에 이러한 구성을 선호합니다. 소형 서버에서 구동되는 엣지 모듈은 광대역 연결이 불안정한 지방의 매장에서도 가동 시간을 연장하며, 통신 장애 시에도 모든 매출 데이터를 확실하게 기록합니다.
하이브리드 도입은 단계적인 전환 경로도 지원합니다. 소매업체는 먼저 재무 및 인사 시스템을 SaaS로 전환하고, 통합을 테스트한 후, 데이터 일관성이 개선된 단계에서 재고 및 주문 워크플로우를 개선합니다. Azure Stack 및 유사한 플랫폼은 통합된 관리 환경을 제공하므로, IT 팀은 단일 콘솔에서 온프레미스 및 클라우드 워크로드를 모니터링할 수 있어 관리 부담을 줄일 수 있습니다. 고급 상품이나 약국 등 엄격한 관리가 요구되는 환경에서는 온프레미스 방식이 여전히 유지되고 있지만, 패치 적용이나 하드웨어 교체 주기에 따른 운영 부담으로 인해 그 점유율은 계속해서 감소하고 있습니다.
2025년에는 도입 건수의 62.4%를 중소기업이 차지한 것으로 평가되었으며, 리소스 단위의 과금 체계 덕분에 6자리 수의 초기 비용이 들지 않기 때문에 대기업보다 더 빠른 속도로 계속 확대될 전망입니다. 인프라, 지원, 향후 업그레이드가 포함된 구독 번들 덕분에 도입 기간이 90일 미만으로 단축되어, 소규모 체인은 서버 유지보수 대신 상품 기획에 집중할 수 있게 됩니다. 각 벤더사는 현재 코딩 없이도 새로운 테넌트에 바로 도입할 수 있는 미리 설정된 계정표와 판촉 엔진을 제공하고 있으며, 이를 통해 컨설턴트의 작업 시간을 단축하고 가치 실현을 가속화하고 있습니다. 그렇긴 하지만, 소매 ERP 업계는 여전히 기술 격차에 직면해 있습니다. 중소기업에서는 전담 ERP 관리자를 고용하는 경우가 드물기 때문에 문제 해결을 위해서는 공급업체가 관리하는 서비스에 의존할 수밖에 없기 때문입니다.
대기업들은 여러 사업체의 연결 결산, 세계 세무 시스템, 첨단 공급망 계획과 같은 고도의 기능을 도입하고 있으며, 이로 인해 평균 계약 규모가 증가하고 있습니다. 그러나 그 복잡성 때문에 도입 기간이 1년을 훨씬 초과하며, 특히 프랜차이즈나 합작 사업의 회계 처리에서 독자적인 데이터 모델이 필요한 경우, 맞춤화 예산이 불어나게 됩니다. 그 결과, 기업용 라이선스의 총 매출액은 중소기업용 판매량을 상회하고 있으며, 시스템 통합사업자들은 여전히 대형 체인점의 프로젝트를 중심으로 대규모 사업을 전개하고 있습니다.
지역별 분석
아시아태평양은 엄격한 전자 청구서 발행 법규와 폭발적으로 증가하는 모바일 상거래 거래량에 힘입어 소매 업계 ERP 시장의 중심지로 자리 잡고 있습니다. 인도 정부 포털에서는 2025 회계연도에 수십억 건의 청구서가 처리될 예정이며, 자동화된 세무 대조는 더 이상 미래의 희망 사항이 아니라 필수 요건이 되었습니다. 중국에서는 대규모 소매 체인의 3분의 2 이상이 이미 클라우드 ERP를 도입했으며, 현지 결제 게이트웨이를 백오피스 원장에 직접 통합함으로써 현금 결제를 신속하게 처리하고 있습니다. 지역 마켓플레이스에 입점하는 동남아시아 판매업체들은 24시간 이내 주문 이행이라는 약속을 지켜야 하며, 이를 위해서는 창고 수준이 아닌 판매업체 수준에서 ERP 기반의 정확한 재고 관리가 요구됩니다.
북미는 성숙해 가고 있지만 여전히 혁신적인 시장이며, 그 초점은 전환에서 최적화로 옮겨가고 있습니다. 소매업체들은 온라인 구매 및 매장 수령 워크플로우를 미세 조정하고, 분할 배송 비용을 절감하며, 매장 앱 내에서 AI를 활용한 상품 추천 기능을 시범 도입하고 있습니다. 엄격한 주 개인정보 보호법에 따라, ERP 데이터베이스 내에서는 세분화된 역할 기반 접근 제어 및 고객 식별자의 토큰화가 진행되고 있습니다. 캐나다에서도 비슷한 추세가 나타나고 있지만, 이중 언어 지원 요건이 설계의 복잡성을 더욱 가중시키고 있습니다.
유럽에서는 근대화와 규정 준수의 균형이 잘 잡혀 있습니다. GDPR(EU 개인정보보호규정) 감사로 인해 클라우드 공급업체 선정에 수개월이 소요되고 있지만, 향후 도입될 ‘디지털 시대의 부가가치세(VAT-in-the-Digital-Age)’ 프로그램에 따라 이미 체인 계열사들은 27개 관할 구역에 걸친 지속적인 거래 보고가 가능한 플랫폼으로의 통합을 추진하고 있습니다. 북유럽의 소매업체들은 플랫폼을 전면적으로 개편하지 않고도 모듈을 교체할 수 있는 ‘조합형 마이크로서비스’를 조기에 도입하고 있는 반면, 남유럽의 각 체인점들은 노후화된 온프레미스 시스템을 대체하는 SaaS 구독 서비스를 통해 비용 관리에 주력하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.06.30According to Mordor Intelligence, the retail enterprise resource planning market size is projected to expand from USD 7.38 billion in 2025 and USD 7.98 billion in 2026 to USD 13.01 billion by 2031, registering a CAGR of 10.27% between 2026 to 2031.
This report is Segmented by Deployment Type (Cloud-Based, On-Premise, and Hybrid), Organization Size (SMEs and Large Enterprises), Component (Finance and Accounting, Inventory and Warehouse Management, Sales and CRM, HR Management, and More), Retail Format (Supermarkets and Hypermarkets, Specialty Stores, Department Stores, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Retail Enterprise Resource Planning (ERP) Market Trends and Insights
Accelerating Shift to Cloud-Based ERP In Retail
Cloud subscriptions represented most new installs in 2025 because retailers want automatic upgrades, elastic compute, and lower infrastructure costs. Hybrid strategies are catching on as chains keep sensitive customer data on local servers to meet data-residency laws, while stream analytics workloads run in public clouds for scale. Mid-sized specialty retailers gain the most because per-store pricing now replaces six-figure perpetual licenses, slashing up-front costs and shrinking implementation windows to under 18 months. The transition also unlocks embedded AI features, such as dynamic pricing, that depend on scalable compute unavailable in legacy data centers.
Growing Omnichannel Retail Complexity
Click-and-collect, ship-from-store, and endless aisle services drive demand for real-time order-management engines. Split-shipment costs drop and fulfillment decisions are optimized when inventory, pricing, and loyalty data live in a single ledger that spans stores, websites, and social-commerce feeds. Modern ERP suites eliminate overnight batch transfers, so a markdown decision propagates in minutes across all locations where the product appears. Social-commerce integrations raise the bar further, compelling retailers to surface products, process payments, and resolve service tickets on external platforms that their legacy systems never contemplated.
High Implementation Costs and Budget Overruns
Nearly three-quarters of recent projects ran over budget, with overruns due to scope creep, messy data migrations, and underestimated change management inflate service hours. Mid-market retailers feel the crunch most because they lack deep IT benches and discover too late that canned templates still need customization. Hidden costs such as third-party integration licenses, dual-running old and new systems, and per-user SaaS fees that spike during peak seasons can drive total ownership above a decade of perpetual-license spend.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Real-Time Inventory Visibility
- Government Mandates for E-Invoicing and Digital Tax Compliance
- Data Security and Privacy Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hybrid deployments are gaining ground in the retail enterprise resource planning market as chains mix on-premises data stores with cloud analytics to comply with local regulations while still tapping elastic compute. The retail enterprise resource planning market size for hybrid solutions is advancing alongside edge servers that keep point-of-sale running during network outages, then synchronize later for central reporting. Multinationals operating in China or the European Union prefer this setup because customer data never leaves national borders, while aggregate insights roll into a global dashboard. Edge modules running on compact servers extend uptime in rural stores where broadband is shaky, ensuring every sale posts even during outages.
Hybrid adoption also supports phased migration paths. Retailers move finance and HR to SaaS first, test integrations, then tackle inventory and order workflows once data cleanliness improves. Azure Stack and similar platforms provide a unified management plane, so IT teams can monitor on-premises and cloud workloads from a single console, reducing admin effort. While on-premise still survives in high-control environments such as luxury or pharmacy, the operational burden of patches and hardware refresh cycles continues to erode its share.
SMEs accounted for 62.4% of deployments in 2025 and will continue to expand faster than their larger peers because per-resource pricing eliminates six-figure entry fees. Subscription bundles that include infrastructure, support, and future upgrades compress implementation to fewer than 90 days, allowing small chains to focus on merchandising rather than server upkeep. Vendors now ship pre-configured chart-of-accounts and promotional engines that drop into a new tenant without coding, shaving consultant hours, and accelerating value capture. The retail enterprise resource planning industry nevertheless faces a skills gap, as SMEs rarely employ full-time ERP administrators and must rely on vendor-managed services for troubleshooting.
Large enterprises buy deeper functionality such as multi-entity consolidations, global tax engines, and advanced supply-chain planning, which boosts average deal size. Yet complexity stretches deployments well beyond a year and inflates customization budgets, especially where franchise or joint-venture accounting demands unique data models. As a result, total enterprise license revenue outweighs sheer SME volume, and system integrators still build sizable practices around big-chain projects.
Geography Analysis
Asia-Pacific anchors the retail enterprise resource planning market, driven by stringent e-invoicing laws and exploding mobile commerce volume. Government portals in India processed billions of invoices in fiscal 2025, making automated tax reconciliation a must-have rather than a future wish. In China, over two-thirds of sizable retail chains already run cloud ERP, integrating local payment gateways directly into back-office ledgers to accelerate cash settlement. Southeast Asian sellers on regional marketplaces must meet 24-hour fulfillment promises, which requires ERP-driven inventory accuracy at the seller level rather than the warehouse level.
North America is a mature yet innovative landscape, shifting its focus from migration to optimization. Retailers fine-tune buy-online-pick-up-in-store workflows, trim split-shipment costs, and pilot AI recommendations inside store apps. Stringent state privacy laws drive granular role-based access controls and tokenization of customer identifiers inside ERP databases. Canada shows parallel trends, though bilingual requirements add another layer of design complexity.
Europe balances modernization with compliance. GDPR audits add months to cloud-vendor selection, but the upcoming VAT-in-the-Digital-Age program is already prompting chains to centralize onto platforms that can deliver continuous transaction reporting across 27 jurisdictions. Nordic retailers push early into composable microservices, swapping modules without full re-platforming, while Southern European chains focus on cost control through SaaS subscriptions that replace aging on-premise systems.
- SAP SE
- Oracle Corporation
- Microsoft Corporation
- Infor, Inc.
- Epicor Software Corporation
- The Sage Group plc
- Acumatica, Inc.
- LS Retail ehf.
- Odoo SA
- Brightpearl Limited
- Lightspeed Commerce Inc.
- IFS AB
- Blue Yonder Group, Inc.
- Aptos, LLC
- Cegid Group SA
- Retail Pro International, LLC
- CitiXsys India Private Limited
- Marg ERP Limited
- Logic ERP Solutions Private Limited
- Erply Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Shift to Cloud-Based ERP in Retail
- 4.2.2 Growing Omnichannel Retail Complexity
- 4.2.3 Rising Demand for Real-Time Inventory Visibility
- 4.2.4 Government Mandates for E-Invoicing and Digital Tax Compliance
- 4.2.5 AI-Driven Demand Forecasting Reduces Stockouts and Markdowns
- 4.2.6 Integration of Embedded Payments within Retail ERP Ecosystems
- 4.3 Market Restraints
- 4.3.1 High Implementation Costs and Budget Overruns
- 4.3.2 Data Security and Privacy Concerns
- 4.3.3 Shortage of Retail-Specific ERP Implementation Talent
- 4.3.4 Disruption Risk from Composable Microservices Architectures
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Type
- 5.1.1 Cloud-Based
- 5.1.2 On-Premise
- 5.1.3 Hybrid
- 5.2 By Organization Size
- 5.2.1 Small and Medium-Sized Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Component
- 5.3.1 Finance and Accounting
- 5.3.2 Inventory and Warehouse Management
- 5.3.3 Sales and Customer Relationship Management
- 5.3.4 Human Resource Management
- 5.3.5 Supply Chain Management
- 5.3.6 Reporting and Analytics
- 5.3.7 Other Components
- 5.4 By Retail Format
- 5.4.1 Supermarkets and Hypermarkets
- 5.4.2 Specialty Stores
- 5.4.3 Department Stores
- 5.4.4 Convenience Stores
- 5.4.5 E-Commerce and Omnichannel Retailers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Australia
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Kenya
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 SAP SE
- 6.4.2 Oracle Corporation
- 6.4.3 Microsoft Corporation
- 6.4.4 Infor, Inc.
- 6.4.5 Epicor Software Corporation
- 6.4.6 The Sage Group plc
- 6.4.7 Acumatica, Inc.
- 6.4.8 LS Retail ehf.
- 6.4.9 Odoo SA
- 6.4.10 Brightpearl Limited
- 6.4.11 Lightspeed Commerce Inc.
- 6.4.12 IFS AB
- 6.4.13 Blue Yonder Group, Inc.
- 6.4.14 Aptos, LLC
- 6.4.15 Cegid Group SA
- 6.4.16 Retail Pro International, LLC
- 6.4.17 CitiXsys India Private Limited
- 6.4.18 Marg ERP Limited
- 6.4.19 Logic ERP Solutions Private Limited
- 6.4.20 Erply Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


