|
시장보고서
상품코드
2066680
프랑스의 실란트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)France Sealants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 프랑스의 실란트 시장 규모는 2025년 3억 8,010만 달러로 평가되었습니다. 2026년에는 4억 170만 달러로 확대되어 2031년까지 5억 3,510만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.90%로 성장할 것으로 전망됩니다.

본 보고서는 수지 유형(실리콘, 폴리우레탄, 아크릴, 에폭시, 기타 수지) 및 최종 사용자 산업(항공우주, 자동차 및 운송, 건축 및 건설, 의료, 기타 최종 사용자 산업)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
프랑스의 실란트 시장 동향 및 분석
에너지 절약형 건축 외피 개보수를 주도하는 수요의 급증
'MaPrimeRenov'는 2025년 12월까지 소득이 매우 낮은 가구를 대상으로 최대 50%의 현금 선지급을 연장했으며, 이를 통해 열교, 지붕 이음매, 덕트 관통부에 사용되는 실리콘 및 폴리우레탄계 실란트의 즉각적인 구매가 촉진되었습니다. Momentive Elemax 2600과 같은 액상 실리콘 기밀·방수재는 제어할 수 없는 기류를 억제함으로써 HVAC의 에너지 사용량을 최대 35%까지 절감할 수 있으며, 시트형 방수막을 설치하기 어려운 리모델링 공사에서 매력적인 투자 회수 수단이 되고 있습니다. 중소득 가구에 대한 보조금 상한선이 80%로 인상됨에 따라, 프랑스의 FDES 인증을 획득한 고품질의 저VOC 제품에 대한 접근성이 확대되고, HQE Cible 8 목표에 기반한 기밀성 기준 준수가 보장됩니다. ISO 11600 클래스 25의 가동성 요건 및 EN 15651-2의 규정이 의무화됨에 따라, 유리 공사 및 파사드 공사의 접합부 내구성이 확보됩니다. 이러한 정책 및 규격 체계가 결합되어, 고성능 건축용 실란트에 대한 수년에 걸친 수요 사이클이 확고하게 자리 잡게 됩니다.
프랑스 자동차 생산에서 전기자동차(EV)의 경량화 요건
알루미늄과 탄소섬유 강화 폴리머, 혹은 강철과 복합재료와 같은 다양한 소재 간의 접착이 전기자동차(EV)의 화이트 바디 구조에서 기계식 체결 부품을 대체하고 있으며, 이에 따라 진동 댐퍼 및 배터리 케이스용 실란트 역할을 겸하는 전단 저항성 에폭시 및 폴리우레탄계 접착제의 소비가 확대되고 있습니다. 헨켈이 2025년 4월에 발표한, AI를 통해 생성된 가상 접착제 및 박리 가능한 화학 조성은 추적 가능성과 사용 후 분해를 의무화하는 EU의 배터리 여권 규정을 염두에 둔 것입니다. UV 조사에 의해 수 분 만에 경화되는 아크릴·에폭시 하이브리드 수지는 플라즈마 전처리를 거침으로써 생산 라인의 타크트 타임을 단축하고, 저에너지 플라스틱에 대한 접착력을 향상시켜, 스텔란티스 및 르노의 공장에서 더 높은 처리량을 실현하고 있습니다. VOC(휘발성 유기 화합물) 농도를 250 g/L 미만으로 유지해야 한다는 LEED v4 및 SCAQMD 규정 1168의 기준치 상향 조정으로 인해, MS 폴리머가 그 우위를 발휘하고 있습니다. 이 제품들은 이소시아네이트에 노출되지 않은 상태에서도 ±25%에서 ±50%의 변위를 실현합니다. 규제와 생산 측면의 요인이 복합적으로 작용하여, 자동차용 실란트는 꾸준한 성장세를 유지하고 있습니다.
석유화학 원료 가격의 변동
매출의 약 50%를 원자재가 차지하기 때문에 프랑스의 배합 제조업체들은 분기별 건설 계약을 통해 가격 급등분을 전가하는 데 어려움을 겪고 있으며, 이로 인해 EBITDA가 압박을 받고 있습니다. BASF가 가이スマ르에서 MDI 생산을 확대함에 따라 2027년까지 공급 부족 현상은 완화될 가능성이 있지만, 지정학적 리스크로 인해 벤젠과 나프타의 가격은 여전히 변동하고 있어 실란트 제조업체들은 이익률의 급격한 변동에 직면해 있습니다. 헤지 대책을 마련하지 않은 기업들은 특히 저가 아시아산 수입품이 여전히 유입되고 있는 상황을 감안할 때, 판매량 감소와 이익 축소 중 하나를 선택해야 하는 상황에 직면해 있습니다.
부문별 분석
2025년, 실리콘은 프랑스의 실란트 시장 점유율의 38.5%를 차지했습니다. 이는 구조용 유리, 복층 유리, 내후성 파사드에 대한 대체 불가능한 수요에 힘입은 결과입니다. “Sikasil IG-25 HM Plus”는 EN 1279-4 및 ASTM C1184를 준수하며, 고가인 진공 단열 유리에서 요구되는 가스 유지 성능을 보장합니다. 폴리우레탄은 프랑스의 실란트 시장 규모 확대를 주도할 것으로 보이며, 2026년부터 2031년까지 연평균 성장률(CAGR) 7.24%를 나타낼 것으로 전망됩니다. 이는 전기자동차 제조업체들이 경량화와 배터리 주행 거리 연장을 도모하기 위해 용접 대신 알루미늄, CFRP 및 강철 모듈을 접착하는 추세가 반영된 결과입니다.
아크릴계 실란트는 도장성이 우수하고 VOC 함량이 거의 제로에 가까워 장식적인 이점이 있어 실내의 정적 접합부에 한정되어 사용되고 있으나, 움직임에 대한 적응성이 낮아 실외에서의 사용은 제한되고 있습니다. 에폭시 계열은 인장 강도와 내화학성 덕분에 느린 경화 속도가 정당화되는 틈새 시장인 산업용 바닥재나 항공우주 분야에서 주류를 이루고 있습니다. Baxxodur EC 151은 5℃에서도 기능적 경화가 가능하여, 겨울철 시공 기간을 연장해 줍니다. 폴리설파이드 계열과 MS 폴리머는 각각 연료 탱크의 밀봉이나 이소시아네이트가 포함되지 않은 시공 이음매와 같은 특수한 역할을 담당하고 있지만, 바이오 신제품의 등장으로 인한 중기적인 대체 위험에 직면해 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.29According to Mordor Intelligence, the france sealants market size is projected to grow from USD 380.10 million in 2025 to USD 401.70 million in 2026, and reach USD 535.10 million by 2031, growing at a CAGR of 5.90% from 2026 to 2031.
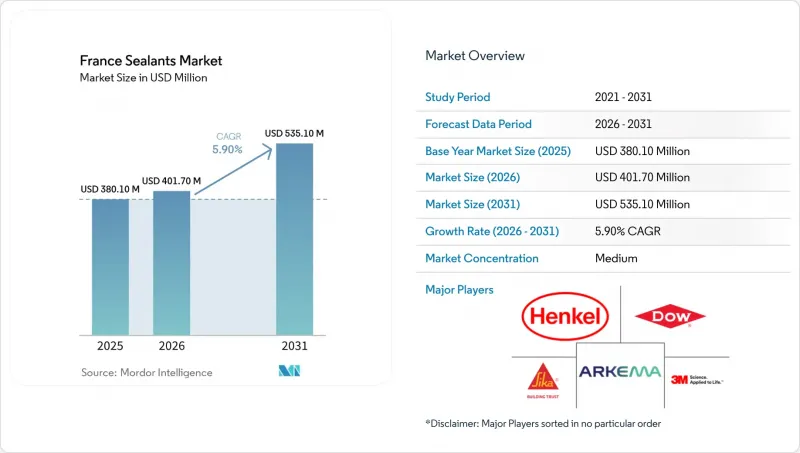
This report is Segmented by Resin Type (Silicone, Polyurethane, Acrylic, Epoxy, and Other Resins) and End-User Industry (Aerospace, Automotive and Transportation, Building and Construction, Healthcare, and Other End-User Industries). The Market Forecasts are Provided in Terms of Value (USD).
France Sealants Market Trends and Insights
Renovation-Led Demand Surge in Energy-Efficient Building Envelope Upgrades
MaPrimeRenov' extended cash advances up to 50% for very modest households through December 2025, stimulating immediate purchases of silicone and polyurethane sealants for thermal bridges, roof junctions, and duct penetrations. Fluid-applied silicone air-and-water barriers such as Momentive Elemax 2600 can reduce HVAC energy use by as much as 35% by limiting uncontrolled airflow, an attractive payback lever in retrofit settings where sheet membranes are difficult to place. The subsidy's raised cost ceiling to 80% for middle-income households broadens access to premium low-VOC products carrying French FDES declarations, ensuring airtightness compliance under HQE Cible 8 targets. Mandatory ISO 11600 Class 25 movement and EN 15651-2 designations safeguard joint durability in glazing and facade works. These policy and standard frameworks collectively lock in a multi-year demand cycle for high-performance building sealants.
EV Lightweighting Requirements in French Automotive Production
Multi-material bonding, aluminum to carbon-fiber-reinforced polymer and steel to composites, is displacing mechanical fasteners in EV body-in-white architecture, pushing consumption of shear-resistant epoxy and polyurethane adhesives that double as vibration dampers and battery-case sealants. Henkel's April 2025 reveal of AI-generated virtual adhesives and debondable chemistries anticipates EU battery-passport rules that will require traceability and end-of-life disassembly. Acrylic-epoxy hybrids activated by UV in minutes are improving line takt times and adhesion to low-energy plastics when pre-treated with plasma, enabling higher throughput at Stellantis and Renault plants. Evolving LEED v4 and SCAQMD Rule 1168 thresholds below 250 g/L VOC are giving MS polymers an advantage, delivering +-25% to +-50% movement without isocyanate exposure. The combined regulatory and production drivers keep automotive grade sealants on a robust growth path.
Petrochemical Feedstock Price Volatility
With raw materials representing roughly 50% of revenue, French formulators struggle to pass spikes through quarterly construction contracts, compressing EBITDA. BASF's MDI expansion in Geismar may ease tightness by 2027, yet geopolitical risk continues to swing benzene and naphtha costs, exposing sealant makers to margin whiplash. Those without hedging must choose between volume attrition and profit erosion, especially given the persistence of lower-priced Asian imports.
Other drivers and restraints analyzed in the detailed report include:
- Composite Bonding Growth in Airbus and Regional Aerospace Clusters
- Repairability-Index Law Boosting DIY and Appliance Maintenance Sealant Sales
- Stricter EU REACH Limits on Di-Isocyanates Raising Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone captured 38.5% of the France sealants market share in 2025, powered by irreplaceable demand in structural glazing, insulating glass units, and weatherproof facades. Sikasil IG-25 HM Plus meets EN 1279-4 and ASTM C1184, securing gas-retention in vacuum-insulated glazing which commands premium unit prices. Polyurethane is set to pace the France sealants market size expansion, growing 7.24% CAGR during 2026-2031 as EV assemblers bond aluminum, CFRP, and steel modules, substituting welds to cut weight and extend battery range.
Acrylics remain relegated to interior static joints where paintability and near-zero VOC confer decorative advantages, but low movement capability limits outdoor use. Epoxies command niche industrial flooring and aerospace applications where tensile strength and chemical resistance justify slow cure; Baxxodur EC 151 allows functional cure at 5 °C, expanding winter construction windows. Polysulfides and MS polymers fill specialized roles, fuel-tank sealing and isocyanate-free construction joints, respectively, but face medium-term substitution risk from bio-based entrants.
List of Companies Covered in this Report:
- 3M
- Arkema
- BASF SE
- BASFIKA Produits Chimiques
- Bolton Group
- CERMIX
- Den Braven France
- DL Chemicals NV
- Dow
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Illinois Tool Works
- ISPO Group
- MAPEI S.p.A.
- RPM International Inc.
- Saint-Gobain Weber
- Sika AG
- Soprema Group
- Soudal NV
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Renovation-led demand surge in energy-efficient building envelope upgrades
- 4.2.2 EV lightweighting requirements in French automotive production
- 4.2.3 Composite bonding growth in Airbus and regional aerospace clusters
- 4.2.4 Repairability-index law boosting DIY and appliance maintenance sealant sales
- 4.2.5 Marine-grade sealants demand from French offshore-wind build-out
- 4.3 Market Restraints
- 4.3.1 Petrochemical feedstock price volatility
- 4.3.2 Stricter EU REACH limits on di-isocyanates raising compliance costs
- 4.3.3 Emerging bio-based adhesive substitutes eroding conventional sealant share
- 4.4 Value Chain Analysis
- 4.5 Distribution Channel Analysis
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Silicone
- 5.1.2 Polyurethane
- 5.1.3 Acrylic
- 5.1.4 Epoxy
- 5.1.5 Other Resins
- 5.2 By End-user Industry
- 5.2.1 Aerospace
- 5.2.2 Automotive and Transportation
- 5.2.3 Building and Construction
- 5.2.4 Healthcare
- 5.2.5 Other End-user Industries
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)}
- 6.4.1 3M
- 6.4.2 Arkema
- 6.4.3 BASF SE
- 6.4.4 BASFIKA Produits Chimiques
- 6.4.5 Bolton Group
- 6.4.6 CERMIX
- 6.4.7 Den Braven France
- 6.4.8 DL Chemicals NV
- 6.4.9 Dow
- 6.4.10 H.B. Fuller Company
- 6.4.11 Henkel AG & Co. KGaA
- 6.4.12 Illinois Tool Works
- 6.4.13 ISPO Group
- 6.4.14 MAPEI S.p.A.
- 6.4.15 RPM International Inc.
- 6.4.16 Saint-Gobain Weber
- 6.4.17 Sika AG
- 6.4.18 Soprema Group
- 6.4.19 Soudal NV
- 6.4.20 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment