|
시장보고서
상품코드
2066690
싱가포르의 실란트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Singapore Sealants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 싱가포르의 실란트 시장 규모는 2025년 3,211만 달러로 평가되었습니다. 2026년에는 3,339만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 4.27%로 성장을 지속하여, 2031년에는 4,115만 달러에 이를 것으로 예측됩니다.

본 보고서는 수지 유형(아크릴, 에폭시, 폴리우레탄, 실리콘, 기타 수지) 및 최종 사용자 산업(항공우주, 자동차, 건축 및 건설, 의료, 기타 최종 사용자 산업)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
싱가포르의 실란트 시장 동향 및 분석
공공 부문 인프라 구축 계획의 가속화
주롱 리전 라인, 크로스 아일랜드 라인 1단계, 서클 라인 6단계, 톰슨 이스트 코스트 라인 5단계, 다운타운 라인 3단계 동쪽 구간 등 5개의 철도 프로젝트가 동시에 진행 중이며, 이를 통해 수십 개의 역이 신설될 예정입니다. 이러한 역에서는 내화 사양의 터널, 승강장, 대합실의 접합부가 필요하기 때문에 속경화·저수축성 실리콘, 폴리우레탄, 폴리설파이드계 실란트에 대한 연간 수요가 지속될 것으로 예측됩니다. 도시재개발청(URA)의 마스터플랜에는 8만 호 이상의 신규 주택 공급이 약속되어 있으며, 주택개발청(HDB)의 자료에 따르면 2026년 127건의 프로젝트가 진행 중이어서, 이를 통해 향후 수년에 걸친 실란트 수요가 확실하게 확보되어 있습니다. CONQUAS 2025에서는 기능 시험 결과가 임시 사용 허가 발급과 연계되게 됨에 따라, 단 한 번의 시공으로 누수가 없는 유리 시공과 물 고임 기준을 충족하는 제품에 대한 평가가 높아지고 있습니다. 따라서 시공업체들은 프라이머가 필요 없는 접착력과 뛰어난 신축성을 갖추고, 보수 주기를 단축할 수 있는 배합을 선호하는 경향이 있습니다. 현장 교육 및 속경화형 모형을 제공하는 유통업체은 사양 채택률을 높이고 재주문을 촉진할 수 있습니다.
녹색 인증을 획득한 건축 외피로의 전환
싱가포르의 ‘그린마크’ 지침에서는 제품 수명 주기 전반에 걸친 탄소 발자국 감축을 중시하고 있으며, 저배출 실란트의 사용을 권장하고 있습니다. 이러한 실란트는 GEV EMICODE EC1 PLUS, 싱가포르 그린 라벨 또는 이에 상응하는 인증을 취득해야 합니다. Sika사의 제품인 ‘Sikaflex Purform’ 및 ‘SikaTop-540 Seal’은 다양한 실내 공기질 기준을 준수하며, 개발자가 ‘에너지 및 환경 설계 리더십(LEED)’ 크레딧을 획득할 수 있도록 지원합니다. 또한, 이러한 제품들은 연면적과 관련된 우대 조치를 포함한 ‘그린 마크’ 인센티브 획득을 개발사가 달성하는 데 도움이 됩니다. 헨켈이 신설한 ‘지네오 사이언스파크’ 연구소는 국가환경청의 용제 규제 도입을 대비해 퍼플루오로알킬 물질을 포함하지 않는 연구 개발을 가속화하고 있으며, 회사는 조기에 규정을 준수할 수 있는 체제를 갖추고 있습니다. 이소시아네이트나 방향족 화합물의 방출량이 극히 적은 습기 경화형 폴리우레탄과 하이브리드 실릴 말단 폴리머는 작업장 내 노출 기준이 강화됨에 따라 시장 점유율을 확대되고 있습니다. 개발업체들은 지반 아래의 방수 공사에서 2액형 에폭시·폴리우레탄 하이브리드 자재를 점점 더 많이 지정하고 있습니다. 이는 수축이 전혀 없어, 매립지 연안 지역 등 지하수위가 높은 곳에서 박리 현상을 방지할 수 있기 때문입니다.
중국공급 상황에 따라 달라지는 실리콘 폴리머 수입 가격의 변동
중국의 금속 실리콘 제련소에 대한 환경 규제를 배경으로, 디메틸카보네이트의 현물 프리미엄이 상승했고, 아시아와 유럽 간의 리드타임이 크게 늘어났습니다. 수입에 전적으로 의존하고 있는 싱가포르에서는 고정 가격 공개 입찰로 인해 비용 전가가 어려워지면서, 판매업자들이 비용 급등분을 흡수하게 되었습니다. 아크릴계나 하이브리드 폴리머로 전환한 기업도 있었지만, 변형량이 많거나 자외선(UV) 내구성이 필수적인 경우, 대체품으로의 전환은 보증 위반의 위험을 수반합니다. 여러 지역에서 원자재를 조달하는 다국적 기업들은 원자재 리스크를 분산시켰지만, 중소규모 기업들은 재고를 늘리는 수밖에 없어 운전자금에 부담이 가중되었습니다.
부문별 분석
2025년, 실리콘은 뛰어난 자외선 저항성과 -40°C-100°C의 사용 온도 범위를 특징으로 하여 싱가포르의 실란트 시장에서 38.50%의 점유율을 유지했습니다. 그러나 2026년부터 2031년에 걸쳐 폴리우레탄은 연평균 성장률(CAGR) 6.21%를 기록하며, 싱가포르 전체 실란트 시장의 성장률을 상회할 것으로 전망됩니다. 이는 건축가가 유리 파사드나 프리캐스트 콘크리트의 이음매에 대해, 낮은 탄성 계수와 높은 변위 흡수 능력을 갖춘 제품을 지정하고 있기 때문입니다. ‘SikaHyflex 250 Facade’는 큰 변위를 견딜 수 있도록 설계되어 있어, 시공업체는 본딩 브레이커 테이프를 사용하지 않고도 이음매 폭을 넓힐 수 있습니다. 습도가 높은 환경에서는 순수 실리콘계 제품이 문제를 일으키는 경우가 많지만, PENOSIL Facade Joint Hybrid 25LM과 같은 하이브리드 MS 폴리머는 매우 효과적입니다. 이 폴리머들은 습한 바탕에도 잘 접착되며, 엄격한 배출 기준도 충족합니다. 한편, 아크릴계 및 부틸계 매스틱은 특히 비용 효율이 필수적인, 변위가 제한적인 용도에서 실내 트림이나 방습층 시공에 여전히 선호되고 있습니다.
용제계 폴리설파이드에서 습기 경화형 화학계로 전환되는 추세는 2028년까지 항공우주용 실란트에서 파라클로로벤조트리플루오라이드의 사용을 금지하는 사우스코스트 대기질 관리 구역(AQMD) 규정 1124에 따라 가속화되고 있으며, 이는 싱가포르의 사양에도 파급될 전 세계적인 공급 합리화의 조짐을 보여주고 있습니다. ‘제품 가중 최대 증분 반응성(PWMIR)’을 준수하는 촉매를 제공하는 제조업체들의 대응은 기존의 폴리설파이드보다 폴리우레탄 및 하이브리드 플랫폼을 구조적으로 우대하는 규제 동향을 여실히 보여주고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.29According to Mordor Intelligence, the singapore sealants market size is expected to grow from USD 32.11 million in 2025 to USD 33.39 million in 2026 and is forecast to reach USD 41.15 million by 2031 at 4.27% CAGR over 2026-2031.
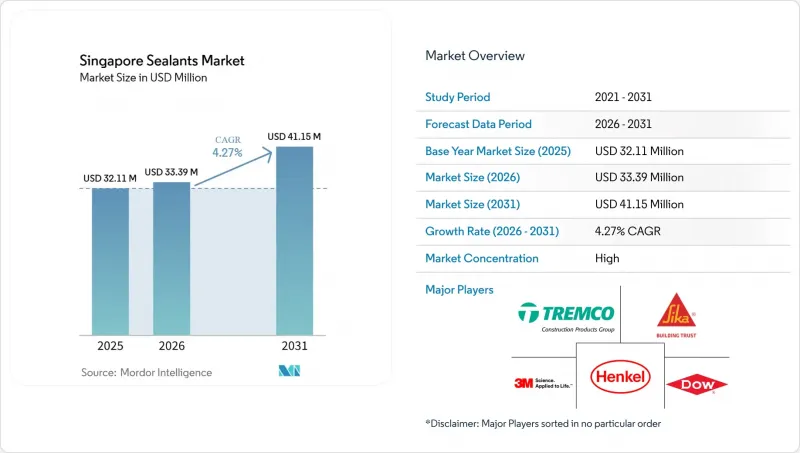
This report is Segmented by Resin Type (Acrylic, Epoxy, Polyurethane, Silicone, and Other Resins ) and End-User Industry (Aerospace, Automotive, Building and Construction, Healthcare, and Other End-User Industries). The Market Forecasts are Provided in Terms of Value (USD).
Singapore Sealants Market Trends and Insights
Accelerated Public-Sector Infrastructure Pipeline
Five concurrent rail packages, the Jurong Region Line, Cross Island Line Stage 1, Circle Line Stage 6, Thomson-East Coast Line Stage 5, and Downtown Line Stage 3 East, will introduce dozens of stations that require fire-rated tunnel, platform, and concourse joints, sustaining annual demand for fast-cure, low-shrink silicone, polyurethane, and polysulfide grades. The Urban Redevelopment Authority's Master Plan pledges more than 80,000 new residential units, while Housing and Development Board data lists 127 active projects in early 2026, collectively locking in multi-year sealant volumes. CONQUAS 2025 now ties functional-test results to Temporary Occupation Permit issuance, elevating the premium on products that achieve leak-free glazing and ponding compliance in a single pass. Contractors, therefore, favor formulations with primer-less adhesion and extended movement capability that shorten remediation cycles. Distributors that supply site training and accelerated-cure mock-ups strengthen specification pull-through and repeat orders.
Transition to Green-Certified Building Envelopes
Singapore's Green Mark guidelines emphasize reducing life-cycle carbon footprints and encourage the use of low-emission sealants. These sealants must hold certifications such as GEV EMICODE EC1 PLUS, the Singapore Green Label, or equivalent. Sika's products, Sikaflex Purform and SikaTop-540 Seal, comply with various indoor-air-quality standards, supporting developers in obtaining Leadership in Energy and Environmental Design (LEED) credits. Additionally, these products help developers qualify for Green Mark incentives, including gross floor area benefits. Henkel's new Geneo Science Park lab accelerates perfluoroalkyl-substance-free research and development ahead of anticipated National Environment Agency solvent limits, keeping the firm positioned for early compliance bids. Moisture-cure polyurethanes and hybrid silyl-terminated polymers, which emit negligible isocyanates or aromatics, gain share as workplace exposure limits tighten. Developers increasingly specify two-component epoxy-polyurethane hybrids for below-grade waterproofing because they deliver zero shrinkage and prevent delamination in high water-table sites along reclaimed coasts.
Volatile Silicone Polymer Import Prices Tied to China Supply
Spot premiums for dimethyl carbonate increased, and lead times between Asia and Europe lengthened significantly, driven by China's environmental restrictions on silicon-metal smelters. Singapore, fully import-dependent, saw distributors absorb cost spikes because fixed-price public tenders prevented pass-through. Some shifted to acrylic or hybrid polymers, but substitution risks warranty breaches where high movement or ultraviolet (UV) durability is mandatory. Multinationals with multi-regional sourcing diversified feedstock exposure, while smaller players relied on higher inventory holdings, straining working capital.
Other drivers and restraints analyzed in the detailed report include:
- Semiconductor Clean-Room Expansion
- Growing aircraft Maintenance, Repair, and Overhaul (MRO) hub status
- Shrinking Public-Housing Backlog Post-Handover Peak
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone retained 38.50% of the Singapore sealants market share in 2025, owing to superior UV resistance and -40 °C to 100 °C service capability. However, polyurethane's 6.21% CAGR from 2026 to 2031 outpaces the overall Singapore sealants market size as architects specify low-modulus, high-movement products for glass facades and precast concrete joints. SikaHyflex 250 Facade is designed to accommodate significant movement, allowing contractors to widen joints without requiring bond-breaker tape. In humid conditions, where pure silicones often face challenges, hybrid MS-polymers like PENOSIL Facade Joint Hybrid 25LM are highly effective. These polymers adhere well to damp substrates and achieve high emissions standards. Meanwhile, acrylic and butyl mastics continue to be preferred for interior trim and vapor-barrier details, particularly in applications where cost sensitivity is critical, and movement is limited.
The transition from solvent-borne polysulfides to moisture-cure chemistries accelerates under South Coast Air Quality Management District (AQMD) Rule 1124, which bans para-chlorobenzotrifluoride in aerospace sealants by 2028, signaling global supply rationalization that will ripple into Singapore specifications. Producers responding with Product-Weighted Maximum Incremental Reactivity-compliant catalysts highlight a regulatory trend that structurally favors polyurethane and hybrid platforms over legacy polysulfides.
List of Companies Covered in this Report:
- 3M
- Alteco Chemical Pte Ltd.
- Dow
- Fosroc, Inc.
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- MAPEI S.p.A.
- PFE Technologies Pte Ltd
- Shin-Etsu Chemical Co., Ltd.
- Sika AG
- Soudal Group
- Tremco Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated public-sector infrastructure pipeline
- 4.2.2 Transition to green-certified building envelopes
- 4.2.3 Semiconductor clean-room expansion
- 4.2.4 Growing aircraft MRO hub status at Seletar and Changi
- 4.2.5 Government incentives for low-VOC materials
- 4.3 Market Restraints
- 4.3.1 Volatile silicone polymer import prices tied to China supply
- 4.3.2 Shrinking public-housing backlog post-HDB 2025 handover peak
- 4.3.3 Tight migrant-labour quotas raising on-site application costs
- 4.4 Value Chain Analysis
- 4.5 Distribution Channel Analysis
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Acrylic
- 5.1.2 Epoxy
- 5.1.3 Polyurethane
- 5.1.4 Silicone
- 5.1.5 Other Resins
- 5.2 By End-user Industry
- 5.2.1 Aerospace
- 5.2.2 Automotive
- 5.2.3 Building and Construction
- 5.2.4 Healthcare
- 5.2.5 Other End-user Industries
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Alteco Chemical Pte Ltd.
- 6.4.3 Dow
- 6.4.4 Fosroc, Inc.
- 6.4.5 H.B. Fuller Company
- 6.4.6 Henkel AG & Co. KGaA
- 6.4.7 MAPEI S.p.A.
- 6.4.8 PFE Technologies Pte Ltd
- 6.4.9 Shin-Etsu Chemical Co., Ltd.
- 6.4.10 Sika AG
- 6.4.11 Soudal Group
- 6.4.12 Tremco Incorporated
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment