

|
시장보고서
상품코드
2072612
인도의 트럭 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2025-2030년)India Truck - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2025 - 2030) |
||||||
 Mordor Intelligence
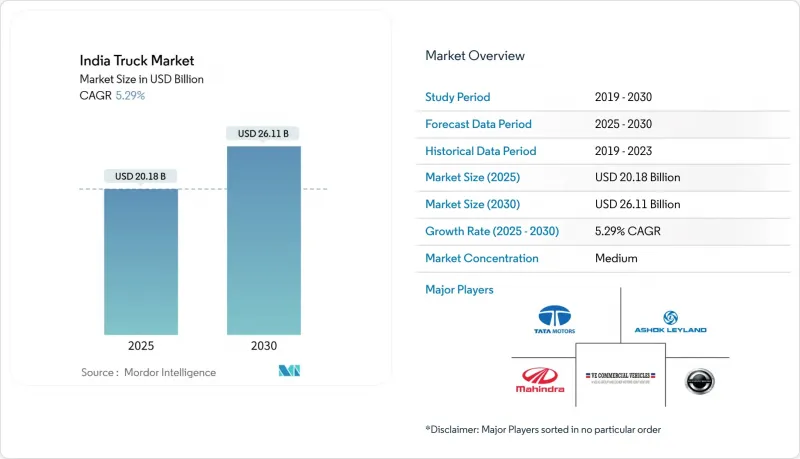
에 의하면, 인도의 트럭 시장 규모는 2025년에 201억 8,000만 달러로 평가되었고, 2030년까지 261억 1,000만 달러에 이를 것으로 예측되며, CAGR은 5.29%로 전망됩니다.

본 보고서는 차종별(소형, 중형, 기타), 적재량별(3.5-7.5톤, 7.5-16톤, 기타), 연료 유형별(디젤, 가솔린, 기타), 용도별(물류, 건설, 기타), 소유 형태별(차량 대여 업체 및 개인 소유자), 차체 유형별(플랫베드, 박스 트럭, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
인도의 트럭 시장 동향 및 인사이트
정부의 인프라 구축 추진(바라트마라, 가티 샤크티)
2024 회계연도, 인도 국도청(NHAI)은 국도 건설에 무려 2조 700억 루피(247억 9,000만 달러)를 투자하며 새로운 기준을 세웠습니다. 이 자본 지출은 사상 최고치를 기록했으며, 전 회계연도 대비 20% 증가했습니다. 2025-26년도 연방 예산에서 정부는 도로운송 및 고속도로부에 2조 8,733억 3,000만 루피(330억 7,000만 달러)를 배정했습니다. 이는 25년도 배분액 대비 2.41%의 소폭 증가에 해당합니다. 2025년까지 19,201km에 달하는 경제 회랑이 완공됨에 따라, 이미 덤프트럭과 트랙터 트레일러의 가동률이 향상되고 있습니다. 새로운 축중량 기준은 대용량 차량군에 대응하며, OEM의 섀시 설계 지침이 되고 있습니다. 인도의 트럭 시장은 시멘트, 철강, 석탄의 대량 운송에 최적화된, 더 중량급 사양으로 이에 대응하고 있습니다. 델리-뭄바이 노선만 보더라도 화물 밀도가 증가하고 있어, 트럭의 총 소유 비용을 개선하는 연속 운행 주기를 뒷받침하고 있습니다.
전자상거래가 주도하는 물류 붐
인도의 물류 부문은 소포 배송의 급증에 힘입어 급속한 변화를 겪고 있으며, 이는 인도 트럭 시장에서 트럭 운송 서비스에 대한 지속적인 수요를 뒷받침하고 있습니다. 주요 전자상거래 기업들은 보다 신속한 서비스를 원하는 소비자들의 높아지는 기대에 부응하기 위해 배송 네트워크와 인프라를 확대되고 있습니다. 물류 업무가 중소 도시로 더욱 깊이 확산됨에 따라, 화물 운송 경로는 새로운 소비 거점을 향해 재편되고 있으며, 도시 환경에 적합하고 기동성이 뛰어난 소형 차량에 대한 수요가 증가하고 있습니다. 텔레매틱스 기술의 발전으로 인해 경로 효율성과 차량 생산성이 향상됨에 따라, 트럭 운송 생태계는 변화하는 시장 역학에 더욱 신속하게 대응하고 최적화되고 있습니다.
BS-VI 규정을 준수하는 트럭에 대한 설비 투자
BS-VI 규격에 대한 의무적 대응 및 에어컨이 장착된 운전실 도입으로 인해, 2025년 10월 이후, 차량 1대당 2만-3만 루피(250-375 달러)의 추가 비용이 발생할 것으로 예상되며, 2026 회계연도 업계 전체의 설비 투자액은 600억 루피(7억 5,000만 달러)에 달할 전망입니다. 여전히 전체 보유 대수의 70%를 차지하는 소규모 사업자들은 월별 상환액(EMI) 증가로 어려움을 겪고 있으며, 이로 인해 차량 교체 시기가 늦어지면서 인도 트럭 시장의 단기적인 수요가 위축되고 있습니다.
부문별 분석
2024년 출하 대수의 48.33%를 차지한 소형 트럭은 인도 트럭 시장의 주축으로 자리 잡고 있으며, 2030년까지 연평균 성장률(CAGR) 6.94%를 나타낼 것으로 전망됩니다. 도시 지역의 도로 규제나 전자상거래 배송 시간대 제약으로 인해, 밀집된 시가지를 누비듯 주행할 수 있는 휠베이스가 짧은 차량이 선호되고 있습니다. OEM을 통한 금융 제도와 유지보수 비용이 낮은 전기차의 구동 시스템이 더해지면서, 수요는 이 등급으로 더욱 쏠리고 있습니다. 중형 트럭은 지역 간 급행 노선을 담당하는 반면, 대형 트랙터는 시멘트, 철강, 석탄의 운송 노선에서 주류를 이루고 있습니다. 소형 트럭의 전기화는 공공 송전망의 제약을 피할 수 있도록 지원하는 디포 충전기의 도움으로, 200km의 도심 노선에서 신속한 투자 회수를 실현하고 있습니다.
Magenta Mobility사의 3톤 전기차와 같은 2세대 모델은 현재 하루 3회 왕복을 소화하며, 자산 생산성을 2배로 높이고 비용 곡선을 재구성하고 있습니다. 한편, 3급 무역 클러스터에서 톤마일 수요가 증가함에 따라 내연기관 모델에 대한 수요도 여전히 존재하며, 이 부문은 인도 트럭 시장에서 여전히 필수적인 성장 동력으로 자리 잡고 있습니다.
3.5-7.5톤급 트럭은 2024년 판매 대수의 39.18%를 차지했습니다. 이는 단순한 적재 능력보다는 적재량의 유연성이 요구되는 인도의 세밀한 소매 네트워크를 반영한 것입니다. 옴니채널 소매업체들이 마이크로 창고로의 신속한 재고 보충을 추진함에 따라, 해당 등급의 연평균 성장률(CAGR)은 7.14%로 다른 모든 적재량 등급을 상회하고 있습니다. 지자체에서 시행하는 엄격한 차축 규제와 낮은 교량 통행 높이 제한은 소형 트럭의 유용성을 더욱 높여주고 있습니다.
고속도로 정비가 지속된다면, 허브 간 노선의 화물 운송은 점차 총중량 16톤 차량으로 전환될 가능성이 있지만, 문 앞 배송 수요로 인해 7.5톤 미만 차량에 대한 수요는 계속해서 호조를 보일 전망입니다. 전략적으로, 각 OEM 업체들은 모듈식 바디 키트를 채택하여 플랫폼의 경제성을 높이고, 새로운 형식 인증 절차를 거치지 않고 SKU의 다양화를 통해 인도 트럭 시장 규모를 확대되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.07.07According to Mordor Intelligence, the indian truck market size stood at USD 20.18 billion in 2025 and is forecast to reach USD 26.11 billion by 2030, reflecting a 5.29% CAGR.
This report is Segmented by Vehicle Type (Light Duty, Medium Duty, and More), Tonnage Capacity (3. 5-7. 5 Tons, 7. 5-16 Tons, and More), Fuel Type (Diesel, Petrol, and More), Application (Logistics, Construction, and More), Ownership (Fleet Operators and Individual Owners), Body Type (Flatbed, Box Truck, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
India Truck Market Trends and Insights
Government Infrastructure Push (Bharatmala, Gati Shakti)
In FY24, the National Highways Authority of India (NHAI) set a new benchmark by investing a staggering Rs. 2,07,000 crore (USD 24.79 billion) in national highway construction. This capital outlay marked a record high, surging 20% from the previous fiscal year. For the Union Budget 2025-26, the government earmarked Rs. 2,87,333.3 crore (USD 33.07 billion) for the Ministry of Road Transport and Highways, a modest 2.41% increase from FY25's allocations. Completing 19,201 km of economic corridors by 2025 already lifts tipper and tractor-trailer utilization. New axle-load norms align with higher-capacity fleets, guiding OEM chassis design. The Indian truck market responds with heavier configurations optimized for bulk cement, steel, and coal haulage. Rising freight density on the Delhi-Mumbai route alone supports continuous-duty cycles that improve truck total cost of ownership.
E-commerce-Led Logistics Boom
India's logistics sector is experiencing a rapid transformation, driven by a sharp rise in parcel deliveries, fueling continuous demand for trucking services in the India truck market. Leading e-commerce companies are expanding their delivery networks and infrastructure to meet growing consumer expectations for faster service. As logistics operations extend deeper into smaller cities, freight routes are reoriented toward new consumption hubs, increasing the need for agile, light-duty vehicles suited for urban environments. Technological advancements in telematics enhance route efficiency and vehicle productivity, making the trucking ecosystem more responsive and optimized for evolving market dynamics.
High BS-VI Truck Capex
Mandatory BS-VI upgrades and AC cabs add INR 20,000-30,000 (USD 250-375) per unit from October 2025, elevating industry capex to INR 60 billion (USD 750 million) in FY26 . Small operators, still 70% of ownership, struggle with higher EMIs, delaying fleet refresh, and dampening near-term demand within the India truck market.
Other drivers and restraints analyzed in the detailed report include:
- Scrappage Policy-Driven Replacement Demand
- Shift to CNG/LNG on TCO Benefits
- Volatile Diesel Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Light-duty trucks held 48.33% of 2024 shipments, underpinning the India truck market while posting a 6.94% CAGR through 2030. Urban road restrictions and e-commerce time windows favor compact wheelbases that weave through dense streets. OEM financing schemes and low-maintenance EV drivetrains further tilt demand toward this class. Medium-duty units cater to regional express lines, whereas heavy tractors dominate cement, steel, and coal corridors. Light-duty electrification unlocks rapid payback on 200-km urban routes, supported by depot chargers that bypass public-grid constraints.
Second-generation models such as Magenta Mobility's 3-ton EV now complete three turns daily, doubling asset productivity and reshaping cost curves. Meanwhile, rising ton-mile demand from Tier-3 trade clusters preserves internal-combustion variants, keeping the segment an indispensable growth engine within the India truck market.
Trucks in the 3.5-7.5 ton band captured 39.18% of 2024 volume, reflecting India's granular retail networks that call for payload agility rather than brute capacity. Their 7.14% CAGR stands above all other tonnage classes as omnichannel retailers push fast replenishment to micro-warehouses. Tight municipal axle mandates and low-bridge clearances reinforce small-tonnage utility.
Continued highway upgrades could gradually swing freight toward 16-ton gross vehicle weights for hub-to-hub lanes, yet doorstep delivery promises keep sub-7.5-ton demand vibrant. Strategically, OEMs overlay modular body kits to stretch platform economics, augmenting the India truck market size through SKU diversity without new homologation cycles.
Complete Report Scope:
- By Vehicle Type
- Light Duty
- Medium Duty
- Heavy Duty
- By Tonnage Capacity
- 3.5-7.5 Tons
- 7.5-16 Tons
- 16-30 Tons
- Above 30 Tons
- By Fuel Type
- Diesel
- Petrol
- Electric
- Other Fuel Type
- By Application
- Logistics
- Construction
- Agriculture
- Mining
- Utility
- Others
- By Ownership
- Fleet Operators
- Individual Owners
- By Body Type
- Flatbed
- Box Truck
- Refrigerated
- Tanker
- Tipper
List of Companies Covered in this Report:
- Tata Motors Limited
- Ashok Leyland
- Mahindra & Mahindra Limited
- VE Commercial Vehicles Ltd. (Eicher)
- BharatBenz (Daimler India Commercial Vehicles)
- Volvo Trucks India
- Scania Commercial Vehicles India Pvt. Ltd.
- Force Motors Limited
- Isuzu Motors India Private Limited
- Hino Motors India
- Olectra Greentech
- BYD India
- Omega Seiki Mobility
- Tresa Motors
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Infrastructure Push (Bharatmala, Gati Shakti)
- 4.2.2 E-commerce-Led Logistics Boom
- 4.2.3 Scrappage Policy-Driven Replacement Demand
- 4.2.4 Shift to CNG/LNG on TCO Benefits
- 4.2.5 Cold-Chain Expansion in Tier-2/3 Cities
- 4.2.6 Connected-Truck Telematics Adoption
- 4.3 Market Restraints
- 4.3.1 High BS-VI Truck Capex
- 4.3.2 Volatile Diesel Prices
- 4.3.3 Driver Shortage and Aging Workforce
- 4.3.4 Sparse Heavy-Duty Charging Network
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value and Volume)
- 5.1 By Vehicle Type
- 5.1.1 Light Duty
- 5.1.2 Medium Duty
- 5.1.3 Heavy Duty
- 5.2 By Tonnage Capacity
- 5.2.1 3.5-7.5 Tons
- 5.2.2 7.5-16 Tons
- 5.2.3 16-30 Tons
- 5.2.4 Above 30 Tons
- 5.3 By Fuel Type
- 5.3.1 Diesel
- 5.3.2 Petrol
- 5.3.3 Electric
- 5.3.4 Other Fuel Type
- 5.4 By Application
- 5.4.1 Logistics
- 5.4.2 Construction
- 5.4.3 Agriculture
- 5.4.4 Mining
- 5.4.5 Utility
- 5.4.6 Others
- 5.5 By Ownership
- 5.5.1 Fleet Operators
- 5.5.2 Individual Owners
- 5.6 By Body Type
- 5.6.1 Flatbed
- 5.6.2 Box Truck
- 5.6.3 Refrigerated
- 5.6.4 Tanker
- 5.6.5 Tipper
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Tata Motors Limited
- 6.4.2 Ashok Leyland
- 6.4.3 Mahindra & Mahindra Limited
- 6.4.4 VE Commercial Vehicles Ltd. (Eicher)
- 6.4.5 BharatBenz (Daimler India Commercial Vehicles)
- 6.4.6 Volvo Trucks India
- 6.4.7 Scania Commercial Vehicles India Pvt. Ltd.
- 6.4.8 Force Motors Limited
- 6.4.9 Isuzu Motors India Private Limited
- 6.4.10 Hino Motors India
- 6.4.11 Olectra Greentech
- 6.4.12 BYD India
- 6.4.13 Omega Seiki Mobility
- 6.4.14 Tresa Motors
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


