

|
시장보고서
상품코드
2072814
미국의 수의용 의료장비 및 소모품 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Veterinary Equipment and Disposables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
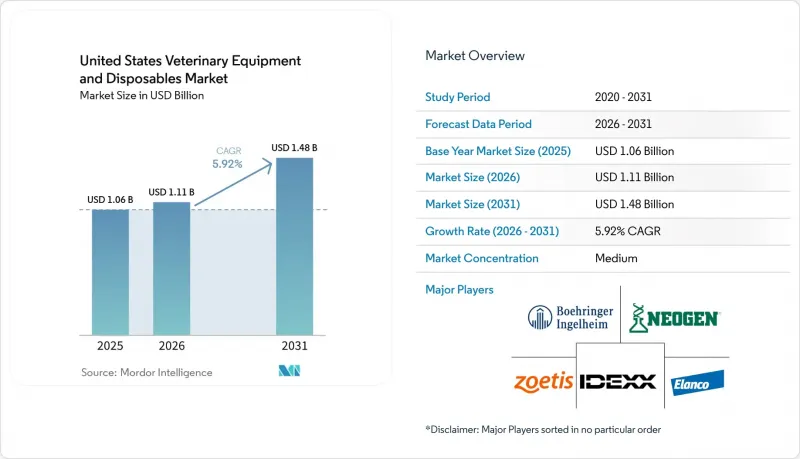
에 의하면, 미국의 수의용 의료장비 및 소모품 시장 규모는 2025년에 10억 6,000만 달러로 평가되었고, 2026년 11억 1,000만 달러로 추정되고, 2031년까지 14억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.92%를 나타낼 전망입니다.
본 보고서는 제품별(기기 및 부속품(마취 기기 등), 일회용 제품 및 소모품(주사기 및 바늘 등)), 동물 유형별(소동물, 대동물), 용도별(외과, 진단, 모니터링), 최종 용도별(동물병원, 동물병원, 연구 기관 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국의 수의용 의료장비 및 소모품 시장 동향과 인사이트
반려동물에 대한 시술 건수 증가
미국의 수의용 의료장비 및 소모품 시장은 무엇보다도 반려동물의 사육 마릿수와 돌봄 활동의 규모에 의해 주도되고 있습니다. 미국 반려동물 제품 협회(American Pet Products Association)의 보고서에 따르면, 2025년에는 미국 가구의 53%가 개를, 39%가 고양이를 키우고 있는 반면, 미국 수의사 협회(American Veterinary Medical Association)의 보고서에 따르면 국내 반려견 수는 8,730만 마리, 반려묘 수는 7,630만 마리에 달할 것으로 추정됩니다. 이러한 환자 수 증가로 인해 예방접종, 일상적인 수술, 치과 치료, 영상 진단 및 진료소 내 진단 검사에 대한 수요가 높아지고 있습니다. 또한, 반려동물이 만성 질환을 앓는 사례가 증가하고 있어, 반복적인 모니터링과 장기적인 치료가 필요하기 때문에 돌봄의 부담도 더욱 복잡해지고 있습니다. 미국수의사협회(AVMA)는 2026년, 미국의 개와 고양이 중 절반 이상이 과체중이거나 비만일 것이라고 발표했습니다. 이로 인해 마취 및 수술 전후 기간의 위험이 높아지면서, 모니터링 장비와 중환자 치료용 소모품의 사용 확대가 촉진되고 있습니다.
일회용 감염 관리 용품으로의 전환
미국의 수의용 의료장비 및 소모품 시장도 외과 및 중환자 치료 현장에서 일회용 멸균 제품으로 전환되고 있습니다. 환자 회전율이 높은 진료소에서는 수술실 회전 시간 단축, 추적성 간소화, 그리고 멸균 작업 부담 경감이 요구되고 있으며, 이에 따라 주사기, 드레이프, 수액 용품 및 기타 일회용 제품이 더욱 주목받고 있습니다. 또한, 기업 네트워크에서는 공급업체 목록의 표준화가 진행되고 있으며, 이로 인해 승인된 공급업체의 선택 폭이 좁아지면서 기준을 충족하는 소모품의 재구매율이 상승하고 있습니다. Covetrus사에 따르면, 이 회사의 VetSuite 네트워크는 서비스 개시 이후 독립 동물병원에 3,000만 달러 이상의 실질적인 비용 절감을 가져다주었습니다. 이는 공동 구매를 통해 더 높은 수준의 소모품을 대규모로 도입하기가 쉬워졌음을 보여줍니다. 그 결과, 소모품 수요 패턴은 일시적인 설비 투자 주기의 영향을 덜 받게 되었으며, 일상적인 진료 처리 능력과 연동되는 경향이 더욱 강해지고 있습니다.
영상 진단 및 수술용 플랫폼의 높은 초기 비용
미국의 수의용 의료장비 및 소모품 시장은 여전히 첨단 장비의 초기 비용이라는 큰 장벽에 직면해 있습니다. CT 시스템, MRI 플랫폼, 디지털 X선 장비, 내시경 타워에는 막대한 설비 투자가 필요하며, 많은 독립형 또는 단일 지점 진료소의 경우 대출 없이는 그 비용을 감당할 수 없습니다. 미국수의사협회(AVMA)는 CareCredit의 조사 결과를 인용하여, 전문 수의학적 치료를 고려 중인 반려동물 주인의 80%에게 비용이 가장 큰 우려 사항임을 밝혔습니다. 이 때문에 진료소 측은 안정적이고 고부가가치가 높은 환자 유입에 의존하는 장비에 대한 투자에 더욱 신중을 기하고 있습니다. 대규모 그룹은 조달 비용을 여러 시설에 분산시켜 공급업체와의 협상에서 더 유리한 조건을 이끌어낼 수 있지만, 소규모 운영자는 매 구매마다 발생하는 비용을 모두 부담해야 합니다. '섹션 179'의 지원 및 자금 조달 옵션은 미국의 수의용 의료장비 및 소모품 시장을 뒷받침하고 있지만, 기업 네트워크와 독립 동물병원 간의 격차를 완전히 해소하는 것은 아닙니다.
부문별 분석
2025년, 미국의 수의용 의료장비 및 소모품 시장 점유율 중 57.48%를 기기 및 부속품이 차지했습니다. 이는 전미에 걸쳐 마취, 모니터링, 영상 진단 및 수액 관리 시스템의 도입 대수가 매우 많다는 점을 반영하고 있습니다. 미국의 수의용 의료장비 및 소모품 시장은 여전히 자본재에 치우쳐 있습니다. 이는 이러한 플랫폼들이 일반 진료와 전문 진료 모두에서 외과, 응급, 입원 환자의 업무 흐름의 기반이 되고 있기 때문입니다. 마취 장비와 환자 모니터는 선택적 수술, 응급 처치, 중환자실 치료 등 모든 상황에서 필요하기 때문에 시술 건수 측면에서 핵심적인 역할을 계속해서 수행하고 있습니다. 연구용 장비와 응급 및 소생 시스템은 여전히 소규모 분야이지만, 협력 병원, 수의과대학, 교육 기관에서 확고한 입지를 차지하고 있습니다.
일회용 제품 및 소모품 부문이 가장 빠른 성장세를 보일 것으로 예상되며, 이 부문의 미국 수의용 의료장비 및 소모품 시장 규모는 2031년까지 연평균 성장률(CAGR) 7.36%로 확대될 것으로 전망됩니다. 이 부문은 주사기, 바늘, 수액용 부속품, 수액 세트, 튜브, 카테터, 수술용 드레이프, 봉합사, 상처 관리 용품 등 재주문 빈도가 높은 제품들로부터 혜택을 보고 있습니다. 대규모 동물병원 그룹을 중심으로 표준화가 진행되고 있어 구매 동향을 예측하기가 더 쉬워졌으며, 이는 폭넓은 제품 라인업과 통합된 발주 지원 체계를 갖춘 공급업체에게 유리하게 작용하고 있습니다. Covetrus사에 따르면, 이 회사의 VetSuite 네트워크는 전미의 독립 동물병원들에 비용 절감을 가져다주고 있으며, 이를 통해 이전에는 주로 단가로 경쟁하던 표준화된 소모품의 도입이 촉진되고 있습니다.
2025년에는 소동물이 해당 부문의 59.17%를 차지했으며, 이에 따라 반려동물 의료는 미국 수의용 의료장비 및 소모품 시장에서 계속해서 중심적인 위치를 차지하고 있습니다. 이러한 현상은 개와 고양이를 키우는 가구가 많아지고, 반려인들이 이전보다 더 많은 검사, 수술, 예방 의료를 수용하는 경향이 있는 것과 관련이 있습니다. 일반 진료소에서 의뢰 전 처리하는 증례의 범위가 넓어짐에 따라, 병원 내 생화학 검사 시스템, 혈액학 분석기, 마취 플랫폼 및 모니터링 기기의 이용이 확대되고 있습니다. 또한, 미국의 수의용 의료장비 및 소모품 시장은 반려동물 관리 분야에서 웰니스 지향적 접근 방식이 확산됨에 따라 혜택을 보고 있으며, 이로 인해 현장 진단 및 일상적인 소모품에 대한 지속적인 수요가 증가하고 있습니다.
대형 동물 부문은 가장 빠르게 성장하고 있는 부문이며, 이 부문의 미국 수의용 의료장비 및 소모품 시장 규모는 2031년까지 연평균 성장률(CAGR) 8.87%로 확대될 것으로 전망됩니다. 이러한 성장은 휴대용 초음파 진단 기기, 현장 진료용 혈액 분석 기기, 그리고 고정된 진료 시설 밖에서도 사용할 수 있는 현장 대응형 수액 관리 제품에 대한 관심이 높아진 데 힘입은 것입니다. 조에티스사는 2026년 2월, 네오젠사의 동물 유전체학 사업을 인수한다고 발표했습니다. 이는 가축 건강 관리 분야에서 보다 정밀한 진단 및 모니터링 기법에 대한 수요가 증가하고 있음을 시사합니다. 또한, 미국 반려동물 제품 협회(APPA)의 보고서에 따르면, 미국에서는 200만 가구가 말을 기르고 있으며, 거리나 접근성이 여전히 장비 선택에 영향을 미치는 말 진료 현장에서 이동형 진료 서비스에 대한 수요를 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.07.07According to Mordor Intelligence, the united states veterinary equipment and disposables market size was valued at USD 1.06 billion in 2025 and is estimated to grow from USD 1.11 billion in 2026 to reach USD 1.48 billion by 2031, at a CAGR of 5.92% during the forecast period (2026-2031).
This report is Segmented by Product (Equipment and Accessories {Anesthesia Equipment, and More}, Disposables and Consumables {Syringes and Needles, and More}), Animal Type (Small Animals, Large Animals), Usage (Surgical, Diagnostic, Monitoring), End Use (Veterinary Clinics, Hospitals, Research Institutes, and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Veterinary Equipment and Disposables Market Trends and Insights
Rising Companion Animal Procedural Volume
The United States veterinary equipment and disposables market is being driven first by the scale of companion animal ownership and care activity. The American Pet Products Association reported that 53% of US households owned dogs and 39% owned cats in 2025, while the American Veterinary Medical Association reported 87.3 million owned dogs and 76.3 million owned cats in the country. That larger patient pool lifts demand for vaccinations, routine surgeries, dental procedures, imaging, and in-clinic diagnostic tests. The care burden is also becoming more complex because pets are living with more chronic conditions that require repeated monitoring and longer treatment pathways. The American Veterinary Medical Association also stated in 2026 that more than half of US dogs and cats are overweight or obese, which raises anesthesia and perioperative risk and supports wider use of monitoring equipment and critical care consumables.
Shift Toward Single-Use Infection-Control Consumables
The United States veterinary equipment and disposables market is also moving toward single-use sterile products in surgical and critical care settings. High-throughput clinics want faster room turnover, simpler traceability, and lower sterilization burden, which makes syringes, drapes, IV accessories, and other disposable items more attractive. Corporate networks are also standardizing their supply lists, which narrows approved vendor pools and increases the repeat purchase rate for compliant consumables. Covetrus said its VetSuite network delivered more than USD 30 million in realized savings to independent clinics since launch, which shows how group purchasing is making higher-standard consumables easier to adopt at scale. The result is a demand pattern in which consumables growth is becoming less tied to one-time capital cycles and more tied to daily clinical throughput.
High Upfront Cost Of Imaging And Surgical Platforms
The United States veterinary equipment and disposables market still faces a meaningful barrier from the upfront cost of advanced equipment. CT systems, MRI platforms, digital radiography units, and endoscopy towers require capital budgets that many independent and single-site practices cannot support without financing. The American Veterinary Medical Association cited CareCredit survey findings showing that cost was the primary concern for 80% of pet owners considering specialty veterinary care, which makes clinics more cautious about investing in equipment that depends on steady, high-value case flow. Large groups can spread procurement costs across multiple facilities and negotiate stronger supplier terms, while smaller operators carry the full exposure of each purchase. Section 179 support and financing options help the United States veterinary equipment and disposables market, but they do not fully close the gap between corporate networks and independent practices.
Other drivers and restraints analyzed in the detailed report include:
- Section 179 Supported Capital Equipment Purchases
- Growth of High-Acuity Referral and Specialty Veterinary Care
- Shortage Of Credentialed Veterinary Technicians For Advanced Equipment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Equipment and accessories captured 57.48% of the United States veterinary equipment and disposables market share in 2025, which reflects the large installed base of anesthesia, monitoring, imaging, and fluid management systems across the country. The United States veterinary equipment and disposables market still leans toward capital equipment because these platforms anchor surgical, emergency, and inpatient workflows in both general and specialty settings. Anesthesia equipment and patient monitors remain central to procedure volume because they are needed across elective surgery, urgent interventions, and ICU care. Research equipment and rescue or resuscitation systems remain smaller categories, but they hold a stable place in referral hospitals, veterinary schools, and teaching facilities.
Disposables and consumables will post the fastest growth, with the United States veterinary equipment and disposables market size for this segment projected to expand at 7.36% CAGR through 2031. This segment benefits from high reorder frequency in syringes and needles, IV accessories, infusion sets, tubes, catheters, drapes, sutures, and wound care materials. Standardization by larger clinic groups is making purchasing more predictable, and that favors vendors with broad product coverage and integrated ordering support. Covetrus said its VetSuite network has delivered savings to independent practices nationwide, which supports the adoption of standardized consumables that previously competed mainly on unit price.
Small animals accounted for 59.17% of the segment in 2025, which keeps companion animal medicine at the center of the United States veterinary equipment and disposables market. That position is tied to strong household ownership of dogs and cats and to owner willingness to approve more testing, surgery, and preventive care than in the past. In-clinic chemistry systems, hematology analyzers, anesthesia platforms, and monitoring equipment are seeing wider use because general practices are handling a broader range of cases before referral. The United States veterinary equipment and disposables market also benefits from a more wellness-oriented approach in companion animal care, which lifts recurring demand for point-of-care diagnostics and everyday consumables.
Large animals are the fastest-growing segment, and the United States veterinary equipment and disposables market size for this segment is forecast to rise at 8.87% CAGR through 2031. Growth here is supported by a stronger interest in portable ultrasound, point-of-care blood analysis, and field-ready fluid management products that can be used outside fixed clinical infrastructure. Zoetis announced in February 2026 that it would acquire Neogen's animal genomics business, which points to growing demand for more precise diagnostic and monitoring approaches in livestock health. The American Pet Products Association also reported that 2 million US households own horses, which supports mobile care demand in equine settings where distance and access still shape equipment choice.
Complete Report Scope:
- By Product
- Equipment and Accessories
- Anesthesia Equipment
- Temperature Management Equipment
- Fluid Management Equipment
- Patient Monitoring Equipment
- Research Equipment
- Rescue and Resuscitation Equipment
- Other Equipment and Accessories
- Disposables and Consumables
- Syringes and Needles
- Bandages and Wound Care Products
- Infusion Sets and IV Accessories
- Tubes and Catheters
- Surgical Consumables
- Equipment and Accessories
- By Animal Type
- Small Animals
- Large Animals
- By Usage
- Surgical
- Diagnostic
- Monitoring
- By End Use
- Veterinary Clinics
- Veterinary Hospitals
- Veterinary Research Institutes
- Academic Institutions
List of Companies Covered in this Report:
- Avante Health Solutions
- B. Braun
- Boehringer Ingelheim
- Covetrus
- Elanco
- Ethicon
- Henry Schein
- IDEXX
- Integra LifeSciences
- Jorgensen Laboratories
- Johnson & Johnson
- Masimo
- Medtronic
- Midmark
- Mindray Animal Medical Technology Co., Ltd.
- Neogen
- Nonin Medical
- Patterson Companies
- Sklar Surgical Instruments
- STERIS
- Vetland Medical Sales and Services, LLC
- VIMIAN Group AB
- Zoetis
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Companion Animal Procedural Volume
- 4.2.2 Shift Toward Single-Use Infection-Control Consumables
- 4.2.3 Section 179 Supported Capital Equipment Purchases
- 4.2.4 Growth of High-Acuity Referral and Specialty Veterinary Care
- 4.2.5 Expansion of Portable and Point-of-Care Diagnostics
- 4.2.6 Rising Demand for Workflow-Safe, Low-Labor Clinical Consumables
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of Imaging and Surgical Platforms
- 4.3.2 Shortage of Credentialed Veterinary Technicians for Advanced Equipment
- 4.3.3 Reimbursement Friction and Price Sensitivity Among Pet Owners
- 4.3.4 Procurement Delays From Highly Regulated Supply Chains
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product
- 5.1.1 Equipment and Accessories
- 5.1.1.1 Anesthesia Equipment
- 5.1.1.2 Temperature Management Equipment
- 5.1.1.3 Fluid Management Equipment
- 5.1.1.4 Patient Monitoring Equipment
- 5.1.1.5 Research Equipment
- 5.1.1.6 Rescue and Resuscitation Equipment
- 5.1.1.7 Other Equipment and Accessories
- 5.1.2 Disposables and Consumables
- 5.1.2.1 Syringes and Needles
- 5.1.2.2 Bandages and Wound Care Products
- 5.1.2.3 Infusion Sets and IV Accessories
- 5.1.2.4 Tubes and Catheters
- 5.1.2.5 Surgical Consumables
- 5.1.1 Equipment and Accessories
- 5.2 By Animal Type
- 5.2.1 Small Animals
- 5.2.2 Large Animals
- 5.3 By Usage
- 5.3.1 Surgical
- 5.3.2 Diagnostic
- 5.3.3 Monitoring
- 5.4 By End Use
- 5.4.1 Veterinary Clinics
- 5.4.2 Veterinary Hospitals
- 5.4.3 Veterinary Research Institutes
- 5.4.4 Academic Institutions
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Avante Animal Health
- 6.3.2 B. Braun Vet Care GmbH
- 6.3.3 Boehringer Ingelheim Animal Health
- 6.3.4 Covetrus, Inc.
- 6.3.5 Elanco Animal Health Incorporated
- 6.3.6 Ethicon US, LLC
- 6.3.7 Henry Schein, Inc.
- 6.3.8 IDEXX Laboratories, Inc.
- 6.3.9 Integra LifeSciences Holdings Corporation
- 6.3.10 Jorgensen Laboratories
- 6.3.11 Johnson & Johnson
- 6.3.12 Masimo Corporation
- 6.3.13 Medtronic plc
- 6.3.14 Midmark Corporation
- 6.3.15 Mindray Animal Medical Technology Co., Ltd.
- 6.3.16 Neogen Corporation
- 6.3.17 Nonin Medical, Inc.
- 6.3.18 Patterson Companies, Inc.
- 6.3.19 Sklar Surgical Instruments
- 6.3.20 STERIS plc
- 6.3.21 Vetland Medical Sales and Services, LLC
- 6.3.22 VIMIAN Group AB
- 6.3.23 Zoetis Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


