

|
시장보고서
상품코드
2114272
수의용 장비 및 소모품 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Veterinary Equipment And Disposables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
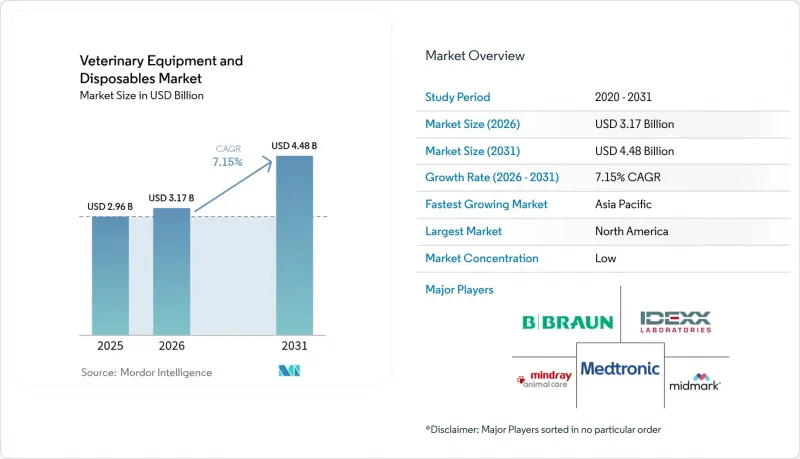
에 의하면, 수의용 장비 및 소모품 시장 규모는 2025년 29억 6,000만 달러로 평가되었습니다. 2026년에는 31억 7,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 7.15%로 성장을 지속하여, 2031년에는 44억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형(기기(치료용 기기, 영상 진단 기기 등) 및 소모품(주사기·바늘, 수액·수혈 세트 등)), 동물 유형(반려동물 및 가축), 최종 사용자(동물병원 및 개인 진료소), 지역(북미, 유럽 등)별로 분류되어 있습니다. 본 보고서에서는 상기 각 부문별 시장 규모(미 달러)를 제시하고 있습니다.
세계의 수의용 장비 및 소모품 시장 동향과 인사이트
반려동물 보험 보급률의 급속한 확대
반려동물 보험은 고성능 영상 진단 시스템 및 병원 내 검사 시스템의 조기 도입을 촉진함으로써 수의용 장비 및 소모품 시장을 변화시키고 있습니다. 보험에 가입한 반려인은 미가입 반려인에 비해 2.3배 더 높은 빈도로 고도의 진단을 승인하고 있으며, 이로 인해 진료소의 수익이 향상되고 기기 투자 회수 기간이 단축되고 있습니다. 미국에서는 보험 적용 대상 반려동물이 현재 550만 마리를 넘어섰으며, 보험사가 보험금 청구 심사를 위해 상세한 영상 진단 보고서나 병리 보고서를 요구하는 사례가 늘어나고 있어, 이는 동물병원의 디지털 X선 촬영 및 CT 플랫폼 업그레이드를 촉진하고 있습니다. 유럽에서도 유사한 경향이 나타나고 있으며, 북유럽 국가에서는 보급률이 30%를 넘어, 마취 모니터 및 치과 치료실의 현대화가 광범위하게 진행되고 있습니다. 아시아의 보험 사업자들은 외래 진단을 보장하는 세트형 소액보험 상품을 출시하여 수요를 더욱 확대되고 있습니다. 보험 급여 상한액 인상에 따른 파급 효과로 인해, 체인 동물병원이나 개인 운영 동물병원에서 고성능 의료기기의 도입이 촉진되고 있습니다.
가축 질병 감시 의무 강화
2024년 4월 미국 농무부(USDA)의 연방 명령에 따라, 젖소 무리는 주간 운송 전에 H5N1 검사를 받아야 할 의무가 부과되었으며, 이에 따라 농장용 PCR 장비, 휴대용 혈액 분석기 및 안전한 데이터 기록 소프트웨어의 수주가 즉시 증가했습니다. 유럽 및 중국의 당국도 가금류, 돼지, 소 사육 현장에서 추적 가능한 신속 진단을 의무화하는 유사한 체계를 도입하고 있으며, 이로 인해 견고한 초음파 진단 장비 및 열화상 장비의 조달이 촉진되고 있습니다. 생산자들은 이러한 도구를 활용하여 검역으로 인한 가동 중단 기간을 최소화하고 수출 적격성을 유지하고 있으며, 그 결과 제조업체에게는 소모품을 통한 지속적인 수익이 창출되고 있습니다. 또한, 이러한 규제로 인해 검사실의 처리 능력 확대가 가속화되어 원심분리기, 생물안전 캐비닛 및 검체 전처리용 로봇의 판매가 촉진되고 있습니다. 현장에 배치된 센서의 짧은 주기적 교체로 인해 예측 기간 동안 애프터마켓의 성장이 지속될 것입니다.
첨단 영상 진단 시스템의 고액 초기 투자
디지털 방사선 촬영 장치의 가격은 약 2만 1,000달러부터 시작하며, 완전한 DR 제품군의 평균 가격은 2만 9,995달러이지만, 보증, 서비스 계약, 소프트웨어 업그레이드를 고려하면 수명 주기 비용은 2배가 됩니다. 소규모 진료소에서는 구매를 미루거나 리퍼브 제품으로 전환하기 때문에 1차 시장의 교체 속도가 둔화되고 있습니다. 신흥국에서는 저금리 대출 이용이 제한적이라는 점이 CT 및 MRI 플랫폼 도입을 더욱 저해하고 있습니다. 대규모 의료 체인은 수량 할인 및 통합된 영상 판독 서비스를 활용하여 검사당 비용을 절감하고 있으며, 그 결과 통합된 네트워크와 개인 개업의 간의 기술 격차가 확대되고 있습니다. 미국 섹션 179와 같은 정부의 세제 혜택은 비용의 일부를 경감해 줄 뿐, 장비 보급을 제약하는 자본 집약성을 완전히 상쇄하지는 못합니다.
부문별 분석
2025년, 수의용 장비 및 소모품 시장에서 기기가 64.02%를 차지했으며, 이는 현대 수의학 업무가 자본 집약적임을 여실히 보여줍니다. AI가 통합된 초음파 진단 장치와 디지털 X선 촬영 장치가 스캔 시간을 단축하고 분류의 정확도를 높임에 따라, 영상 진단 장치는 가장 빠르게 성장하는 하위 카테고리가 되었습니다. 외과용 레이저 및 재생 의료용 기기는 치료의 선택지를 넓히고 높은 이익률을 가져다주고 있습니다. 마취 워크스테이션과 다중 매개변수 모니터는 시술 안전 프로토콜이 엄격해짐에 따라 꾸준히 보급되고 있습니다. 수의학 기기·소모품 시장에서 소모품 시장 규모는 비교적 작지만, 감염 관리 기준과 예측 가능한 비용 모델을 배경으로 일회용 드레이프, 카테터, 내시경용 소모품은 연평균 성장률(CAGR) 7.74%를 나타낼 것으로 예측됩니다.
2025년에는 일회용 제품이 시장 점유율의 35.98%를 차지했으며, 이러한 지속적인 수익 구조는 안정적인 현금 흐름을 추구하는 공급업체에게 매력적입니다. 판매 수량 면에서는 주사기와 바늘이 주류를 이루고 있지만, 예방 피부과에 중점을 둔 상처 피복재와 세포진단용 슬라이드에 대한 수요도 증가하고 있습니다. 오염 위험이 높은 분야에서는 일회용 내시경 액세서리가 주목받고 있지만, 최근 연구에 따르면 재사용 가능한 집게도 반복적인 멸균을 거치면 비열등성이 입증되었습니다. 비용 대비 효과에 대한 논의가, 특히 자원이 제한된 진료소에서 시장 침투율을 좌우하게 될 것입니다. 통기성이 뛰어난 라미네이트 소재의 눈부신 발전으로 인해 일회용 제품의 환경적 부담이 줄어들어, 지속가능성을 중시하는 구매자들의 관심을 끌 가능성이 있습니다.
지역별 분석
북미는 2025년 매출의 41.05%를 차지했으며, 그 배경에는 높은 반려동물 사육률, 높은 보험 보급률, 그리고 장비 업그레이드를 촉진하는 연방 정부의 가축 검사 지침이 있습니다. 미국의 진료소에서는 AI를 활용한 혈액학 및 세포진단 플랫폼 도입이 빠르게 진행되고 있는 반면, 캐나다에서는 소의 추적 가능성과 반려동물의 치과 치료가 중시되고 있습니다. 멕시코에서는 확대되는 중산층이 강아지 및 고양이를 위한 건강 관리 프로그램을 주도하고 있어, 소형 기기 교체 수요 증가로 이어지고 있습니다. 시장은 성숙 단계에 접어들었지만, 워크플로우를 효율화하는 배터리 구동식 디지털 X선 촬영 장비 및 클라우드 PACS의 업데이트 수요는 여전히 존재합니다.
아시아태평양은 가장 빠르게 성장하고 있으며, 2031년까지 연평균 성장률(CAGR)은 9.12%로 전망됩니다. 일본에서는 고령화되는 반려동물을 대응하기 위해 저침습 수술 기구가 도입되고 있습니다. 한국은 IVDD(추간판 질환)에 걸리기 쉬운 소형견을 위한 디지털 신경 진단 분야를 선도하고 있습니다. 인도에서는 가축의 현대화에 따라 휴대용 초음파 진단 장비와 유선염 검사 리더기의 도입이 진행되고 있으며, 호주에서는 수출 자격을 유지하기 위해 생물보안 대책을 적용한 가금류 검사 시스템의 업그레이드가 추진되고 있습니다.
유럽은 엄격한 동물 복지 규제와 반려동물에 대한 광범위한 의료 서비스 제공으로 시장 점유율 2위를 차지하고 있습니다. 독일에서는 X선 조작자에 대한 방사선 안전 인증이 의무화되어 있으며, 저선량 검출기로의 교체가 진행되고 있습니다. 영국 경쟁·시장청(CMA)의 수의학 가격 조사는 투명성을 중시하는 비용 효율적인 분석 장비 조달을 촉진할 가능성이 있습니다. 프랑스와 네덜란드에서는 EU 그린딜(Green Deal) 목표에 부합하여 친환경 마취 가스 회수 시스템의 시범 운영이 진행되고 있습니다. 스페인 등 남유럽 시장에서는 반려동물과 가축을 모두 다루는 혼합 진료에 대응하기 위해, 영상 진단실에서의 다양한 유형에 대응할 수 있는 범용성이 우선시되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the veterinary equipment and disposables market size is expected to grow from USD 2.96 billion in 2025 to USD 3.17 billion in 2026 and is forecast to reach USD 4.48 billion by 2031 at 7.15% CAGR over 2026-2031.
This report is Segmented by Product Type (Equipment [Therapeutic Equipment, Diagnostic Imaging and More] and Disposables [Syringes & Needles, Infusion & Transfusion Sets and More]), Animal (Companion Animals and Livestock Animals), End User (Veterinary Hospitals and Private Clinics), and Geography (North America, Europe and More). The Report Offers the Value (USD) for the Above Segments.
Global Veterinary Equipment And Disposables Market Trends and Insights
Rapid Growth in Pet Insurance Penetration
Pet insurance policies are reshaping the veterinary equipment and disposables market by encouraging earlier adoption of high-end imaging and in-house laboratory systems. Insured clients approve advanced diagnostics 2.3 times more often than uninsured owners, which lifts practice revenue and accelerates equipment payback periods. In the United States, policy coverage now exceeds 5.5 million pets, and insurers increasingly require detailed imaging or pathology reports for claim validation, driving clinics to upgrade to digital radiography and CT platforms. Europe mirrors this trajectory, as Nordic countries exceed a 30% penetration rate, prompting widespread modernization of anesthesia monitors and dental suites. Asian providers are launching bundled micro-insurance products that cover outpatient diagnostics, further broadening demand. The cascading effect of higher reimbursement limits supports the placement of premium instruments across corporate chains and independent practices.
Rising Livestock Disease Surveillance Mandates
The USDA Federal Order of April 2024 compels dairy herds to test for H5N1 before interstate transport, immediately boosting orders for on-farm PCR units, handheld blood analyzers, and secure data-logging software. European and Chinese authorities are deploying comparable frameworks that require traceable, rapid diagnostics within poultry, swine, and cattle operations, catalyzing procurement of ruggedized ultrasound and thermal-imaging equipment. Producers utilize these tools to minimize quarantine downtime and maintain export eligibility, resulting in recurring revenue from consumables for manufacturers. The mandates also accelerate laboratory capacity expansion, stimulating sales of centrifuges, biosafety cabinets, and sample-prep robotics. Short-cycle replacement of field-deployed sensors sustains aftermarket growth throughout the forecast window.
High Capital Cost for Advanced Imaging Suites
Digital radiography units start at around USD 21,000, and full DR suites average USD 29,995; however, lifetime costs double once warranties, service contracts, and software upgrades are factored in. Small clinics postpone purchases or turn to refurbished systems, which slows primary market turnover. In emerging economies, limited access to low-interest financing further deters adoption of CT and MRI platforms. Large corporate chains leverage volume discounts and centralized reading services to dilute per-exam costs, thereby widening the technology gap between consolidated networks and solo practitioners. Government tax incentives, such as US Section 179, provide partial relief but do not fully offset the capital intensity that constrains equipment penetration.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Minimally-Invasive Surgical Tools
- Growth of Tele-Veterinary Diagnostics Platforms
- Shortage of Skilled Veterinary Radiologists
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Equipment represented 64.02% of the veterinary equipment and disposables market in 2025, underscoring the capital-intensive nature of modern practice operations. Diagnostic imaging units are the fastest-growing subcategory, as AI-integrated ultrasound and digital radiography reduce scan times and enhance triage accuracy. Surgical lasers and regenerative therapy devices broaden therapeutic options and carry premium margins. Anesthesia workstations and multiparameter monitors record steady uptake due to stricter procedural safety protocols. The veterinary equipment and disposables market size for disposables is smaller; however, single-use drapes, catheters, and endoscopy consumables are projected to post an 7.74% CAGR, driven by infection-control standards and predictable cost models.
Disposables accounted for a 35.98% share in 2025, but their recurring-revenue profile appeals to suppliers seeking stable cash flows. Syringes and needles dominate the volume; wound dressings and cytology slides are growing, with a focus on preventive dermatology. Single-use endoscopy accessories garner attention where contamination risk is high, although recent studies have found reusable forceps to be non-inferior after repeated sterilization. Cost-benefit debates will shape penetration levels, especially in resource-constrained clinics. Material advances in breathable laminates lower the environmental footprint of disposables and may attract sustainability-minded buyers.
Complete Report Scope:
- By Product Type
- Equipment
- Therapeutic Equipment
- Diagnostic Imaging
- Anesthesia Machines
- Patient Monitoring
- Dental Equipment
- Disposables
- Syringes & Needles
- Infusion & Transfusion Sets
- Catheters
- Wound Dressings & Bandages
- Surgical Drapes & Gowns
- Equipment
- By Animal Type
- Companion Animals
- Dogs
- Cats
- Horses
- Others
- Livestock Animals
- Cattle
- Swine
- Poultry
- Others
- Companion Animals
- By End User
- Veterinary Clinics
- Veterinary Hospitals
- Academic & Research Institutes
- Mobile/ Ambulatory Services
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 41.05% of 2025 revenue, anchored by high pet ownership, favorable insurance penetration, and federal livestock testing directives that stimulate equipment upgrades. The United States clinics are rapidly adopting AI-powered hematology and cytology platforms, while Canada is emphasizing cattle traceability and companion animal dental care. Mexico's growing middle class drives puppy and kitten wellness programs, leading to increased turnover of small equipment. Although mature, the region still represents a market for replacing battery-powered digital radiography and cloud PACS that streamline workflows.
The Asia-Pacific region is the fastest-growing, with a 9.12% CAGR through 2031. Japan adopts minimally invasive surgical tools to serve an aging pet population. South Korea leads in digital neuro-diagnostics for small dogs prone to IVDD. India's livestock modernization drives the adoption of portable ultrasound and mastitis-test readers, while Australia upgrades its biosecure poultry inspection systems to maintain export status.
Europe ranks second in share owing to robust welfare regulations and broad companion coverage. Germany mandates radiation safety certification for X-ray operators, driving upgrades to low-dose detectors. The UK Competition and Markets Authority investigation into veterinary pricing could spur transparency-driven procurement of cost-efficient analyzers. France and the Netherlands pilot eco-friendly anaesthesia scavenging systems, aligning with EU Green Deal ambitions. Southern markets such as Spain prioritize multi-species versatility in imaging suites to serve mixed companion-livestock practices.
- IDEXX
- Covetrus
- Heska
- Midmark
- B. Braun Vet Care
- Jorgen Kruuse A/S
- Shenzhen Mindray Animal Medical
- Neogen
- Zoetis (VetScan)
- Eickemeyer Veterinary Equipment
- Agfa-Gevaert
- Antibe Therapeutics (Citagenix)
- Veterinary Instrumentation
- Smiths Group
- Cardinal Health
- Burtons Medical Equipment
- Orion Concept Inc.
- Dispomed
- Esaote
- IMV Technologies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth in Pet Insurance Penetration
- 4.2.2 Rising Livestock Disease Surveillance Mandates
- 4.2.3 Expansion of Minimally-Invasive Surgical Tools
- 4.2.4 Growth of Tele-Veterinary Diagnostics Platforms
- 4.2.5 Mainstream Adoption of Single-Use Endoscopy
- 4.2.6 Genetic Screening Driving Preventive Equipment Demand
- 4.3 Market Restraints
- 4.3.1 High Capital Cost for Advanced Imaging Suites
- 4.3.2 Shortage of Skilled Veterinary Radiologists
- 4.3.3 Re-Use Culture in Price-Sensitive Markets
- 4.3.4 Regulatory Ambiguity for Novel Disposables
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Equipment
- 5.1.1.1 Therapeutic Equipment
- 5.1.1.2 Diagnostic Imaging
- 5.1.1.3 Anesthesia Machines
- 5.1.1.4 Patient Monitoring
- 5.1.1.5 Dental Equipment
- 5.1.2 Disposables
- 5.1.2.1 Syringes & Needles
- 5.1.2.2 Infusion & Transfusion Sets
- 5.1.2.3 Catheters
- 5.1.2.4 Wound Dressings & Bandages
- 5.1.2.5 Surgical Drapes & Gowns
- 5.1.1 Equipment
- 5.2 By Animal Type
- 5.2.1 Companion Animals
- 5.2.1.1 Dogs
- 5.2.1.2 Cats
- 5.2.1.3 Horses
- 5.2.1.4 Others
- 5.2.2 Livestock Animals
- 5.2.2.1 Cattle
- 5.2.2.2 Swine
- 5.2.2.3 Poultry
- 5.2.2.4 Others
- 5.2.1 Companion Animals
- 5.3 By End User
- 5.3.1 Veterinary Clinics
- 5.3.2 Veterinary Hospitals
- 5.3.3 Academic & Research Institutes
- 5.3.4 Mobile/ Ambulatory Services
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 IDEXX Laboratories
- 6.3.2 Covetrus
- 6.3.3 Heska Corporation
- 6.3.4 Midmark Corporation
- 6.3.5 B. Braun Vet Care
- 6.3.6 Jorgen Kruuse A/S
- 6.3.7 Shenzhen Mindray Animal Medical
- 6.3.8 Neogen Corporation
- 6.3.9 Zoetis (VetScan)
- 6.3.10 Eickemeyer Veterinary Equipment
- 6.3.11 Agfa-Gevaert N.V.
- 6.3.12 Antibe Therapeutics (Citagenix)
- 6.3.13 Veterinary Instrumentation
- 6.3.14 Smiths Medical (ICU Medical)
- 6.3.15 Cardinal Health
- 6.3.16 Burtons Medical Equipment
- 6.3.17 Orion Concept Inc.
- 6.3.18 Dispomed Ltd.
- 6.3.19 Esaote SpA
- 6.3.20 IMV Technologies
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


