

|
시장보고서
상품코드
2097338
자동차용 피스톤 핀 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Piston Pin - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
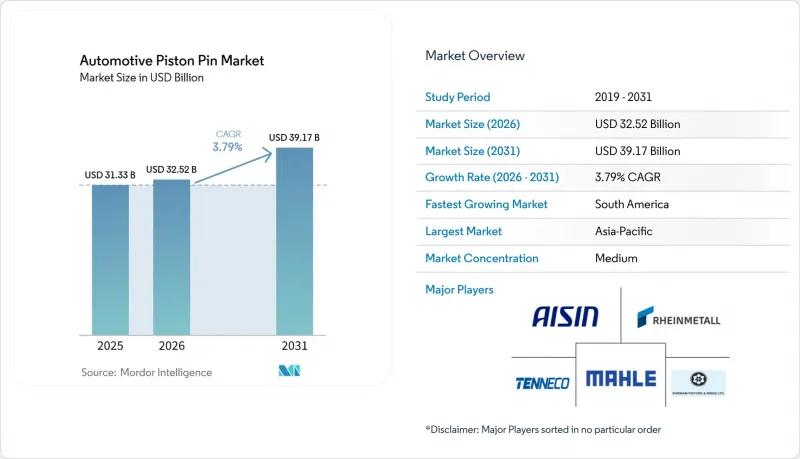
에 의하면, 자동차용 피스톤 핀 시장은 2025년에 313억 3,000만 달러로 평가되었습니다. 2026년에 325억 2,000만 달러, 2031년까지 391억 7,000만 달러에 이를 것으로 예측되며, CAGR은 3.79%로 성장할 전망입니다.

본 보고서는 차종별(승용차, 소형 상용차, 중형·대형 상용차), 연료별(디젤, 가솔린, 대체 연료), 재질별(강철, 알루미늄, 티타늄), 판매 채널별(OEM 및 애프터마켓), 지역별(북미, 남미 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
세계의 자동차용 피스톤 핀 시장 동향 및 인사이트
SUV 주도 하에 승용차 생산 대수의 급증
세계 SUV 수요는 엔진 배기량 및 기통 수 증가를 지속적으로 견인하고 있으며, 이에 따라 필요한 피스톤 핀의 수량이 직접적으로 증가하고 있습니다. 인도의 SUV 신규 등록 대수는 2020년부터 2024년에 걸쳐 두 자릿수 성장률을 보였으며, 이는 자동차용 피스톤 핀 시장에서 승용차가 차지하는 압도적인 기여도를 뒷받침하고 있습니다. 프리미엄 SUV용으로 사양이 정해진 대형 터보차저 장착 엔진에는 고성능 강합금 및 DLC 코팅이 요구되어, 차량 1대당 부품 가치를 높이고 있습니다. 정밀한 단조 및 코팅 기술을 제공하는 공급업체들은 전 세계 자동차 제조업체들에게 SUV가 수익성의 핵심이 되고 있다는 점에 힘입어, OEM 플랫폼을 통한 장기 공급 계약을 확보하고 있습니다. 따라서 아시아태평양 및 북미에서의 SUV 보급률 상승은 피스톤 핀 제조업체의 판매량 및 가치 성장 전망을 더욱 확대시킬 것입니다.
신흥국에서의 내연기관(ICE) 차량 생산 지속
인프라 및 비용 현실로 인해 인도, 동남아시아, 남미에서는 기존 방식의 파워트레인이 여전히 주류를 이루며, 자동차용 피스톤 핀 시장의 기초적인 수요를 뒷받침하고 있습니다. 인도의 부품 부문은 2025-26년에 한 자릿수 후반대의 성장이 예상되며, 엔진 부품은 OEM의 부품 명세서(BOM)의 4분의 1 이상을 차지하고 있습니다. 국내에서 부가가치 창출이 의무화됨에 따라 현지 단조 및 기계 가공에 대한 투자가 촉진되고, 수입 의존도가 낮아지며, 공급업체의 진출 범위가 확대되고 있습니다. 농업 기계 및 상용차의 경우, 조기 전동화보다 디젤의 신뢰성이 중시되기 때문에 수요량이 증가하고 있습니다. 그 결과, 개발도상 지역에서의 내연기관(ICE) 중심의 성장 궤도가 성숙 시장에서 예상되는 수요 감소분을 상쇄하고 있습니다.
BEV 보급 가속화
배터리식 전기차(BEV)는 내연기관 시스템을 완전히 배제하기 때문에 피스톤 핀의 사용이 사라지게 되어, 장기적인 수요에 있어 가장 심각한 구조적 위협을 초래합니다. 중국의 전기차 점유율은 2024년에 경차 생산 대수의 2배 이상으로 확대되었습니다. 이러한 추세는 구매 인센티브와 현지 배터리 생산에 의해 더욱 가속화되고 있습니다. 유럽에서도 엄격한 CO₂ 배출 목표와 충전 네트워크 확대로 인해 유사한 동향이 나타나고 있습니다. 공급업체들은 생산량 감소를 상쇄하기 위해 대체 연료 차량, 하이브리드 차량, 혹은 파워트레인 이외의 부품으로 사업을 다각화해야 합니다. 하지만 기존 차량 보유 대수와 하이브리드화로의 전환 과정으로 인해, 이러한 제약의 완전한 영향은 2020년대 후반까지 미뤄질 것이며, 생산 능력의 단계적 전환이 가능해질 것입니다.
부문 분석
2025년, 승용차는 자동차용 피스톤 핀 시장 매출의 55.68%를 차지했으며, 이는 전 세계 경차의 조립 생산 대수가 견조한 추세를 보이고 있음을 반영합니다. 프리미엄 SUV의 경우 대구경 엔진이나 여러 개의 터보차저가 채택됨에 따라 내구성에 대한 요구가 높아지고 있어, 승용차용 자동차 피스톤 핀 시장 규모는 계속 확대되고 있습니다. OEM의 모듈식 플랫폼 전략은 장기적인 조달 파트너십을 더욱 공고히 하고 있으며, 세계 사업 전개와 엄격한 품질 관리 시스템을 갖춘 공급업체에 유리하게 작용하고 있습니다. 한편, 성숙한 경제권에서는 승용차의 노후화에 따라 정비 주기가 장기화되고 있어 애프터마켓 수요가 꾸준히 증가하고 있습니다.
경상용차 부문은 인도, 동남아시아, 라틴아메리카에서 라스트 마일 물류 및 지방 운송이 확대됨에 따라 2031년까지 연평균 성장률(CAGR) 5.05%라는 가장 높은 성장률을 기록할 전망입니다. 소형 디젤 엔진이나 CNG 엔진을 탑재한 경상용차(LCV)가 중요한 역할을 하고 있습니다. 잦은 출발과 정지의 반복 및 적재량의 변동은 피스톤 핀이나 베어링 등의 엔진 부품에 추가적인 부하를 주어 마모를 가속화합니다. 이러한 현상은 특히 2급 및 3급 서비스 거점에서 애프터마켓의 안정적인 수요를 뒷받침하고 있습니다. OEM과 협력하며 기동성이 뛰어난 유통 네트워크를 자랑하는 각 공급업체들은 내마모성 합금의 공동 개발을 추진하고 있습니다. 이러한 혁신 기술은 도시 지역의 교통 정체나 열 사이클과 같은 과제를 견딜 수 있도록 설계되었습니다.
2025년, 가솔린 엔진 구조는 확립된 연료 공급 인프라와 소비자들이 익숙해져 있는 사용감 덕분에 자동차용 피스톤 핀 시장 점유율의 48.59%를 차지했습니다. 이 부문의 완만한 성장은 내연기관의 요소를 유지하는 하이브리드화의 진전에 힘입은 것으로, 전기 구동 방식이 도입되더라도 피스톤 핀의 사용은 지속되고 있습니다. 한편, 디젤 엔진은 화물 운송 및 오프로드 장비 분야에서 여전히 필수적이지만, 규제 강화에 따라 그 점유율은 서서히 감소하고 있습니다.
대체 연료 분야는 정책적 인센티브와 차량 함대의 경제성에 힘입어 6.44%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 상업용 사업자들이 연료비 절감과 배기가스 감축 목표 달성을 목표로 하는 가운데, CNG 및 LNG 엔진용 자동차 피스톤 핀 시장 규모는 급속히 확대되고 있습니다. 뛰어난 열 안정성을 갖춘 특수한 형태의 피스톤 핀은 고가대로 거래되어 단위당 수익을 끌어올리고 있습니다. PHINIA 및 기타 1차 공급업체와 공동 개발이 진행 중인 수소 내연기관(ICE) 프로토타입은 기존 연료 구성의 양상을 다각화할 미래의 고수익성 하위 시장을 예고합니다.
지역별 분석
아시아태평양은 중국의 광범위한 공급망과 인도의 급성장하는 부품 부문에 힘입어 2025년 자동차용 피스톤 핀 시장 매출의 45.56%를 차지했습니다. 각 지역 정부는 세제 혜택 및 인프라 구축을 통해 현지화를 추진하고 있으며, 이에 따라 전 세계 Tier 1 공급업체들은 조립 공장 인근에 단조 및 코팅 시설을 확장하도록 장려받고 있습니다. 차량 보유 대수의 급증과 폐차보다는 교체를 선호하는 수리 문화로 인해 애프터마켓 수요는 계속해서 호조를 보이고 있습니다.
남미는 브라질의 자동차 생산 회복과 북미 및 유럽 OEM 제조업체에 부품을 공급하는 지역 무역을 통해 2031년까지 연평균 성장률(CAGR)이 4.08%로 가장 높을 것으로 전망됩니다. 브라질과 아르헨티나의 농업 기계화가 트랙터용 엔진 부품 소비를 견인하는 한편, 화물 운송의 확대로 인해 중형 및 대형 상용차용 핀 수요가 증가하고 있습니다.
북미와 유럽은 큰 시장 점유율을 차지하고 있지만, 전동화가 내연기관(ICE)의 생산 대수를 압박하고 있어 성장은 완만한 수준에 그치고 있습니다. 그럼에도 불구하고, 고급차 프로그램 및 고성능 애프터마켓 분야는 틈새 성장 기회를 유지하고 있습니다. 독일과 미국의 첨단 제조 거점은 전 세계 수출 시장을 대상으로 고정밀·경량 피스톤 핀을 전문적으로 생산하고 있습니다. 북미 전역에 걸친 하이브리드 파워트레인의 보급은 광범위한 전동화 아키텍처 속에서 소배기량 내연기관 부품을 유지함으로써 절대적인 감소를 완화하고 있습니다.
중동 및 아프리카에서는 인프라 프로젝트와 노후화된 상용차 차량군의 교체 부품 수요에 힘입어 안정적인 한 자릿수 초반대의 성장이 나타나고 있습니다. 현지에 뿌리를 둔 엔진 재구축 생태계는 가혹한 가동 환경에 적합한 견고한 디젤 엔진용 설계를 제공함으로써 피스톤 핀 공급업체에 지속적인 애프터마켓 기회를 제공합니다. 또한, 걸프 국가들의 정부 경제 다각화 정책의 일환으로 지역 자동차 산업 클러스터에 대한 투자가 진행되고 있으며, 완성차 수입에서 현지 부품 생산으로의 단계적 전환을 위한 기반이 마련되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.05According to Mordor Intelligence, the automotive piston pin market is projected to reach USD 31.33 billion in 2025, USD 32.52 billion in 2026, and USD 39.17 billion by 2031, growing at a CAGR of 3.79%.
This report is Segmented by Vehicle Type (Passenger Vehicle, Light Commercial Vehicle, and Medium and Heavy Commercial Vehicle), Fuel Type (Diesel, Gasoline, and Alternative Fuel), Material Type (Steel, Aluminum, and Titanium), Sales Channel (OEM and Aftermarket), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Piston Pin Market Trends and Insights
SUV-Led Surge in Passenger-Vehicle Output
Global SUV demand continues to drive increases in engine displacement and cylinder counts, directly increasing the required piston pin volumes. India's SUV registrations grew at double-digit rates between 2020 and 2024, reinforcing the dominant contribution of passenger vehicles to the automotive piston pin market. Large-format turbocharged engines specified for premium SUVs demand advanced steel alloys and DLC coatings, raising per-vehicle content value. Suppliers that offer precise forging and coating capabilities secure long-term OEM platforms, as SUVs anchor automakers' profitability worldwide. Rising SUV penetration across APAC and North America, therefore, magnifies volume and value growth outlooks for piston pin manufacturers.
Sustained ICE Vehicle Production in Emerging Economies
Infrastructure and cost realities keep traditional powertrains prevalent across India, Southeast Asia, and South America, safeguarding baseline demand in the automotive piston pin market. India's component sector projects high-single-digit growth in 2025-26, with engine parts accounting for over one-quarter of the OEM bill of materials. Domestic value-addition mandates encourage investment in local forging and machining, reducing reliance on imports and broadening supplier participation. Agricultural machinery and commercial vehicles bolster volumes as these applications favor diesel reliability over early electrification. Consequently, ICE-centric growth trajectories in developing regions offset volume losses anticipated in mature markets.
Accelerating BEV Adoption
Battery-electric vehicles eliminate internal-combustion systems entirely, eliminating piston-pin use and posing the sharpest structural threat to long-range demand. China's electric-car share more than doubled to light-vehicle output in 2024, a trajectory reinforced by purchase incentives and localized cell manufacturing. Europe mirrors this trend through stringent CO2 targets and expanding charging networks. Suppliers must diversify toward alt-fuel, hybrid, or non-powertrain components to hedge volume erosion. Nonetheless, legacy vehicle fleets and hybridization pathways defer the restraint's full impact to the latter half of the decade, allowing managed capacity transitions.
Other drivers and restraints analyzed in the detailed report include:
- Growth in CNG/LNG And Other Alt-Fuel ICE Fleets
- Lightweight, High-Performance Engine Demand
- Engine Downsizing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars accounted for 55.68% of the automotive piston pin market revenue in 2025, reflecting sustained global light-vehicle assembly output. The automotive piston pin market size for passenger vehicles continues to rise as premium SUVs require larger-bore engines and multiple turbochargers, which heighten durability requirements. OEM modular platform strategies further cement long-term sourcing partnerships, favoring suppliers with global footprints and strict quality management systems. Meanwhile, aftermarket volumes grow steadily because aging passenger-vehicle fleets extend maintenance cycles in mature economies.
The light commercial vehicle segment is on track for the fastest 5.05% CAGR through 2031 as last-mile logistics and rural transport grow in India, Southeast Asia, and Latin America. Light commercial vehicles (LCVs) equipped with compact diesel and CNG engines play a crucial role. The frequent stop-start cycles and varying payloads put added strain on engine components, such as piston pins and bearings, leading to heightened wear. This phenomenon fuels a consistent demand in the aftermarket, particularly in tier-2 and tier-3 service hubs. Suppliers boasting nimble distribution networks collaborating with OEMs are co-developing wear-resistant alloys. These innovations are designed to withstand the challenges of urban congestion and thermal cycling.
Gasoline architectures accounted for 48.59% of the automotive piston pin market share in 2025, owing to entrenched fueling infrastructure and consumer familiarity. The segment's moderate expansion benefits from ongoing hybridization that retains combustion elements, sustaining piston pin use even as electric drive integrates. Simultaneously, diesel remains indispensable in freight and off-highway equipment, though its share edges lower under regulatory scrutiny.
Alternative fuels post the highest CAGR at 6.44%, propelled by policy incentives and fleet economics. The automotive piston pin market size for CNG and LNG engines is growing rapidly as commercial operators pursue lower fuel costs and emissions targets-specialized pin geometries with superior thermal stability command premium prices, lifting revenue per unit. Hydrogen ICE prototypes under development with PHINIA and other tier-ones signal future high-margin sub-markets that will diversify the traditional fuel-mix landscape.
Complete Report Scope:
- By Vehicle Type
- Passenger Vehicle
- Light Commercial Vehicle
- Medium and Heavy Commercial Vehicle
- By Fuel Type
- Diesel
- Gasoline
- Alternative Fuel
- By Material Type
- Steel
- Aluminum
- Titanium
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific retained 45.56% of the automotive piston pin market revenue in 2025, anchored by China's expansive supply chain and India's fast-growing component sector. Regional governments bolster localization through tax incentives and infrastructure development, prompting global tier-ones to expand their forging and coating facilities near assembly plants. Aftermarket demand remains vibrant as fleet sizes surge and repair culture favors replacement over retirement.
South America posts the highest CAGR at 4.08% through 2031, owing to Brazil's revitalized automotive output and regional trade that channels components to North American and European OEMs. Agricultural mechanization across Brazil and Argentina drives consumption of tractor engine parts, while freight expansion increases demand for medium- and heavy-duty commercial vehicle pins.
North America and Europe hold a sizeable share, yet grow modestly, as electrification weighs on ICE volumes. Nevertheless, premium vehicle programs and performance aftermarket segments preserve niche growth opportunities. Advanced manufacturing hubs in Germany and the United States specialize in high-precision, lightweight piston pins that serve global export markets. Hybrid powertrain prevalence across North America mitigates outright declines by maintaining smaller-displacement ICE components within broader electrified architectures.
The Middle East and Africa exhibit stable, low-single-digit expansion, driven by infrastructure projects and demand for replacement parts for aging commercial fleets. Localized engine-rebuilding ecosystems provide recurring aftermarket opportunities for piston pin suppliers, offering rugged, diesel-oriented designs suitable for harsh operating environments. Government diversification agendas in Gulf states also invest in regional automotive clusters, laying the groundwork for a gradual shift from completely built-up imports to localized part production.
- MAHLE GmbH
- Tenneco Inc.
- Aisin Corporation
- Rheinmetall AG
- Shriram Pistons & Rings Ltd.
- Shandong Binzhou Bohai Piston Co., Ltd.
- Burgess-Norton
- Art Metal Mfg. Co., Ltd.
- Hitachi Astemo Ltd.
- NPR RIKEN Corp.
- JE Pistons
- Wiseco Piston Company
- Elgin Industries
- Samkrg Pistons & Rings Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 SUV-Led Surge In Passenger-Vehicle Output
- 4.2.2 Sustained ICE Vehicle Production In Emerging Economies
- 4.2.3 Growth In CNG/LNG And Other Alt-Fuel ICE Fleets
- 4.2.4 Lightweight, High-Performance Engine Demand
- 4.2.5 Advanced DLC/PVD Coatings Unlocking Downsizing
- 4.2.6 Hybrid ICE Peak-Pressure Upgrades
- 4.3 Market Restraints
- 4.3.1 Accelerating BEV Adoption
- 4.3.2 Engine Downsizing (Fewer Cylinders)
- 4.3.3 OEM Vertical Integration Of Pin Machining
- 4.3.4 Patent-Protected H2 ICE Pin Designs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Passenger Vehicle
- 5.1.2 Light Commercial Vehicle
- 5.1.3 Medium and Heavy Commercial Vehicle
- 5.2 By Fuel Type
- 5.2.1 Diesel
- 5.2.2 Gasoline
- 5.2.3 Alternative Fuel
- 5.3 By Material Type
- 5.3.1 Steel
- 5.3.2 Aluminum
- 5.3.3 Titanium
- 5.4 By Sales Channel
- 5.4.1 OEM
- 5.4.2 Aftermarket
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 Spain
- 5.5.3.4 Italy
- 5.5.3.5 France
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 MAHLE GmbH
- 6.4.2 Tenneco Inc.
- 6.4.3 Aisin Corporation
- 6.4.4 Rheinmetall AG
- 6.4.5 Shriram Pistons & Rings Ltd.
- 6.4.6 Shandong Binzhou Bohai Piston Co., Ltd.
- 6.4.7 Burgess-Norton
- 6.4.8 Art Metal Mfg. Co., Ltd.
- 6.4.9 Hitachi Astemo Ltd.
- 6.4.10 NPR RIKEN Corp.
- 6.4.11 JE Pistons
- 6.4.12 Wiseco Piston Company
- 6.4.13 Elgin Industries
- 6.4.14 Samkrg Pistons & Rings Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


