

|
시장보고서
상품코드
2117459
자동차용 피스톤 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Piston - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
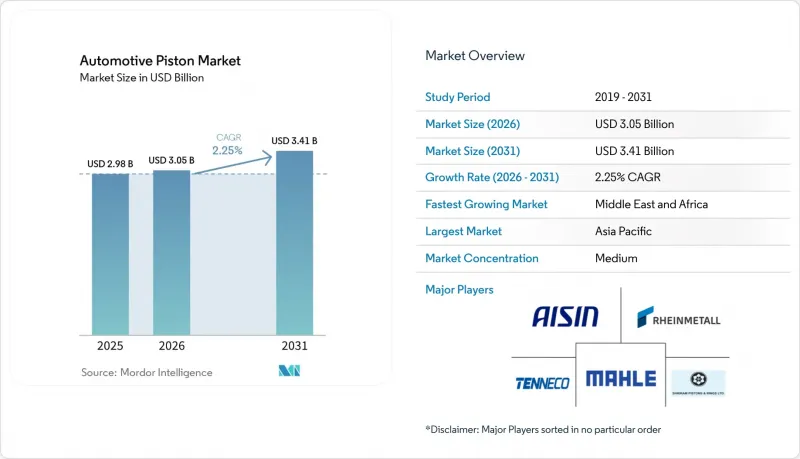
에 의하면, 자동차용 피스톤 시장 규모는 2025년 29억 8,000만 달러에서 2026년에는 30억 5,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 2.25%로 성장을 지속하여, 2031년까지 34억 1,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 구성 부품 유형(피스톤, 피스톤 링, 피스톤 핀), 코팅 유형(오일 셰딩, 건식 필름 윤활, 열 차단), 차종(승용차, 상용차), 재질(알루미늄, 강철), 지역(북미, 남미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 전망은 금액(미 달러) 및 수량(단위)으로 제시되어 있습니다.
세계 자동차용 피스톤 시장 동향 및 인사이트
신흥 시장에서 내연기관(ICE) 수요 지속
신흥국에서는 충전 인프라가 여전히 제한적이고 차량의 가격 접근성이 매우 중요하기 때문에 여전히 내연기관(ICE) 파워트레인에 의존하고 있습니다. 인도는 2025 회계연도에 80만 대 이상의 차량을 수출했으며, 그 대부분은 아프리카와 라틴아메리카로 수출된 가솔린 차량 또는 플렉스 연료 차량이었습니다. 중국은 이중 전략을 채택하고 있으며, 국내 판매가 배터리 전기자동차 플랫폼으로 전환되는 가운데도 내연 기관의 수출은 계속되고 있습니다. 브라질의 에탄올 프로그램과 아르헨티나의 CNG 택시는 피스톤 엔진의 수명을 연장하고 지역적 수요를 뒷받침하고 있습니다. 우타르 프라데시 주, 상파울루 또는 몬테레이에 공장을 둔 공급업체들은 이러한 생산량을 효율적으로 충족시킬 수 있습니다. 이 지역의 저소득층 구매자들은 새로운 대체 기술보다 검증된 내연기관 기술을 선호하기 때문에 자동차용 피스톤 시장은 그 혜택을 누리고 있습니다.
엄격한 배기가스 규제가 경량 알루미늄 및 코팅 피스톤을 촉진
2025년 중반에 시행될 유로 7 규제와 향후 도입될 바라트 스테이지 7 기준에 따라, 자동차 제조업체들은 NOx 및 미세먼지 배출을 억제하는 더 가볍고 냉각 성능이 뛰어난 피스톤을 채택해야 할 압박을 받고 있습니다. 열 차단층이 적용된 알루미늄 피스톤은 최고 온도를 낮추고, 노킹 현상 없이 더 높은 압축비를 실현합니다. 이황화 몰리브덴을 배합한 스커트 코팅은 콜드 스타트 시 마찰을 줄여주며, 유럽 및 미국의 차량 함대 평균 CO₂ 배출 규제 준수를 지원합니다. 이러한 규제는 기술의 급속한 업데이트 주기를 촉진하며, 코팅 피스톤 전문 제조업체에 새로운 수주 기회를 창출하고 있습니다. 동남아시아와 남미에서도 유사한 규제가 확산됨에 따라, 자동차용 피스톤 시장은 이러한 솔루션을 여러 대륙으로 확대되고 있습니다.
전기차(EV) 보급 가속화가 내연기관 차량 판매 대수를 잠식하고 있다.
2025년, 중국에서는 신차 등록 대수의 약 40%, 유럽에서는 25%를 배터리식 전기차(EV)가 차지하며 피스톤 수요를 직접적으로 감소시켰습니다. 테슬라와 BYD를 비롯한 전기차 제조업체들은 생산 능력을 확대하고 있으며, 기존 자동차 제조업체들도 탄소 중립 공약을 달성하기 위해 자본을 재분배하고 있습니다. 내연기관(ICE) 차량의 감소는 OEM 및 애프터마켓 양쪽 채널에서 피스톤 수요의 감소를 의미합니다. 이러한 매출에 미치는 영향은 구매 인센티브나 무배출 규제를 도입한 지역에서 가장 심각합니다. 각 공급업체들은 전기차 보급 속도가 완만한 시장을 타겟으로 삼아 이러한 감소를 상쇄하려 하고 있지만, 자동차용 피스톤 시장 전체에 미치는 영향은 여전히 큽니다.
부문 분석
피스톤은 2025년 부품 매출의 49.02%를 차지하며, 이 부문에서 자동차용 피스톤 시장 점유율을 지탱하는 가장 큰 비중을 차지하고 있습니다. 각 공급업체들은 배출가스 규제가 강화됨에 따라 열 관리 및 마찰 저감을 도모하기 위해 피스톤의 크라운 형상과 스커트 프로파일을 지속적으로 개선하고 있습니다. 설계 측면에서는 다운사이징된 엔진의 실린더 내압 상승에 대응하기 위해 경량화에 중점을 두고 있습니다. 그 결과, 전동화 압력이 가해지고 있음에도 불구하고 피스톤은 여전히 판매량의 주류를 이루고 있습니다. Tier 1 제조업체들은 대량 생산을 수행하는 조립 공장에 대한 적시 납품을 보장하기 위해 전 세계의 파운드리을 활용하고 있습니다.
각 OEM 업체들이 터보차저 탑재 플랫폼을 위해 DLC 코팅이 적용된 표면 경화 처리 피스톤 핀을 채택한 결과, 피스톤 핀 시장은 3.84%라는 가장 높은 연평균 성장률(CAGR)을 기록했습니다. 이러한 업그레이드를 통해 피로 수명이 향상되었으며, 마모 현상 없이 더 높은 회전수(RPM)를 실현할 수 있게 되었습니다. 애프터마켓 구매자들은 오버홀 작업을 효율화할 수 있는 완전한 핀·링 키트를 선호합니다. 코팅 전문 기업과의 업계 협력을 통해 인증 절차가 가속화되고, 시장 출시까지의 기간이 단축되고 있습니다. 가치가 고정밀 핀으로 이동함에 따라 소규모 틈새 시장 제조업체들도 차별화를 꾀할 여지를 얻고 있습니다.
2025년에는 열 차단 코팅이 42.34%라는 압도적인 점유율을 차지하며, 피스톤 상단의 단열 및 연소 안정화에서 그 역할을 더욱 공고히 했습니다. 이러한 세라믹계 코팅층은 Euro 7 및 향후 시행될 EPA 규정의 PN10 기준 달성에 기여하고 있습니다. 각 OEM 업체들은 비용보다 내구성을 우선시하며, 실적이 입증된 공급업체와 다년 계약을 체결하고 있습니다. 경량 알루미늄 피스톤과의 통합을 통해 열 보호 기능을 유지하면서 질량을 줄이고 있습니다. 전 세계 시험소 프로토콜에 기반한 인증은 시장 진입 요건이 되고 있습니다.
드라이 필름 윤활 코팅은 이 부문에서 가장 높은 연평균 성장률(CAGR) 3.29%를 기록하며 시장을 주도하고 있습니다. 이황화 몰리브덴 배합 소재는 콜드 스타트 시의 경계 마찰을 줄여, 차량 전체의 평균 CO₂ 배출량 감축에 기여하고 있습니다. 신흥 화학 기술에서는 이황화 텅스텐이나 흑연 나노 플레이크를 사용하여 고부하 조건에서의 수명을 연장하고 있습니다. 다층 코팅은 유분을 밀어내는 특성을 결합함으로써 단위 면적당 기능 밀도를 높이고 있습니다. 자동차 제조업체들이 CO2 배출량 감축을 1그램 단위로 추구하는 가운데, 자동차용 피스톤 시장에서는 검증된 마찰 저감 효과를 제공하는 공급업체들이 높이 평가받고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 47.71%를 차지하며, 자동차용 피스톤 시장에서 이 지역의 중심적인 위치를 부각시키고 있습니다. 인도의 수출 지향형 조립 라인에서는 가솔린 소형차가 아프리카와 라틴아메리카로 출하되고 있어, 전 세계 내연기관(ICE) 수요를 지속시키고 있습니다. 중국에서는 국내 판매가 전기차(EV)로 전환되고 있음에도 불구하고, ‘일대일로’ 파트너국을 대상으로 대규모 내연기관(ICE) 생산을 유지하고 있습니다. 일본은 하이브리드 차량 및 수소 관련 사업에 중점을 두고 있으며, 특수 코팅이 적용된 정밀 가공 피스톤에 대한 수요가 높습니다. 지역 공급업체들은 비용 효율이 높은 알루미늄 주조품과 고급 코팅 제품 모두를 대응하기 위해 이중 생산 라인에 투자하고 있습니다.
유럽과 북미는 시장이 성숙 단계에 접어들었으나, 엄격한 배기가스 규제와 대규모 애프터마켓 차량 군 덕분에 여전히 중요한 시장으로 남아 있습니다. 유로 7 및 EPA 2027 기준에 따라 OEM 각사는 연소실 개량을 피할 수 없게 되었으며, 생산 대수 감소에도 불구하고 피스톤 기술 혁신은 계속되고 있습니다. 차량의 노후화에 따라 교체용 부품 판매가 증가하고 있으며, 이는 공급업체를 신차 시장의 변동으로부터 보호하고 있습니다. 제너럴 모터스(GM)의 V형 엔진 공장 최근 개보수 등 자본 투자가 이루어지고 있는 점으로 미루어 볼 때, 내연기관에서의 철수는 급격한 것이 아니라 장기적인 과도기임을 확인할 수 있습니다. 현지 1차 공급업체들은 부가가치가 높은 코팅 기술과 애프터마켓을 위한 신속한 유통 체계를 제공함으로써 수익성을 확보하고 있습니다.
중동 및 아프리카은 연평균 성장률(CAGR) 2.52%의 성장이 예상되며, 남미 지역도 인프라 및 가격 측면의 제약으로 인해 전동화가 지연되고 있어 판매 대수 증가가 예상됩니다. 브라질의 에탄올 차량이나 아르헨티나의 CNG 택시에는 부식성 연료에 내성이 있는 고압축비 피스톤이 필요합니다. 걸프 국가들의 석유 자금으로 운영되는 차량 플리트는 내연기관(ICE) 차량의 교체 주기가 짧기 때문에 OEM 조립 키트 및 애프터마켓 부품 수요를 뒷받침하고 있습니다. 멕시코와 남아프리카에 거점을 둔 공급업체들은 무역 협정을 활용하여 두 대륙에 효율적으로 서비스를 제공합니다. 선진국들이 전동 파워트레인으로 전환하는 가운데, 이러한 신흥 지역들은 전반적으로 자동차용 피스톤 시장의 성장 폭을 넓히고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.01According to Mordor Intelligence, the automotive piston market size is expected to grow from USD 2.98 billion in 2025 to USD 3.05 billion in 2026 and is forecast to reach USD 3.41 billion by 2031 at a 2.25% CAGR over 2026-2031.
This report is Segmented by Component Type (Piston, Piston Ring, and Piston Pin), Coating Type (Oil Shedding, Dry Film Lubrication, and Thermal Barrier), Vehicle Type (Passenger Cars and Commercial Vehicles), Material Type (Aluminum and Steel), and Geography (North America, South America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Piston Market Trends and Insights
Continued ICE Demand in Emerging Markets
Emerging economies still rely on ICE powertrains because charging infrastructure remains limited and vehicle affordability is crucial. India exported more than 800,000 vehicles in fiscal 2025, most of them gasoline or flex-fuel models serving Africa and Latin America. China follows a dual-track approach, keeping ICE exports flowing even while domestic sales shift toward battery-electric platforms. Brazil's ethanol program and Argentina's CNG taxi fleets extend the service life of piston-equipped engines, supporting regional demand. Suppliers with plants in Uttar Pradesh, Sao Paulo, or Monterrey can meet this volume efficiently. The automotive piston market benefits because low-income buyers in these regions prioritize proven ICE technology over newer alternatives.
Stringent Emissions Pushing Lightweight Aluminum and Coated Pistons
Euro 7 legislation, effective mid-2025, and forthcoming Bharat Stage 7 standards are pushing automakers toward lighter, better-cooled pistons that curb NOx and particulate emissions. Aluminum pistons with thermal-barrier crowns lower peak temperatures and allow higher compression without knock. Skirt coatings infused with molybdenum disulfide cut friction at cold start, aiding fleet-average CO2 compliance in Europe and the United States. These regulations encourage rapid technology refresh cycles, creating new contract opportunities for coated-piston specialists. As similar rules proliferate in Southeast Asia and South America, the automotive piston market scales these solutions across multiple continents.
Accelerating EV Penetration Cannibalizes ICE Volumes
Battery-electric vehicles captured roughly 40% of new registrations in China and 25% in Europe during 2025, directly displacing piston demand. Tesla, BYD, and other EV manufacturers are scaling capacity, and legacy OEMs are reallocating capital to meet carbon-neutral pledges. Fewer ICE vehicles mean fewer pistons across both OEM and aftermarket channels. The revenue impact is most severe in regions offering purchase incentives or zero-emission mandates. Suppliers are offsetting this decline by targeting markets with slower EV uptake, but the overall drag on the automotive piston market remains material.
Other drivers and restraints analyzed in the detailed report include:
- Growing Vehicle Parc Driving Aftermarket Piston Replacement
- Hydrogen-ICE Prototypes Need High-Temperature Steel Pistons
- Engine Downsizing Reduces Piston Count per Vehicle
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pistons accounted for the largest share, 49.02% of 2025 component revenue, anchoring the automotive piston market share for this segmentation. Suppliers continue refining crown geometry and skirt profiles to manage heat and reduce friction in stricter emissions regimes. Design efforts focus on weight trimming to harmonize with higher cylinder pressures in downsized engines. Pistons thus remain the volume backbone despite pressure to electrify. Tier-1 manufacturers leverage global foundries to assure just-in-time delivery for high-volume assembly plants.
Piston pins registered the fastest 3.84% CAGR as OEMs adopt DLC-coated, case-hardened varieties for turbocharged platforms. The upgrade boosts fatigue life and enables higher RPM without galling. Aftermarket buyers favor complete pin-ring kits that streamline overhaul labor. Industry collaboration with coating specialists accelerates qualification cycles and shortens time-to-market. As value shifts toward high-precision pins, smaller niche producers gain room to differentiate.
Thermal-barrier coatings led with a dominant 42.34% share in 2025, reinforcing their role in insulating piston crowns and stabilizing combustion. These ceramic-based layers help meet PN10 standards in Euro 7 and upcoming EPA rules. OEMs prioritize durability over cost, awarding multi-year contracts for proven suppliers. Integration with lightweight aluminum pistons reduces mass while preserving thermal protection. Certification per global lab protocols has become an entry requirement.
Dry-film lubrication coatings set the pace with a 3.29% CAGR, the fastest within this segment. Molybdenum disulfide blends lower boundary friction during cold starts, contributing to lower fleet-average CO2. Emerging chemistries use tungsten disulfide and graphite nanoflakes to extend life at higher loads. Multilayer coatings combine oil-shedding properties, thereby increasing the functional density per unit area. As automakers seek every gram of CO2 reduction, the automotive piston market rewards suppliers offering validated friction-reduction gains.
Complete Report Scope:
- By Component Type
- Piston
- Piston Ring
- Piston Pin
- By Coating Type
- Oil Shedding
- Dry Film Lubrication
- Thermal Barrier
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Material Type
- Aluminum
- Steel
- By Region
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 47.71% of 2025 revenue, underscoring its centrality to the automotive piston market. India's export-oriented assembly lines ship gasoline compact cars to Africa and Latin America, prolonging global ICE demand. China maintains large-scale ICE output for Belt-and-Road partners even as domestic sales tilt toward EVs. Japan emphasizes hybrid and hydrogen initiatives, requiring precision-machined pistons with specialized coatings. Regional suppliers invest in dual production lines to handle both cost-sensitive cast aluminum and premium coated products.
Europe and North America are mature but remain critical through stringent emissions mandates and sizable aftermarket fleets. Euro 7 and EPA 2027 standards oblige OEMs to refine combustion chambers, keeping piston innovation alive despite falling volumes. Aging vehicle populations elevate replacement sales, buffering suppliers from new-vehicle volatility. Capital infusions, such as General Motors' recent upgrades to V-engine plants, confirm a lengthy transition rather than an abrupt ICE exit. Local Tier-1s secure profitability by offering value-added coatings and rapid aftermarket distribution.
The Middle East and Africa, forecasted to grow at a 2.52% CAGR, and South America offer volume upside because electrification lags due to infrastructure and affordability constraints. Brazil's ethanol fleet and Argentina's CNG taxis need high-compression pistons resistant to corrosive fuels. Oil-funded fleets in Gulf states renew ICE vehicles on shorter cycles, supporting OEM assembly kits and aftermarket parts. Suppliers with facilities in Mexico or South Africa leverage trade agreements to serve both continents efficiently. Collectively, these emerging regions add growth breadth to the automotive piston market as advanced economies pivot to electrified powertrains.
- Mahle GmbH
- Tenneco Inc.
- Rheinmetall AG (Kolbenschmidt)
- Aisin Corporation
- Shriram Pistons and Rings Ltd.
- Hitachi Astemo Ltd.
- NPR Holdings Co. Ltd.
- RIKEN Corporation
- Art Metal Mfg. Co. Ltd.
- Burgess Norton
- Bohai Automotive Systems
- Hirschvogel Group
- Dongsuh Industrial Co.
- India Pistons Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Continued ICE Vehicle Demand in Emerging Markets
- 4.2.2 Stringent Emissions Pushing Lightweight Al and Coated Pistons
- 4.2.3 Growing Vehicle Parc Driving Aftermarket Piston Replacement
- 4.2.4 Hydrogen ICE Prototypes Need High-Temperature Steel Pistons
- 4.2.5 Low-Friction Skirt Coatings for Fuel-Economy Credits
- 4.2.6 3-D Printed Custom Pistons for Performance Tuning
- 4.3 Market Restraints
- 4.3.1 Accelerating EV Penetration Cannibalises ICE Volumes
- 4.3.2 Engine Downsizing Reduces Piston Count Per Vehicle
- 4.3.3 Cylinder-Deactivation Cuts Piston Duty Cycles
- 4.3.4 OEM Cap-Ex Diverted to E-Powertrain R&D
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Threat of Substitutes
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Bargaining Power of Buyers
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Component Type
- 5.1.1 Piston
- 5.1.2 Piston Ring
- 5.1.3 Piston Pin
- 5.2 By Coating Type
- 5.2.1 Oil Shedding
- 5.2.2 Dry Film Lubrication
- 5.2.3 Thermal Barrier
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Commercial Vehicles
- 5.4 By Material Type
- 5.4.1 Aluminum
- 5.4.2 Steel
- 5.5 By Region
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 Spain
- 5.5.3.4 Italy
- 5.5.3.5 France
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Mahle GmbH
- 6.4.2 Tenneco Inc.
- 6.4.3 Rheinmetall AG (Kolbenschmidt)
- 6.4.4 Aisin Corporation
- 6.4.5 Shriram Pistons and Rings Ltd.
- 6.4.6 Hitachi Astemo Ltd.
- 6.4.7 NPR Holdings Co. Ltd.
- 6.4.8 RIKEN Corporation
- 6.4.9 Art Metal Mfg. Co. Ltd.
- 6.4.10 Burgess Norton
- 6.4.11 Bohai Automotive Systems
- 6.4.12 Hirschvogel Group
- 6.4.13 Dongsuh Industrial Co.
- 6.4.14 India Pistons Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


