

|
시장보고서
상품코드
2100574
자동차용 유압 시스템 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Hydraulic Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 자동차용 유압 시스템 시장 규모는 2025년에 394억 1,000만 달러로 평가되었고 2026년 415억 4,000만 달러에서 2031년까지 540억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.41%를 나타낼 전망입니다.
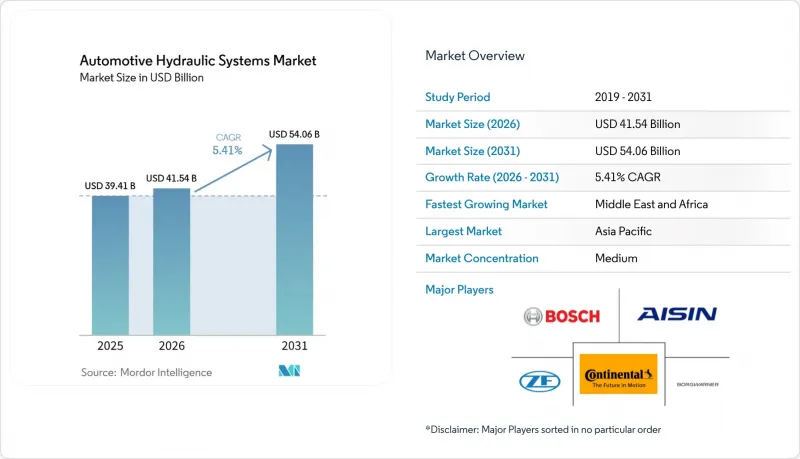
본 보고서는 용도별(브레이크, 클러치, 서스펜션 등), 부품별(마스터 실린더, 슬레이브 실린더 등), 차량 유형별(승용차, 소형 상용차 등), 판매 채널별(OEM·애프터마켓), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
전 세계 자동차용 유압 시스템 시장 동향 및 인사이트
전 세계 상용차 생산·판매 대수 증가
트럭과 버스의 생산 대수가 급증함에 따라, 1대당 유압 시스템 탑재량이 증가하고 있습니다. 이는 대형 차량의 경우 브레이크, 스티어링, 보조 구동을 위해 여러 개의 고압 회로가 필요하기 때문입니다. 인도의 자동차 산업은 2024년에 3,060만 대의 차량을 생산하여 국내 및 수출 시장에서의 유압 시스템 수요를 견인했습니다. 미국의 차량 운영사는 섀시 공급 부족에 직면해 있으며, 정기적인 유압 유지보수가 필요한 트럭의 가동률이 높아지고 있습니다. 제로 배출 트럭에 탑재되는 전동 파워트레인에는 여전히 유압 방식이 채택된 추가적인 열 관리 루프가 도입되어 있어, 이를 통해 부품 출하량이 더욱 유지되고 있습니다. 사업자들은 검증된 내구성을 중시하고 있으며, 이것이 전동화가 진행되는 상황에서도 자동차용 유압 시스템 시장을 지탱하고 있습니다.
제동 안전 기준 강화(ABS, ESC, EBS)
새로운 규정에 따라 자동차 제조업체는 정밀한 유압 제어에 의존하는 자동 긴급 제동 및 첨단 안정성 제어 시스템의 탑재가 의무화되었습니다. NHTSA의 FMVSS 127은 2029년 9월 이후 미국의 모든 경차를 대상으로 하며, 충돌 회피 속도의 목표치를 시속 62마일로 설정하고 있습니다. EU에서 도입이 예정된 Euro 7 기준에서는 브레이크 입자 배출 제한이 마련되어, 저분진형 유압 부품의 채택이 촉진됩니다. 이러한 요건으로 인해 자동차용 유압 시스템 시장에서 첨단 밸브, 부스터, 마이크로펌프에 대한 잠재 수요가 확대될 것입니다.
완전 전기식 브레이크·스티어링 시스템으로의 급속한 전환
배터리식 EV 플랫폼은 경량화와 정밀한 제어를 중시하고 있어, 유체 배관을 생략한 전기 기계식 유닛의 채택이 진행되고 있습니다. 미국에서는 EPA의 다중 오염 물질 규제가 이러한 전환을 가속화하고 있습니다. 독일의 각 공급업체들은 전기차 모델에서 유압 부품 사용량이 감소하고 있는 점을 감안하여 생산 체제를 재검토하고 있습니다. 상용 트럭의 경우 필요한 작동력이 크기 때문에 전환 속도는 완만하지만, 장기적인 대체 위험이 자동차용 유압 시스템 시장에 무겁게 드리워져 있습니다.
부문 분석
브레이크는 2025년 매출의 44.62%를 차지하며, 이 부문이 자동차용 유압 시스템 시장에서 가장 큰 점유율을 차지하고 있습니다. NHTSA(미국 도로교통안전국)의 긴급 제동 규정 등 규제 요건으로 인해 견조한 수요가 확보되고 있으며, 순수 전기차(EV)의 경우에도 유압식 백업 회로가 유지되고 있습니다. 한편, 파워 스티어링 어시스트는 전기유압식 랙이 에너지 효율과 스티어링 감각 간의 균형을 맞추면서 연평균 성장률(CAGR) 6.19%로 확대되고 있습니다. 이는 전동화 플랫폼에서 자동차용 유압 시스템 시장 규모가 계속해서 확대될 수 있음을 보여줍니다.
충돌 회피 시스템에는 고압 제어가 필요하기 때문에 브레이크 관련 수요는 안정적입니다. 조향 보조 시스템은 빠른 유압 응답에 의존하는 능동형 차선 유지 기술을 기반으로 전개되고 있습니다. 서스펜션 용도는 승차감을 추구하는 고급차 수요의 혜택을 받고 있지만, 클러치 및 팬 구동 용도는 엔진의 전동화에 따라 감소 추세를 보이고 있습니다. 상용차 분야의 회생식 유압 에너지 저장 시스템은 소폭이지만 꾸준한 기여를 보이는 신흥 하위 부문으로 부상하고 있습니다.
2025년에는 마스터 실린더가 부품 매출의 34.88%를 차지하며, 모든 차종에 보편적으로 탑재되어 있다는 사실이 부각되었습니다. 이러한 압도적인 점유율로 인해 안정적인 판매량이 확보되는 한편, ADAS(첨단 운전자 지원 시스템)에서 온디맨드 압력 공급이 요구됨에 따라 유압 펌프는 7.05%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이러한 수치는 자동차용 유압 시스템 시장에서 펌프의 점유율 확대를 의미하며, 수동적 제어 아키텍처에서 능동적 제어 아키텍처로의 전환을 시사하고 있습니다.
리저버, 호스, 매니폴드는 복합 소재를 활용한 경량 설계에 힘입어 꾸준한 성장세를 보이고 있습니다. 밸브와 액추에이터는 통합 센서를 통한 폐루프 제어가 가능해짐에 따라 매출이 증가하고 있습니다. 어큐뮬레이터의 경우, PFAS 프리 작동유 솔루션이 확립될 때까지는 전망이 엇갈리지만, 하이브리드 서스펜션의 에너지 저장 분야에서 장기적인 중요성을 유지할 가능성이 조사 결과를 통해 시사되고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 48.42%를 차지하며, 자동차용 유압 시스템 시장의 중심을 형성하고 있음을 뒷받침하고 있습니다. 2025년에는 중국이 가장 많은 자동차를 생산했습니다. 2025년 인도의 자동차 생산 대수가 대폭 증가한 것은 해당 지역의 자동차용 유압 시스템 시장 규모를 확대시켜 장기적인 수요의 기반이 되고 있습니다. 일본에서는 보조금에 힘입은 전기차(EV)의 보급으로 파워트레인용 유압 용도의 일부가 감소하는 반면, 브레이크 및 서스펜션에 대한 수요는 유지되고 있어 공급업체들은 제품 포트폴리오를 재검토해야 하는 상황에 직면해 있습니다. 탄탄한 공급망과 풍부한 노동력을 바탕으로 아시아태평양은 양산 부품공급 거점으로서 당연한 선택지가 되고 있지만, PFAS 및 누출에 관한 규제로 인해 공장에서는 유체 처리 공정의 업그레이드가 요구되고 있습니다.
북미에서는 엄격한 안전 규제와 급속한 전동화가 병행되어 진행되고 있어, 유압 수요에 상반되는 두 가지 요인이 작용하고 있습니다. NHTSA의 새로운 평가 프로토콜과 FMVSS 127로 인해 브레이크 유압 시스템의 기술적 복잡성은 유지되는 반면, EPA의 배기가스 규제는 전기차(EV)의 보급을 가속화하고 있어, 이는 향후 생산 대수를 감소시킬 가능성이 있습니다. 미국은 여전히 레벨 3 자율주행의 거점이며, 이는 전기유압 모듈 전문 제조업체에 개발상의 우위를 제공합니다. 캐나다와 멕시코는 USMCA에 기반한 통합 물류 회랑을 통해 지역적 규모를 뒷받침하고 있으며, 정책 변동에도 불구하고 북미 조립 제조업체에 대한 공급을 안정적으로 유지하고 있습니다.
유럽은 규제 수립에 있어 주도적인 입장에 있지만, 비용 경쟁력 저하로 어려움을 겪고 있습니다. 유로 7(Euro 7)의 미세먼지 배출 제한 및 PFAS 규제로 인해, 자금력이 있는 기업만이 감당할 수 있는 고액의 재설계가 불가피하기 때문입니다. 아프리카는 낮은 기저에서 2031년까지 연평균 성장률(CAGR) 7.11%라는 가장 높은 성장률을 보이고 있으며, 나이지리아, 케냐, 이집트의 인프라 투자가 오프로드용 유압 장비 수요를 끌어올리고 있습니다. 남미에서는 광업·농업 기계 분야에서 꾸준한 성장이 나타나고 있으나, 거시경제의 변동성으로 인해 전망은 불투명합니다. 중동 시장에서는 기존 파워트레인에 대한 선호도와 산업 정책에 따른 인센티브가 맞물려, 현지 유압 장비 조립을 촉진할 가능성이 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.11According to Mordor Intelligence, the automotive hydraulics systems market size was valued at USD 39.41 billion in 2025 and is estimated to grow from USD 41.54 billion in 2026 to reach USD 54.06 billion by 2031, at a CAGR of 5.41% during the forecast period (2026-2031).
This report is Segmented by Application (Brakes, Clutch, Suspension, and More), Component (Master Cylinder, Slave Cylinder, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Sales Channel (OEM and Aftermarket), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Hydraulic Systems Market Trends and Insights
Rising Global Commercial Vehicle Production and Sales
Surging truck and bus output increases hydraulic content per unit because heavy platforms need multiple high-pressure circuits for braking, steering, and auxiliary drives. India's industry produced 30.6 million vehicles in 2024, reinforcing hydraulic demand across domestic and export markets. U.S. fleet operators face chassis shortages, prompting greater utilization of trucks that require regular hydraulic maintenance. Electric powertrains in zero-emission trucks introduce extra thermal management loops that remain hydraulic, further sustaining component volumes. Operators value proven durability, which supports the automotive hydraulics systems market even as electrification spreads.
Stricter Brake-Safety Mandates (ABS, ESC, EBS)
New rules oblige carmakers to install automatic emergency braking and enhanced stability control that rely on precise hydraulic modulation. NHTSA's FMVSS 127 covers all U.S. light vehicles from September 2029 and sets collision-avoidance speed targets of 62 mph. The EU's upcoming Euro 7 standards bring brake particle limits, driving the adoption of low-dust hydraulic components. These requirements enlarge the addressable demand for advanced valves, boosters, and micro-pumps within the automotive hydraulics systems market
Rapid Shift to Fully-Electric Brake & Steering Systems
Battery EV platforms target weight savings and precise control, favoring electromechanical units that omit fluid lines. EPA multi-pollutant standards accelerate this transition in the United States. German suppliers reorganize production footprints as electric models trim hydraulic content. Commercial trucks move more slowly because of higher force requirements, yet long-term substitution risk weighs on the automotive hydraulics systems market.
Other drivers and restraints analyzed in the detailed report include:
- Growing Premium-Vehicle Demand for Hydraulic Suspension
- Electro-Hydraulic Modules for Level-3 AD Systems
- Environmental Concerns Over Hydraulic-Fluid Leakage
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Brakes accounted for 44.62% of 2025 revenue, giving this segment the largest share of the automotive hydraulics systems market. Regulatory mandates such as NHTSA's emergency braking rule lock in resilient demand, and even pure EVs retain hydraulic backup circuits. Meanwhile, power-steering assist expands at a 6.19% CAGR as electro-hydraulic racks balance energy efficiency with steering feel. This illustrates how the automotive hydraulics systems market size can continue to climb within electrified platforms.
Brake content remains stable because collision-avoidance systems need high-pressure modulation. Steering assist builds on active-lane technologies that depend on fast hydraulic response. Suspension applications benefit from premium-car demand for ride comfort, while clutch and fan-drive uses fade in line with engine electrification. Regenerative hydraulic energy storage in commercial vehicles marks an emerging sub-segment with modest but steady contributions
Master cylinders constituted 34.88% of component sales in 2025, underscoring their universal fit across vehicle classes. Their dominance ensures stable volume, while hydraulic pumps post the highest 7.05% CAGR as advanced driver assistance features require on-demand pressure. These figures translate into a portion of the automotive hydraulics systems market share for pumps, signaling a pivot from passive to active control architectures.
Reservoirs, hoses, and manifolds record incremental gains driven by lightweight designs using composite lines. Valves and actuators climb in value because integrated sensors enable closed-loop control. Accumulators face mixed prospects pending PFAS-free fluid solutions, yet research holds promise for long-term relevance in hybrid suspension energy storage.
Complete Report Scope:
- By Application
- Brakes
- Clutch
- Suspension
- Power-steering Assist
- Fan-drive Systems
- Valve-train (Tappets/Actuators)
- Others
- By Component
- Master Cylinder
- Slave / Wheel Cylinder
- Reservoir
- Hose & Tubing
- Hydraulic Pump
- Valve & Manifold
- Actuator / Booster
- Accumulator & Seals
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium & Heavy-duty Commercial Vehicles
- Off-highway Vehicles (Agriculture & Construction)
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific commands 48.42% of global revenue in 2025, underscoring its status as the center of gravity for the automotive hydraulics systems market. China produced the most vehicles in 2025. India's 2025 output of a significant number of vehicles expands the regional automotive hydraulics systems market size and anchors long-term demand. Japan's subsidy-backed EV rollout reduces certain powertrain hydraulic applications while preserving brake and suspension needs, prompting suppliers to recalibrate their portfolios. Deep supply chains and abundant labor make the Asia-Pacific region the default choice for volume components, though PFAS and leakage regulations are forcing factories to upgrade fluid-handling processes.
North America mixes rigorous safety regulations with fast-tracking electrification, creating a dual pull on hydraulic demand. NHTSA's new assessment protocols and FMVSS 127 sustain technical complexity in brake hydraulics, while EPA emissions rules accelerate EV adoption, which can trim future volumes. The United States remains a Level 3 automation hub, giving electro-hydraulic module specialists a development advantage. Canada and Mexico buttress the regional scale through integrated corridors under USMCA, stabilizing supply for North American assemblers despite policy shifts.
Europe leads on rule-making yet battles eroding cost competitiveness, as Euro 7 particle limits and PFAS curbs force costly redesigns that only well-funded firms can absorb. Africa delivers the fastest 7.11% CAGR through 2031 from a low base, with infrastructure spending in Nigeria, Kenya and Egypt lifting off-highway hydraulic demand. South America shows steady growth in mining and agricultural machinery, though macroeconomic volatility clouds visibility. Middle Eastern markets combine legacy powertrain preferences with industrial policy incentives that could spur local hydraulic assembly.
- Robert Bosch GmbH
- ZF Friedrichshafen AG
- Continental AG
- Aisin Corporation
- BorgWarner Inc.
- Valeo SA
- Eaton Corporation plc
- Schaeffler AG
- KYB Corporation
- WABCO (ZF CVCS)
- JTEKT Corporation
- GKN Automotive
- Denso Corporation
- Nexteer Automotive Group
- Nissin Kogyo Co. Ltd
- Hitachi Astemo Ltd
- Brembo SpA
- Mando Corp
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising global commercial vehicle production and sales
- 4.2.2 Stricter brake-safety mandates (ABS, ESC, EBS)
- 4.2.3 Growing premium-vehicle demand for hydraulic suspension
- 4.2.4 Electro-hydraulic modules for Level-3+ AD systems
- 4.2.5 Low-cost hydraulic packs for entry-level EVs in emerging markets
- 4.2.6 Regenerative hydraulic energy-storage in hybrid suspensions
- 4.3 Market Restraints
- 4.3.1 Rapid shift to fully-electric brake and steering systems
- 4.3.2 Environmental concerns over hydraulic fluid leakage
- 4.3.3 Elastomer-seal raw-material shortages inflating costs
- 4.3.4 OEM preference for dry brake-by-wire in robotaxi fleets
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Application
- 5.1.1 Brakes
- 5.1.2 Clutch
- 5.1.3 Suspension
- 5.1.4 Power-steering Assist
- 5.1.5 Fan-drive Systems
- 5.1.6 Valve-train (Tappets/Actuators)
- 5.1.7 Others
- 5.2 By Component
- 5.2.1 Master Cylinder
- 5.2.2 Slave / Wheel Cylinder
- 5.2.3 Reservoir
- 5.2.4 Hose & Tubing
- 5.2.5 Hydraulic Pump
- 5.2.6 Valve & Manifold
- 5.2.7 Actuator / Booster
- 5.2.8 Accumulator & Seals
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium & Heavy-duty Commercial Vehicles
- 5.3.4 Off-highway Vehicles (Agriculture & Construction)
- 5.4 By Sales Channel
- 5.4.1 OEM
- 5.4.2 Aftermarket
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Robert Bosch GmbH
- 6.4.2 ZF Friedrichshafen AG
- 6.4.3 Continental AG
- 6.4.4 Aisin Corporation
- 6.4.5 BorgWarner Inc.
- 6.4.6 Valeo SA
- 6.4.7 Eaton Corporation plc
- 6.4.8 Schaeffler AG
- 6.4.9 KYB Corporation
- 6.4.10 WABCO (ZF CVCS)
- 6.4.11 JTEKT Corporation
- 6.4.12 GKN Automotive
- 6.4.13 Denso Corporation
- 6.4.14 Nexteer Automotive Group
- 6.4.15 Nissin Kogyo Co. Ltd
- 6.4.16 Hitachi Astemo Ltd
- 6.4.17 Brembo SpA
- 6.4.18 Mando Corp
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


