|
시장보고서
상품코드
2100700
반도체 유량 제어 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Flow Control in Semiconductor Industry - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
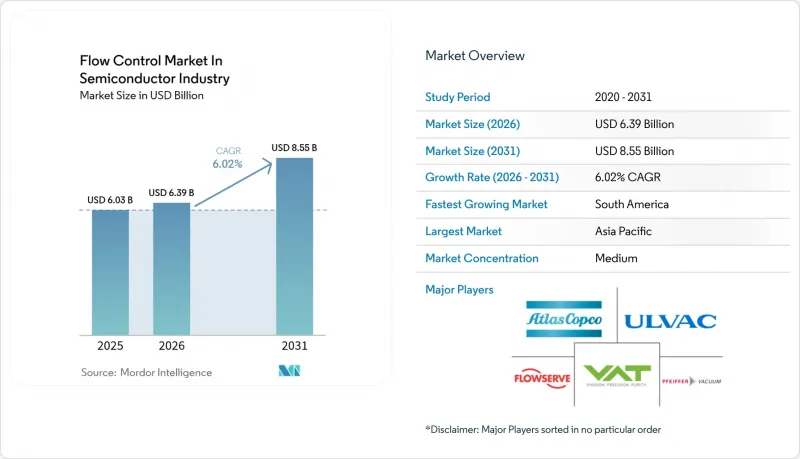
에 의하면, 반도체 유량 제어 시장 2026년 시장 규모는 63억 9,000만 달러로 추정되고 있어 2025년 60억 3,000만 달러에서 확대해, 2031년에는 85억 5,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 6.02%를 나타낼 전망입니다.

본 보고서는 구성 요소(진공 시스템, 밸브, 기계적 씰 등), 공정 단계(성막, 에칭, 이온 주입, 리소그래피 등), 유체(기체, 액체), 청정도 등급(고순도, 표준 순도), 밸브 구동 방식(수동, 공압식, 전동식) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 반도체 산업의 유량 제어 시장 동향 및 인사이트
한국 및 대만 팹에서의 EUV 리소그래피용 진공 수요의 폭발적 확대
한국 및 대만의 반도체 제조업체들은 EUV 리소그래피 생산 능력을 확대함에 따라 초고진공 유량 제어 시스템에 대한 전례 없는 수요를 주도하고 있습니다. TSMC의 High-NA EUV 기술로의 전환에는 10-11 Torr 이하의 진공도가 필요하며, 포토레지스트 처리 중 탄화수소 오염을 방지하기 위한 특수한 밸브 구성이 요구됩니다. 삼성의 EUV 로드맵에는 2026년까지 15대의 새로운 EUV 스캐너 도입이 포함되어 있으며, 각 스캐너당 약 200만-300만 달러 상당의 전용 유량 제어 인프라가 필요합니다. 이러한 기술적 복잡성은 EUV가 분자 오염에 극도로 민감하기 때문이며, 미량의 유기 화합물이라도 미러의 반사율을 저하시켜 리소그래피 수율을 떨어뜨릴 우려가 있습니다.
200층을 넘는 3D-NAND로의 전환이 고유량 ALD 밸브 수요를 끌어올리고 있다(중국)
중국이 200층을 넘는 3D-NAND 기술을 적극적으로 추구하는 가운데, 전례 없는 규모의 전구체 공급에 대응할 수 있는 고유량 ALD 밸브에 대한 수요가 크게 증가하고 있습니다. YMTC의 232층 3D-NAND 개발에는 50 nm/시간을 초과하는 증착 속도가 필요한 ALD 공정이 요구되며, 기존의 128층 공정에 비해 3-4배의 유량을 가진 밸브 시스템이 필요합니다. 기술적 과제는 300mm 웨이퍼 전체에 걸쳐 전구체의 균일성을 유지하면서, 서로 다른 화학 물질 간의 교차 오염을 방지하는 데 있습니다. 중국의 각 제조업체들은 해외 공급업체에 대한 의존도를 낮추기 위해 국내 유량 제어 능력에 막대한 투자를 하고 있으며, NAURA나 AMEC과 같은 기업들이 독자적인 밸브 기술을 개발하고 있습니다. 그러나 중국은 불소 엘라스토머 씰의 80% 이상을 일본이나 독일공급업체로부터 수입하고 있어, 고순도 소재 조달 측면에서 이러한 전환에 큰 장벽이 놓여 있습니다.
EU의 PFAS 단계적 폐지안이 소재 재설계 비용을 상승시키고 있다.
EU는 2029년까지 4,000종의 불소화 화합물을 퇴출할 계획이며, 이로 인해 밸브 제조업체들은 듀폰(DuPont)의 칼레즈(Kalrez)나 유사한 씰을 대체할 수밖에 없는 상황에 처해 있습니다. 유럽 기업들에 따르면, 소재 비용이 40-80% 증가할 뿐만 아니라 인증 주기가 18-24개월에 달할 전망이며, 2025년 4월부터 시행되는 네덜란드의 수출 규제에 대한 대응도 시급한 상황입니다.
부문 분석
2025년, 밸브는 반도체 유량 제어 시장에서 45.40%의 점유율을 차지했습니다. EUV 리소그래피 및 첨단 패키징은 초고진공에 의존하고 있기 때문에 진공 시스템 매출은 연평균 성장률(CAGR) 6.95%로 증가하고 있습니다.
누출률 10-12 mbar·L/s 미만을 유지할 수 있는 전금속 게이트 밸브 수요가 급속히 확대되고 있으며, VAT와 Fujikin이 도입을 주도하고 있습니다. 진공 시스템용 반도체 유량 제어 시장 규모는 2,000 l/s의 유량을 달성하고 MTBF가 50,000시간을 초과하는 자기 베어링이 탑재된 신형 드라이 펌프에 힘입어 가장 빠르게 확대될 전망입니다.
각 공급업체들은 밸브, 펌프, 질량 유량 제어기를 모듈식 스키드에 통합하는 움직임을 강화하고 있으며, 이를 통해 팹 설치 시간을 30% 단축하고 있습니다. 스마트 밸브에 내장된 예측 분석 기능은 처리량을 향상시키고 씰 수명을 연장함으로써 팹 운영자의 총 소유 비용(TCO)을 절감합니다. 연구 개발(R&D)의 초점은 ISO-1 청정도 기준을 충족하는 PFAS 프리 엘라스토머와 전해 연마된 유체 접촉부로 이동하고 있습니다.
박막 형성 공정은 2025년 매출의 20.80%를 차지했으나, 리소그래피는 연평균 성장률(CAGR) 7.6%로 성장하며 반도체 유량 제어 시장 수요를 견인하는 최대 요인으로 부상하고 있습니다.
원자층 증착(ALD)에서는 10억 분의 1 단위의 불순물 제어를 동반한 밀리초 단위의 밸브 전환이 요구됩니다. Applied Materials의 선택적 증착 플랫폼에서는 전구체를 신속하게 전환해야 하므로, 첨단 밸브 매니폴드가 필수적입니다. 한편, 리소그래피 장비용 반도체 유량 제어 시장 규모는 고NA EUV의 보급에 따라 확대되고 있습니다. 이는 오염이 없는 포토레지스트 라인이 수율에 직접적인 영향을 미치기 때문입니다.
에칭, 이온 주입, 습식 세정은 여전히 필수적이지만, 시장은 성숙기에 접어들었습니다. 이 분야의 업그레이드는 주로 생산 능력 증대에 따른 것입니다. 자동화된 재료 이송과 관련된 로드락 업그레이드의 경우, 생산성 향상을 목표로 하는 200mm 팹에 300mm 자동화 기술이 보급됨에 따라 투자가 다시 활발해지고 있습니다.
지역별 분석
2025년, 아시아태평양은 대만과 한국을 중심으로 반도체 유량 제어 시장의 33.60% 점유율을 차지했습니다. TSMC의 9개 팹 확장 및 삼성의 EUV 도입 확대가 최대 수요 동력이 되고 있습니다. 중국은 수출 규제에도 불구하고 여전히 막대한 성장이 예상되며, YMTC와 SMIC가 독자적인 공급망을 구축하고 있습니다. 일본의 장비 부문과 소재에 대한 전문 지식 또한 밸브 및 펌프에 대한 높은 수요를 뒷받침하고 있습니다. 북미에서는 CHIPS 법에 따라 새로운 활력이 나타나고 있습니다. 인텔, 마이크론, 세계파운드리(GlobalFoundries)의 각 프로젝트에서는 각각 1억 5,000만-2억 달러 규모의 유체 시스템이 필요하며, 이를 통해 리드타임을 단축하고 회복력을 강화하는 지역 클러스터가 형성되고 있습니다. 유럽 시장에서는 PFAS 규제로 인해 소재 재설계 비용이 증가하는 한편, 규제를 준수하는 공급업체에게는 경쟁 우위로 작용하고 있습니다. 또한 ASML의 네덜란드 거점에서는 EUV 대응 부품에 대한 전문적인 수주가 지속되고 있습니다.
브라질을 필두로 한 남미는 정부가 공급망 다각화를 도모하기 위해 반도체 조립·검사 분야에 대한 투자를 유치하고 있어 7.55%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 인프라 부족과 인력 부족은 여전히 과제로 남아 있지만, 목표가 명확한 우대 조치와 다국적 기업과의 제휴를 통해 신흥 팹 환경에 적합한 모듈식 저비용 유량 제어 패키지에 대한 수요가 서서히 증가하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.11According to Mordor Intelligence, flow control market size in semiconductor industry market size in 2026 is estimated at USD 6.39 billion, growing from 2025 value of USD 6.03 billion with 2031 projections showing USD 8.55 billion, growing at 6.02% CAGR over 2026-2031.
This report is Segmented by Component (Vacuum Systems, Valves, Mechanical Seals, and More), Process Step (Deposition, Etching, Ion Implantation, Lithography, and More), Flow Medium (Gases, Liquids), Cleanliness Rating (High-Purity, Standard-Purity), Valve Actuation Type (Manual, Pneumatic, Electric), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Flow Control in Semiconductor Industry Trends and Insights
Explosive EUV Lithography Vacuum Requirements in Korean and Taiwanese Fabs
Korean and Taiwanese semiconductor manufacturers are driving unprecedented demand for ultra-high vacuum fluid handling systems as they scale EUV lithography capacity. TSMC's transition to High-NA EUV technology requires vacuum levels below 10^-11 torr, demanding specialized valve configurations that prevent hydrocarbon contamination during photoresist processing. Samsung's EUV roadmap includes 15 new EUV scanners by 2026, each requiring dedicated fluid handling infrastructure worth approximately USD 2-3 million per tool. The technical complexity stems from EUV's sensitivity to molecular contamination, where even trace amounts of organic compounds can degrade mirror reflectivity and reduce lithography yield.
3D-NAND Transition Beyond 200 Layers Boosting High-Flow ALD Valves (China)
China's aggressive pursuit of 3D-NAND technology beyond 200 layers is creating substantial demand for high-flow atomic layer deposition valves capable of handling precursor delivery at unprecedented scales. YMTC's development of 232-layer 3D-NAND requires ALD processes with deposition rates exceeding 50 nm/hour, necessitating valve systems with flow rates 3-4 times higher than conventional 128-layer processes. The technical challenge lies in maintaining precursor uniformity across 300mm wafers while preventing cross-contamination between different chemical species. Chinese manufacturers are investing heavily in domestic fluid handling capabilities to reduce dependence on foreign suppliers, with companies like NAURA and AMEC developing indigenous valve technologies. However, the transition faces significant hurdles in high-purity material sourcing, as China imports over 80% of its fluoro-elastomer seals from Japanese and German suppliers.
EU PFAS Phase-Out Proposals Increasing Material Redesign Costs
EU plans to remove 4,000 fluorinated compounds by 2029, forcing valve makers to substitute DuPont Kalrez and similar seals. European firms report 40-80% higher material costs and 18-24 month qualification cycles while also navigating Dutch export controls effective April 2025.
Other drivers and restraints analyzed in the detailed report include:
- U.S. CHIPS Act Fab Build-out Raising Chemical-Distribution Valve Demand
- Dry Vacuum Pump Adoption to Meet PFAS-Emission Rules (Japan)
- Tight High-Purity Fluoro-Elastomer Supply Inflating Seal Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Valves held 45.40% semiconductor fluid handling market share in 2025. Vacuum system revenue is rising at a 6.95% CAGR because EUV lithography and advanced packaging rely on ultra-high vacuum.
Demand for all-metal gate valves able to hold leak rates below 10-12 mbar*l/s grows quickly, with VAT and Fujikin leading adoption. The semiconductor fluid handling market size for vacuum systems is poised to expand fastest, supported by new dry pumps with magnetic bearings that reach 2,000 l/s and exceed 50,000 hours MTBF.
Suppliers increasingly bundle valves, pumps, and mass-flow controllers in modular skids that cut fab install time by 30%. Predictive analytics embedded in smart valves improve throughput and extend seal life, reducing total cost of ownership for fab operators. R&D focus has shifted toward PFAS-free elastomers and electropolished wetted paths that meet ISO-1 cleanliness.
Deposition processes generated 20.80% of 2025 revenue, while lithography is growing at 7.6% CAGR and becoming the fastest driver of semiconductor fluid handling market demand.
Atomic-layer deposition requires millisecond valve switching with parts-per-billion impurity control. Selective deposition platforms from Applied Materials must alternate precursors rapidly, necessitating advanced valve manifolds. Conversely, the semiconductor fluid handling market size for lithography tools increases alongside High-NA EUV because contamination-free photoresist lines directly impact yield.
Etch, ion implant, and wet clean remain essential but mature; upgrades here primarily follow capacity additions. Load-lock upgrades tied to automated material transfer are experiencing renewed investment as 300 mm automation spreads to 200 mm fabs seeking productivity gains.
Complete Report Scope:
- By Component
- Vacuum Systems
- Valves
- Ball
- Butterfly
- Gate
- Globe
- Other Valves
- Mechanical Seals
- Mass Flow Controllers
- Flow Meters
- By Process Step
- Deposition (PVD / CVD / ALD)
- Etching and Dry Strip
- Ion Implantation
- Lithography
- Wafer Cleaning and CMP
- Metrology and Inspection
- Load Lock and Transfer
- Water and Waste Treatment
- By Flow Medium
- Gases
- Liquids
- By Cleanliness Rating
- High-Purity (ISO 1-3)
- Standard-Purity (ISO 4+)
- By Valve Actuation Type
- Manual
- Pneumatic
- Electric
- Solenoid
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Netherlands
- United Kingdom
- Rest of Europe
- Asia-Pacific
- China
- Taiwan
- South Korea
- Australia
- Japan
- India
- Southeast Asia
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Africa
- South Africa
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific held 33.60% semiconductor fluid handling market share in 2025, anchored by Taiwan and South Korea. TSMC's nine-fab expansion and Samsung's EUV scale-up are foremost demand engines. China remains a colossal growth prospect despite export controls, with YMTC and SMIC building indigenous supply chains. Japan's equipment sector and materials expertise also sustain high valve and pump requirements. North America enjoys renewed momentum through the CHIPS Act. Intel, Micron, and GlobalFoundries projects each require USD 150-200 million in fluid systems, fostering regional clusters that shorten lead times and bolster resilience. Europe's market confronts PFAS restrictions that inflate material redesign costs yet also create competitive moats for compliant suppliers; ASML's Dutch base sustains specialized orders for EUV-ready components.
South America, led by Brazil, registers the fastest 7.55% CAGR as governments court semiconductor assembly and test investments to diversify supply chains. Infrastructure gaps and skills shortages remain hurdles but targeted incentives and multinational partnerships are stimulating incremental demand for modular, lower-cost fluid handling packages suited to emerging fab environments.
- Pfeiffer Vacuum GmbH
- Atlas Copco AB
- Gardner Denver (Ingersoll Rand)
- Flowserve Corporation
- Busch Holding GmbH
- Kurt J. Lesker Company
- ULVAC Inc.
- Edwards Vacuum Ltd.
- Ebara Corporation
- MKS Instruments Inc.
- INFICON Holding AG
- SMC Corporation
- VAT Vakuumventile AG
- Fujikin Incorporation
- GEMU Holding GmbH and Co. KG
- Swagelok Company
- Festo SE and Co. KG
- CKD Corporation
- Parker-Hannifin Corporation
- AESSEAL plc
- EKK Eagle Industry Co.
- DuPont de Nemours Inc.
- Freudenberg Group
- Greene Tweed and Co. Inc.
- Jordan Valve (Richards Industries)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosive EUV Lithography Vacuum Requirements in Korean and Taiwanese Fabs
- 4.2.2 3D-NAND Transition Beyond 200 Layers Boosting High-Flow ALD Valves (China)
- 4.2.3 U.S. CHIPS Act Fab Build-out Raising Chemical-Distribution Valve Demand
- 4.2.4 Dry Vacuum Pump Adoption to Meet PFAS-Emission Rules (Japan)
- 4.2.5 Hybrid-Bonding Packaging Needs Sub-1 Torr Micro-Flow Controls (Global)
- 4.2.6 IIoT-Enabled Smart Valves for Predictive Maintenance (Europe)
- 4.3 Market Restraints
- 4.3.1 EU PFAS Phase-Out Proposals Increasing Material Redesign Costs
- 4.3.2 Tight High-Purity Fluoro-Elastomer Supply Inflating Seal Prices
- 4.3.3 Capex-Intensive Ultra-High-Vacuum Valves Limiting Adoption in South America
- 4.3.4 18-24 Month Qualification Cycles with Tier-1 Tool OEMs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Vacuum Systems
- 5.1.2 Valves
- 5.1.2.1 Ball
- 5.1.2.2 Butterfly
- 5.1.2.3 Gate
- 5.1.2.4 Globe
- 5.1.2.5 Other Valves
- 5.1.3 Mechanical Seals
- 5.1.4 Mass Flow Controllers
- 5.1.5 Flow Meters
- 5.2 By Process Step
- 5.2.1 Deposition (PVD / CVD / ALD)
- 5.2.2 Etching and Dry Strip
- 5.2.3 Ion Implantation
- 5.2.4 Lithography
- 5.2.5 Wafer Cleaning and CMP
- 5.2.6 Metrology and Inspection
- 5.2.7 Load Lock and Transfer
- 5.2.8 Water and Waste Treatment
- 5.3 By Flow Medium
- 5.3.1 Gases
- 5.3.2 Liquids
- 5.4 By Cleanliness Rating
- 5.4.1 High-Purity (ISO 1-3)
- 5.4.2 Standard-Purity (ISO 4+)
- 5.5 By Valve Actuation Type
- 5.5.1 Manual
- 5.5.2 Pneumatic
- 5.5.3 Electric
- 5.5.4 Solenoid
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 Netherlands
- 5.6.2.4 United Kingdom
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Taiwan
- 5.6.3.3 South Korea
- 5.6.3.4 Australia
- 5.6.3.5 Japan
- 5.6.3.6 India
- 5.6.3.7 Southeast Asia
- 5.6.4 Middle East
- 5.6.4.1 Israel
- 5.6.4.2 Saudi Arabia
- 5.6.4.3 United Arab Emirates
- 5.6.5 Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Rest of Africa
- 5.6.6 South America
- 5.6.6.1 Brazil
- 5.6.6.2 Argentina
- 5.6.6.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, JVs, Funding)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Pfeiffer Vacuum GmbH
- 6.4.2 Atlas Copco AB
- 6.4.3 Gardner Denver (Ingersoll Rand)
- 6.4.4 Flowserve Corporation
- 6.4.5 Busch Holding GmbH
- 6.4.6 Kurt J. Lesker Company
- 6.4.7 ULVAC Inc.
- 6.4.8 Edwards Vacuum Ltd.
- 6.4.9 Ebara Corporation
- 6.4.10 MKS Instruments Inc.
- 6.4.11 INFICON Holding AG
- 6.4.12 SMC Corporation
- 6.4.13 VAT Vakuumventile AG
- 6.4.14 Fujikin Incorporation
- 6.4.15 GEMU Holding GmbH and Co. KG
- 6.4.16 Swagelok Company
- 6.4.17 Festo SE and Co. KG
- 6.4.18 CKD Corporation
- 6.4.19 Parker-Hannifin Corporation
- 6.4.20 AESSEAL plc
- 6.4.21 EKK Eagle Industry Co.
- 6.4.22 DuPont de Nemours Inc.
- 6.4.23 Freudenberg Group
- 6.4.24 Greene Tweed and Co. Inc.
- 6.4.25 Jordan Valve (Richards Industries)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment