

|
시장보고서
상품코드
2113208
북미의 농업용 조제 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Agriculture Adjuvants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
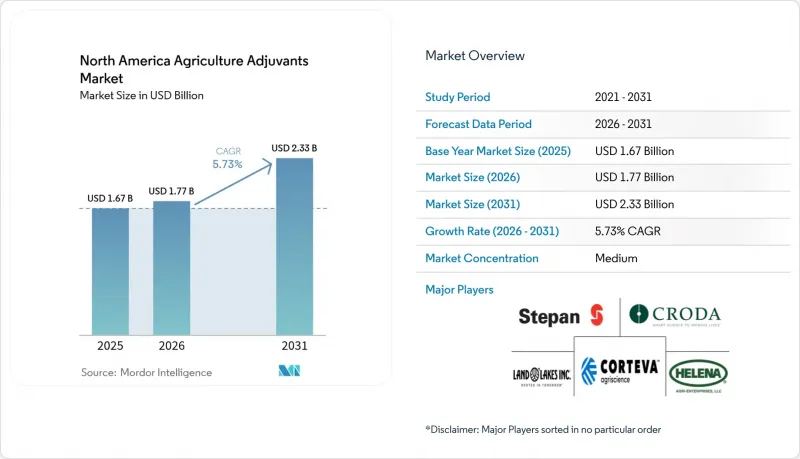
에 의하면, 2026년 북미의 농업용 조제 시장 규모는 17억 7,000만 달러로 추정되며, 2025년 16억 7,000만 달러에서 확대되어 2031년에는 23억 3,000만 달러에 달할 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 5.73%를 기록할 것으로 전망됩니다.
본 보고서는 유형별(활성제 계열 보조제 및 범용 계열 보조제), 용도별(제초제용 보조제, 살충제용 보조제, 살균제용 보조제 등), 작물별(작물 유래 및 비작물 유래), 지역별(미국, 멕시코, 캐나다 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미 농업용 보조제 시장 동향 및 인사이트
천연 및 지속 가능한 보조제 사용 확대
2024년, 미국의 유기농 경작 면적은 전년 대비 12% 증가한 560만 에이커에 달했으며, 전미 유기농 프로그램(NOP) 규정을 준수하는 OMRI 인증 보조제 시장 점유율이 확대되었습니다. 소매업체들이 공급망 파트너에게 지속가능성 평가 기준을 적용함에 따라, 많은 제초제 프로그램에서 메틸 소에이트와 에틸 락테이트가 석유 유래 작물유 농축액을 대체하고 있습니다. 2024년에 출시된 쿠로다의 유채유 유래 계면활성제 시리즈는 재생 가능한 원료가 휘발성 유기 화합물(VOC) 규제 기준을 충족하면서도, 위험이 낮은 자재를 원하는 생산자의 요구에도 부응할 수 있음을 보여줍니다. 캘리포니아주의 엄격한 휘발성 유기 화합물(VOC) 규제로 인해 이러한 추세는 더욱 가속화되고 있습니다. 저VOC 보조제는 효과를 저해하지 않으면서 대기질 규정을 준수할 수 있기 때문입니다. 식품 가공업체공급 계약에 포함된 탄소 강도 지표는 스코프 3 감축 실적을 입증할 수 있는 자재 공급업체에 보상을 제공함으로써 수요를 더욱 확대되고 있습니다.
작물 보호용 화학물질 수요 증가
팔머 아마란스와 워터헴프의 글리포세이트 내성으로 인해, 2020년 이후 중서부 지역의 옥수수 및 대두 재배 시스템에서 1에이커당 제초제 살포 횟수가 25% 급증했습니다. 이로 인해 유효 성분의 투여량을 늘리지 않고도 살포 범위를 확보하기 위해 보조제 사용량이 증가하고 있습니다. 멕시코에서도 유사한 경향이 나타납니다. ‘Fertilizantes para el Bienestar’ 프로그램에 따라 시날로아주 및 소노라주의 상업 농장에 대해 연방 정부의 보조금을 통해 제초제 및 보조제 비용의 최대 50%가 지원되고 있습니다. 또한, 옥수수 뿌리벌레와 대두 진딧물의 개체군에서 피레스로이드계 살충제에 대한 내성이 확산됨에 따라 살충제용 보조제 사용량도 증가하고 있으며, 표피 침투성 및 내우성을 높이는 화학 물질에 대한 관심이 높아지고 있습니다. 아몬드와 포도 생산자들은 살균제의 수관 피복성을 높이기 위해 고품질 보조제를 채택하고 있습니다. 이를 통해 살포 간격을 연장하고, 성수기의 인력 부족을 완화하고 있습니다. 생산자들은 작용기전의 조합이나 pH를 조절하는 보조제, 물의 경도를 관리하는 보조제 등을 병용하고 있으며, 이러한 보조제들은 복잡한 탱크 혼합 시 발생하는 항균 작용을 피하기 위해 필수적인 요소로 자리 잡고 있습니다.
환경보호청 및 규제 지침의 강화
환경보호청(EPA)의 ‘2024년 제초제 전략’에 따르면, 『멸종위기종 보호법』에 따라 지정된 1,500개 카운티에서 살포업자는 보조제 선정 내용 및 기상 매개변수를 기록해야 할 의무가 있으며, 소규모 사업자는 새로운 기록 관리 시스템을 도입하거나,아니면 규정 위반에 따른 처벌을 받게 됩니다. 거친 액적 사용 의무는 현재 미국 경작지의 40%에 달하며, 이로 인해 작은 잡초에 대한 효과가 떨어지거나 부적절한 보조제가 사용된 경우 재처리가 필요할 수 있습니다. 캐나다 해충관리규제청(PMRA)은 모든 계면활성제 성분에 대해 수생 독성 데이터 제출을 의무화하여, 이로 인해 신규 진출기업의 등록 기간이 연장되고 비용이 증가하고 있습니다. 멕시코는 노닐페놀 에톡실레이트 혼합물의 수입 허가를 엄격히 규제하여, 판매업자들에게 배합 변경이나 시장 철수를 강요하고 있습니다. 이러한 장벽이 높아지는 가운데, 미국 환경보호청(EPA)의 등록을 취득한 공급업체는 시장에서 우위를 점하고 있습니다. 이는 생산자들이 감사를 간소화할 수 있는 추적 가능한 제품을 선호하기 때문입니다.
부문 분석
2025년에는 계면활성제계 보조제가 매출의 60.25%를 차지했습니다. 이는 옥수수 및 대두의 발아 후 제초제 프로그램에서 비이온성 계면활성제와 작물유 농축물이 여전히 핵심을 이루고 있기 때문입니다. 메틸소에이트를 포함한 유성 블렌드는 침투성과 내우성을 높여주고 있어, 바이오 대체품이 등장하고 있음에도 불구하고 여전히 시장에서 입지를 유지하고 있습니다. 한편, 범용 보조제는 2031년까지 연평균 9.41%의 성장률을 보일 것으로 예측되며, 이 기간이 끝날 무렵 북미 농업용 보조제 시장 규모는 이 카테고리만으로도 9억 8,000만 달러를 크게 넘어설 것으로 전망됩니다. 이러한 급속한 성장의 주된 원인은 드리프트 억제용 폴리머와 부착 촉진제에 있습니다. 이는 정밀 살포기가 탱크 내 유효 성분 농도를 3배로 높이기 때문에 전용 첨가제 없이는 막힘 위험이 높아지기 때문입니다.
수질 조절제 또한 높은 성장이 예상되는 분야 중 하나입니다. 이는 처리되지 않은 경수 조건에서는 글리포세이트의 효능이 최대 30%까지 떨어질 수 있다는 증거가 있기 때문입니다. 또한, 생물 유래 제품이 주류를 이루고 있는 가운데, 상용제 또한 중요한 역할을 하고 있습니다. 미생물 제제와 합성 제제를 혼합할 때 응집을 방지하기 위해, 한 번의 살포로 시용을 완료하고자 하는 생산자에게 있어 용해성제는 필수적인 요건이 되고 있습니다. 이러한 실용 분야에서의 성장세에 힘입어, 북미 농업용 보조제 시장에서 액티베이터 시장 점유율은 액티베이터의 절대 매출액이 증가하고 있음에도 불구하고 소폭 하락할 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.24According to Mordor Intelligence, North America agriculture adjuvants market size in 2026 is estimated at USD 1.77 billion, growing from 2025 value of USD 1.67 billion with 2031 projections showing USD 2.33 billion, growing at 5.73% CAGR over 2026-2031.
This report is Segmented by Type (Activator Adjuvants and Utility Adjuvants), by Application (Herbicide Adjuvants, Insecticide Adjuvants, Fungicide Adjuvants, and More), by Crop Type (Crop-Based and Non-Crop-Based), and by Geography (United States, Mexico, Canada, and More). The Market Forecasts are Provided in Terms of Value (USD).
North America Agriculture Adjuvants Market Trends and Insights
Increasing Use of Natural and Sustainable Adjuvants
Organic acreage in the United States grew 12% year on year to 5.6 million acres in 2024, opening more shelf space for OMRI-listed adjuvants that comply with National Organic Program rules . Methyl soyate and ethyl lactate are now displacing petroleum-based crop-oil concentrates in many herbicide programs as retailers extend sustainability scorecards to their supply partners. Croda's rapeseed-derived surfactant line, launched in 2024, illustrates how renewable feedstocks can satisfy both volatile-organic-compound limits and grower preference for lower-risk inputs. California's stringent Volatile Organic Compound (VOC) rules accelerate this trend because low adjuvants preserve air-quality compliance without compromising efficacy. Carbon-intensity metrics embedded in food-processor supply contracts amplify demand by rewarding input suppliers that can document Scope 3 reductions.
Growing Demand for Crop-Protection Chemicals
Palmer amaranth and waterhemp resistance to glyphosate triggered a 25% surge in herbicide treatments per acre in Midwestern corn and soybean systems since 2020, elevating adjuvant usage to maintain coverage without raising active-ingredient loads. Mexico mirrors this trajectory: federal subsidies now offset up to 50% of herbicide and adjuvant costs for commercial farms in Sinaloa and Sonora under the Fertilizantes para el Bienestar program. Insecticide adjuvants are also climbing as pyrethroid resistance spreads in corn rootworm and soybean aphid populations, spurring interest in chemistries that enhance cuticle penetration and rainfastness. Almond and grape growers deploy premium adjuvants to enhance fungicide canopy coverage, thereby extending spray intervals and reducing labor bottlenecks during peak season as growers stack modes of action, adjuvants that buffer pH, and manage water hardness, becoming indispensable to avoid antagonism in complex tank mixes.
Stringent Environmental Protection Agency and Regulatory Guidelines
The Environmental Protection Agency's (EPA's) 2024 Herbicide Strategy requires applicators in 1,500 counties designated under the Endangered Species Act to log adjuvant selection and weather parameters, prompting small operators to adopt new record-keeping systems or face compliance penalties. Coarser droplet mandates now cover 40% of the United States cropland, which can reduce efficacy on small-seeded weeds and may lead to repeat treatments if unsuitable adjuvants are used. Canada's Pest Management Regulatory Agency added aquatic-toxicity data requirements for every surfactant component, extending registration timelines and raising costs for new entrants. Mexico tightened import permits on nonylphenol ethoxylate blends, forcing distributors either to reformulate or exit. As hurdles rise, suppliers with Environmental Protection Agency (EPA) registrations gain a market advantage because growers prefer traceable products that simplify audits.
Other drivers and restraints analyzed in the detailed report include:
- Higher Investment in Adjuvant R&D by Multinationals
- Expansion of Precision-Spraying Technologies
- Low Grower Awareness in Specialty-Crop Pockets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Activator adjuvants accounted for 60.25% of the revenue in 2025, as non-ionic surfactants and crop-oil concentrates remained core to post-emergence herbicide programs in corn and soybeans. Oil-based blends that include methyl soyate offer enhanced penetration and rainfastness, explaining their continued presence even as bio-based alternatives emerge. Utility adjuvants, however, are forecast to rise 9.41% annually to 2031, lifting the North America agriculture adjuvants market size for this category well above USD 980 million by the period end. Drift-control polymers and deposition aids form the backbone of this surge because precision sprayers triple the active-ingredient concentration in the tank, which increases the risk of clogging without specialized additives .
Water conditioners are another high-growth pocket, given evidence that untreated hard-water conditions can slash glyphosate efficacy by as much as 30%. Compatibility agents round out the story as biologicals move mainstream, making it a non-negotiable requirement for growers who want single-pass applications, preventing flocculation when mixing microbes and synthetics. Momentum in these utility segments means the North America agriculture adjuvants market share for activators is expected to slide modestly even as absolute activator revenue rises.
Complete Report Scope:
- By Type
- Activator Adjuvants
- Surfactants
- Oil Adjuvants
- Utility Adjuvants
- Activator Adjuvants
- By Application
- Herbicide Adjuvants
- Insecticide Adjuvants
- Fungicide Adjuvants
- Other Applications
- By Crop Type
- Crops Based
- Grains and Cereals
- Fruits and Vegetables
- Oil Seeds
- Other Applications
- Non-Crops Based
- Turf and Ornamental Grass
- Others
- Crops Based
- By Geography
- United States
- Canada
- Mexico
- Rest of North America
List of Companies Covered in this Report:
- Corteva Agriscience
- Land O'Lakes Inc.
- Stepan Company
- Croda International plc
- Helena Agri-Enterprises LLC (Marubeni Corporation)
- Huntsman Corporation
- Farmers Business Network Inc.
- BASF SE
- Evonik Industries AG
- Solvay SA
- Nufarm Limited
- Loveland Products Inc. (Nutrien Ltd.)
- Wilbur-Ellis Company LLC
- Clariant AG
- Nouryon Holding B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing use of natural and sustainable adjuvants
- 4.2.2 Growing demand for crop-protection chemicals
- 4.2.3 Higher investment in adjuvant R&D by multinationals
- 4.2.4 Expansion of precision-spraying technologies
- 4.2.5 Carbon-credit incentives for input-efficiency products
- 4.2.6 Surfactant blends optimized for biologicals
- 4.3 Market Restraints
- 4.3.1 Stringent Environmental Protection Agency and regulatory guidelines
- 4.3.2 Low grower awareness in specialty-crop pockets
- 4.3.3 Volatility in tall-oil and methyl-soyate feedstocks
- 4.3.4 Increasing scrutiny of wetting agents
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Activator Adjuvants
- 5.1.1.1 Surfactants
- 5.1.1.2 Oil Adjuvants
- 5.1.2 Utility Adjuvants
- 5.1.1 Activator Adjuvants
- 5.2 By Application
- 5.2.1 Herbicide Adjuvants
- 5.2.2 Insecticide Adjuvants
- 5.2.3 Fungicide Adjuvants
- 5.2.4 Other Applications
- 5.3 By Crop Type
- 5.3.1 Crops Based
- 5.3.1.1 Grains and Cereals
- 5.3.1.2 Fruits and Vegetables
- 5.3.1.3 Oil Seeds
- 5.3.1.4 Other Applications
- 5.3.2 Non-Crops Based
- 5.3.2.1 Turf and Ornamental Grass
- 5.3.2.2 Others
- 5.3.1 Crops Based
- 5.4 By Geography
- 5.4.1 United States
- 5.4.2 Canada
- 5.4.3 Mexico
- 5.4.4 Rest of North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Corteva Agriscience
- 6.4.2 Land O'Lakes Inc.
- 6.4.3 Stepan Company
- 6.4.4 Croda International plc
- 6.4.5 Helena Agri-Enterprises LLC (Marubeni Corporation)
- 6.4.6 Huntsman Corporation
- 6.4.7 Farmers Business Network Inc.
- 6.4.8 BASF SE
- 6.4.9 Evonik Industries AG
- 6.4.10 Solvay SA
- 6.4.11 Nufarm Limited
- 6.4.12 Loveland Products Inc. (Nutrien Ltd.)
- 6.4.13 Wilbur-Ellis Company LLC
- 6.4.14 Clariant AG
- 6.4.15 Nouryon Holding B.V.


