

|
시장보고서
상품코드
2113917
보행 보조 기기 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Walking Assist Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
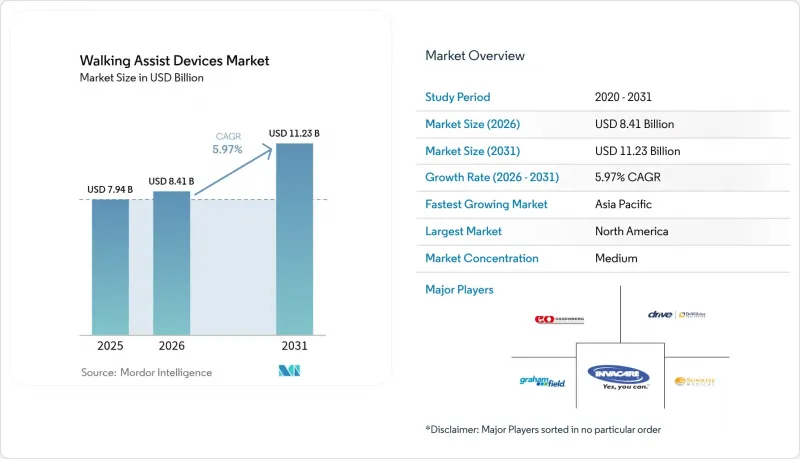
에 의하면, 보행 보조 기기 시장 규모는 2025년 79억 4,000만 달러로 평가되었습니다. 2026년에는 84억 1,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 5.97%로 성장을 지속하여, 2031년에는 112억 3,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형별(지팡이, 목발, 보행기·롤러터, 휠체어, 기타),기술별(수동 보조 기기, 전동 이동 기기, 기타), 최종 사용자별(병원 및 클리닉, 재활센터, 기타), 유통 채널별(약국·소매점, 전자상거래 플랫폼, 의료용품 판매업체), 지역별(북미, 유럽, 아시아태평양, 기타)로 분류되어 있습니다.
세계의 보행 보조 기기 시장 동향 및 인사이트
퇴행성 관절염·류마티스 관절염 유병률 증가
퇴행성 관절염으로 인한 부담은 비만 및 장시간 앉아 있는 생활 습관과 함께 증가하고 있습니다. 미국에서는 3,250만 명이 퇴행성 관절염을 앓고 있으며, 직접적인 의료비는 연간 650억 달러에 달할 전망입니다. 전 세계 환자 수는 현재 6억 600만 명을 넘어섰으며, 55세 이후 발병률이 급격히 상승하기 때문에 보조 기구는 장기 요양의 필수적인 요소가 되고 있습니다. 류마티스 관절염도 유사한 추세를 보이고 있으며, 2024년 데이터에 따르면 흡연이 인과적 위험 요인임이 확인되었고, 사회경제적으로 유리한 지역에서는 여성의 발병률이 높은 것으로 나타났습니다. 이러한 추세로 인해 휠체어, 보행기, 관절에 가해지는 부담을 경감시키는 솔루션에 대한 수요가 뒷받침되고 있습니다.
수술 후 재활 기기에 대한 수요 증가
2024년에는 선택적 관절 치환술 건수가 회복되었으며, 현재는 하이브리드형 원격 재활 프로그램이 외래 환자의 회복 과정을 지원하고 있습니다. 지속적 수동 운동 장치, 센서 장착 보행기, 경량 휠체어를 통해 조기 퇴원이 가능해지며 재입원 위험이 감소합니다. 또한, 중환자실(ICU)에서 발생한 근력 저하에 대처하기 위해 보행기에 신경근 전기 자극 기능이 탑재되는 사례가 늘고 있습니다.
전동 기기의 높은 구입 및 유지 비용
WHILL Model Ci와 같은 보급형 전동 휠체어의 소매 가격은 4,999달러로, 많은 환자에게는 감당하기 어려운 가격입니다. 리튬 이온 배터리 팩은 5-7년마다 교체해야 하며, 그 비용은 초기 비용의 최대 40%에 달할 전망입니다. 모터의 의도파관 않은 작동과 관련된 781대의 SmartDrive 유닛을 포함한 최근의 리콜 사례는 엄격한 품질 관리의 필요성을 여실히 보여주고 있습니다. 이러한 사고는 보험료나 서비스 요금 인상으로 이어져, 비용 측면에 대한 우려를 더욱 가중시키고 있습니다.
부문 분석
2025년, 휠체어는 전 세계 매출의 47.12%를 차지하며, 급성기 및 장기 요양 분야 모두에서 중심적인 역할을 하고 있는 것으로 확인되었습니다. 현재는 수동식 모델이 주류를 이루고 있지만, 배터리 가격 하락에 따라 전동식 및 스마트형 모델이 주요 구매 대상으로 자리 잡고 있습니다. 보행용 벨트, 리프트 조끼, 관련 이송 보조 기구는 연평균 성장률(CAGR) 7.03%로, 다른 카테고리를 상회하는 성장이 예상됩니다. 이러한 성장세는 근로자 안전에 관한 규제 강화와 간병인의 부상을 최소화하려는 움직임을 반영하고 있습니다.
FDA 및 CE 규정에 따라 클래스 I 또는 클래스 II로 지정되어 있어, 규제의 명확성이 휠체어의 기초적인 수요를 뒷받침하고 있습니다. 탈부착 가능한 양방향 추진 시스템과 같은 혁신 기술은 인체공학적 편의성을 향상시키고 이용 사례를 확대하며, 보행 보조 기기 시장에 지속적인 활력을 불어넣고 있습니다. 한편, 파킨슨병이나 뇌졸중 후 환자를 위한 낙상 방지 기기는 기존 제품의 경계를 모호하게 만들고, 웨어러블 기술과의 융합을 시사하고 있습니다.
보행 보조 기기 시장에서 수동식 기기 시장 규모는 여전히 가장 크지만, 스마트 센서 플랫폼이 가장 빠른 성장세를 보이고 있습니다. 수동식 휠체어, 목발, 보행기는 가격이 저렴하고 충전이 필요 없으며 사이버 위험도 최소화되어 2025년에는 56.20%의 점유율을 차지했습니다. 연평균 성장률(CAGR) 7.74%로 성장을 지속하고, 있는 스마트 기기에는 LiDAR, 압력 센서, 실시간 분석 기능이 탑재되어 있어 장애물 경고 및 생체 신호 모니터링이 가능합니다. 전동 휠체어는 배터리 기술의 혁신과 시험 기준의 명확화로 인해 그 중간 위치에 자리 잡고 있습니다.
의료용 IoT(Internet of Medical Things)는 클라우드 대시보드를 통한 지속적인 모니터링을 가능하게 하여, 임상의가 원격으로 치료를 조정할 수 있게 해줍니다. 반면, 사이버 보안은 비용과 복잡성을 증가시킵니다. 현재 FDA는 연결형 보조 기기에 대해 소프트웨어 부품 목록과 시판 후 패치 적용 계획의 제출을 의무화하고 있습니다. 실제로 사용자는 가격, 유지보수 능력, 정보 공유에 대한 안심감 등의 요소를 종합적으로 고려하여 선택하고 있습니다.
지역별 분석
2025년, 북미는 견고한 보험 적용 범위와 확립된 임상 경로에 힘입어 전 세계 매출의 40.21%를 차지했습니다. 이 지역은 2026년에 시행될 FDA 품질 시스템 개정의 혜택을 받고 있으며, 이를 통해 시판 후 모니터링이 간소화되고 공급업체 감사 기준이 통일될 것입니다. 그러나 전동 휠체어의 높은 정가와 환급과 관련된 복잡한 코딩이 도입 지연으로 이어질 가능성이 있습니다. 최근 메디케어에 대한 부정 청구를 둘러싸고 1,350만 달러의 합의가 성사된 것은 청구 처리에 대한 모니터링이 여전히 엄격함을 여실히 보여주고 있습니다. 캐나다의 보조기기 지원 프로그램과 멕시코에서 지속적으로 성장하고 있는 민간 보험 부문이 해당 지역 수요를 더욱 끌어올리고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.19%를 나타낼 것으로 예측되며, 이는 세계에서 가장 빠른 속도입니다. 2016년부터 2050년에 걸쳐 80세 이상 인구가 4배로 증가할 것이라는 인구 동향의 추세와, 콤팩트하고 경량화된 보조기구를 선호하는 도시 지역의 과밀화 문제가 맞물려 시장을 견인하고 있습니다. 일본에서는 간병보험을 통해 고급 휠체어 비용이 지급되는 반면, 중국의 국내 제조업체들은 수출용 전동 스쿠터 라인업을 확충하고 있습니다. 고령자의 약 40%가 연금 제도의 적용 대상에서 제외되어 있기 때문에 합리적인 가격은 필수적이며, 그 결과 대여 프로그램과 재생 기기 교환 서비스가 급증하고 있습니다.
유럽에서는 국민건강보험 제도와 통일된 CE 마킹 요건의 뒷받침을 받아 꾸준한 성장을 유지하고 있습니다. 독일과 프랑스에서는 법정 보험을 통해 판매량을 견인하고 있는 반면, 영국에서는 브렉시트 이후 적합성 프로토콜 조정이 진행되고 있습니다. 독일에 본사를 둔 선라이즈 메디컬(Sunrise Medical)은 지역 내 제조 체계와 라이드 디자인스(Ride Designs) 등의 최근 인수를 활용하여 시트 제품 라인업을 확대되고 있습니다. 의료기기 규정(EU) 2017/745는 보다 엄격한 임상적 증거와 시판 후 모니터링을 의무화하고 있어, 강력한 품질 보증(QA) 시스템을 갖춘 공급업체에 유리하게 작용하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.26According to Mordor Intelligence, the walking assist devices market size is expected to grow from USD 7.94 billion in 2025 to USD 8.41 billion in 2026 and is forecast to reach USD 11.23 billion by 2031 at 5.97% CAGR over 2026-2031.
This report is Segmented by Product Type (Canes, Crutches, Walkers/Rollators, Wheelchairs, and More), by Technology (Manual Assist Devices, Powered Mobility Devices, and More), by End User (Hospitals and Clinics, Rehabilitation Centers, and More), by Distribution Channel (Pharmacy and Retail Stores, E-Commerce Platforms, Medical Supply Dealers), by Geography (North America, Europe, Asia-Pacific, and More).
Global Walking Assist Devices Market Trends and Insights
Accelerating prevalence of osteoarthritis & rheumatoid arthritis
The osteoarthritis burden is rising in tandem with obesity and sedentary lifestyles. In the United States, 32.5 million people live with osteoarthritis and direct medical costs reach USD 65 billion annually. Global prevalence now exceeds 606 million cases, and incidence climbs sharply after age 55, making assistive devices a routine component of long-term care. Rheumatoid arthritis follows a similar pattern, with 2024 data confirming smoking as a causal risk factor and showing higher rates among women in high socio-demographic regions. These trends sustain demand for wheelchairs, walkers and joint-offloading solutions.
Rising demand for post-operative rehabilitation equipment
Elective joint-replacement volumes rebounded in 2024, and hybrid telerehabilitation programmes now support outpatient recovery pathways. Continuous-passive-motion devices, sensorised walkers and lightweight wheelchairs allow earlier discharge and reduce readmission risk. Neuromuscular electrical stimulation is increasingly embedded in walkers to counter ICU-acquired weakness.
High acquisition & maintenance costs of powered devices
Entry-level powered wheelchairs such as the WHILL Model Ci retail for USD 4,999, out of reach for many patients. Lithium-ion battery packs require replacement every five to seven years, adding up to 40% of initial cost. Recent recalls, including 781 SmartDrive units linked to unintended motor activation, underline the need for rigorous quality control. Such incidents amplify cost concerns by elevating insurance premiums and service fees.
Other drivers and restraints analyzed in the detailed report include:
- Rapidly expanding geriatric population base
- Commercialization of AI-enabled smart canes & sensor walkers
- Limited reimbursement coverage in developing nations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wheelchairs held 47.12% of global revenue in 2025, confirming their central role in both acute and long-term settings. Manual models dominate today, but powered and smart variants are entering mainstream procurement as battery prices fall. Gait belts, lift vests and related transfer aids are projected to outpace other categories at 7.03% CAGR. Their rise reflects stricter worker-safety rules and the push to minimize caregiver injuries.
Regulatory clarity sustains baseline wheelchair demand, given their Class I or Class II designation under FDA and CE rules. Innovations such as the detachable two-way propulsion system improve ergonomics and widen use cases, keeping the walking assist devices market dynamic. Meanwhile, fall-prevention devices for Parkinson's and post-stroke patients are blurring traditional boundaries, hinting at convergence with wearable technologies.
The walking assist devices market size for manual devices remains the largest, yet smart sensor platforms are registering the fastest gains. Manual chairs, crutches and walkers are affordable, need no charging and carry minimal cyber-risk, explaining their 56.20% share in 2025. Smart devices, posting 7.74% CAGR, embed lidar, pressure sensors and real-time analytics to warn of obstacles or monitor vital signs. Powered chairs occupy a middle ground, benefiting from battery innovations and clearer test standards.
The Internet of Medical Things enables continuous monitoring through cloud dashboards, allowing clinicians to adjust therapy remotely. Still, cyber-security adds cost and complexity; FDA now requires software bills of materials and post-market patching plans for connected aids. In practice, users choose along a spectrum of price, maintenance capacity and information-sharing comfort.
Complete Report Scope:
- By Product Type
- Canes
- Crutches
- Walkers/Rollators
- Wheelchairs
- Gait Belts & Lift Vests
- Power Scooters
- Others
- By Technology
- Manual Assist Devices
- Powered Mobility Devices
- Smart Sensor-Enabled Devices
- By End User
- Hospitals and Clinics
- Rehabilitation Centers
- Home-care Settings
- Elderly-care Facilities
- By Distribution Channel
- Pharmacy and Retail Stores
- E-commerce Platforms
- Medical Supply Dealers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 40.21% of global revenue in 2025, anchored by robust insurance coverage and established clinical pathways. The region benefits from new FDA Quality System amendments effective in 2026, which simplify post-market surveillance and align supplier audits. Yet high list prices for powered chairs and complex coding for reimbursement can delay adoption. The recent USD 13.5 million settlement involving improper Medicare claims underscores ongoing billing scrutiny. Canada's assistive-device programmes and Mexico's growing private insurance sector add depth to regional demand.
Asia-Pacific is projected to deliver an 8.19% CAGR to 2031, the fastest worldwide. Demographic momentum, with the 80+ cohort quadrupling between 2016 and 2050, intersects with urban-density challenges that favour compact, lightweight aids. Japan's long-term-care insurance reimburses high-end wheelchairs, while China's domestic manufacturers scale up powered scooter lines for export. Approximately 40% of seniors lack pension coverage, making affordability essential; as a result, rental programmes and refurbished equipment exchanges are proliferating.
Europe maintains steady growth backed by universal healthcare and harmonised CE marking requirements. Germany and France drive volume through statutory insurance, whereas the United Kingdom adjusts post-Brexit conformity protocols. Sunrise Medical, headquartered in Germany, leverages in-region manufacturing and recent acquisitions such as Ride Designs to broaden its seating portfolio. The Medical Device Regulation (EU) 2017/745 imposes more stringent clinical evidence and post-market vigilance, benefiting suppliers with strong QA systems.
- Invacare
- Sunrise Medical
- Permobil AB
- GF Health Products, Inc.
- Pride Mobility Products Corporation
- Honda Motor Co. (Walking Assist)
- Ottobock
- Ekso Bionics
- ReWalk Robotics
- Drive DeVilbiss Healthcare (Medical Depot, Inc. )
- Medline Industries
- Karma Medical
- Yuwell Group
- Topro Industrie AS
- LifeWalker Mobility (UPWalker)
- Besco Medical
- Human Care Group
- Ossenberg
- Benmor Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating prevalence of osteoarthritis & rheumatoid arthritis
- 4.2.2 Rising demand for post-operative rehabilitation equipment
- 4.2.3 Rapidly expanding geriatric population base
- 4.2.4 Increasing fall-related injuries prompting preventive walking aids
- 4.2.5 Commercialisation of AI-enabled smart canes & sensor walkers
- 4.2.6 Growth in long-COVID-linked mobility impairments
- 4.3 Market Restraints
- 4.3.1 High acquisition & maintenance costs of powered devices
- 4.3.2 Limited reimbursement coverage in developing nations
- 4.3.3 Product recalls due to safety / stability issues
- 4.3.4 Cyber-security & data-privacy risks in connected mobility aids
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Canes
- 5.1.2 Crutches
- 5.1.3 Walkers/Rollators
- 5.1.4 Wheelchairs
- 5.1.5 Gait Belts & Lift Vests
- 5.1.6 Power Scooters
- 5.1.7 Others
- 5.2 By Technology
- 5.2.1 Manual Assist Devices
- 5.2.2 Powered Mobility Devices
- 5.2.3 Smart Sensor-Enabled Devices
- 5.3 By End User
- 5.3.1 Hospitals and Clinics
- 5.3.2 Rehabilitation Centers
- 5.3.3 Home-care Settings
- 5.3.4 Elderly-care Facilities
- 5.4 By Distribution Channel
- 5.4.1 Pharmacy and Retail Stores
- 5.4.2 E-commerce Platforms
- 5.4.3 Medical Supply Dealers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Invacare Corporation
- 6.3.2 Sunrise Medical
- 6.3.3 Permobil AB
- 6.3.4 GF Health Products, Inc.
- 6.3.5 Pride Mobility Products Corporation
- 6.3.6 Honda Motor Co. (Walking Assist)
- 6.3.7 Ottobock SE & Co. KGaA
- 6.3.8 Ekso Bionics
- 6.3.9 ReWalk Robotics
- 6.3.10 Drive DeVilbiss Healthcare (Medical Depot, Inc. )
- 6.3.11 Medline Industries
- 6.3.12 Karma Medical
- 6.3.13 Yuwell Group
- 6.3.14 Topro Industrie AS
- 6.3.15 LifeWalker Mobility (UPWalker)
- 6.3.16 Besco Medical
- 6.3.17 Human Care Group
- 6.3.18 Ossenberg GmbH
- 6.3.19 Benmor Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


