

|
시장보고서
상품코드
2123654
지팡이 및 목발 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Global Canes And Crutches - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
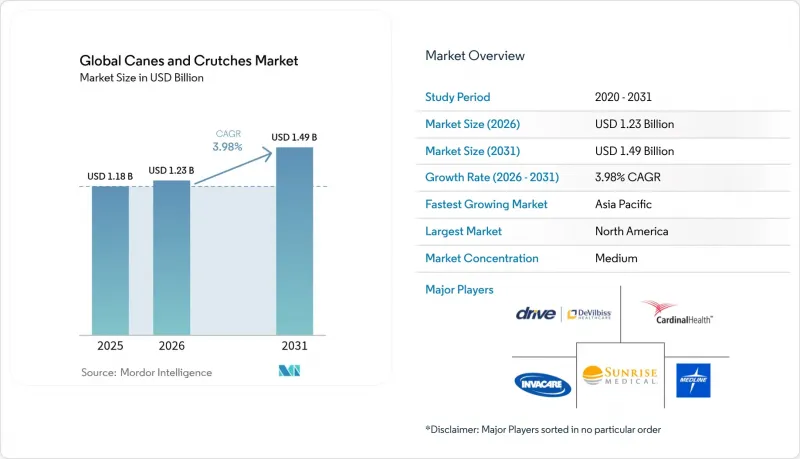
에 의하면, 지팡이 및 목발 시장 규모는 2025년에 11억 8,000만 달러로 평가되었고, 2026년 12억 3,000만 달러에서 2031년까지 14억 9,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 3.98%를 나타낼 전망입니다.
본 보고서는 제품 유형별(지팡이(싱글 포인트 지팡이 등), 목발(겨드랑이 목발 등), 기타), 소재별(목재, 알루미늄, 기타), 최종 사용자별(병원 및 클리닉, 재택 간호, 기타), 유통 채널별(소매 약국, 기타), 지역별(북미, 유럽, 아시아태평양, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 지팡이 및 목발 시장 동향 및 인사이트
전 세계 고령 인구 증가
유엔 데이터에 따르면, 최빈국(LDC)에서 65세 이상 고령자 비율이 급격히 상승하고 있어, 지팡이 및 목발 시장의 장기적인 확대 추세가 뒷받침되고 있습니다. 고령층의 확대는 균형 보조 기구에 대한 수요 증가뿐만 아니라, 진행 중인 신체 기능 저하에 따른 교체 수요 증가로 직결됩니다. 일본을 비롯한 아시아 국가들에서는 2025년까지 고령자 1명당 근로자 수가 2.4명까지 감소한 것으로 평가되었으며, 간병인의 부담이 커지는 한편, 자가 관리용 보조기구의 이용이 촉진되고 있습니다. 각국 정부는 건강한 노화를 위한 시책 및 보험 급여 개선을 통해 이에 대응하고 있으며, 이러한 요인들이 맞물려 장기적인 구매세가 유지되고 있습니다.
퇴행성 관절염과 류마티스 관절염의 유병률 증가
근골격계 질환으로 인해 지팡이 및 목발 시장에는 만성적인 이용자층이 끊임없이 유입되고 있습니다. 이러한 질환은 서서히 진행되기 때문에 보조기구의 수명이 길어지고, 교체 빈도도 높아집니다. 수술에 비해 비용을 절감하고자 하는 지불 주체에게 비침습적 보조기구는 매력적이며, 목발과 지팡이는 보존적 치료 전략의 핵심적인 역할을 수행하고 있습니다. 또한 젊은 세대에서도 앉아 있는 시간이 많은 생활 방식이나 스포츠로 인한 부하로 인해 관절 손상이 발생하고 있어, 대상 수요가 기존의 고령자층을 넘어 확대되고 있습니다.
대체 이동 보조기구의 보급
휠체어, 스쿠터, 보행기는 특히 근력이나 균형 감각이 현저히 저하된 이용자에게 기능적인 대안 수단이 됩니다. 전동 이동 기기에 관한 메디케어의 상세한 규정에 따라, 특정 임상 프로파일을 가진 이용자에게 있어 이러한 선택지는 경제적으로도 실현 가능해졌습니다. 전동 보조 기술의 발전으로 필요한 노력의 차이는 더욱 줄어들고 있으며, 일부 소비자는 목발을 완전히 생략하기도 합니다.
부문 분석
지팡이 부문은 2025년 지팡이 및 목발 시장에서 54.72%의 점유율을 차지한 것으로 평가되었으며, 경증에서 중등도의 균형 장애를 가진 사용자에게는 싱글 포인트형, 4각형, 오프셋형 각 디자인이 범용성을 발휘하고 있는 것으로 확인되었습니다. 목발은 받침대가 작지만, 재활 프로토콜에서 조기 보행이 중시되고, 스마트 목발 프로토타입이 기술에 정통한 클리닉의 관심을 끌고 있기 때문에 2031년까지 연평균 성장률(CAGR) 4.25%로 확대될 것으로 예측됩니다. 겨드랑이 목발은 사용자의 피로와 신경 압박의 위험이 있어, 수요는 인체공학에 기반한 전완형으로 이동하고 있습니다. 하중 센서와 블루투스 모듈을 탑재한 스마트 목발은 부상 후 관리를 근거 기반의 과정으로 변화시키고, 치료 준수 상황을 추적하는 데 주력하는 치료사들의 관심을 끌고 있습니다.
소재 대체가 진행되고 있는 점이 제품의 하위 세분화를 뒷받침하고 있습니다. 경량 탄소섬유로 제작된 샤프트는 보행 시 가동 범위를 넓히고 상체의 부담을 줄여주므로, 장기 사용자들 사이에서 채택이 확대되고 있습니다. 아이스 팁, 피벗식 페룰,충격 흡수 그립 등의 부속품 판매는 정기적인 수익원이 되어, 제조업체가 범용 프레임 이외의 부문에서 차별화를 꾀하는 데 일조하고 있습니다. 목발 처방은 외래 수술과 동반되는 경우가 많기 때문에 퇴원 계획 담당자는 지팡이 및 목발 시장에서 브랜드 선택에 있어 중요한 결정권을 가진 존재가 되었습니다.
알루미늄은 뛰어난 가성비와 확립된 금형 라인 덕분에 2025년에는 매출의 37.05%를 차지했습니다. 한편, 탄소섬유는 연평균 성장률(CAGR) 4.33%를 기록하며 가장 빠르게 성장하는 부문입니다. 복합재로 제작된 샤프트는 강철 제품에 비해 무게가 절반 이하이면서도 높은 반복 하중을 견딜 수 있으며, 이러한 장점은 허약한 고령자부터 적극적인 재활 치료를 받고 있는 환자에 이르기까지 폭넓은 계층에서 지지를 받고 있습니다. 또한, 탄소섬유는 구조적 무결성을 해치지 않으면서 센서 어레이용 배선을 내장할 수 있는데, 이는 차세대 커넥티드 보조 기기에 있어 필수적인 요건입니다.
목재는 전통적인 미관을 선호하는 사용자를 위한 틈새 시장을 유지하고 있지만, 시장 점유율의 하락은 무게, 습기, 유지보수의 어려움 때문인 것으로 보입니다. 열가소성 엘라스토머는 끝부분이나 인체공학적으로 설계된 손잡이에 채택되고 있으며, 그 미끄럼 방지 성능과 진동 흡수성은 작업 치료사들로부터 다시 한 번 주목을 받고 있습니다. 의료 분야의 조달 정책이 전체 수명 주기 동안의 탄소 발자국 감소를 중시하는 가운데, 재활용 가능한 복합 수지는 지속가능성이라는 새로운 요소를 도입하여 지팡이 및 목발 시장을 더욱 활성화하고 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 40.10%를 차지한 것으로 평가되었으며, 의료기기 구매를 지원하는 메디케어 및 메디케이드 정책과 견고한 유통 인프라에 힘입고 있습니다. 이 지역의 지팡이 및 목발 시장 규모는 청구 표준화 및 청구 처리 신속화를 도모하는 업데이트된 HCPCS 코드의 혜택을 받고 있습니다(cms.gov). 첨단 기술의 도입이 진행됨에 따라 센서가 탑재된 모델의 조기 보급이 촉진되어 공급업체에 가격 결정력이 부여되고 있습니다. 65세 이상 주민의 비율이 해마다 증가하고 있어, 인구 동향은 여전히 주요 성장 동인으로 작용하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 4.34%를 기록하며 가장 높은 성장률을 보일 것으로 예측됩니다. 2040년 일본의 의료 지출은 89조 엔에 달할 것으로 예상되며, 급속히 고령화되는 인구에 대해 비용 대비 효과가 높은 이동 보조 기구를 도입하는 것이 재정상의 시급한 과제가 되고 있습니다. 또한 2060년까지 중국의 의료 지출이 33조 4,000억 달러에 달할 것으로 예상되어, 이에 따라 잠재 고객 기반이 더욱 확대될 것입니다. 각 지역 정부는 기본적인 보행 보조기 비용을 지원하는 지역 보건 프로그램에 투자하고 있으며, 이는 판매량 증가를 뒷받침하고 있습니다. 중국과 인도의 현지 제조 클러스터는 리드 타임을 단축하고 배송 비용을 절감함으로써 지팡이 및 목발 시장의 보급을 가속화하고 있습니다.
유럽에서는 견조하지만 완만한 성장이 예상됩니다. 통일된 CE 마크 취득 절차로 시장 진입이 원활해지는 한편, 각국의 보험사는 엄격한 증거 요건을 유지하고 있어 공급업체들은 데이터가 풍부한 스마트 기기 개발로 방향을 전환하고 있습니다. 지속가능성 관련 지침에 따라 재활용 가능한 소재가 권장되면서 탄소섬유 채택이 가속화되고 있습니다. 대조적으로, 중동 및 아프리카와 남미는 초기 단계에서 발전 단계로 전환되고 있습니다. 가처분 소득 증가와 보험 적용 범위의 확대로 인해 점차 보급이 진행되고 있지만, 유통 네트워크의 제약과 의료 종사자 밀도의 낮음이 단기적인 진전을 억제하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the canes and crutches market size was valued at USD 1.18 billion in 2025 and estimated to grow from USD 1.23 billion in 2026 to reach USD 1.49 billion by 2031, at a CAGR of 3.98% during the forecast period (2026-2031).
This report is Segmented by Product Type (Canes [Single-Point Canes, and More], Crutches [Axillary Crutches, and More], and More), Material Composition (Wood, Aluminum, and More), End User (Hospitals & Clinics, Home-Care Settings, and More), Distribution Channel (Retail Pharmacies, and More), and Geography (North America, Europe, Asia-Pacific, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Canes And Crutches Market Trends and Insights
Rise in Global Geriatric Population
United Nations data show the share of people aged 65 and above rising sharply in the least-developed economies, confirming a prolonged upswing for the canes and crutches market. Larger elderly cohorts directly translate into higher demand for balance-support aids as well as replacements driven by progressive mobility decline. Asian countries such as Japan face support-ratio drops to 2.4 workers per senior by 2025, tightening caregiver capacity and encouraging uptake of self-help devices. Governments respond with healthy-ageing policies and reimbursement improvements, which together sustain long-range purchasing momentum.
Growing Incidence of Osteoarthritis & Rheumatoid Arthritis
Musculoskeletal disorders push a constant flow of chronic users into the canes and crutches market. These conditions advance gradually, extending device lifecycles and replacement frequency. Non-invasive aids appeal to payers seeking cost avoidance versus surgery, making crutches and canes central to conservative treatment strategies. As younger cohorts experience joint damage owing to sedentary lifestyles and sports stress, addressable demand widens beyond traditional senior demographics.
Availability of Alternative Mobility Devices
Wheelchairs, scooters and walkers present functional substitutes, especially for users whose strength or balance is severely impaired. Medicare's detailed rules for power mobility equipment make these options financially feasible for specific clinical profiles. Advancing power-assist technology narrows the effort gap further, prompting some consumers to bypass crutches entirely.
Other drivers and restraints analyzed in the detailed report include:
- Rise in Rehabilitation & Home-Health Adoption
- Smart, Sensor-Enabled Canes & Crutches Adoption Surge
- Shrinking Third-Party Reimbursement for "Low-Tech" Aids
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The segment held a 54.72% share of the canes and crutches market in 2025, confirming the versatility of single-point, quad and offset designs for users with light to moderate balance issues. Crutches, though smaller in base, are projected to expand at a 4.25% CAGR through 2031 as rehabilitation protocols emphasize early ambulation and as smart crutch prototypes attract technology-savvy clinics. Axillary models risk user fatigue and nerve compression, steering demand toward ergonomic forearm formats. Smart crutches equipped with load sensors and Bluetooth modules transform post-injury care into an evidence-based process, appealing to therapists intent on tracking compliance.
Rising material substitution underpins the product split. Lightweight carbon-fiber shafts improve swing clearance and reduce upper-body strain, boosting adoption among long-term users. Accessory sales such as ice tips, pivoting ferrules and shock-absorbing grips form a recurring-revenue layer that helps manufacturers differentiate beyond commodity frames. Because crutch prescriptions often accompany outpatient surgeries, hospital discharge planners have become a critical gatekeeper for brand choice in the canes and crutches market.
Aluminum delivered 37.05% revenue in 2025 thanks to its friendly price-performance ratio and established tooling lines. Carbon-fiber, however, represents the fastest growing slice at a 4.33% CAGR. Composite shafts withstand high cyclic loading while weighing less than half of steel counterparts, a benefit that resonates with frail seniors and active rehabilitation patients alike. In addition, carbon-fiber accommodates embedded wiring for sensor arrays without compromising structural integrity, a prerequisite for the next generation of connected aids.
Wood keeps a niche foothold serving users who favor traditional aesthetics, yet its declining share reflects weight, moisture and maintenance drawbacks. Thermoplastic elastomers find roles in tips and ergonomic handles, where slip resistance and vibration dampening gain renewed attention from occupational therapists. As healthcare procurement policies embrace lower life-cycle carbon footprints, recyclable composite resins add a sustainability lever that further propels the canes and crutches market.
Complete Report Scope:
- By Product Type
- Canes
- Single-point Canes
- Quad / Multiple-leg Canes
- Crutches
- Axillary Crutches
- Forearm Crutches
- Hands-free / Smart Crutches
- Accessories
- Canes
- By Material Composition
- Wood
- Aluminum
- Carbon-fiber / Composite
- Thermoplastic & Others
- By End User
- Hospitals & Clinics
- Home-care Settings
- Rehabilitation Centers
- Sports Injury Centers
- By Distribution Channel
- Retail Pharmacies
- Hospital Pharmacies
- Online
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America anchored 40.10% of global revenue in 2025, supported by Medicare and Medicaid policies that subsidize device acquisition and by robust distribution infrastructures. The canes and crutches market size in the region benefits from updated HCPCS codes that standardize billing and facilitate quicker claims processing cms.gov. High technology adoption encourages early uptake of sensor-enabled models, giving suppliers pricing power. Demographic patterns remain a core driver, as the proportion of residents aged 65+ grows each year.
Asia-Pacific is forecast to post the fastest 4.34% CAGR through 2031. Japan's projected healthcare outlay of ¥89 trillion in 2040 underscores the financial imperative to deploy cost-effective mobility aids for a rapidly greying population. China's anticipated health spend reaching USD 33.4 trillion by 2060 further expands the prospective customer base. Regional governments invest in community health programs that reimburse basic walking aids, stimulating volume expansion. Local manufacturing clusters in China and India compress lead times and lower landed costs, accelerating penetration of the canes and crutches market.
Europe delivers solid yet slower growth. Harmonized CE-mark processes streamline market entry, while national payers maintain strict evidence requirements that push suppliers toward data-rich smart devices. Sustainability directives favor recyclable materials, accelerating carbon-fiber adoption. In contrast, Middle East & Africa and South America move from nascent to developing stages. Rising disposable incomes and insurance coverage improvements permit gradual uptake, though constrained distribution networks and lower clinician density temper short-term advances.
- Drive DeVilbiss Healthcare
- Cardinal Health
- Medline Industries
- GF Health Products
- NOVA Medical Products
- Invacare
- Ergoactives
- Sunrise Medical
- Ossenberg
- BESCO Medical
- Carex (Compass Health)
- Ottobock
- Pride Mobility Products
- iWALKFree
- Flexmotiv
- TFI HealthCare
- AMG Medical
- Home Medical Products
- Benmor Medical
- Stander
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise in Global Geriatric Population
- 4.2.2 Growing Incidence of Osteoarthritis & Rheumatoid Arthritis
- 4.2.3 Rise in Rehabilitation & Home-health Adoption
- 4.2.4 Smart, Sensor-enabled Canes & Crutches Adoption Surge
- 4.2.5 Sustainability-driven Demand for Carbon-fiber Aids
- 4.2.6 Hands-free Knee-crutch Innovations Boosting Accessory Sales
- 4.3 Market Restraints
- 4.3.1 Availability of Alternative Mobility Devices
- 4.3.2 Shrinking Third-party Reimbursement for "Low-tech" Aids
- 4.3.3 Ergonomic Injuries from Prolonged Axillary-crutch Use
- 4.3.4 Growing Preference for Robotic Exoskeletons
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Canes
- 5.1.1.1 Single-point Canes
- 5.1.1.2 Quad / Multiple-leg Canes
- 5.1.2 Crutches
- 5.1.2.1 Axillary Crutches
- 5.1.2.2 Forearm Crutches
- 5.1.2.3 Hands-free / Smart Crutches
- 5.1.3 Accessories
- 5.1.1 Canes
- 5.2 By Material Composition
- 5.2.1 Wood
- 5.2.2 Aluminum
- 5.2.3 Carbon-fiber / Composite
- 5.2.4 Thermoplastic & Others
- 5.3 By End User
- 5.3.1 Hospitals & Clinics
- 5.3.2 Home-care Settings
- 5.3.3 Rehabilitation Centers
- 5.3.4 Sports Injury Centers
- 5.4 By Distribution Channel
- 5.4.1 Retail Pharmacies
- 5.4.2 Hospital Pharmacies
- 5.4.3 Online
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles
- 6.3.1 Drive DeVilbiss Healthcare
- 6.3.2 Cardinal Health
- 6.3.3 Medline Industries
- 6.3.4 GF Health Products
- 6.3.5 NOVA Medical Products
- 6.3.6 Invacare Corporation
- 6.3.7 Ergoactives
- 6.3.8 Sunrise Medical
- 6.3.9 Ossenberg GmbH
- 6.3.10 BESCO Medical
- 6.3.11 Carex (Compass Health)
- 6.3.12 Ottobock
- 6.3.13 Pride Mobility Products
- 6.3.14 iWALKFree
- 6.3.15 Flexmotiv
- 6.3.16 TFI HealthCare
- 6.3.17 AMG Medical
- 6.3.18 Home Medical Products Inc.
- 6.3.19 Benmor Medical
- 6.3.20 Stander
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


