

|
시장보고서
상품코드
2113946
중동 및 아프리카의 컨베이어 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Middle East And Africa Conveyors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
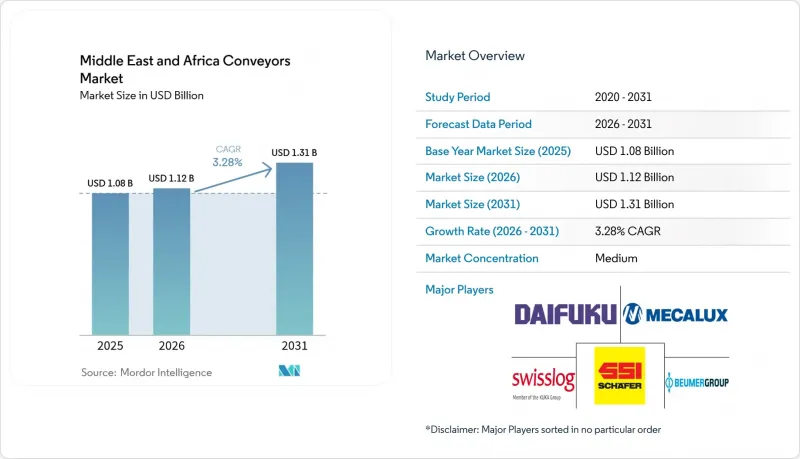
에 의하면, 중동 및 아프리카의 컨베이어 시장 규모는 2025년 10억 8,000만 달러로 평가되었습니다. 2026년에는 11억 2,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 3.28%로 성장을 지속하여, 2031년에는 13억 1,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품 유형(벨트 컨베이어, 롤러 컨베이어, 팔레트 컨베이어 등), 최종 사용자 산업(공항, 소매 및 전자상거래, 자동차, 일반 제조업 등), 컨베이어 방향(수평, 경사, 수직),설치 장소(바닥 설치형, 천장 설치형), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
중동 및 아프리카의 컨베이어 시장 동향 및 인사이트
전자상거래의 급속한 성장
UAE 및 사우디아라비아의 온라인 소매 침투율은 2024년에 총 매출의 15%에 달하여, 소비자 수요와 주문 처리 능력 간의 격차를 더욱 확대시켰습니다. 아마존의 10만 제곱미터 규모 리야드 시설과 Noon의 20만 제곱미터 규모 두바이 확장 프로젝트는 모두 피크 시간대에 시간당 5,000건 이상의 주문을 처리할 수 있는 모듈식 벨트 컨베이어, 롤러 컨베이어,및 ‘상품에서 사람으로(Goods-to-Person)’ 방식의 컨베이어에 의존하고 있습니다. 제벨 알리를 경유하는 크로스보더 소포 유입량은 전년 대비 40% 증가했으며, 이에 따라 3PL 각사는 고속 합류 컨베이어와 자동화된 통관 분류 시스템 도입을 불가피하게 하고 있습니다. RFID 리더기와 비전 가이드식 분기 장치를 갖춘 컨베이어는 99.9%의 분류 정확도를 실현하여 당일 배송 약속을 확실하게 이행하고 있습니다. 풀필먼트 사업자들이 다층 메자닌을 도입함에 따라 1제곱미터당 컨베이어 밀도가 높아지고 있으며, 연간 단위가 아닌 분기별로 규모 조정이 가능한, 센서가 풍부하게 탑재된 모듈식 플랫폼에 대한 수요가 더욱 증가하고 있습니다.
GCC 전역에 걸친 인프라 메가 프로젝트의 부상
사우디아라비아의 5,000억 달러 규모 ‘NEOM’ 프로젝트 및 350억 달러 규모의 ‘킹 살만 국제공항’ 프로젝트에서는 주변 온도 50℃와 사막의 모래폭풍을 견딜 수 있도록 설계된 골재용,수하물용, 건설용 컨베이어가 50킬로미터 이상에 걸쳐 필요합니다. 두바이 사우스나 카타르의 관광 회랑에서 진행되는 유사한 대규모 개발 프로젝트에서는 ISO 50001 에너지 관리 규격의 채택이 요구되고 있으며, 이에 따라 가변 주파수 드라이브와 회생 브레이크의 도입이 촉진되고 있습니다. 각 OEM 업체들은 최대 40%의 내재 탄소 감축 목표를 달성하기 위해 태양광 발전에 대응하는 파워트레인을 개발하고, 하이브리드 방식의 전기·공압 구동 시스템을 제공합니다. 2030년까지 이어지는 입찰 주기에서는 공급업체가 환율 변동이나 수입 관세의 급등을 피할 수 있도록 유연한 현지 조립 능력이 요구되고 있습니다. 이러한 프로젝트는 컨베이어에 대한 장기적인 수요를 확고히 하는 한편, 수주 패턴에 편차가 발생하기 때문에 해당 지역에서 견고한 파트너십을 구축한 공급업체에게 유리하게 작용합니다.
높은 초기 설비 투자
표준 벨트 및 롤러 시스템의 경우, 컨베이어 설치 비용은 일반적으로 1선형미터당 800-2,500달러이지만, 오버헤드식 파워 앤 프리 라인에서는 1미터당 8,000달러까지 치솟습니다. 아프리카 사업자들은 수입 관세와 통화 약세로 인해 15-25%의 추가 비용을 부담하게 되며, EBITDA 마진이 10% 미만인 기업의 경우 투자 회수 기간이 5년 이상으로 늘어납니다. 현지 은행이 제공하는 설비 리스 상품은 제한적이기 때문에 자금 조달 격차가 여전히 존재하며, 이로 인해 중소기업은 저비용의 중력식 롤러나 수작업에 의한 이송을 어쩔 수 없이 선택하고 있습니다. 벤더 파이낸싱이나 종량제 모델을 제공하는 OEM 각사는 미개척 수요의 3분의 1 가까이를 차지하는 ‘미싱 미들(Missing Middle)’ 부문 개척에 착수하기 시작했습니다.
부문 분석
2025년, 벨트 컨베이어는 중동 및 아프리카 전체 컨베이어 시장의 48.12%를 차지하며, 1미터당 500kg의 적재 제한이 있는 광업, 공항 수하물 운반, 식품 가공 등의 용도에서 확고한 입지를 다졌습니다. 롤러 컨베이어는 일반 제조업에서 골판지 상자와 팔레트 이송을 주도하는 한편, 팔레트 컨베이어는 1,000kg을 초과하는 무거운 자동차용 하위 어셈블리의 이송을 담당하고 있습니다. 오버헤드 시스템은 절대적인 규모는 작지만, 제약 업계의 클린룸이나 다층 자동차 공장에서 오염 없는 이송 경로와 바닥 면적 최적화가 요구됨에 따라 2031년까지 연평균 성장률(CAGR) 5.18%를 나타낼 것으로 전망됩니다.
2024년 UAE 및 사우디아라비아의 여러 풀필먼트 허브에 도입된 인터롤(Interroll)의 모듈식 컨베이어 플랫폼은 유지보수 팀이 4시간 이내에 재구성할 수 있는 ‘플러그 앤 플레이’ 섹션으로의 전환을 강조하며, 이를 통해 총 수명 주기 비용을 최대 25% 절감합니다. 오버헤드식 파워 앤 프리 라인은 루시드 모터스의 전기차 공장 및 시아의 사우디아라비아 조립 단지에 도입될 예정입니다. 이러한 시설에서는 차체 패널이 바닥 통행을 방해하지 않으면서 도장, 용접, 최종 조립 각 구역을 통과해야 합니다. 이 분야의 두드러진 동향으로는 센서가 탑재되고 IoT를 지원하는 플랫폼으로의 전환을 들 수 있습니다. 이를 통해 예측 유지보수를 통한 상태 모니터링과 소프트웨어 주도형 처리량 최적화가 가능해지며, ISO 50001 준수를 요구하는 지역 규제 요건에도 부합합니다.
중동 및 아프리카 컨베이어 시장의 2025년 수요 중 34.85%를 공항 운영 사업자가 차지했으며, 이는 허브 공항의 수하물 인프라에 대한 다년간의 투자를 반영한 것입니다. 그러나 온라인 이용이 확산되고 GCC 국가들에서 이집트와 케냐로 당일 배송에 대한 기대가 커짐에 따라, 소매 및 전자상거래 풀필먼트 센터가 2031년까지 연평균 성장률(CAGR) 6.33%라는 가장 높은 성장률을 기록할 전망입니다.
알마라이나 네슬레로 대표되는 식품 및 음료 제조업체들은 HACCP 프로토콜을 준수하기 위해 스테인리스 재질의 위생적인 컨베이어 개조를 추진하고 있으며, 시설당 평균 지출은 40% 증가했습니다. 한편, 제약 업계의 클린룸에서는 FDA 21 CFR Part 11의 추적성 요건을 준수하도록 설계된 오버헤드식 파워 앤 프리 시스템이 요구되고 있으며, 1미터당 비용이 1만 달러에 달하는 이 시스템은 오염 위험을 대폭 줄이고 있습니다. 부문 간의 경계가 모호해지고 있다는 사실은 EC 사업자가 수축 방지를 위해 의약품 등급의 육안 검사를 채택하거나, 음료 공장이 SKU 혼합 키트 조립을 위해 EC 스타일의 토트 컨베이어를 도입하고 있는 점에서도 분명합니다. 업계 전반에 걸친 도입 사례를 보유한 공급업체들은 이러한 융합이 가속화되는 가운데 경쟁 우위를 확보하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.26According to Mordor Intelligence, the middle east and Africa conveyors market size is expected to grow from USD 1.08 billion in 2025 to USD 1.12 billion in 2026 and is forecast to reach USD 1.31 billion by 2031 at 3.28% CAGR over 2026-2031.
This report is Segmented by Product Type (Belt Conveyors, Roller Conveyors, Pallet Conveyors, and More), End-User Industry (Airport, Retail and E-Commerce, Automotive, General Manufacturing, and More), Conveyor Orientation (Horizontal, Inclined, and Vertical), Conveyor Location (Floor-Mounted, and Overhead-Mounted), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Conveyors Market Trends and Insights
Rapid Growth Of E-Commerce
Online retail penetration in the UAE and Saudi Arabia rose to 15% of total sales in 2024, magnifying the gap between consumer demand and fulfillment capacity. Amazon's 100,000-square-meter Riyadh facility and Noon's 200,000-square-meter Dubai expansion both rely on modular belt, roller, and goods-to-person conveyors capable of processing more than 5,000 orders per hour in peak periods. Cross-border parcel inflows via Jebel Ali climbed 40% year over year, forcing 3PLs to deploy high-speed merge conveyors and automated customs sortation. Conveyors equipped with RFID readers and vision-guided diverters deliver 99.9% sort accuracy, ensuring compliance with same-day delivery promises. As fulfillment operators adopt multi-level mezzanines, conveyor intensity per square meter is rising, further amplifying demand for sensor-rich modular platforms that can be re-scaled quarterly rather than annually.
Rise Of Infrastructure Megaprojects Across GCC
Saudi Arabia's USD 500 billion NEOM and USD 35 billion King Salman International Airport projects require more than 50 kilometers of aggregate, baggage, and construction conveyors engineered for 50 °C ambient temperatures and desert sandstorms. Similar large-scale developments in Dubai South and Qatar's tourism corridors specify ISO 50001 energy management, catalyzing uptake of variable-frequency drives and regenerative braking. OEMs are building solar-ready power trains and offering hybrid electric-pneumatic drives to meet embodied-carbon reduction targets of up to 40%. Tender cycles that run through 2030 necessitate flexible local assembly capacity so suppliers avoid foreign-exchange swings and import-duty spikes. These projects cement long-term conveyor demand yet create lumpy order patterns that favor vendors with robust regional partnerships.
High Initial Capital Expenditure
Typical conveyor installations cost USD 800-2,500 per linear meter for standard belt and roller systems, escalating to USD 8,000 per meter for overhead power-and-free lines. African operators incur an extra 15-25% because of import duties and currency depreciation, stretching payback periods beyond five years for companies running on sub-10% EBITDA margins. Financing gaps persist as local banks offer limited equipment-leasing products, nudging SMEs toward low-cost gravity rollers or manual handling. OEMs that provide vendor financing and pay-per-use models are beginning to unlock the "missing-middle" segment representing nearly one-third of untapped demand.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Warehouse Automation Investments By 3PLs
- Surge In Airport Baggage-Handling System Upgrades
- Limited Skilled Maintenance Workforce
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Belt conveyors represented 48.12% of the Middle East and Africa conveyors market in 2025, entrenched in mining, airport baggage, and food processing applications where load limits reach 500 kg per meter. Roller conveyors dominate carton and pallet flows in general manufacturing, while pallet conveyors serve heavy automotive sub-assemblies exceeding 1,000 kg. Overhead systems, although smaller in absolute terms, will post a 5.18% CAGR through 2031 as pharmaceutical clean rooms and multi-level automotive plants target contamination-free routing and floor-space optimization.
Interroll's modular conveyor platform, installed across multiple UAE and Saudi fulfillment hubs in 2024, underscores the pivot toward plug-and-play sections that maintenance teams can reconfigure within four-hour windows, cutting total lifecycle costs by up to 25% . Overhead power-and-free lines are slated for Lucid Motors' EV plant and Ceer's Saudi assembly campus, where body panels must traverse painting, welding, and final-assembly zones without obstructing floor traffic. The embedded trend is a migration to sensor-enabled, IoT-ready platforms that allow predictive health monitoring and software-driven throughput optimization, aligning with regional mandates for ISO 50001 compliance.
Airport operators accounted for 34.85% of 2025 demand in the Middle East and Africa conveyors market, reflecting historic investment in hub-airport baggage infrastructure. Yet retail and e-commerce fulfillment centers will record the fastest 6.33% CAGR through 2031 as online penetration climbs and same-day delivery expectations spread from the GCC to Egypt and Kenya.
Food and beverage producers led by Almarai and Nestle are retrofitting stainless-steel hygienic conveyors to satisfy HACCP protocols, raising average spend per facility by 40%. Meanwhile, pharmaceutical clean rooms demand overhead power-and-free systems engineered for FDA 21 CFR Part 11 traceability, driving per-meter costs to USD 10,000 but radically reducing contamination risk. The blurring of segment boundaries is evident as e-commerce operators adopt pharmaceutical-grade vision inspection for shrinkage control, while beverage plants install e-commerce-style tote conveyors for mixed-SKU kitting. Suppliers with cross-sector case studies hold a competitive edge as convergence accelerates.
Complete Report Scope:
- By Product Type
- Belt Conveyors
- Roller Conveyors
- Pallet Conveyors
- Overhead Conveyors
- Screw Conveyors
- Chain Conveyors
- By End-User Industry
- Airport
- Retail and E-Commerce
- Automotive
- General Manufacturing
- Food and Beverage
- Pharmaceuticals
- Mining and Minerals
- By Conveyor Orientation
- Horizontal
- Inclined
- Vertical
- By Conveyor Location
- Floor-Mounted
- Overhead-Mounted
- By Country
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Oman
- Kuwait
- Bahrain
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Kenya
- Morocco
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Daifuku Co. Ltd.
- SSI Schaefer AG
- Swisslog Holding AG
- BEUMER Group GmbH and Co. KG
- Mecalux SA
- KNAPP AG
- Kardex Holding AG
- Interroll Holding AG
- CITCOnveyors SRL
- Melco Conveyor Equipment (Pty) Ltd.
- Fives Intralogistics SAS
- Vanderlande Industries B.V.
- Bastian Solutions LLC
- Dematic Corp.
- FlexLink AB
- Siemens Logistics GmbH
- Dorner Manufacturing Corp.
- Continental AG
- Hytrol Conveyor Company Inc.
- TGW Logistics Group GmbH
- Honeywell Intelligrated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth of E-Commerce
- 4.2.2 Rise of Infrastructure Megaprojects Across GCC
- 4.2.3 Accelerating Warehouse Automation Investments by 3PLs
- 4.2.4 Surge in Airport Baggage Handling System Upgrades
- 4.2.5 Mining Sector Modernization in Africa
- 4.2.6 Greenfield Electric-Vehicle Assembly Plants
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Expenditure
- 4.3.2 Limited Skilled Maintenance Workforce
- 4.3.3 Volatile Raw Material Prices
- 4.3.4 Fragmented OEM and After-Sales Network in Africa
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Intensity of Competitive Rivalry
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Belt Conveyors
- 5.1.2 Roller Conveyors
- 5.1.3 Pallet Conveyors
- 5.1.4 Overhead Conveyors
- 5.1.5 Screw Conveyors
- 5.1.6 Chain Conveyors
- 5.2 By End-User Industry
- 5.2.1 Airport
- 5.2.2 Retail and E-Commerce
- 5.2.3 Automotive
- 5.2.4 General Manufacturing
- 5.2.5 Food and Beverage
- 5.2.6 Pharmaceuticals
- 5.2.7 Mining and Minerals
- 5.3 By Conveyor Orientation
- 5.3.1 Horizontal
- 5.3.2 Inclined
- 5.3.3 Vertical
- 5.4 By Conveyor Location
- 5.4.1 Floor-Mounted
- 5.4.2 Overhead-Mounted
- 5.5 By Country
- 5.5.1 Middle East
- 5.5.1.1 United Arab Emirates
- 5.5.1.2 Saudi Arabia
- 5.5.1.3 Qatar
- 5.5.1.4 Oman
- 5.5.1.5 Kuwait
- 5.5.1.6 Bahrain
- 5.5.1.7 Turkey
- 5.5.1.8 Israel
- 5.5.1.9 Rest of Middle East
- 5.5.2 Africa
- 5.5.2.1 South Africa
- 5.5.2.2 Egypt
- 5.5.2.3 Nigeria
- 5.5.2.4 Kenya
- 5.5.2.5 Morocco
- 5.5.2.6 Rest of Africa
- 5.5.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Daifuku Co. Ltd.
- 6.4.2 SSI Schaefer AG
- 6.4.3 Swisslog Holding AG
- 6.4.4 BEUMER Group GmbH and Co. KG
- 6.4.5 Mecalux SA
- 6.4.6 KNAPP AG
- 6.4.7 Kardex Holding AG
- 6.4.8 Interroll Holding AG
- 6.4.9 CITCOnveyors SRL
- 6.4.10 Melco Conveyor Equipment (Pty) Ltd.
- 6.4.11 Fives Intralogistics SAS
- 6.4.12 Vanderlande Industries B.V.
- 6.4.13 Bastian Solutions LLC
- 6.4.14 Dematic Corp.
- 6.4.15 FlexLink AB
- 6.4.16 Siemens Logistics GmbH
- 6.4.17 Dorner Manufacturing Corp.
- 6.4.18 Continental AG
- 6.4.19 Hytrol Conveyor Company Inc.
- 6.4.20 TGW Logistics Group GmbH
- 6.4.21 Honeywell Intelligrated
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


