

|
시장보고서
상품코드
2113976
죽종절제술 기기 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Atherectomy Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 죽종절제술 기기 시장 규모는 2025년에 10억 4,000만 달러로 평가되었습니다. 2026년 11억 2,000만 달러에서 2031년까지 16억 1,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 7.58%를 나타낼 전망입니다.
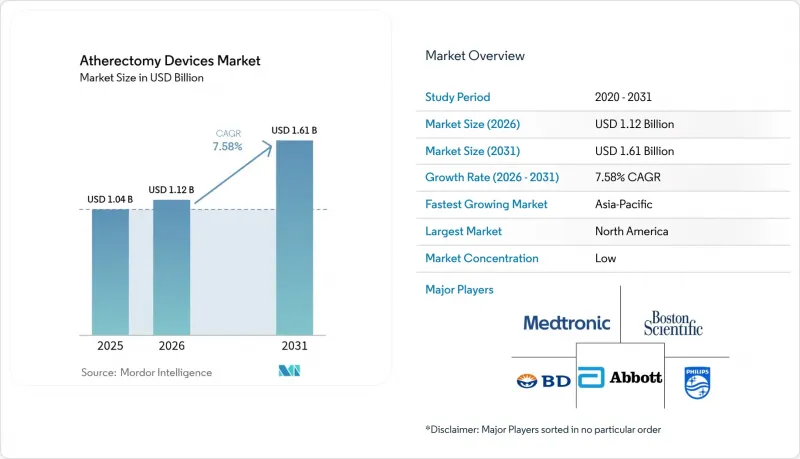
본 보고서에서는 업계를 제품별(방향성 아텔렉토미 시스템, 궤도식 아텔렉토미 시스템, 광 절제(레이저) 아텔렉토미 시스템,회전식 아텔렉토미 시스템), 용도별(말초 혈관 용도, 심혈관 용도, 신경혈관 용도), 최종 사용자별(병원 및 외과 센터, 외래수술센터(ASC) 등), 그리고 지역별로 분류하고 있습니다.
세계의 죽종절제술 기기 시장 동향 및 인사이트
말초동맥질환 및 관상동맥질환 유병률 증가
말초동맥질환은 전 세계적으로 2억 명 이상에게 영향을 미치고 있으며, 특히 당뇨병이나 대사증후군을 동반한 고령층에서 그 영향이 두드러집니다. 이 질환의 부담이 증가함에 따라, 중증 석회화 병변은 단순한 풍선 혈관 성형술만으로는 충분한 효과를 얻기 어려워 치료의 복잡성이 증가하고 있습니다. 현재 미국 및 유럽의 지침에서는 25cm 미만의 서혜부 병변에 대해 혈관내 치료를 권장하고 있으며, 이에 따라 아테렉토미 적응증이 되는 환자층이 확대되고 있습니다. 병원 보고에 따르면, 고령 환자의 경우 폐색 부위가 더 길고 복잡하여 허용 가능한 관강 회복을 얻기 위해서는 혈관 전처치 기술이 필요합니다. 그 결과, 의료기기 제조업체들은 편심성 석회화를 제거하면서도 색전증 발생을 최소화할 수 있는 시스템을 중시하고 있습니다. 장기적인 인구 동향의 호재에 힘입어, 적어도 향후 10년 동안은 시술 건수가 두 자릿수 성장을 유지할 것으로 전망됩니다.
저침습 혈관 내 시술의 보급 확대
병원과 외래수술센터(ASC)에서는 입원 기간 단축과 조기 보행 재개가 중시되고 있으며, 의사들은 마취 시간 단축 및 수술 부위 합병증 감소로 이어지는 시술법을 선택하도록 권장받고 있습니다. 2023년에는 6,308개 시설에서 OBL(대퇴동맥 경유) 시술에 대한 메디케어 환급액이 68억 달러에 달했습니다. 아테렉토미는 대부분의 시스템이 6Fr 시스를 지원하며 당일 퇴원이 가능하기 때문에 이러한 변화에 적합합니다. 혈관외과 의사 및 고위 의료진의 숙련도가 높아짐에 따라, 외래수술센터(ASC)에서의 아테렉토미 시술 건수는 연평균 성장률(CAGR) 8.06%로 성장을 지속하고 있습니다. 지급 기관이 OBL의 안전성 지표에 대해 갖는 신뢰도가 높아짐에 따라 이용률이 더욱 상승하고 있으며, 이는 새로운 시스템에 대한 설비 투자를 지속시키는 선순환을 강화하고 있습니다. 유럽 및 아시아태평양의 선진국에서도 절대적인 수는 적지만, 유사한 추세가 관찰됩니다.
PTA/스텐트 삽입술에 비해 우월성을 입증하는 장기적인 근거는 제한적입니다.
2,005명의 환자를 대상으로 한 ECLIPSE 연구에서는 약물 방출형 스텐트 삽입 전 표적 혈관 기능 부전 예방에 있어, 오비탈 아테렉토미가 단순 풍선 혈관 성형술에 비해 통계적으로 유의한 우월성은 인정되지 않았습니다(00450-7/초록). 이러한 중립적인 결과는 아테렉토미가 절단 위험을 감소시킨 반면 재시술률을 증가시켰습니다는 과거 말초혈관 레지스트리의 결과와 일치합니다. 따라서, 근거에 기반한 보험사는 효과가 입증된 하위 집단에 한해 보험 적용을 제한할 가능성이 있으며, 시술자의 선호도보다 무작위 배정 데이터를 우선시하는 지역에서는 시술 건수 증가가 억제될 것입니다.
부문 분석
2025년, 방향성 시스템은 아테렉토미 기기 시장 매출의 41.78%를 차지했습니다. 이는 정확한 플라크 제거와 사후 확장용 풍선과의 호환성을 중시하는 외과의사의 선호도를 반영한 것입니다. 디렉셔널 플랫폼용 아테렉토미 기기 시장 규모는 새로운 커터 헤드 형상으로 인해 플라크 제거 능력을 저해하지 않으면서 통과 프로파일이 개선됨에 따라, 2031년까지 연평균 성장률(CAGR) 7.08%로 꾸준히 확대될 것으로 예측됩니다. 레이저 카테터는 흡입 보조 설계로 인해 색전 위험을 대폭 낮출 수 있어, 연평균 성장률(CAGR) 7.74%로 가장 빠르게 성장하는 치료법입니다. 회전식 및 궤도식 기기는 고도로 석회화된 관상동맥 및 장골동맥 병변에 여전히 필수적이지만, ECLIPSE 임상시험에서 중립적인 결과가 나온 이후 엄격한 검증을 받고 있습니다.
경쟁 우위는 차별화된 바 코팅, 실시간 피드백 알고리즘 및 번들 서비스 계약에 달려 있습니다. 애보트의 ‘Diamondback 360’은 다이아몬드가 박힌 크라운이 편심 궤도를 그리며 칼슘을 깎아내는 방식을 채택한 반면, 보스턴 사이언티피크의 ‘Jetstream’은 스텐트 내 재협착에 대응하기 위해 전면 절단 블레이드와 흡입 기능을 결합하고 있습니다. mm 단위의 로봇 공학 등 산학 공동 프로젝트는 구불구불한 신경혈관 내부를 원격 조작으로 탐색할 수 있는 차세대 시스템의 도래를 예고하고 있습니다. 사전 결정 변경 관리 계획(Predetermined Change Control Plans)에 관한 FDA의 지침에 따라, 제조업체는 소프트웨어 업데이트 내용을 사전에 규정할 수 있게 되었으며, 이로 인해 반복 주기가 단축되고 혁신의 속도가 가속화되고 있습니다.
지역별 분석
북미는 높은 시술 밀도, 확립된 보험 환급 제도, 그리고 견고한 임상 연구 인프라를 배경으로 2025년 아테렉토미 기기 시장 매출의 38.74%를 차지했습니다. 이 지역의 성장률은 시술 건수가 병원 입원 환자에서 외래 환자로 이동함에 따라 한 자릿수 중반 수준으로 둔화되고 있습니다. 아시아태평양의 아테렉토미 기기 시장 규모는 국내 제조에 대한 우대 조치와 심혈관 질환 유병률 증가를 배경으로 2031년까지 연평균 성장률(CAGR) 8.08%로 성장할 전망입니다. 중국의 ‘제14차 5개년 계획’에서는 고급 중재용 의료기기의 현지 생산을 장려하고 있으며, 이를 통해 지역 기업들은 품질을 저하시키지 않으면서도 수입품보다 저렴한 가격으로 제품을 공급할 수 있게 될 것입니다. 한편, 일본과 한국에서는 혈관 준비 코드가 인증되는 성숙한 보험 급여 제도를 활용하여 조기 도입을 촉진하고 있습니다.
유럽은 여전히 3위 지역 시장이며, 의료기기 규정(MDR)의 영향을 받은 증거 중심의 구매 위원회가 특징입니다. 병원 측은 장기적인 안전성 등록 자료를 중시하기 때문에 재시술률 감소를 입증한 공급업체가 우선 공급업체로서의 지위를 확보하고 있습니다. 혁신 도입이 가장 빠른 곳은 독일과 네덜란드이며, 이들 국가에서는 OBL(진료 관행 기반 카테터실)에 상당하는 시설이 진단 관련 그룹(DRG)에 기반한 포괄 지급 제도 하에서 운영되고 있습니다. 라틴아메리카 및 중동 및 아프리카는 전 세계 매출 총액의 10% 미만을 차지할 뿐이지만, 민간 보험사들이 말초 혈관 치료에 대한 보험 적용 범위를 확대함에 따라 한 자릿수 후반대의 높은 성장률을 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.26According to Mordor Intelligence, the atherectomy devices market size was valued at USD 1.04 billion in 2025 and estimated to grow from USD 1.12 billion in 2026 to reach USD 1.61 billion by 2031, at a CAGR of 7.58% during the forecast period (2026-2031).
This report Segments the Industry Into by Product (Directional Atherectomy Systems, Orbital Atherectomy Systems, Photo-Ablative (Laser) Atherectomy Systems, Rotational Atherectomy Systems), by Application (Peripheral Vascular Applications, Cardiovascular Applications, Neurovascular Applications), by End User (Hospitals and Surgical Centers, Ambulatory Care Centers, and More), and Geography.
Global Atherectomy Devices Market Trends and Insights
Rising Prevalence of Peripheral & Coronary Artery Disease
Peripheral artery disease affects more than 200 million people worldwide, most acutely in aging populations with diabetes and metabolic syndrome. The expanding burden raises procedural complexity because heavily calcified lesions respond poorly to plain balloon angioplasty. Current U.S. and European guidelines now recommend endovascular interventions for infra-inguinal lesions under 25 cm, opening a larger pool of candidates for atherectomy. Hospitals report that older patients present with longer, more complex occlusions that require vessel-preparation techniques to achieve acceptable luminal gain. Consequently, device makers emphasize systems able to debulk eccentric calcium while minimizing embolic events. The long-term demographic tailwind supports double-digit growth in procedure volumes for at least the next decade.
Growing Adoption of Minimally Invasive Endovascular Procedures
Hospitals and outpatient centers prefer shorter stays and quicker ambulation, pushing physicians to select techniques that reduce anesthesia time and wound complications. Medicare reimbursements for OBL interventions reached USD 6.8 billion across 6,308 facilities in 2023. Atherectomy fits this shift because most systems are compatible with 6Fr sheaths, allowing same-day discharge. Ambulatory surgical centers have posted an 8.06% CAGR in atherectomy procedure counts as vascular surgeons and advanced practice providers gain proficiency. Rising comfort among payors with OBL safety metrics further lifts utilization, reinforcing a feedback loop that sustains capital purchases of new systems. Comparable trends in Europe and advanced Asia-Pacific economies are visible albeit at lower absolute volumes.
Limited Long-Term Evidence of Superiority vs. PTA/Stenting
The 2,005-patient ECLIPSE trial reported no statistical advantage for orbital atherectomy over plain balloon angioplasty in preventing target vessel failure before drug-eluting stent implantation(00450-7/abstract). This neutral outcome echoes prior peripheral registries in which atherectomy reduced amputation risk yet increased repeat intervention rates. Evidence-based payors may therefore restrict reimbursement to subgroups with demonstrated benefit, constraining volume growth in regions that prioritize randomized data over operator preference.
Other drivers and restraints analyzed in the detailed report include:
- Favorable Reimbursement Incentives for Office-Based Labs (U.S.)
- Laser Systems with Active Aspiration Lower Distal-Embolization Risk
- High Device & Capital Costs for Providers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Directional systems generated 41.78% of atherectomy devices market revenue in 2025, reflecting surgeon preference for precise plaque excision and compatibility with post-dilation balloons. The atherectomy devices market size for directional platforms is projected to grow at a steady 7.08% CAGR to 2031 as new cutter-head geometries improve crossing profile without sacrificing debulking capacity. Laser catheters represent the fastest-rising modality at 7.74% CAGR because aspiration-assisted designs significantly lower embolic risk. Rotational and orbital devices remain essential for densely calcified coronary and iliac lesions yet face scrutiny following neutral ECLIPSE outcomes.
Competitive positioning hinges on differentiated burr coatings, real-time feedback algorithms, and bundled service contracts. Abbott's Diamondback 360 leverages a diamond-embedded crown that orbits eccentrically to sand down calcium, whereas Boston Scientific's Jetstream incorporates front-cutting blades plus aspiration for in-stent restenosis. University-industry projects such as milli-scale robotics foreshadow next-generation systems capable of remote navigation through tortuous neurovascular beds. FDA guidance on Predetermined Change Control Plans allows manufacturers to pre-specify software updates, shortening iteration cycles and accelerating innovation cadence.
Complete Report Scope:
- By Device Type (Value)
- Directional Atherectomy Devices
- Rotational Atherectomy Devices
- Orbital Atherectomy Devices
- Laser Atherectomy Devices
- By Application (Value)
- Peripheral Vascular Disease
- Coronary Artery Disease
- Neurovascular Disease
- By End User (Value)
- Hospitals & Surgical Centers
- Ambulatory Surgical Centers
- Office-Based Labs
- by Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America generated 38.74% of atherectomy devices market revenue in 2025 on the back of high procedural density, entrenched reimbursement, and robust clinical research infrastructure. The region's growth moderates to mid-single-digit rates as volume shifts from hospital inpatient to outpatient venues. The atherectomy devices market size in Asia-Pacific will expand at an 8.08% CAGR through 2031, underpinned by domestic manufacturing incentives and accelerating cardiovascular disease prevalence. China's Fourteenth Five-Year Plan calls for local production of high-end interventional devices, positioning regional firms to undercut imports without compromising quality. Japan and South Korea, meanwhile, leverage mature reimbursement systems that now recognize vessel-preparation codes, stimulating early adoption.
Europe remains the third-largest regional segment, characterized by evidence-oriented purchasing committees influenced by the Medical Device Regulation. Hospitals emphasize long-term safety registries; therefore, suppliers that document reduced reintervention rates achieve preferred-vendor status. Innovation uptake is fastest in Germany and the Netherlands where OBL equivalents-practice-based cath labs-operate under bundled diagnosis-related group payments. Latin America and Middle East & Africa collectively account for less than 10% of global sales but show high-single-digit growth as private insurers expand coverage for peripheral vascular procedures.
- Abbott Laboratories
- Medtronic
- Boston Scientific
- Koninklijke Philips
- AngioDynamics
- Beckton Dickinson
- Straub Medical
- Avinger Inc.
- Terumo
- Shockwave Medical Inc.
- Cook Group
- Merit Medical Systems
- Penumbra
- BIOTRONIK
- Rex Medical LP
- Ra Medical Systems Inc.
- Cardiovascular Systems Inc. (CSI)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of peripheral & coronary artery disease
- 4.2.2 Growing adoption of minimally-invasive endovascular procedures
- 4.2.3 Favorable reimbursement incentives for office-based labs (U.S.)
- 4.2.4 Laser systems with active aspiration lower distal-embolization risk
- 4.2.5 Domestic manufacturing push in Asia-Pacific for plaque-modification devices
- 4.2.6 Synergistic outcomes of atherectomy + drug-coated balloons
- 4.3 Market Restraints
- 4.3.1 Limited long-term evidence of superiority vs. PTA/stenting
- 4.3.2 High device & capital costs for providers
- 4.3.3 Imminent reimbursement cuts due to over-utilisation reviews
- 4.3.4 Supply-chain risk for diamond-coated burr materials
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Device Type (Value)
- 5.1.1 Directional Atherectomy Devices
- 5.1.2 Rotational Atherectomy Devices
- 5.1.3 Orbital Atherectomy Devices
- 5.1.4 Laser Atherectomy Devices
- 5.2 By Application (Value)
- 5.2.1 Peripheral Vascular Disease
- 5.2.2 Coronary Artery Disease
- 5.2.3 Neurovascular Disease
- 5.3 By End User (Value)
- 5.3.1 Hospitals & Surgical Centers
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Office-Based Labs
- 5.4 by Geography (Value)
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Medtronic plc
- 6.3.3 Boston Scientific Corporation
- 6.3.4 Koninklijke Philips N.V.
- 6.3.5 AngioDynamics Inc.
- 6.3.6 Becton, Dickinson and Company
- 6.3.7 Straub Medical AG
- 6.3.8 Avinger Inc.
- 6.3.9 Terumo Corporation
- 6.3.10 Shockwave Medical Inc.
- 6.3.11 Cook Medical LLC
- 6.3.12 Merit Medical Systems Inc.
- 6.3.13 Penumbra Inc.
- 6.3.14 Biotronik SE & Co. KG
- 6.3.15 Rex Medical LP
- 6.3.16 Ra Medical Systems Inc.
- 6.3.17 Cardiovascular Systems Inc. (CSI)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


